
 Enhanced Oil Recovery Market | 2026-2036
Enhanced Oil Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Enhanced Oil Recovery Market Analysis
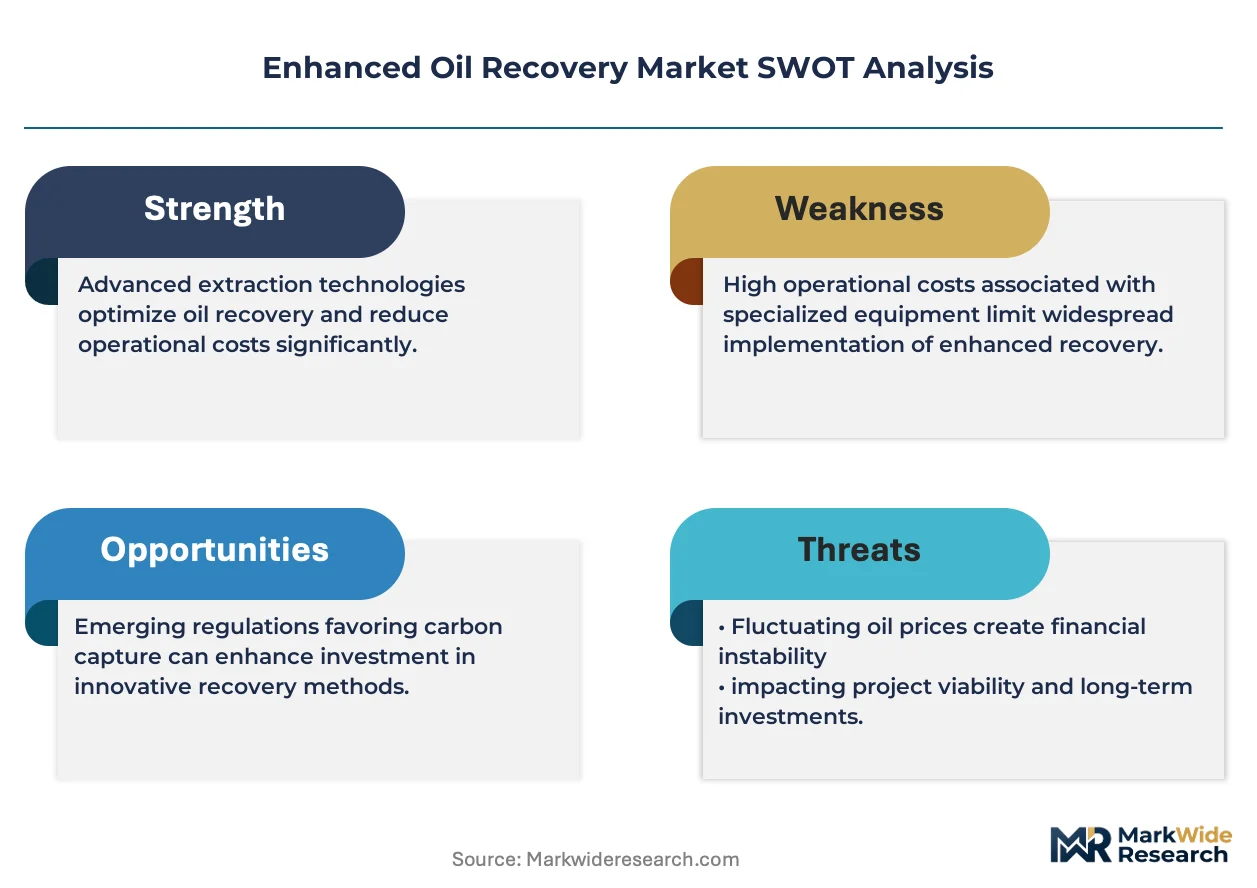
Project finance structures tied to long-term production-sharing contracts are reshaping competitive entry in the Enhanced Oil Recovery sector, lowering capital barriers for independent operators and specialized service firms. Schlumberger Limited leverages its integrated technology platform to dominate complex reservoir characterization and chemical EOR design. Halliburton Company anchors its position through manufacturing scale in polymer supply and well intervention services. Baker Hughes Company differentiates via advanced gas injection systems and digital monitoring capabilities.
Enhanced oil recovery encompasses engineered techniques that supplement natural reservoir pressure to mobilize and extract crude oil remaining after primary and secondary production stages, typically targeting reservoirs where waterflooding has recovered less than half of original oil in place. Thermal recovery methods such as steam-assisted gravity drainage functionally require injection temperatures exceeding 150 degrees Celsius to reduce heavy oil viscosity for surface production. Gas injection segments, particularly CO2 flooding, occupy the largest margin pools due to carbon utilization incentives and established pipeline infrastructure in North American basins. Chemical injection represents the fastest-growing technology category as surfactant-polymer formulations improve sweep efficiency in heterogeneous carbonate formations.
The US Environmental Protection Agency regulates CO2 sequestration under Class VI well standards, directly shaping project economics and permitting timelines for carbon-enhanced oil recovery developments. Saudi Arabia's national regulator mandates local content requirements and environmental impact assessments for all major EOR field expansions, influencing contractor selection and technology transfer obligations. China's Ministry of Ecology and Environment enforces dual carbon goals that constrain steam-based thermal projects while accelerating chemical and gas injection alternatives. Stakeholders must monitor evolving carbon accounting methodologies and their impact on project finance eligibility across jurisdictions.
Market Dynamics
Carbon utilization incentives under the US Inflation Reduction Act are compressing project payback periods for CO2-enhanced oil recovery, while Saudi Aramco's carbonate megaprojects pull chemical injection technologies into high-temperature, high-salinity reservoir conditions that exceed legacy design envelopes.
Growth Catalysts
- IRA 45Q Tax Credits:The US Inflation Reduction Act's expanded carbon capture incentives reduce net CO2 supply costs for Permian Basin operators, improving project-level returns on carbon-enhanced oil recovery developments.
- Polymer flooding:Surfactant-polymer formulations engineered for carbonate heterogeneity are extending sweep efficiency in Saudi Arabia's Ghawar and Khurais fields beyond waterflood recovery factors.
- Digital twin deployment:Real-time reservoir simulation platforms are reducing pattern optimization cycles from months to weeks, accelerating response to injector-producer communication changes.
Market Restraints
- CO2 supply concentration:Anthropogenic CO2 capture infrastructure remains concentrated in US Gulf Coast industrial corridors, constraining project scalability in other basins lacking pipeline networks.
- Polymer thermal degradation:High-temperature carbonate reservoirs exceeding 90 degrees Celsius accelerate hydrolysis of conventional polyacrylamides, limiting chemical EOR applicability in deep Middle Eastern formations.
- Class VI permitting:EPA underground injection control timelines extending 18-24 months for CO2 sequestration wells delay project sanctioning and compress development windows.
Strategic Opportunities
- Low-salinity waterflooding:Smart water injection techniques tuned to specific crude-brine-rock interactions offer incremental recovery in mature Norwegian North Sea assets without full chemical EOR capital commitments.
- Direct air capture integration:Coupling DAC facilities with depleted oil fields creates closed-loop CO2 sourcing for enhanced oil recovery in regions lacking industrial point-source availability.
- China chemical EOR acceleration:Ministry of Ecology and Environment constraints on steam-based thermal projects redirect investment toward surfactant-polymer and alkali-surfactant-polymer systems in Daqing and Shengli fields.
Industry Challenges
- Reservoir geochemistry modeling:Predicting mineral dissolution-precipitation reactions in carbonate formations under chemical flooding requires specialized expertise scarce outside integrated service companies and national oil company research centers.
- Pattern conformance management:Heterogeneous carbonate permeability distributions create thief zones that divert injected fluids from target oil zones, demanding continuous well intervention and profile modification workovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enhanced Oil Recovery Market |
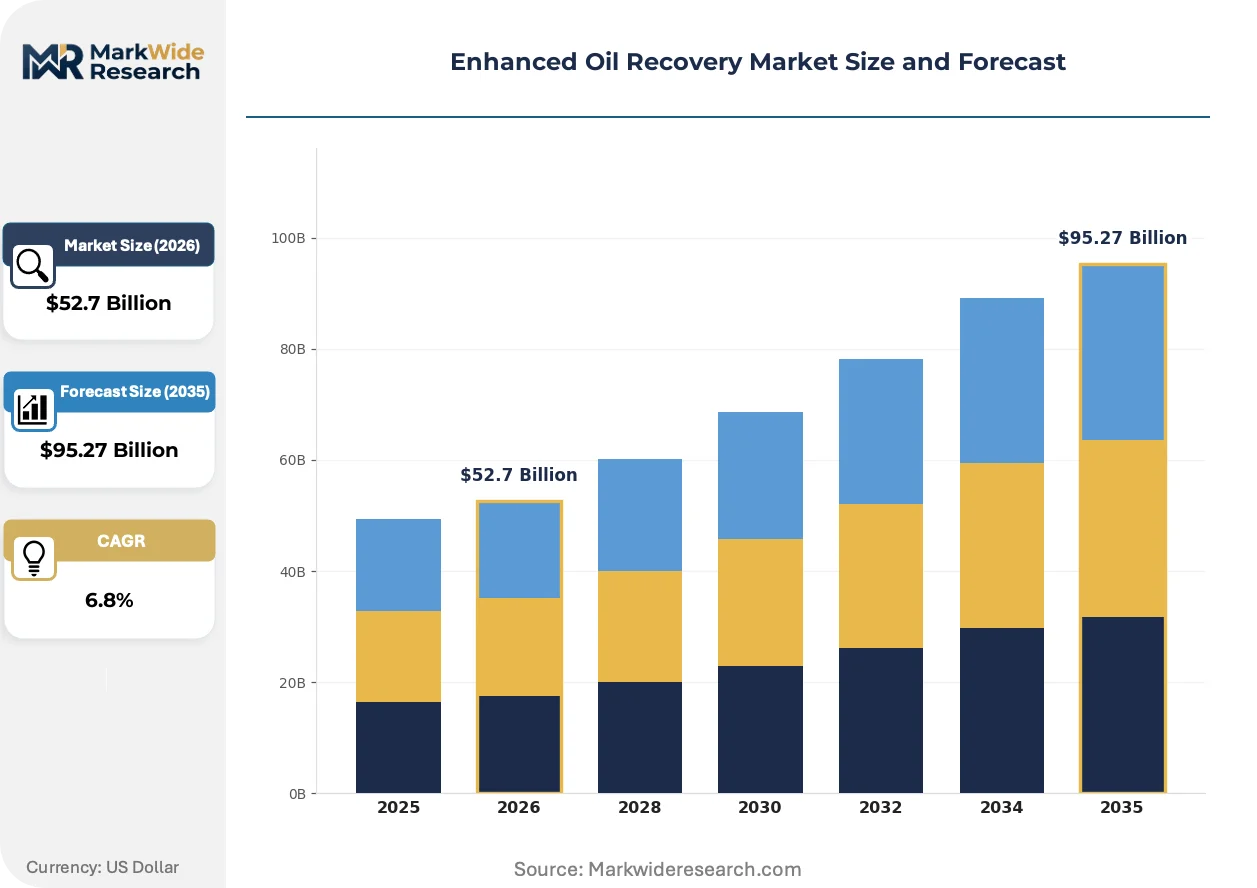
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Thermal Recovery, Gas Injection, Chemical Injection, Miscible Flooding Oil Field Type: Onshore, Offshore, Shale, Heavy Oil End User: Independent Producers, National Oil Companies, Oilfield Services, Refiners Methodology: Primary Recovery, Secondary Recovery, Enhanced Techniques, Hybrid Methods |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, ExxonMobil Corporation, Chevron Corporation, Shell plc, BP plc, TotalEnergies SE, Occidental Petroleum Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enhanced Oil Recovery Market Emerging Trajectories
Real-time monitoring architectures and machine learning inference at the edge are compressing reservoir management decision cycles, while regulatory frameworks increasingly tie project finance eligibility to verified carbon accounting methodologies.
Reservoir surveillance technology is digitizing production optimization workflows. Distributed fiber-optic sensing and autonomous downhole gauges generate continuous pressure-temperature-flow profiles across multi-well patterns. Saudi Aramco and international majors deploy these sensor networks at scale in carbonate megaprojects. The resulting data streams enable predictive maintenance of artificial lift systems and real-time allocation of injection volumes across patterns.
EPA Class VI well construction standards are tightening monitoring and verification requirements for CO2 sequestration projects. Operators must demonstrate mechanical integrity across injection and confining zones through continuous pressure monitoring and periodic testing. Carbon-enhanced oil recovery developments in the Permian Basin face extended permitting timelines and elevated capital requirements for monitoring wells. Project sponsors are responding by integrating third-party verification into front-end engineering to accelerate regulatory approval.
Field development contracting is fragmenting as national oil companies unbundle integrated service packages. Saudi Aramco's In-Kingdom Total Value Add program mandates local content thresholds that reshape contractor selection criteria. Independent operators in the US Midcontinent increasingly procure polymer supply, reservoir characterization, and well intervention services from separate vendors rather than single-source integrated providers. This unbundling is most pronounced in North American unconventional basins where operator technical capabilities support direct vendor management.
Enhanced Oil Recovery Market Segmentation
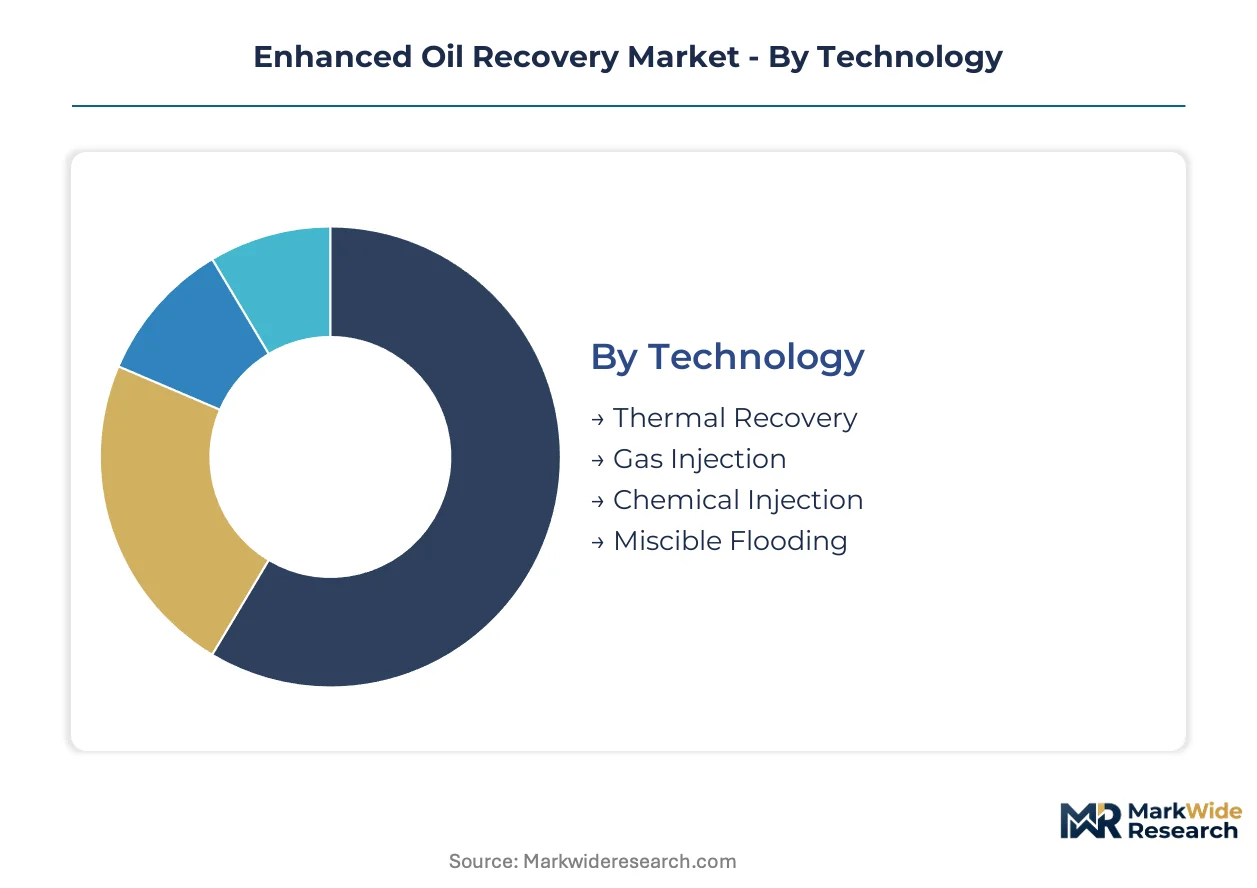
Technology choice in enhanced oil recovery determines capital intensity, operational complexity, and ultimate recovery factors across reservoir types. Segmentation reveals how operators match injection methods to crude viscosity, formation depth, and existing infrastructure.
Technology:
Cost tier differentiation separates mature thermal methods from emerging chemical formulations requiring specialized supply chains.
- Thermal Recovery:Steam-assisted gravity drainage and cyclic steam stimulation reduce heavy oil viscosity through sustained injection temperatures above 150 degrees Celsius. Saudi Aramco deploys thermal methods in shallow carbonate formations where viscosity reduction unlocks reserves uneconomical through pressure maintenance alone.
- Chemical Injection:Surfactant-polymer formulations improve sweep efficiency in heterogeneous reservoirs by lowering interfacial tension and increasing water viscosity. Demand concentrates in Saudi Arabia's Ghawar field where high-temperature, high-salinity conditions exceed legacy polymer design envelopes.
- Gas Injection:CO2 and hydrocarbon miscible flooding target light oil reservoirs where miscibility development mobilizes residual oil. Permian Basin operators leverage IRA 45Q tax credits to compress net CO2 supply costs.
- Miscible Flooding:Controlled solvent injection achieves single-phase displacement in deep, high-pressure formations. North Sea operators apply miscible methods in mature Brent-type reservoirs nearing waterflood limits.
Thermal recovery commands the established base. The steepest expansion runs through chemical injection.
Oil Field Type:
Application setting dictates equipment specifications, logistics requirements, and regulatory exposure for EOR deployments.
- Onshore:Surface accessibility enables pad drilling, centralized steam generation, and pipeline CO2 distribution at scale. US Midcontinent independent producers favor onshore chemical EOR for lower capital barriers and faster pattern optimization.
- Offshore:Platform constraints limit thermal method feasibility while favoring gas injection and compact chemical skids. Norwegian North Sea assets deploy low-salinity waterflooding as an incremental offshore recovery technique.
- Shale:Ultra-low permeability requires huff-and-puff gas injection rather than continuous flooding. Permian operators experiment with CO2 huff-and-puff in Wolfcamp and Bone Spring formations.
- Heavy Oil:Viscosity exceeding 10,000 centipoise functionally mandates thermal methods for surface production. Venezuela's Orinoco Belt and Canada's Athabasca region anchor heavy oil thermal demand.
Onshore development commands the established base. Offshore applications are climbing the fastest as platform electrification enables new injection architectures.
End User:
Customer type determines procurement sophistication, technology integration depth, and local content obligations.
- National Oil Companies:Saudi Arco, ADNOC, and CNPC anchor megaproject demand with integrated research capabilities and long-term field development horizons. NOCs mandate local content thresholds that reshape contractor selection in Saudi Arabia's In-Kingdom Total Value Add program.
- Independent Producers:Permian Basin operators and US Midcontinent independents unbundle services, procuring polymer supply, reservoir characterization, and well intervention from separate vendors rather than single-source integrated providers.
- Oilfield Services:Schlumberger, Halliburton, and Baker Hughes deploy integrated technology platforms spanning reservoir characterization through chemical manufacturing and well intervention.
- Refiners:Downstream integration into upstream EOR secures heavy crude feedstock for complex conversion units. Motiva and Saudi Aramco affiliates pursue refinery-anchored heavy oil production.
National oil companies command the established base. Independent producers are gaining share fastest as project finance structures lower capital barriers.
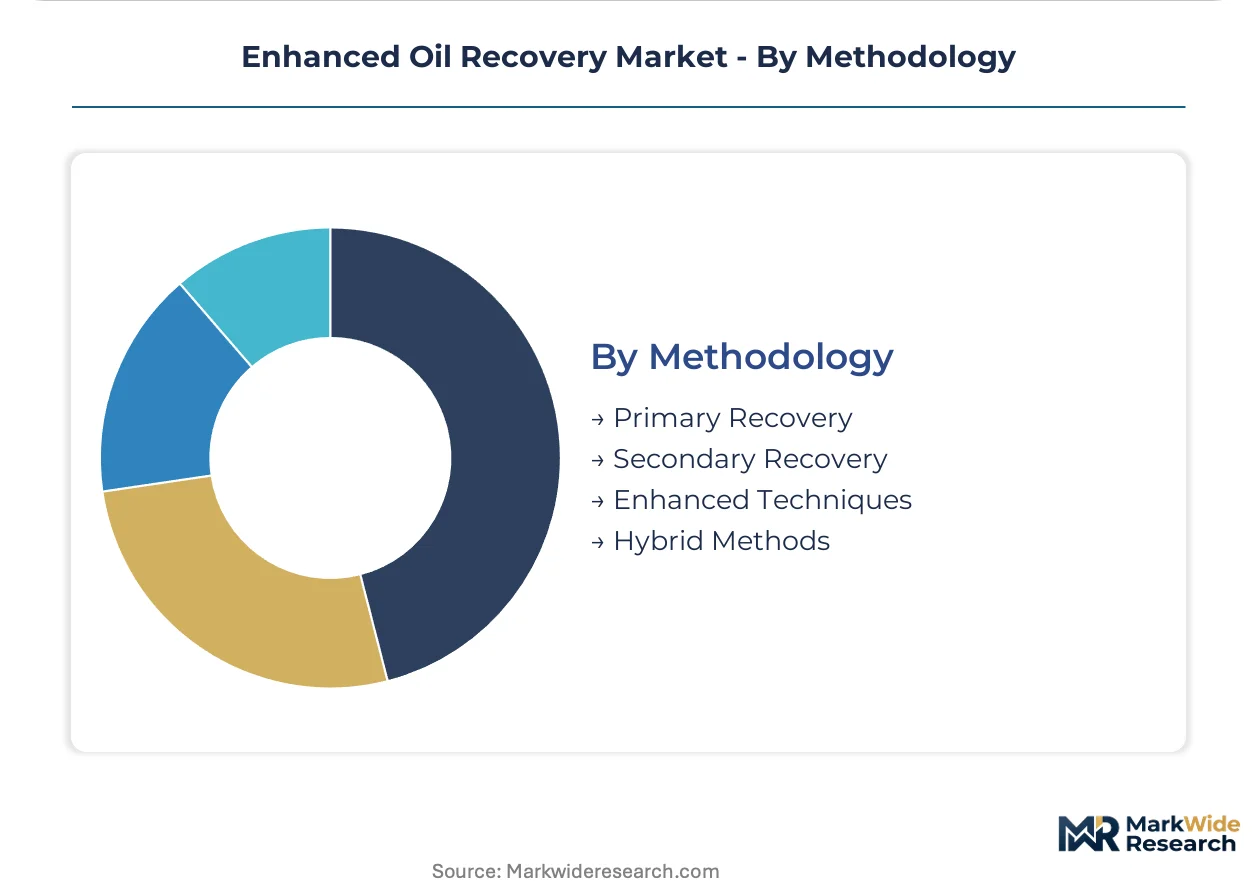
Methodology:
Maturity stage framing distinguishes legacy production maintenance from advanced recovery techniques targeting residual oil.
- Enhanced Techniques:Tertiary methods including thermal, gas, and chemical injection target oil remaining after waterflood depletion. These methods achieve recovery factors exceeding 50 percent of original oil in place in carbonate megaprojects.
- Secondary Recovery:Waterflooding and pressure maintenance programs remain the dominant transition stage between primary depletion and tertiary methods. Most Saudi carbonate fields currently operate in secondary recovery mode with EOR expansion underway.
- Primary Recovery:Natural drive mechanisms including solution gas drive and water drive exploit reservoir energy without injection. Primary methods typically recover less than 10 percent of heavy oil in place.
- Hybrid Methods:Sequential or simultaneous application of multiple EOR techniques tuned to reservoir heterogeneity. Operators in Daqing field combine polymer flooding with surfactant-alternating-gas processes.
Enhanced techniques command the established base. Hybrid methods are expanding most quickly as digital twin platforms enable real-time process optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's 45Q tax credits are compressing project payback periods for CO2-enhanced oil recovery, while Saudi Arabia's carbonate megaprojects pull chemical injection technologies into high-temperature, high-salinity reservoir conditions.
United States
Permian Basin operators leverage IRA 45Q incentives to reduce net CO2 supply costs for carbon-enhanced oil recovery developments. The EPA regulates CO2 sequestration under Class VI well standards, shaping project economics and permitting timelines. Midland-Odessa anchors Permian CO2 infrastructure with established pipeline networks connecting industrial point sources to oilfields.
Saudi Arabia
Saudi Aramco's Ghawar and Khurais field expansions drive demand for surfactant-polymer formulations engineered for carbonate heterogeneity. The national regulator mandates local content requirements and environmental impact assessments under the In-Kingdom Total Value Add program. Dhahran's technology corridor concentrates EOR research centers and contractor operations serving Eastern Province megaprojects.
China
Ministry of Ecology and Environment constraints on steam-based thermal projects redirect investment toward surfactant-polymer systems in Daqing and Shengli fields. Dual carbon goals enforce emissions caps that accelerate chemical and gas injection alternatives. Daqing's mature oilfield complex hosts the country's largest polymer flooding deployment with integrated manufacturing supply chains.
Canada
Thermal recovery methods dominate Alberta's oil sands where steam-assisted gravity drainage targets heavy oil viscosity reduction. Provincial regulators enforce methane emissions monitoring and water use restrictions for thermal projects. Fort McMurray anchors the Athabasca region's thermal EOR infrastructure with centralized steam generation and bitumen upgrading facilities.
Norway
Equinor and partners deploy low-salinity waterflooding as an incremental recovery technique in mature North Sea assets without full chemical EOR capital commitments. The Norwegian Petroleum Directorate mandates decommissioning security and emissions reporting for offshore enhanced recovery. Stavanger's energy cluster concentrates subsea technology providers and reservoir engineering expertise serving North Sea brownfield redevelopment.
Enhanced Oil Recovery Market Vendor Landscape
On the supply side, the industry is consolidating around integrated technology platforms that span reservoir characterization through chemical manufacturing and well intervention. Three strategic archetypes dominate: full-service oilfield services conglomerates with manufacturing scale, national oil company affiliates with captive demand, and specialized chemical suppliers with formulation expertise. Competitive moves center on unbundling integrated service packages to capture independent operator procurement and local content compliance in Middle Eastern markets.
Within the integrated services tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify archetypes defined by technology breadth and manufacturing scale. Schlumberger represents the reservoir characterization-to-chemical design vector. Halliburton occupies the polymer supply and well intervention position. Baker Hughes anchors the gas injection systems and digital monitoring specialization. These three entities collectively shape competitive dynamics through their respective platform strategies.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell plc |
| BP plc |
| TotalEnergies SE |
| Occidental Petroleum Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in North American polymer manufacturing is compressing margins for chemical EOR suppliers while simultaneously expanding procurement leverage for Permian Basin operators and Saudi Aramco contractors. This utilization imbalance feeds directly into pricing posture: suppliers accept extended payment terms and bundled service discounts to defend offtake volumes in a buyer-favorable environment.
Pricing Analysis
Certification level creates the primary spread across EOR chemical supply tiers, with ISO-certified polymer grades commanding meaningful premiums over industrial-grade alternatives in Saudi Arabia's In-Kingdom Total Value Add program. Project-based long-term offtake contracts dominate, though spot purchasing resurges during pattern optimization cycles. Price differentiation hinges on thermal stability specifications for high-temperature carbonate reservoirs and volume scale commitments. Cost compression in standard-grade polymers is intensifying because Chinese manufacturers are expanding export capacity into Middle Eastern markets. National oil companies exhibit the lowest price sensitivity due to integrated R&D budgets, while US Midcontinent independents aggressively unbundle services to minimize unit chemical costs.
Supply Chain Analysis
US export controls on advanced reservoir simulation software and fiber-optic sensing technology constrain technology transfer to certain national oil company research centers, fragmenting equipment procurement channels. Manufacturing concentrates in the United States, China, and Germany for polymer feedstocks, specialty surfactant formulations, and precision downhole gauges respectively. The supply chain draws from acrylamide monomer production, ethylene oxide derivatives, and rare-earth-doped optical fibers as critical inputs. Single-source vulnerability runs through CO2 pipeline networks concentrated in the US Gulf Coast industrial corridor. Distribution runs through integrated service company logistics platforms and independent chemical distributors serving unbundled procurement patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as national oil companies consolidate megaproject awards and independent operators expand direct vendor management capabilities, compressing supplier margins and reshaping contract structures across the value chain.
For Market Incumbents: Insulate polymer supply margins through backward integration into acrylamide monomer production in the US Gulf Coast, while accelerating thermal-stable formulation R&D to defend positioning in Saudi Arabia's high-temperature carbonate megaprojects. The threat of Chinese chemical exporters gaining IECEx certification for Middle Eastern deployment demands preemptive capacity lock-ups with Aramco and ADNOC. For New Entrants and Emerging Players: Pursue white-space opportunities in direct air capture integration for CO2 sourcing in regions lacking industrial point-source infrastructure, targeting European North Sea assets and stranded Permian sub-basins. The most penetrable segment sits with independent operators unbundling services in the US Midcontinent, where technical procurement sophistication supports multi-vendor chemical supply without integrated service overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty chemical suppliers with decade-long polymer flooding contracts anchored to Saudi and Chinese national oil company fields. Long-term viability favors acquisition targets possessing in-house surfactant-polymer formulation capabilities and established Class VI well construction partnerships. The signal to watch is EPA permitting velocity for CO2 sequestration projects, as accelerated approval timelines would inflect capital allocation toward carbon-enhanced oil recovery infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal-Stable Polymer R&D Investment | Unlocks Ghawar and Khurais field deployment where temperatures exceed conventional hydrolysis limits. |
| Direct Air Capture Integration | Creates closed-loop CO2 sourcing for Permian operators lacking pipeline access to industrial point sources. |
| Digital Twin Platform Deployment | Compresses pattern optimization cycles for Saudi Aramco's carbonate megaprojects from months to weeks. |
| Class VI Well Construction Partnership | Accelerates EPA permitting timelines for Occidental and independent Permian carbon-EOR developments. |
| Local Content Compliance Buildout | Satisfies In-Kingdom Total Value Add thresholds for Schlumberger and Halliburton Saudi contracting. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with reservoir engineers at national oil companies, polymer supply procurement leads, EPA underground injection control specialists, and digital twin platform developers. Secondary validation drew from SEC 10-K filings of integrated service companies, EPA Class VI permit application databases, Saudi Aramco technical papers, and IEA enhanced oil recovery technology roadmaps. Bottom-up pattern deployment counts across major fields were triangulated against top-down chemical consumption estimates from trade flow data.
Calibration against historical deployment trajectories anchored volume projections across the analysis window, with technology segmentation disaggregating thermal, chemical, gas injection, and hybrid method adoption curves. Modeled dimensions spanned reservoir type, crude viscosity class, operator archetype, and regulatory framework cluster. CAGRs were derived from least-squares fitting of deployment curves against oil price scenario bands. Forecast inputs incorporated polymer thermal degradation kinetics, CO2 pipeline network expansion assumptions, and national oil company capital budget allocation patterns.
Macroeconomic conditions sit as an overlay; deviation in Brent crude price bands or carbon credit valuation trajectories would shift the trajectory of chemical EOR deployment versus gas injection alternatives. Forecasts reflect documented assumptions regarding EPA permitting velocity, Saudi local content enforcement intensity, and Chinese dual carbon goal implementation pace. Material shifts in IRA 45Q credit permanence or Middle East geopolitical risk premiums would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market