
 East Africa Oil and Gas Downstream Market | 2026-2036
East Africa Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Oil and Gas Downstream Market Foresight
API certification for petroleum product quality is redrawing competitive boundaries across East African downstream markets. TotalEnergies leverages its integrated supply chain from import terminals to retail networks across Kenya and Tanzania. Eni anchors its position through offshore gas development tied to domestic power generation offtake. China National Petroleum Corporation competes via infrastructure financing linked to refinery and pipeline projects in Uganda and South Sudan.
The East Africa oil and gas downstream sector encompasses refining, storage, distribution, and marketing of crude oil derivatives including gasoline, diesel, jet fuel, heating oil, and base petrochemical feedstocks, with specifications typically requiring sulfur content below 50 ppm for road fuels under regional standards. Refined fuels dominate current revenue pools given transport sector dependence across the region, while petrochemicals represent the fastest-growing segment as Kenya and Tanzania develop import substitution capacity for plastics and fertilizers. Industrial supply channels capture premium margins through direct contracts with mining and manufacturing operations, whereas retail outlets face volume competition from informal cross-border fuel flows.
Kenya's Energy and Petroleum Regulatory Authority, Tanzania's Energy and Water Utilities Regulatory Authority, and the East African Community's Common Market Protocol collectively shape fuel pricing mechanisms, import licensing, and cross-border pipeline standards. These frameworks determine who can access storage terminals, distribute products, and participate in government tender processes. Stakeholders must track regulatory divergence between national petroleum pricing formulas and emerging carbon accounting requirements tied to development finance.
Market Dynamics
The East African Community's harmonized petroleum standards are compressing product quality differentials while concentrating procurement authority among import terminal operators with certified storage infrastructure.
Growth Catalysts
- Power sector fuel switching:Kenya's gas-fired generation expansion is pulling LNG and LPG through Mombasa import terminals, creating dedicated offtake contracts with coastal storage facilities.
- EAC Common Market Protocol:Cross-border pipeline standardization is eliminating technical barriers to product movement between Kenya, Tanzania, and Uganda.
- Refinery modernization:Hydrocracking upgrades at coastal processing hubs are enabling 10 ppm ultra-low sulfur diesel production for domestic and export markets.
Market Restraints
- Import dependency concentration:Over 90 percent of refined product supply flows through three coastal terminals, creating single-point vulnerability to maritime logistics disruptions.
- Currency mismatch exposure:Dollar-denominated crude and product purchases against shilling-denominated retail sales generate working capital squeezes during exchange rate volatility.
- Informal cross-border arbitrage:Unregulated fuel flows from neighboring markets with divergent tax regimes erode formal channel volumes in border zones.
Strategic Opportunities
- Uganda pipeline corridor development:The East African Crude Oil Pipeline termination at Tanga offers integrated storage and distribution infrastructure for regional product redistribution.
- LPG cylinder penetration programs:National clean cooking initiatives in Tanzania and Kenya are accelerating household fuel substitution away from biomass and kerosene.
- Digital bunkering platforms:Vessel fueling coordination apps are compressing port turnaround times for maritime traffic at Dar es Salaam and Mombasa.
Industry Challenges
- API certification backlog:Laboratory accreditation delays for product quality testing are extending inventory release times at import terminals.
- Specialized tankage scarcity:Dedicated LPG and bitumen storage capacity constraints limit product mix flexibility during demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Oil and Gas Downstream Market |
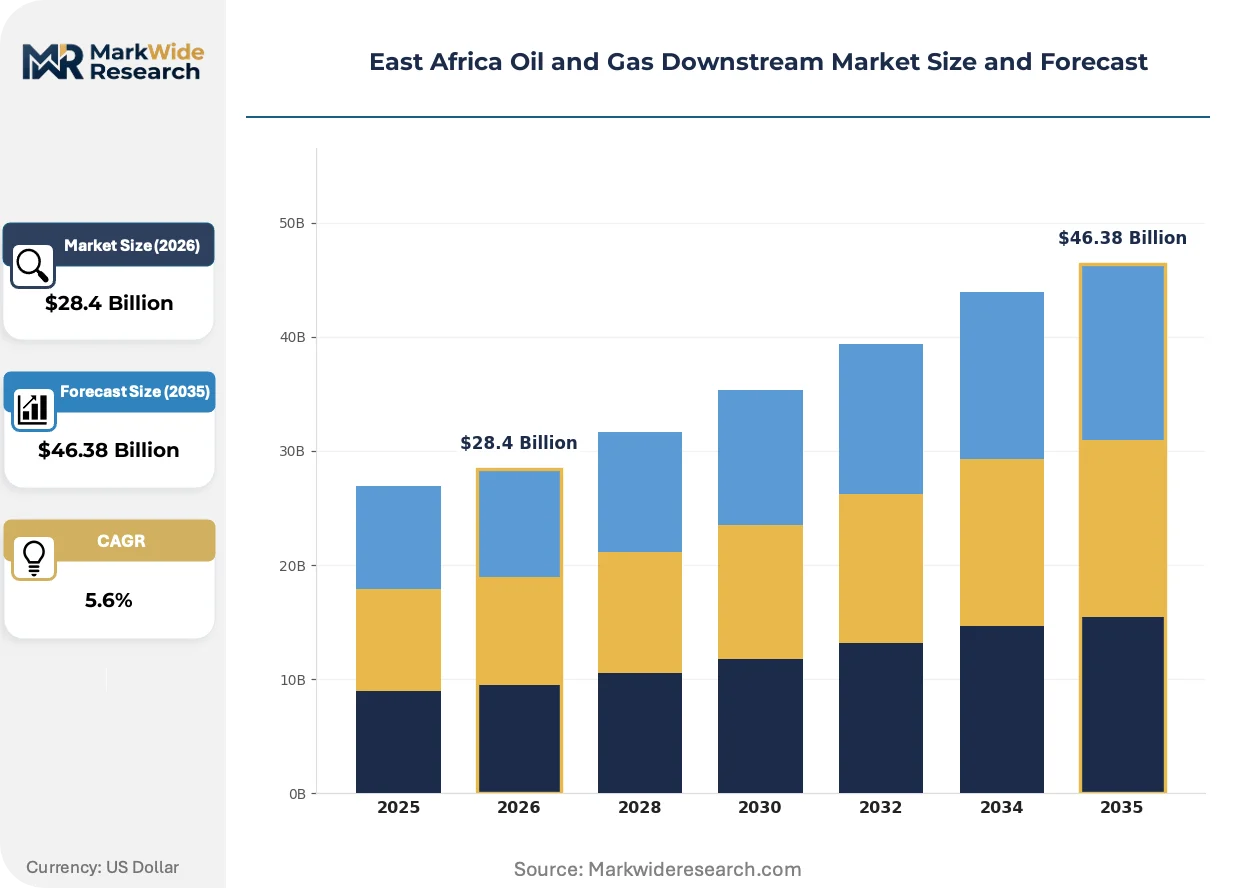
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $46.38 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Asphalt Distribution Channel: Retail Outlets, Industrial Supply, Wholesale Distributors, Online Platforms Service Type: Transport Services, Storage Solutions, Blending Services, Consulting End User: Transportation Sector, Industrial Manufacturing, Construction, Power Generation |
| Companies Covered | Eni, TotalEnergies, Sudan National Petroleum Corporation, Equinor, Exxon Mobil Corporation, China National Petroleum Corporation, Petrogal SA, Savannah Energy, Royal Dutch Shell, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Oil and Gas Downstream Market Shifts & Advancements
Digital infrastructure and regulatory convergence are compressing transaction layers while elevating quality transparency requirements across East African fuel supply chains.
Automated tank gauging and terminal management systems are supplanting manual dipstick measurements and paper-based inventory reconciliation at coastal storage facilities. Major import terminal operators in Mombasa and Dar es Salaam are completing sensor network deployments that enable real-time custody transfer verification. This infrastructure is compressing product losses from evaporation and measurement disputes while accelerating vessel discharge rates.
Kenya's Energy and Petroleum Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority are converging on common sulfur specifications for road fuels ahead of full EAC harmonization. The phased 50 ppm to 10 ppm transition is forcing refinery upgrade investments and import source diversification. Transport fleet operators in Nairobi and Dar es Salaam are accelerating pre-buying of compliant stock ahead of enforcement deadlines.
Direct-to-fleet fueling contracts are bypassing traditional retail network intermediaries for mining and logistics operators with concentrated vehicle pools. Major construction and haulage companies in Kenya's Rift Valley and Tanzania's Central Corridor are negotiating bulk diesel deliveries to captive on-site storage. This channel compression is visible most acutely in gold mining districts around Geita and industrial zones outside Nairobi.
East Africa Oil and Gas Downstream Market Segmentation
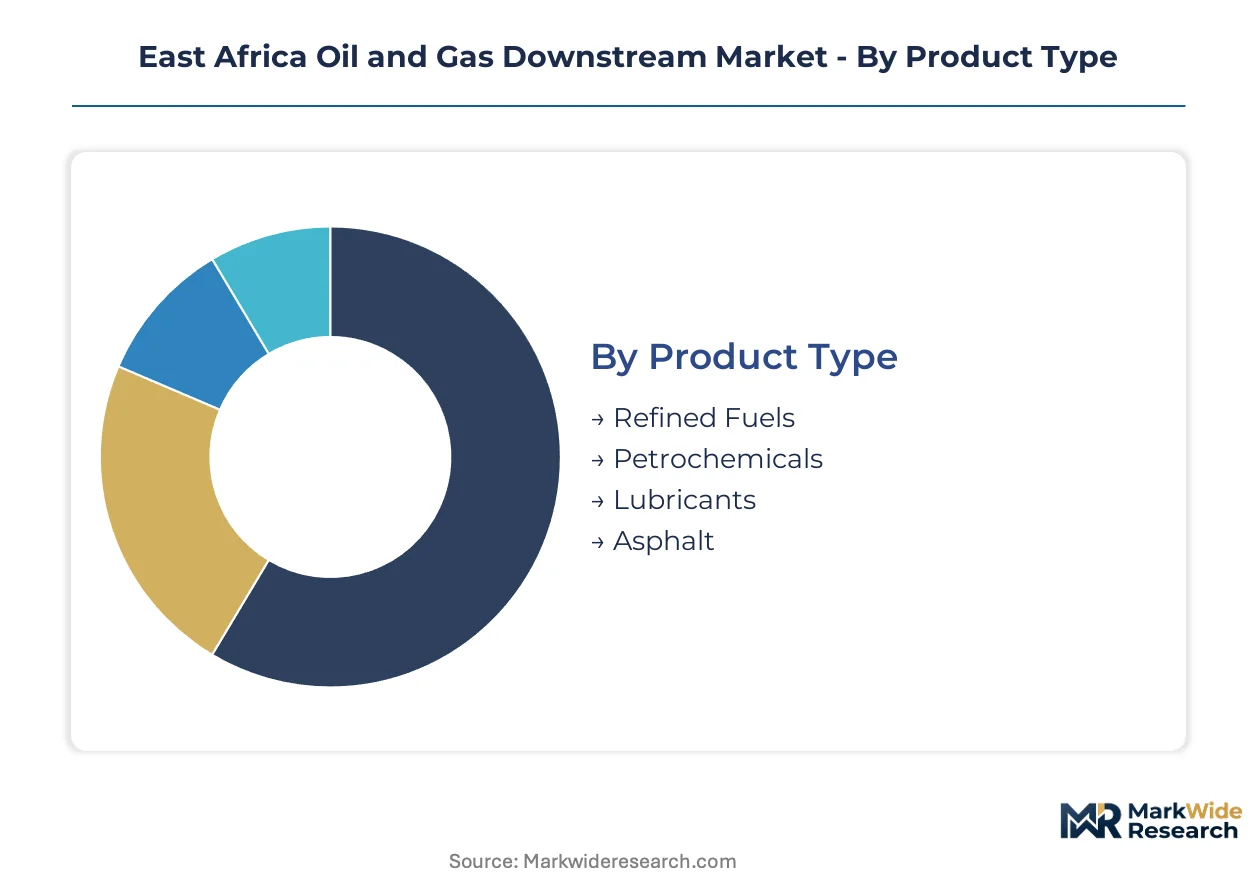
Segmentation in East Africa's downstream oil and gas market reveals how regulatory frameworks, infrastructure constraints, and end-use demand patterns create distinct competitive arenas. Each dimension—product type, distribution channel, service type, and end user—operates under different margin structures and capital intensity requirements.
Product Type:
Kenya's Energy and Petroleum Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority enforce divergent sulfur specifications that segment product quality tiers across the region.
- Refined Fuels:Gasoline, diesel, and jet fuel meeting EAC harmonized standards of 50 ppm sulfur content, with coastal terminals in Mombasa and Dar es Salaam handling bulk import and storage. Kenya's Rift Valley transport corridors and Tanzania's Central Corridor generate concentrated diesel offtake from mining and logistics fleets.
- Petrochemicals:Base feedstocks for plastics and fertilizers including naphtha and propylene derivatives. Demand concentrates around Mombasa's emerging industrial zone as Kenya pursues import substitution for packaging materials and agricultural inputs.
- Lubricants:Engine oils and industrial lubricants formulated for tropical operating conditions and extended drain intervals. Blending operations in Nairobi and Dar es Salaam serve commercial vehicle fleets and construction equipment.
- Asphalt:Bitumen for road construction and waterproofing applications, imported in heated bulk shipments through coastal terminals. Tanzania's Central Corridor infrastructure program and Kenya's Northern Corridor expansion drive bulk procurement.
Refined fuels handles the majority of throughput; petrochemicals is climbing the fastest on share.
Distribution Channel:
Channel economics vary sharply between high-volume wholesale operations and fragmented retail networks subject to informal cross-border competition.
- Retail Outlets:Branded and independent fuel stations serving passenger vehicles and small commercial operators across Nairobi, Dar es Salaam, and secondary cities. Margin compression from unregulated fuel flows in border zones around Busia and Namanga challenges formal channel economics.
- Industrial Supply:Direct contracts with mining, manufacturing, and construction operations featuring captive on-site storage and volume-based pricing. Gold mining districts around Geita and cement plants in Kenya's Athi River corridor anchor this channel's premium margin structure.
- Wholesale Distributors:Bulk product redistribution from coastal import terminals to inland depots and secondary markets. The East African Crude Oil Pipeline termination at Tanga is reshaping wholesale geography for Uganda and Rwanda.
- Online Platforms:Digital fuel ordering and fleet management systems enabling direct scheduling of bulk deliveries. Nairobi-based logistics technology providers are piloting automated procurement for commercial transport operators.
Industrial supply captures the highest margin per liter; online platforms are gaining share fastest among emerging channels.
Service Type:
Service differentiation reflects infrastructure ownership patterns and the scarcity of certified technical capabilities across the region.
- Transport Services:Product movement via road tanker, rail, and coastal barge from import terminals to inland distribution points. Kenya's meter-gauge rail rehabilitation and Tanzania's standard-gauge corridor determine modal economics.
- Storage Solutions:Tank farm operations at Mombasa and Dar es Salaam terminals with automated gauging and custody transfer systems. API certification requirements for quality testing are extending inventory release timelines.
- Blending Services:Fuel additive mixing and lubricant formulation for specification compliance and performance enhancement. Nairobi and Dar es Salaam blending plants serve regional markets with customized product batches.
- Consulting:Regulatory compliance, supply chain optimization, and carbon accounting advisory for downstream participants. Development finance conditionality is elevating demand for emissions tracking expertise.
Storage solutions commands the highest capital barriers; consulting is expanding most quickly as regulatory complexity deepens.
End User:
End-use demand concentration shapes procurement scale and contract structures across downstream market participants.
- Transportation Sector:Road freight, passenger bus operations, and aviation fuel offtake dominating refined fuel consumption. Kenya's Northern Corridor and Tanzania's Central Corridor freight corridors generate predictable high-volume demand.
- Industrial Manufacturing:Cement, steel, and food processing operations requiring diesel for captive power and process heat. Grid reliability gaps in manufacturing zones sustain fuel-based backup generation.
- Construction:Earthmoving equipment and asphalt demand tied to infrastructure project cycles. Tanzania's Central Corridor and Kenya's Vision 2030 flagship projects drive episodic bulk procurement.
- Power Generation:Gas-fired and diesel-fired electricity plants procuring LNG, LPG, and fuel oil through long-term offtake agreements. Kenya's Lake Turkana wind backup and Tanzania's Kinyerezi gas expansion anchor this segment's growth trajectory.
Transportation sector absorbs the largest volume share; power generation is the fastest mover on share as fuel switching accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power generation utilities and mining conglomerates concentrate procurement authority across East African downstream markets. Coastal import terminals at Mombasa and Dar es Salaam anchor supply logistics. The East African Community's harmonized petroleum standards are compressing quality differentials between national markets.
Kenya
Kenya's Energy and Petroleum Regulatory Authority enforces 50 ppm sulfur specifications for road fuels ahead of the 10 ppm transition. Lake Turkana wind backup plants and Kinyerezi gas expansion projects are pulling LNG and LPG through Mombasa terminals. The Northern Corridor freight network generates concentrated diesel offtake from haulage fleets serving Nairobi industrial zones.
Tanzania
Tanzania's Energy and Water Utilities Regulatory Authority oversees fuel pricing formulas and import licensing for Dar es Salaam terminal operators. The Central Corridor infrastructure program is driving episodic bulk asphalt procurement for road construction. Gas-fired generation expansion at Kinyerezi is creating dedicated LNG offtake contracts with coastal storage facilities.
Uganda
Uganda's petroleum supply depends on pipeline corridors from Mombasa and the emerging Tanga termination point for the East African Crude Oil Pipeline. The country's national petroleum regulator coordinates import licensing with regional standards harmonization. Kampala industrial zones and Albertine basin oil development are reshaping demand concentration for refined products.
South Sudan
South Sudan's downstream market relies on northern corridor supply chains through Uganda and Kenya. The country's petroleum ministry coordinates with regional regulators on cross-border pipeline standards. Juba and Upper Nile oil production zones generate demand for diesel-powered captive generation and heavy equipment fueling.
Ethiopia
Ethiopia's fuel procurement flows through Djibouti port terminals with road tanker distribution to Addis Ababa industrial corridors. The country's energy authority manages import licensing for state-controlled petroleum distribution. Manufacturing zones around Addis Ababa and cement plants in the Oromia region anchor diesel demand for process heat and captive power.
East Africa Oil and Gas Downstream Market Competitive Landscape
Player mix skews toward integrated international majors with captive terminal infrastructure and state-linked national oil companies with preferential import access. Terminal ownership concentration at Mombasa and Dar es Salaam creates natural oligopoly positions for storage-certified operators. Strategic archetypes include integrated majors leveraging supply chain control, NOCs with government tender advantages, and infrastructure financiers linking project debt to offtake rights. Competitive moves center on refinery modernization partnerships and digital bunkering platform deployments.
Among integrated majors with East African downstream positions, TotalEnergies, Eni, and Exxon Mobil Corporation represent distinct strategic archetypes. TotalEnergies anchors its position through retail network density across Kenya and Tanzania. Eni exemplifies the upstream-downstream linkage model through offshore gas development tied to power generation offtake. Exxon Mobil Corporation occupies a trading and supply optimization tier with global sourcing capabilities for regional product import.
| Leading Market Players |
|---|
| Eni |
| TotalEnergies |
| Sudan National Petroleum Corporation |
| Equinor |
| Exxon Mobil Corporation |
| China National Petroleum Corporation |
| Petrogal SA |
| Savannah Energy |
| Royal Dutch Shell |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Mombasa terminal operators and Kenya Power lock in supply access while fixing price visibility against Platts Singapore benchmarks. These arrangements insulate procurement officers from exchange rate volatility but tether margins to dollar-denominated crude movements.
Pricing Analysis
Cost-plus contracts indexed to Mean of Platts Singapore (MOPS) dominate refined product procurement. Price differentiation rests on sulfur compliance tier and volume scale, with 10 ppm ultra-low sulfur diesel commanding premium spreads over 50 ppm standard grades. Pricing pressure stems from informal cross-border arbitrage eroding formal channel volumes in Busia and Namanga border zones. Mining and logistics fleets show lowest price sensitivity due to captive on-site storage requirements, while independent retail stations face acute margin compression.
Supply Chain Analysis
Port congestion at Dar es Salaam and Mombasa container terminals elevates inbound logistics costs for bitumen and LPG heated bulk shipments. Geographic supply concentrates in Saudi Arabia, India, and the United Arab Emirates as primary refined product sources. Raw material dependencies span crude feedstocks, fuel additives, and specialized tankage materials. Single-source vulnerability runs through the three coastal import terminals handling over ninety percent of regional supply. Distribution runs through wholesale redistributors with coastal terminal access feeding inland depots across Kenya, Tanzania, and Uganda.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Terminal certification requirements and EAC harmonized standards create structural barriers that protect incumbent positions.
For Market Incumbents: Secure API certification for quality testing laboratories to compress inventory release timelines at Mombasa and Dar es Salaam terminals. Deepen backward integration into captive LPG storage capacity to capture clean cooking initiative demand in Tanzania and Kenya. Emerging digital bunkering platforms threaten traditional vessel fueling coordination margins. For New Entrants and Emerging Players: Lead with digital fleet management platforms targeting Nairobi-based logistics operators with automated procurement and delivery scheduling. White-space concentrates in online fuel ordering channels for mid-sized commercial transport fleets lacking captive storage infrastructure. Uganda's pipeline corridor development at Tanga offers geographic entry point for wholesale redistribution plays. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors infrastructure-heavy operators with certified terminal access. Long-term viability hinges on positioning for power generation fuel switching and petrochemical import substitution capacity buildout. Acquisition targets should display integrated storage-to-retail footprints or specialized bitumen/LPG tankage scarcity premiums. Watch API certification backlog resolution as inflection signal for inventory velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Modernization Partnership | Hydrocracking upgrades enable 10 ppm diesel production for EAC export markets. |
| LPG Cylinder Penetration Program | Tanzania's clean cooking initiative accelerates household fuel substitution from biomass. |
| Digital Bunkering Platform Deployment | Real-time vessel coordination compresses port turnaround times at Dar es Salaam. |
| Pipeline Corridor Storage Development | East African Crude Oil Pipeline termination at Tanga reshapes Uganda supply geography. |
| Direct-to-Fleet Contract Expansion | Mining operators in Geita and Rift Valley bypass retail intermediaries for bulk diesel. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPRA licensing records, EWURA tariff filings, and EAC harmonization protocols. Primary interviews engaged terminal operations managers, fuel procurement officers at Kenya Power and Tanesco, wholesale distributor principals, and logistics fleet managers across Nairobi and Dar es Salaam. Secondary validation drew from customs import data, petroleum pricing formula disclosures, and infrastructure project development databases. Bottom-up volume builds triangulated against top-down macroeconomic demand elasticity estimates.
Segmentation dimensions modeled span product type, distribution channel, service tier, and end-use sector across the analysis window. CAGRs derive from regression analysis against GDP elasticity, fleet expansion rates, and power generation capacity additions. Industry-specific forecast inputs include EAC sulfur specification transition timelines and LNG import terminal commissioning schedules.
The analysis sits within stated boundaries; outcomes outside sustained EAC regulatory convergence or maritime logistics stability would require recalibration. Forecasts reflect assumptions regarding exchange rate volatility management and informal cross-border flow containment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Europe LNG Bunkering Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market