
 Asia-Pacific Floating Production Systems Market | 2026-2036
Asia-Pacific Floating Production Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Floating Production Systems Market Outlook
Integrated subsea processing tied to digital twin architectures is fragmenting traditional FPSO contracting models. SBM Offshore leverages its standardized hull platform to sustain repeat-order economics across Southeast Asian fields. Hyundai Heavy Industries anchors South Korean yard dominance through dedicated offshore fabrication complexes. MODEC Inc differentiates via proprietary turret mooring systems purpose-built for typhoon-prone waters.
Asia-Pacific floating production systems encompass moored vessels and platforms that extract, process, and store hydrocarbons without fixed infrastructure, typically processing crude through three-phase separators at pressures exceeding 150 bar and temperatures up to 180°C before offloading to shuttle tankers. FPSO units command the largest committed capital share given their full-cycle production-storage-offloading integration, while TLP designs gain traction in ultra-deepwater plays where vertical tendon compliance eliminates heave-induced fatigue. Spar platforms occupy niche roles in harsh-environment fields off northwest Australia where minimal vessel motion protects subsea riser integrity.
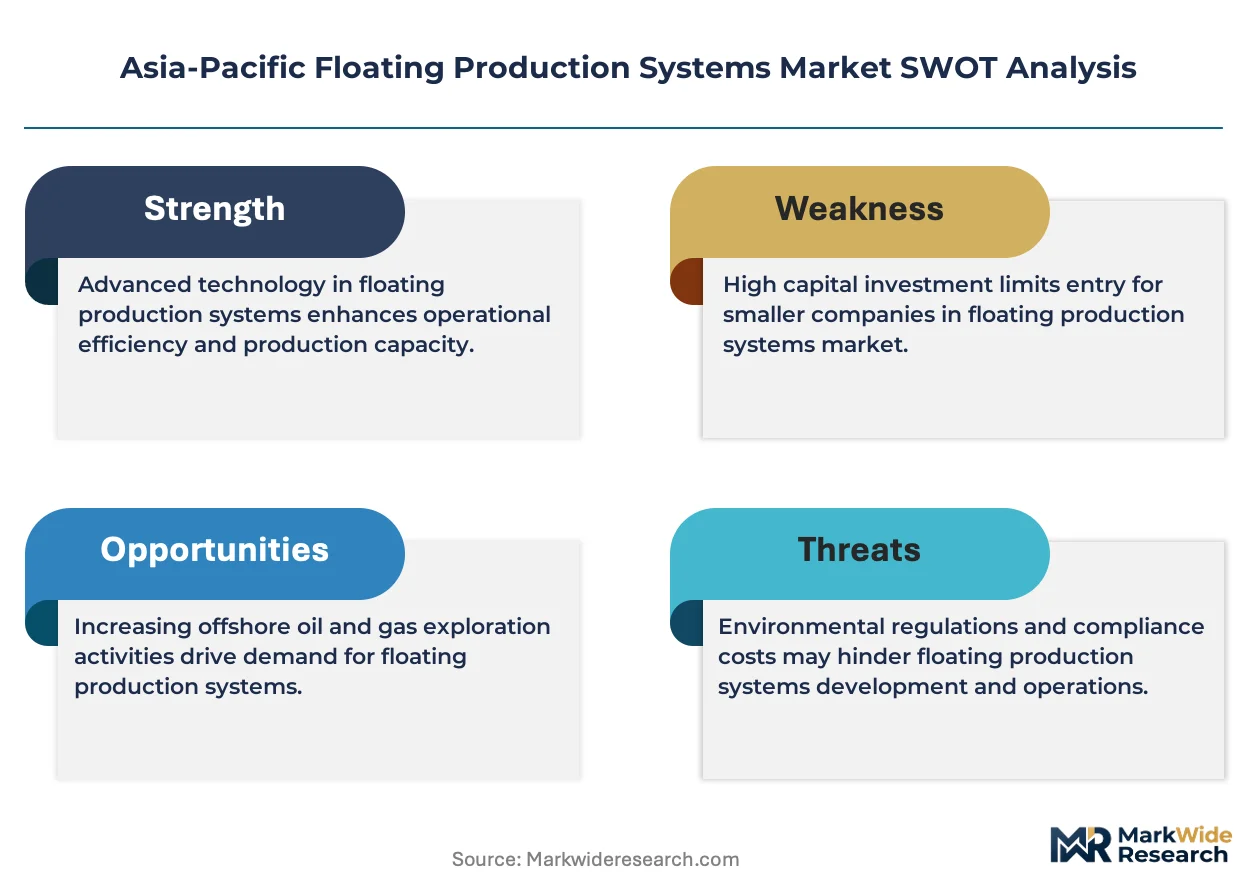
Installation type classifications face tightening scrutiny under Australia's NOPSEMA safety case regime and Indonesia's revised MEMR drilling permits, both mandating dynamic positioning redundancy for deepwater operations. South Korea's KR classification society and Japan's ClassNK enforce hull fatigue-life standards that extend design verification cycles by twelve to eighteen months. Stakeholders must weigh turret supplier concentration against emerging Chinese yard qualification under CCS rules before committing to twenty-year field development contracts.
Market Dynamics
Deepwater exploration economics off Australia's northwest shelf and Indonesia's frontier basins are compressing contracting cycles for moored production solutions, forcing vessel operators to pre-position fabrication slots before final investment decisions.
Growth Catalysts
- Pre-salt discoveries in Indonesia's frontier basins:MEMR drilling permit revisions have streamlined approval timelines for moored production solutions in ultra-deepwater blocks, accelerating field development schedules.
- Australia's NOPSEMA safety case regime:Dynamic positioning redundancy mandates for deepwater operations have institutionalized premium vessel specifications that extend field service life.
- LNG-compatible hull designs:South Korean yard technology leaps enable dual-process capability that unlocks gas-condensate fields previously uneconomic for standalone FPSO deployment.
Market Restraints
- Turret supplier concentration:Proprietary mooring system fabrication concentrates among three specialist yards, creating single-source vulnerability for twenty-year field contracts.
- High-grade steel alloy volatility:HY-80 and HY-100 hull plate input costs fluctuate with nickel and molybdenum spot markets, compressing fabrication margins on fixed-price EPC contracts.
- Subsea riser fatigue life limitations:Steel catenary riser design envelopes constrain water depth ratings to approximately 1,500 meters, excluding the deepest frontier plays.
Strategic Opportunities
- Vietnam's Ca Voi Xanh development:Underpenetrated offshore licensing rounds offer first-mover positioning for integrated FPSO-plus-subsea packages in contested South China Sea blocks.
- Digital twin convergence with subsea processing:Real-time asset integrity monitoring layered onto standardized hull platforms enables performance-based contracting that transfers operational risk to vessel owners.
- Japan's METI offshore wind hybridization pilots:Floating platform technology cross-application creates transferable engineering capabilities for next-generation multi-use hull designs.
Industry Challenges
- Marine warranty surveyor capacity constraints:Classification society specialist shortages at South Korea's KR and Japan's ClassNK extend design verification cycles by twelve to eighteen months.
- Legacy vessel integration complexity:Brownfield tiebacks to existing FPSO infrastructure require bespoke turret modifications that disrupt standardized platform economics.
- Capex intensity for dual-hull LNG storage:Membrane tank retrofits and cryogenic processing trains demand front-loaded capital deployment that strains project finance structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Floating Production Systems Market |
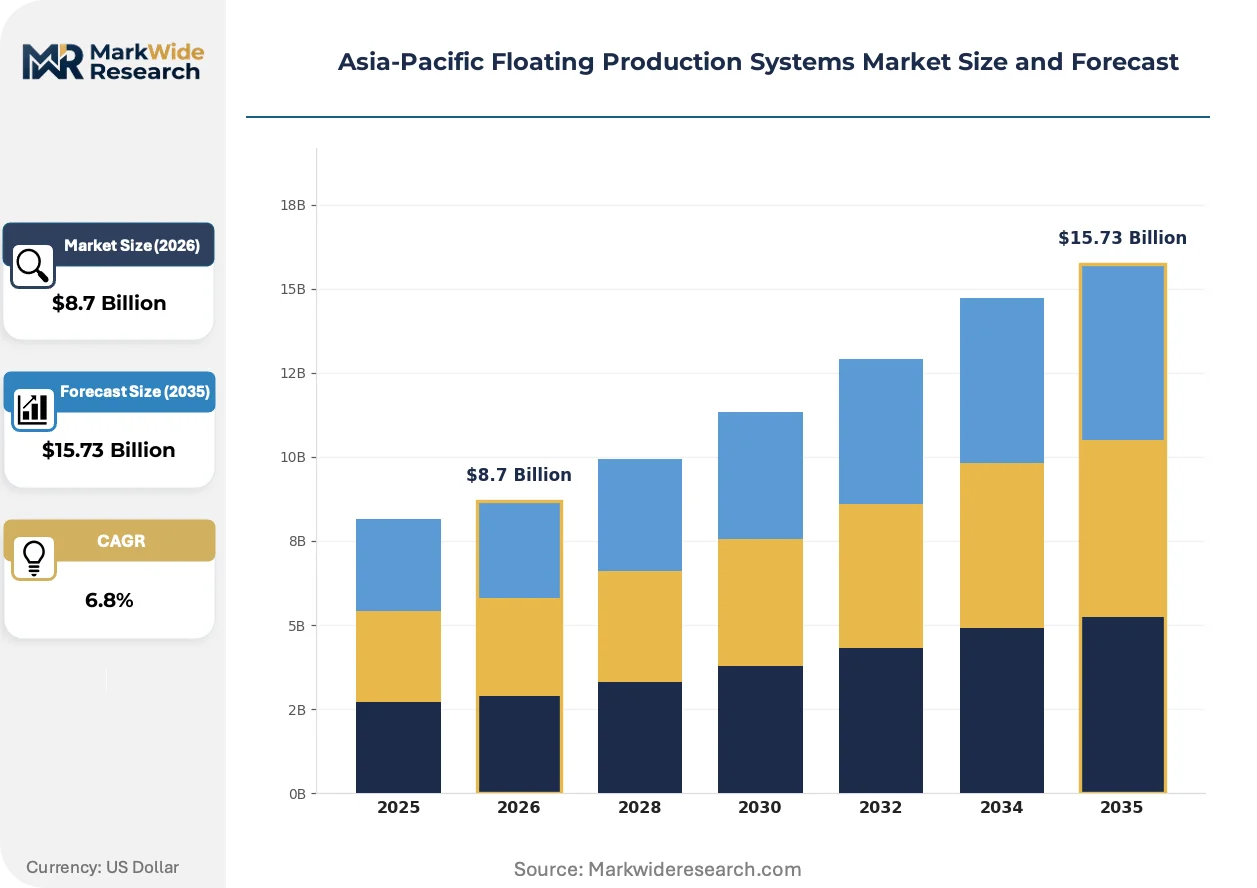
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FPSO, FSO, TLP, Spar Installation Type: Onshore, Offshore, Deepwater, Shallow Water End User: Oil & Gas Companies, EPC Contractors, Service Providers, Government Agencies Service Type: Production, Maintenance, Decommissioning, Inspection |
| Companies Covered | Bumi Armada Berhad, Hyundai Heavy Industries Co. Ltd, Keppel Offshore & Marine Ltd, SBM Offshore, Samsung Heavy Industries Co. Ltd, MODEC Inc, Malaysia Marine and Heavy Engineering SDN BHD, Mitsubishi Heavy Industries Ltd, BW Offshore Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Floating Production Systems Market Strategic Shifts
Subsea processing architectures are fragmenting traditional FPSO contracting models, compressing the boundary between vessel-based and seabed-based hydrocarbon separation while enabling smaller hull formats.
Integrated digital twin platforms are digitizing asset integrity management across Southeast Asian field operations. International oil majors operating Australia's northwest shelf deploy real-time hull stress monitoring combined with predictive maintenance algorithms. This convergence is digitizing operational decision-making that previously relied on periodic physical inspection cycles.
Australia's NOPSEMA safety case regime and Indonesia's revised MEMR drilling permits now mandate dynamic positioning redundancy for deepwater operations. These requirements institutionalize premium vessel specifications that extend design verification timelines. Ultra-deepwater plays off Timor-Leste and Myanmar are most affected, with operators pre-positioning dual-redundancy architectures before regulatory submission.
Buyer procurement patterns are compressing from discrete vessel charter cycles toward integrated subsea-to-surface packages. National oil companies in Indonesia and Malaysia now specify performance-based contracts that transfer operational risk to vessel owners. This behavioral shift is most visible in pre-salt frontier basins where reservoir uncertainty demands flexible production capacity scaling.
Asia-Pacific Floating Production Systems Market Segmentation
Floating production system procurement in Asia-Pacific fragments across vessel configuration, water depth rating, and contracting structure. Each segmentation axis carries distinct implications for capex intensity, regulatory exposure, and operational risk allocation across Australia's northwest shelf and Indonesia's frontier basins.
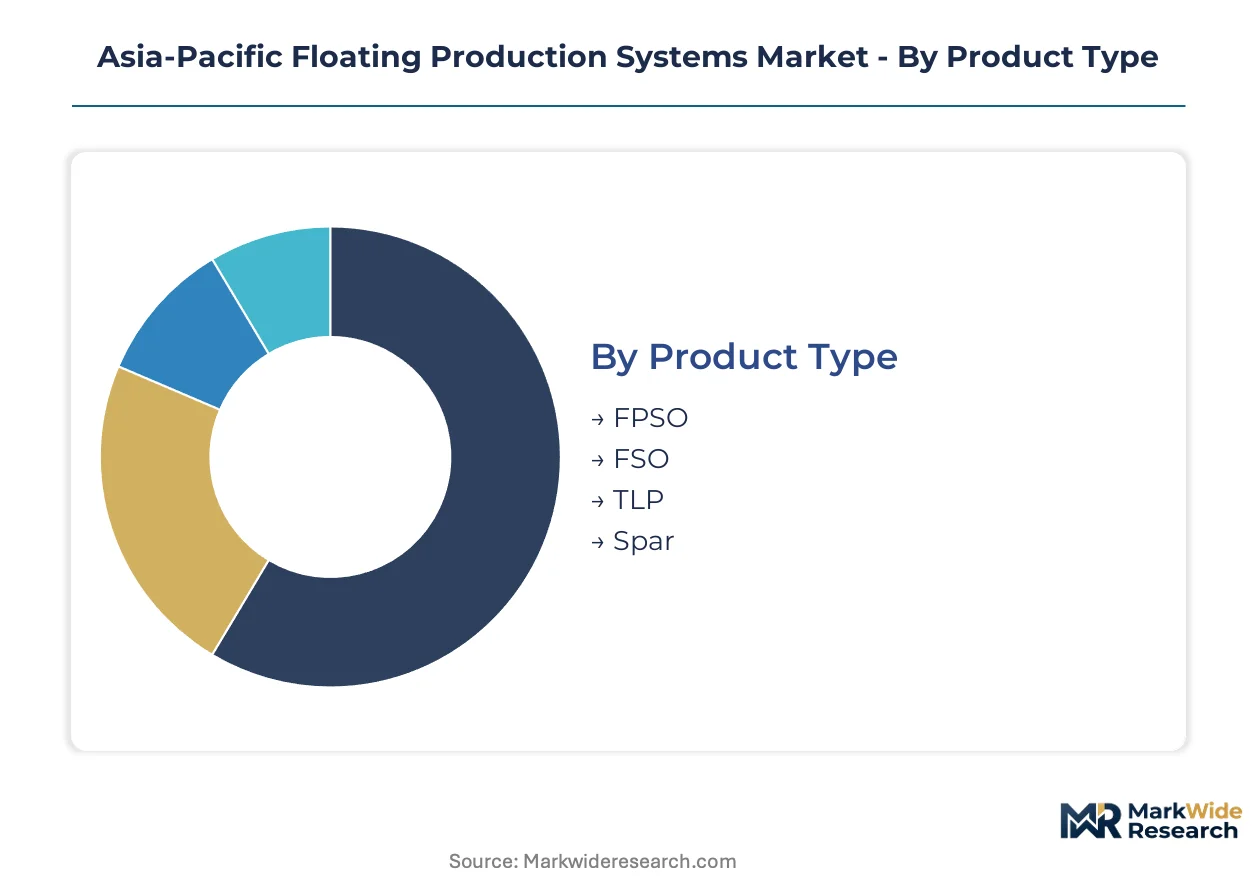
Product Type:
Mature hull configurations anchor current deployment volumes while emerging platform architectures reshape frontier field economics.
- FPSO:Full-cycle production-storage-offloading integration processes crude through three-phase separators at pressures exceeding 150 bar and temperatures up to 180°C before shuttle tanker offloading. Australia's northwest shelf and Indonesia's pre-salt basins concentrate committed capital here, with dual-hull LNG storage retrofits now expanding gas-condensate applicability.
- TLP:Tension-leg platforms deploy vertical tendon compliance to eliminate heave-induced fatigue in ultra-deepwater plays exceeding 1,500 meters. Timor-Leste and Myanmar frontier blocks drive specification demand where steel catenary riser limitations exclude conventional moored solutions.
- Spar:Deep-draft single-column hulls minimize vessel motion to protect subsea riser integrity in harsh-environment fields off northwest Australia.
- FSO:Stripped-down storage-only variants serve brownfield tiebacks and early production systems where processing remains vessel-based.
FPSO configurations retain volume leadership; TLP designs hold the steepest expansion curve as frontier drilling pushes beyond riser fatigue thresholds.
Installation Type:
Water depth classification determines regulatory jurisdiction, dynamic positioning redundancy mandates, and fabrication slot pre-positioning requirements.
- Deepwater:Operations below 500 meters trigger Australia's NOPSEMA safety case regime and Indonesia's revised MEMR drilling permits, both institutionalizing premium vessel specifications with dual-redundancy architectures. Pre-salt discoveries in Indonesia's frontier basins compress contracting cycles here.
- Offshore:Mid-depth moored installations between 200-500 meters dominate current Asia-Pacific deployment, with South Korean yards pre-positioning fabrication slots before final investment decisions.
- Shallow Water:Fixed-platform economics typically prevail above 200 meters, limiting floating system penetration to marginal field redevelopment.
- Onshore:Fabrication and integration activities concentrate at South Korean yard complexes and Singapore assembly facilities.
Offshore installations command current deployment volumes; deepwater ratings are expanding most quickly as exploration frontiers advance.
End User:
Contracting entity type shapes risk allocation, performance guarantee structures, and technology specification authority.
- Oil & Gas Companies:International majors operating Australia's northwest shelf and national oil companies in Indonesia and Malaysia now specify integrated subsea-to-surface packages with performance-based contracting that transfers operational risk to vessel owners.
- EPC Contractors:Fixed-price lump-sum arrangements dominate here, exposing fabricators to high-grade steel alloy volatility in HY-80 and HY-100 hull plate procurement.
- Service Providers:Specialized turret mooring system suppliers and subsea processing integrators occupy critical single-source positions in twenty-year field contracts.
- Government Agencies:Licensing and permitting authorities in Australia, Indonesia, and Timor-Leste enforce classification society standards through KR and ClassNK verification protocols.
Oil and gas companies retain procurement volume leadership; EPC contractors face the steepest margin compression curve under fixed-price discipline.
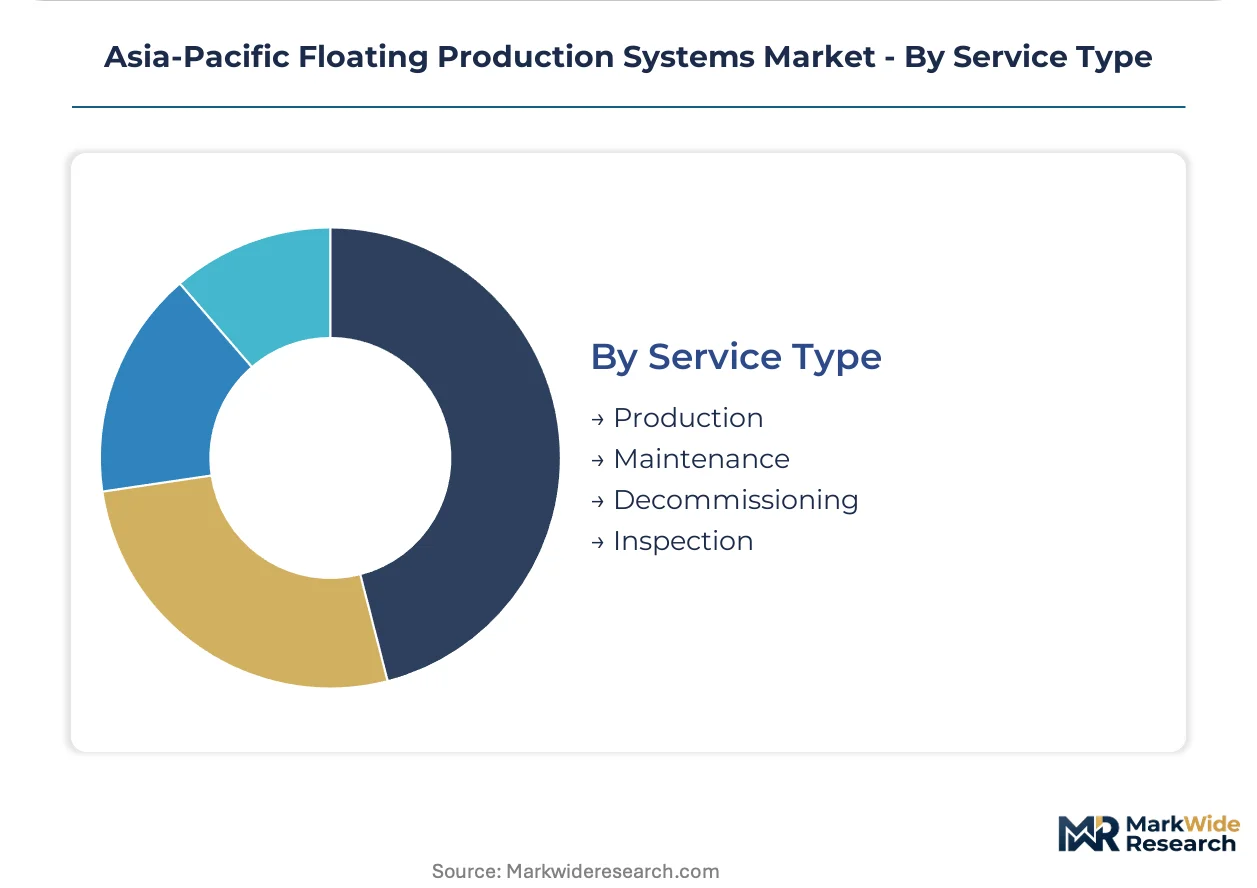
Service Type:
Lifecycle stage segmentation determines revenue predictability, asset utilization rates, and digital twin technology deployment intensity.
- Production:Real-time hull stress monitoring combined with predictive maintenance algorithms now digitizes operational decision-making that previously relied on periodic physical inspection cycles across Southeast Asian field operations.
- Maintenance:Brownfield tiebacks to existing FPSO infrastructure require bespoke turret modifications that disrupt standardized platform economics and extend dry-docking intervals.
- Inspection:Marine warranty surveyor capacity constraints at South Korea's KR and Japan's ClassNK extend design verification cycles by twelve to eighteen months.
- Decommissioning:Twenty-year field development contracts approaching maturity in Australia's mature basins will activate hull recycling and site restoration obligations.
Production services retain revenue leadership; maintenance activities are gaining share fastest as installed base ages and brownfield complexity mounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean fabrication complexes export LNG-compatible hull designs to Indonesia's frontier basins and Australia's northwest shelf, anchoring the region's trade-flow corridor for moored production solutions.
Australia
Deepwater exploration off the northwest shelf drives demand for FPSO units with dual-redundancy dynamic positioning systems. NOPSEMA's safety case regime mandates extended design verification cycles that institutionalize premium vessel specifications. Perth serves as the engineering hub where international majors coordinate field development schedules.
Indonesia
Pre-salt discoveries in frontier basins require moored production solutions capable of processing three-phase separators at extreme pressures. MEMR drilling permit revisions have streamlined approval timelines for ultra-deepwater blocks. Jakarta coordinates licensing rounds that attract integrated subsea-to-surface package bids.
South Korea
Technology leaps in LNG-compatible hull designs enable dual-process capability for gas-condensate fields. KR classification society enforces hull fatigue-life standards that extend verification protocols. Ulsan and Geoje fabrication complexes pre-position slots before final investment decisions from regional operators.
Malaysia
Brownfield tiebacks to existing FPSO infrastructure demand bespoke turret modifications that disrupt standardized platform economics. The country's petroleum regulator enforces performance-based contracting terms that transfer operational risk to vessel owners. Kuala Lumpur anchors procurement coordination for Southeast Asian field developments.
Japan
METI offshore wind hybridization pilots create transferable engineering capabilities for multi-use hull designs. ClassNK specialist shortages extend design verification cycles alongside South Korean counterparts. Tokyo-Yokohama clusters concentrate marine warranty surveyor capacity for regional classification needs.
Asia-Pacific Floating Production Systems Market Competitive Environment
Channel-controlling players compete with product-specialist players across fabrication slots and proprietary mooring technologies. The vendor base concentrates among integrated yard groups and dedicated offshore contractors, creating tiered supply dynamics. Two strategic archetypes dominate: full-cycle FPSO operators with standardized hull platforms, and specialized turret system fabricators with typhoon-resistant engineering. Competitive moves center on pre-positioning fabrication capacity ahead of FID cycles and securing twenty-year performance-based contracts.
Among South Korean fabricators, Hyundai Heavy Industries Co. Ltd and Samsung Heavy Industries Co. Ltd occupy positions as scale-driven hull providers. SBM Offshore exemplifies the full-cycle operator archetype with repeat-order economics across Southeast Asian fields. MODEC Inc represents the specialized tier through proprietary turret mooring systems purpose-built for harsh-environment deployments.
| Leading Market Players |
|---|
| Bumi Armada Berhad |
| Hyundai Heavy Industries Co. Ltd |
| Keppel Offshore & Marine Ltd |
| SBM Offshore |
| Samsung Heavy Industries Co. Ltd |
| MODEC Inc |
| Malaysia Marine and Heavy Engineering SDN BHD |
| Mitsubishi Heavy Industries Ltd |
| BW Offshore Ltd |
| Others |
Value Chain & Pricing Dynamics
The Busan-to-Singapore heavy-lift corridor anchors fabrication logistics for Asia-Pacific floating production systems, with charter rate volatility in the Capesize segment feeding directly into EPC contract contingency pricing and downstream buyer tier segmentation between integrated majors and independent operators.
Pricing Analysis
Next-generation LNG-compatible hull designs command substantial premiums over legacy crude-only configurations, while prior-generation single-hull FPSOs trade at distressed asset values in secondary markets. Project-based lump-sum contracting dominates, with price differentiation driven by KR classification tier and South Korean yard reputation versus emerging Chinese CCS-qualified alternatives. Pricing pressure stems from nickel and molybdenum spot volatility in HY-80 hull plate procurement. National oil companies in Indonesia and Malaysia exhibit lowest price sensitivity given performance-based risk transfer structures; independent EPC contractors face acute margin compression under fixed-price discipline.
Supply Chain Analysis
Tariff exposure between South Korea and China dominates supply chain risk calculus for turret mooring system procurement. Geographic concentration centers on South Korea, Singapore, and China for hull fabrication, with Japan and Norway supplying specialized subsea processing modules. Raw material dependencies rest on high-grade steel alloys, dynamic positioning thruster packages, and cryogenic membrane tank systems. Single-source vulnerability concentrates among three proprietary turret fabricators. Distribution runs through direct EPC contracting to international oil majors and national oil companies, with limited spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating production systems face substitution pressure from subsea processing architectures that compress the boundary between vessel-based and seabed-based separation, forcing incumbents to defend integrated platform economics against modular seabed alternatives.
For Market Incumbents: Insulate fabrication slot portfolios through pre-positioning agreements with South Korean yards before competitor FID cycles. Anchor proprietary turret technology positions against emerging Chinese CCS-qualified alternatives through extended field service contracts. Dynamic positioning redundancy mandates under Australia's NOPSEMA regime create certification barriers that favor established players with verified dual-redundancy architectures. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Ca Voi Xanh development through integrated FPSO-plus-subsea package bids in contested South China Sea blocks. Target brownfield turret modification services where legacy vessel integration complexity disrupts standardized economics for incumbents. Partner with marine warranty surveyors at ClassNK or KR to accelerate design verification timelines that incumbent yards cannot compress. For Investors and Strategic Acquirers: Specialized turret system fabricators with typhoon-resistant engineering capabilities represent the most defensible acquisition archetype given proprietary mooring concentration and twenty-year contract visibility. Long-term viability hinges on exposure to Indonesia's pre-salt frontier basins versus mature Australian northwest shelf decommissioning cycles. Watch MEMR drilling permit issuance velocity as the inflection signal for contracting cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Fabrication Slot Pre-Positioning | Secures Ulsan and Geoje yard capacity before competitor FID commitments lock supply. |
| Dual-Certification Investment | Simultaneous KR and ClassNK qualification expands addressable buyer pool across Australian and Japanese regulatory jurisdictions. |
| Subsea Processing Integration | Compresses vessel hull size requirements while capturing seabed separation value previously lost to specialist contractors. |
| Performance-Based Contracting | Transfers reservoir uncertainty risk to vessel owners under terms national oil companies now mandate. |
| Digital Twin Platform Deployment | Enables real-time hull stress monitoring that extends dry-docking intervals and reduces inspection costs. |
Study Parameters
Desk research of vessel orderbook databases, classification society rule sets, and national petroleum regulator licensing records preceded structured interviews with FPSO project directors, turret system engineering leads, marine warranty surveyors at KR and ClassNK, and procurement executives at Indonesian and Malaysian national oil companies. Secondary validation drew from MEMR drilling permit filings, NOPSEMA safety case submissions, and South Korean yard capacity announcements. Bottom-up field development pipeline analysis triangulated against top-down capex allocation surveys from international oil majors.
Forecast assumptions held regulatory frameworks constant across the analysis window while varying exploration success rates in Indonesia's frontier basins and Australian northwest shelf depletion curves. Segmentation modeling incorporated water depth rating, hull configuration type, contracting structure, and end-user risk allocation profile. CAGRs derived from weighted average of project sanctioning timelines and fabrication slot availability constraints. Industry-specific inputs included steel alloy price trajectory scenarios and dynamic positioning system technology adoption curves.
Sensitivities concentrate around MEMR permit approval velocity, South Korean yard labor availability, and subsea riser fatigue life technology breakthroughs. Forecasts reflect documented assumptions regarding nickel and molybdenum input cost stability and turret supplier concentration persistence. Material shifts in Chinese yard CCS qualification timelines or Australian decommissioning obligation enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market