
 South America Offshore Energy Market | 2026-2036
South America Offshore Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South America Offshore Energy Market Analytics
Brazil's pre-salt basin expansion is reshaping investment flows across the South America offshore energy sector. Petrobras leverages its integrated drilling and production capabilities to dominate deepwater operations in the Santos Basin. Shell anchors its regional portfolio through stakes in multiple pre-salt consortia, while TotalEnergies competes via specialized floating production unit deployments.
South America offshore energy encompasses hydrocarbon extraction and renewable generation systems installed in marine environments beyond territorial coastlines, typically operating at water depths exceeding 100 meters using subsea tiebacks, floating platforms, or anchored turbine arrays. These installations serve utilities and independent power producers requiring baseload electricity or refined fuel feedstocks. Floating platforms and subsea systems currently absorb the majority of capital deployment, with wind turbines representing the fastest-growing technology segment as coastal states auction maritime lease blocks. Oil extraction maintains the largest application share, though renewable generation is attracting disproportionate investor attention due to long-term offtake contracts.
ANP, Brazil's national petroleum regulator, mandates local content requirements that shape supplier selection and equipment sourcing for offshore projects. Environmental licensing protocols under IBAMA and evolving maritime jurisdiction standards across Argentine, Brazilian, and Uruguayan waters determine where developers can feasibly site new infrastructure. Stakeholders must monitor how cross-border regulatory harmonization progresses and whether carbon capture applications secure dedicated licensing frameworks.
Market Dynamics
Brazil's ANP local content mandates are compressing supplier margins while accelerating domestic fabrication capacity for floating production systems. This regulatory pressure is redistributing procurement flows toward certified local yards and reshaping how international contractors structure consortium bids.
Growth Catalysts
- Pre-salt field maturation:Brazil's Santos Basin subsea tieback programs are sustaining rig demand and subsea equipment orders through predictable development cycles.
- Floating offshore wind auctions:Brazil's leasing rounds for maritime renewable blocks are opening new capital deployment channels for turbine developers and mooring specialists.
- ANP concession acceleration:The regulator's streamlined pre-salt block timelines are compressing exploration-to-production intervals for deepwater operators.
Market Restraints
- Steel input volatility:Floating platform hull fabrication depends on specialized high-grade plate whose pricing swings compress EPC margins on fixed-price contracts.
- Subsea equipment supply concentration:Brazil's southeastern yards dominate SURF system integration, creating single-source risk for project timelines.
- Environmental licensing friction:IBAMA's extended maritime impact review timelines delay field development approvals in sensitive coastal zones.
Strategic Opportunities
- Argentine offshore frontier:The country's underexplored Austral and Malvinas basins offer first-mover positioning for seismic contractors and drilling operators.
- Green hydrogen export infrastructure:Uruguay's offshore wind-to-hydrogen pilot zones are attracting electrolyzer and pipeline engineering contracts.
- Decommissioning liability frameworks:Brazil's emerging well abandonment regulations are creating specialized rigless P&A service demand.
Industry Challenges
- Deepwater robotics skill scarcity:ROV pilot and subsea automation technician pipelines cannot match deployment growth in Brazil's ultradeep plays.
- Floating wind mooring certification:Dynamic cable qualification protocols remain unsettled, delaying bankability for pre-commercial arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Offshore Energy Market |
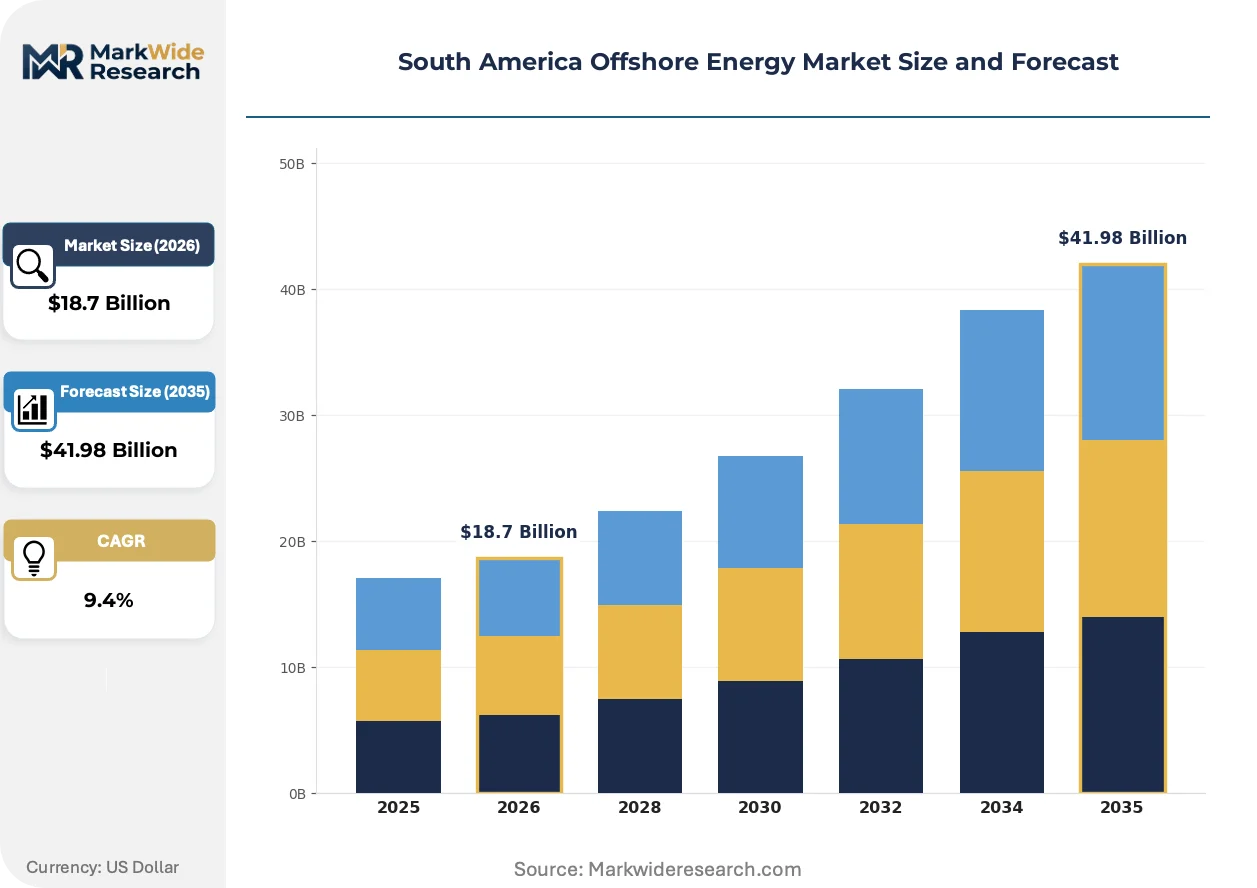
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Decommissioning, Maintenance Technology: Floating Platforms, Subsea Systems, Wind Turbines, Solar Arrays Application: Oil Extraction, Natural Gas Production, Renewable Generation, Carbon Capture End User: Utilities, Independent Power Producers, Government Agencies, Investors |
| Companies Covered | Petrobras, Chevron Corporation, Exxon Mobil Corporation, Repsol SA, Enel Green Power S.p.A., Ecopetrol, Shell, TotalEnergies, CNOOC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Offshore Energy Market Evolving Landscape
Digital twin integration and modular platform design are compressing offshore construction schedules while forcing recalibration of traditional EPC risk allocation models.
Subsea processing technology is collapsing the economic water-depth threshold for standalone field development. Petrobras and international partners are deploying subsea boosting and separation systems at 2,000-meter depths previously requiring surface facilities. This capability is collapsing the capital intensity gap between deepwater and ultradeepwater projects, redirecting exploration budgets toward frontier blocks.
Brazil's ANP local content framework is tightening domestic sourcing quotas for floating production unit hull construction. The regulation is forcing international contractors to form joint ventures with Brazilian shipyards or face bid disqualification. Subsea tree and manifold suppliers are responding by licensing fabrication technology to certified local partners.
Power purchase agreement structures are displacing traditional tariff-based offtake for offshore wind projects. Independent power producers in Brazil's southeastern states are negotiating corporate renewable supply contracts directly with industrial load centers. This channel shift is most visible in São Paulo state's manufacturing corridor, where energy-intensive users are securing 15-20 year price visibility through direct bilateral agreements.
South America Offshore Energy Market Segmentation
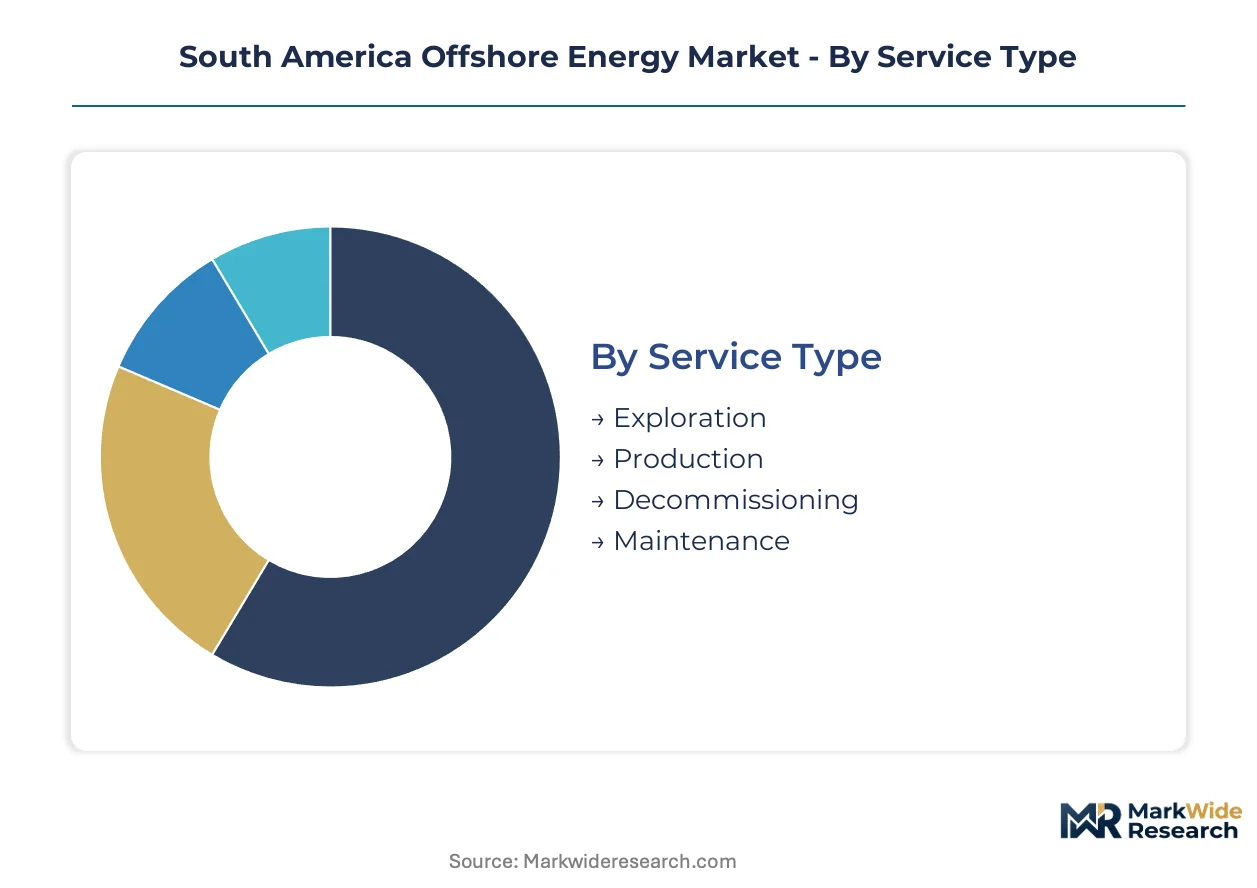
Offshore energy segmentation in South America reflects divergent capital intensity profiles across hydrocarbon and renewable value chains. Service type and technology splits determine procurement patterns, while end-user composition shapes contract structures and financing terms.
Service Type:
Cost tier differentiation across the offshore project lifecycle determines margin structure and equipment utilization rates for contractors.
- Exploration:Seismic acquisition and appraisal drilling programs deploy specialized 3D vessel fleets and dynamically positioned rigs. Demand concentrates in Brazil's southeastern basins where ANP concession rounds accelerate block evaluation timelines.
- Production:Field development encompasses subsea installation, platform commissioning, and tieback construction requiring integrated EPC capabilities. Santos Basin operators sustain this segment through predictable brownfield expansion cycles.
- Decommissioning:Well abandonment and platform removal services are expanding as early-production assets reach end-of-life.
- Maintenance:Inspection, repair, and intervention contracts support operational uptime for floating production units.
Production commands current capital deployment. Exploration is rotating up the share rankings as frontier licensing accelerates.
Technology:
Application requirements across water depth and resource type drive technology selection and supplier specialization.
- Floating Platforms:FPSOs, semisubmersibles, and tension-leg platforms enable hydrocarbon processing in ultradeepwater environments. Brazilian yards anchor fabrication demand through ANP-mandated local content quotas.
- Subsea Systems:Trees, manifolds, and flowlines connect seabed wells to surface facilities. Campos Basin tieback programs sustain equipment orders despite water-depth limitations.
- Wind Turbines:Floating offshore wind installations are gaining project pipeline depth through maritime lease auctions.
- Solar Arrays:Marine photovoltaic applications remain pre-commercial in South American waters.
Floating platforms retain installed base dominance. Wind turbines are climbing the fastest as auction frameworks mature.
Application:
Volume concentration across hydrocarbon extraction versus emerging energy vectors determines infrastructure investment priorities.
- Oil Extraction:Pre-salt carbonate reservoirs in the Santos Basin sustain the majority of regional offshore production. Petrobras-operated fields anchor subsea equipment demand and floating platform orders.
- Natural Gas Production:Associated gas processing and dedicated offshore gas developments supply domestic petrochemical feedstocks.
- Renewable Generation:Wind-to-electron projects are attracting corporate offtake contracts from São Paulo industrial load centers.
- Carbon Capture:Subsurface storage appraisal is advancing through saline aquifer characterization studies.
Oil extraction maintains capacity leadership. Renewable generation is expanding most quickly through bilateral power purchase structures.
End User:
Customer type fragmentation shapes contract tenor, risk allocation, and financing instrument selection across project categories.
- Utilities:State-controlled and privatized electricity distributors procure baseload capacity through regulated auctions. Brazilian distributors dominate floating wind offtake negotiations.
- Independent Power Producers:Merchant developers and corporate renewable suppliers structure bilateral contracts outside tariff mechanisms.
- Government Agencies:National oil companies and energy ministries direct exploration licensing and strategic reserve development.
- Investors:Infrastructure funds and private equity allocate capital through project finance and development-stage equity positions.
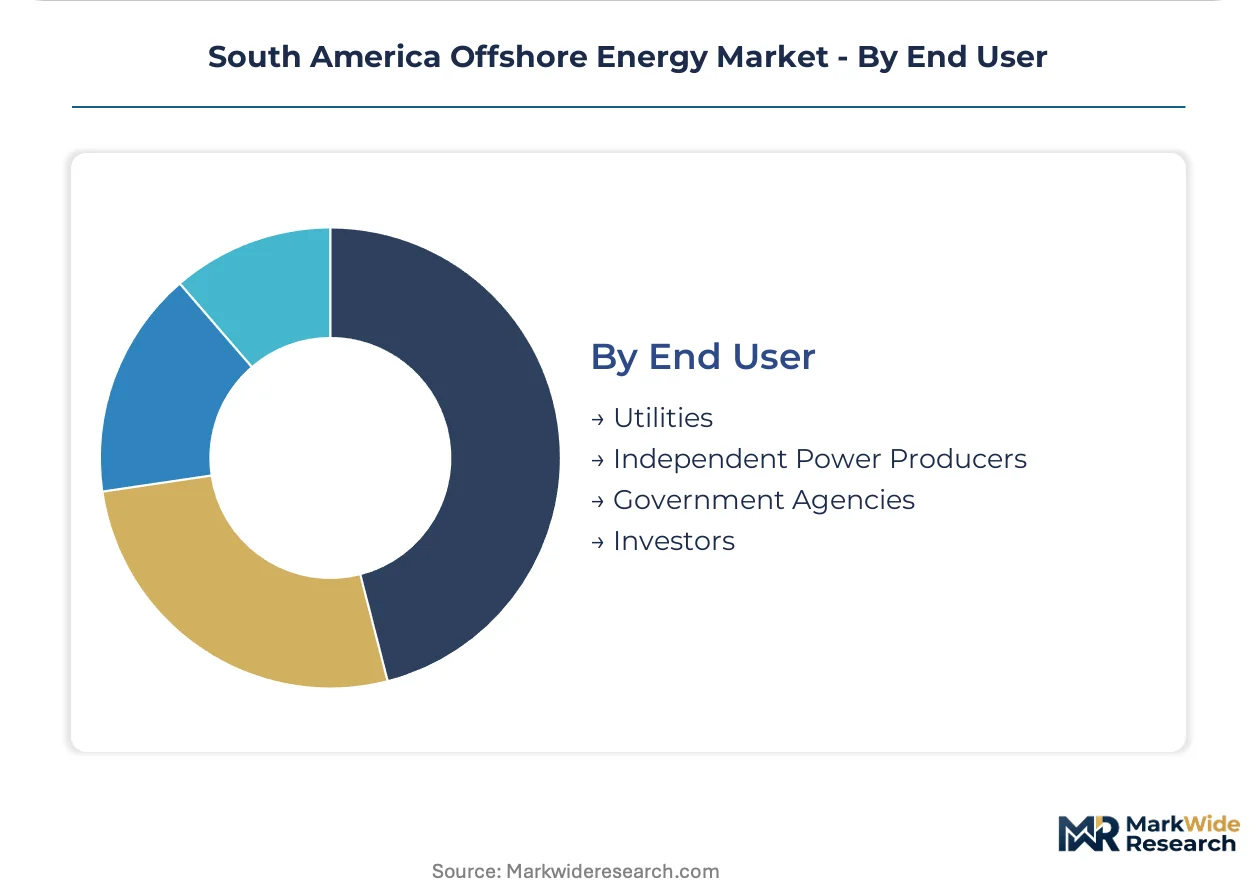
Utilities anchor contracted revenue streams. Independent power producers are gaining share fastest through direct corporate supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANP's regulatory framework anchors capital deployment across Brazilian offshore basins, with southeastern state clusters absorbing the majority of floating platform and subsea equipment orders. Argentine and Uruguayan maritime zones are attracting frontier exploration bids as lease auction frameworks mature.
Brazil
Santos Basin pre-salt carbonate reservoirs sustain rig demand and FPSO fabrication orders through predictable brownfield expansion cycles. ANP local content mandates compress supplier margins while accelerating domestic yard capacity for hull construction. Rio de Janeiro's shipbuilding corridor concentrates floating production unit integration, with Petrobras-operated consortia driving subsea tree procurement.
Argentina
Austral Basin underexplored sedimentary sequences offer first-mover positioning for seismic contractors and drilling operators. The country's national petroleum regulator advances offshore licensing rounds through simplified concession protocols. Tierra del Fuego industrial clusters host emerging supply base development for southern maritime operations.
Uruguay
Offshore wind-to-hydrogen pilot zones attract electrolyzer engineering contracts and maritime lease applications. The national energy directorate structures renewable maritime block auctions with bilateral offtake provisions. Montevideo's port complex anchors floating turbine assembly and mooring system staging.
Colombia
Caribbean coastal sedimentary basins sustain natural gas-focused offshore exploration through dedicated licensing rounds. ANH hydrocarbon regulator streamlines environmental permitting for shallow-water development programs. Barranquilla's maritime industrial zone concentrates subsea equipment maintenance and platform modification services.
Guyana
ExxonMobil-operated Stabroek Block developments anchor deepwater production growth and FPSO deployment sequences. The country's petroleum regulator structures production sharing agreements with accelerated cost recovery provisions. Georgetown's supply base infrastructure expands through dedicated oil services corridor investment.
South America Offshore Energy Market Competitive Landscape
Capability concentration sits with national oil companies holding integrated drilling and production competencies; scale advantage sits with international majors deploying capital across multiple basin positions. The market structure tiers between state-controlled operators with concession dominance and private developers competing through specialized floating unit deployments. Strategic archetypes include pre-salt consortium anchors, floating wind specialists, and integrated subsea equipment suppliers. Competitive moves center on joint venture formation with local yards and technology licensing to satisfy domestic content requirements.
Among Brazilian state-controlled operators, Petrobras exemplifies the integrated capability archetype through its Santos Basin pre-salt dominance. International majors including Shell and TotalEnergies occupy scale-driven positions across multiple regional consortia. Chevron Corporation represents the frontier basin specialist tier through its Guyana-Suriname position.
| Leading Market Players |
|---|
| Petrobras |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Repsol SA |
| Enel Green Power S.p.A. |
| Ecopetrol |
| Shell |
| TotalEnergies |
| CNOOC |
| Others |
Value Network & Pricing Analysis
Steel plate tariff exposure determines both pricing tier spreads and supply chain shape across South America offshore energy markets. ANP local content mandates force international contractors toward Brazilian fabrication partnerships, compressing margins while redistributing procurement flows.
Pricing Analysis
Brazilian hull fabrication commands premium pricing against Asian yard alternatives due to freight differentials and local content compliance value. Three-tier pricing structure separates ANP-certified domestic construction from regional Latin American sourcing and Asian import options. Cost compression in standard-tier SURF equipment is intensifying because of supplier consolidation in Rio de Janeiro's shipbuilding corridor. Independent power producers exhibit highest price sensitivity through competitive auction bidding, while Petrobras-operated consortia absorb premium tiers via long-term offtake security.
Supply Chain Analysis
Export control regimes on subsea processing technology limit component flows from US and EU suppliers to Brazilian integration yards. Geographic supply concentration centers on South Korea, Singapore, and Brazil for floating platform hulls, with subsea trees drawing from UK, Norway, and licensed Brazilian fabricators. Raw material dependencies rest on high-grade steel plate, dynamic cable alloys, and subsea wellhead forgings. Single-source vulnerability concentrates in Brazilian southeastern yards for SURF system integration. Distribution runs through Rio de Janeiro supply bases to offshore installation vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore wind electrification poses substitution pressure that hydrocarbon incumbents must navigate through portfolio diversification. Market participants face compressed timelines for positioning across both brownfield oil expansion and greenfield renewable auctions.
For Market Incumbents: Pre-empt floating wind displacement by securing maritime lease blocks ahead of pure-play renewable developers. Anchor brownfield oil competitiveness through backward integration into Brazilian hull fabrication capacity. Defend against specialist turbine developers by licensing mooring technology to local partners under ANP content frameworks. For New Entrants and Emerging Players: Build out Argentine Austral Basin seismic services before international majors commit exploration capital. Target Uruguay's offshore wind-to-hydrogen pilot zones as the most penetrable geography for electrolyzer engineering contracts. Enter through joint venture structures with Montevideo port authorities for turbine assembly staging. For Investors and Strategic Acquirers: The market sits at a dual-cycle phase that favors integrated operators with renewable-hydrocarbon optionality. Long-term viability hinges on exposure to both Santos Basin pre-salt production and southeastern Brazil floating wind pipelines. Acquisition targets should display ANP certification relationships and subsea technology licensing portfolios. Watch ANP concession round frequency as the signal for capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Production Unit Localization | ANP hull construction mandates force joint ventures with Rio de Janeiro shipyards. |
| Subsea Technology Licensing | International contractors transfer fabrication IP to certified Brazilian partners. |
| Offshore Wind Maritime Leasing | Brazilian auction frameworks open capital channels for turbine developers. |
| Green Hydrogen Export Infrastructure | Uruguay pilot zones attract electrolyzer engineering and pipeline contracts. |
| Decommissioning Liability Preparation | Brazilian well abandonment regulations create rigless P&A service demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, project development databases, and trade flow records. Interviews with EPC contractors, ANP regulatory officers, utility planning directors, and subsea equipment procurement managers informed demand-side validation. Secondary sources include ANP concession round documentation, IBAMA environmental licensing records, BNDES financing disclosures, and customs import data for floating platform components. Bottom-up project pipeline aggregation was cross-checked against top-down macroeconomic energy demand modeling.
Forecast inputs incorporate water depth classification, project scale tiers, technology type splits, and regulatory framework variations across the projection horizon. Segmentation dimensions modeled include service type, technology category, application vector, and end-user archetype. CAGRs were derived from installation cost trajectory analysis and capacity factor assumptions for renewable versus hydrocarbon assets. Industry-specific inputs capture ANP local content quota evolution and floating wind auction schedule density.
Stress conditions across steel price volatility, environmental licensing delays, and offshore wind offtake contract penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ANP regulatory continuity and pre-salt field decline rates. Material shifts in Brazil's local content enforcement intensity or floating wind bankability standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market