
 Europe Oil and Gas Separation Market | 2026-2036
Europe Oil and Gas Separation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oil and Gas Separation Market Intelligence
Multi-source procurement for separator packages is rebalancing toward integrated system providers with in-house fabrication capabilities. Alfa Laval AB leverages its centrifugal separation heritage to anchor premium positions in offshore contract awards. Schlumberger Limited sustains technology leadership through digital monitoring integrations across subsea processing trains. TechnipFMC plc competes on project execution scale, bundling separation modules with subsea infrastructure for North Sea brownfield redevelopment.
Europe oil and gas separation encompasses mechanical and physicochemical processes that isolate hydrocarbon phases, produced water, and contaminants at pressures typically ranging from 10 to 150 bar and temperatures between 20°C and 200°C, serving the fundamental purpose of conditioning crude oil and natural gas for pipeline transport, refining, or export. Gravity separation equipment dominates installed base volumes across onshore facilities, though membrane separation is gaining share in gas processing applications where CO2 and H2S removal must meet stringent pipeline specifications. Cyclonic separation occupies a specialized niche in offshore platforms where footprint constraints and motion sensitivity limit conventional vessel deployment.
EU Green Deal targets, REACH chemical compliance, and the F-Gas Regulation collectively constrain material selection and emissions profiles for separation equipment deployed across European member states, particularly affecting refrigerant-based dew point control units and glycol dehydration systems. The European Maritime Safety Agency and national regulators in Norway and the United Kingdom enforce offshore equipment certification standards that extend design validation timelines but create barriers against non-European suppliers. Stakeholders must monitor how carbon border adjustment mechanisms and evolving methane intensity benchmarks reshape total-cost-of-ownership calculations for replacement versus upgrade decisions across aging North Sea assets.
Market Dynamics
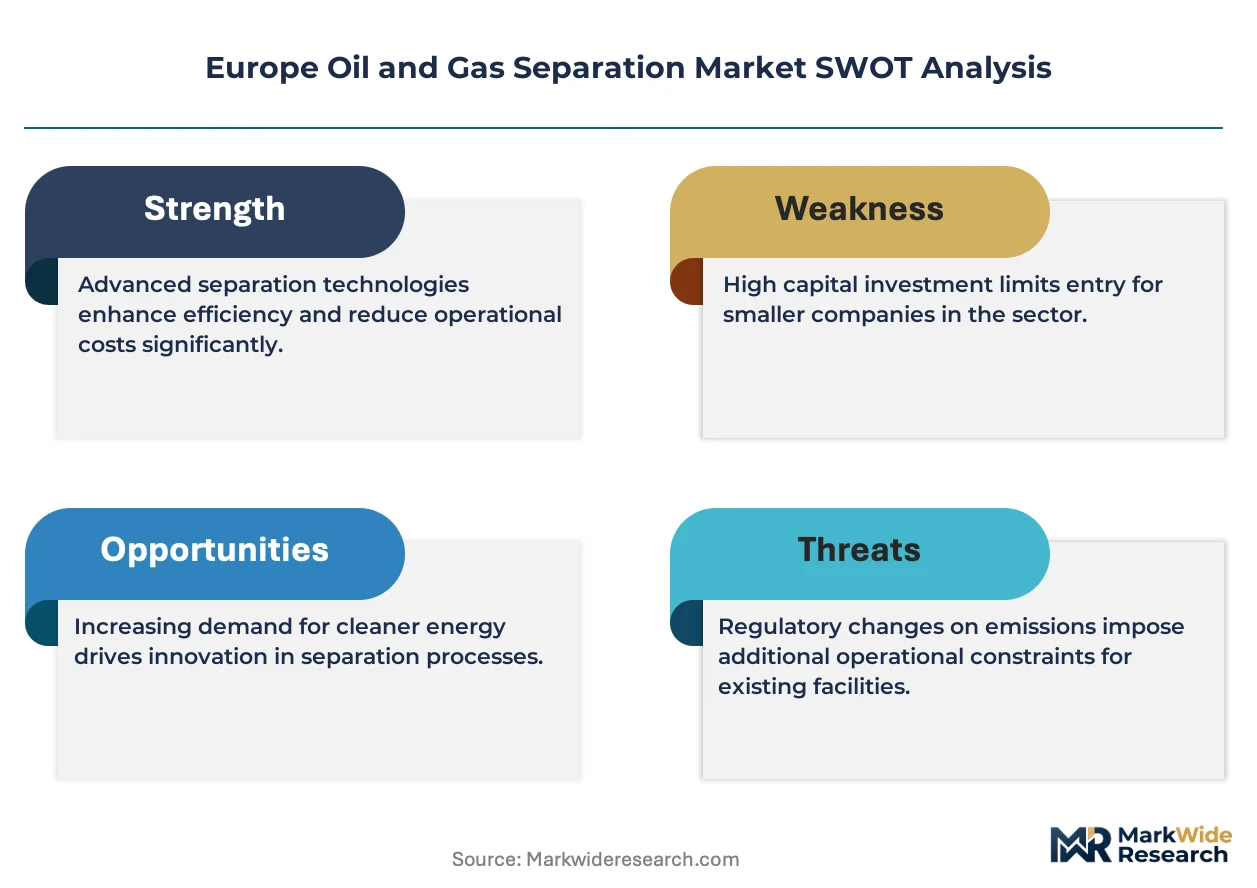
North Sea brownfield redevelopment cycles and EU F-Gas Regulation compliance deadlines are compressing equipment replacement timelines while elevating membrane and electrostatic separation technologies over conventional gravity vessels across European offshore and onshore facilities.
Growth Catalysts
- EU Green Deal methane intensity benchmarks:Operators in Norway and the United Kingdom face escalating penalties for fugitive emissions, accelerating separator upgrades with integrated gas recovery systems.
- Produced water reinjection mandates:Dutch and Danish regulators now require sub-15 ppm oil-in-water discharge standards, driving demand for compact flotation and membrane polishing units on aging platforms.
- Electrostatic coalescence:This technology handles high water-cut crudes from mature North Sea fields where traditional gravity separation fails, penetrating offshore retrofit contracts at accelerating rates.
Market Restraints
- Specialized alloy supply concentration:Super-duplex stainless steel for sour service vessels depends on a limited Nordic and German supplier base, exposing fabricators to 18-month lead time volatility.
- REACH chemical compliance costs:ECHA restrictions on hexavalent chromium coatings and certain elastomer compounds force material requalification, extending engineering validation cycles by 8-14 months.
- Subsea separation substitution:Seabed processing modules with integrated separation functions reduce topside vessel counts, cannibalizing traditional platform-based equipment demand in deepwater Norway developments.
Strategic Opportunities
- Netherlands onshore gas treatment:Groningen field decommissioning and adjacent small-field tiebacks create demand for modular, transportable separation skids with rapid deployment capabilities.
- Digital twin integration:Convergence of physics-based separation modeling with real-time sensor networks enables predictive maintenance contracts, shifting revenue from hardware sales to performance-guaranteed service agreements.
- Carbon border adjustment mechanisms:CBAM phase-in from 2026 favors European-fabricated equipment with embedded emissions documentation, disadvantaging imported Asian vessels and strengthening domestic supplier positions.
Industry Challenges
- Subsea processing integration:Topsides engineers lack experience interfacing new electrostatic separators with legacy subsea distribution manifolds, causing commissioning delays on Norwegian brownfield projects.
- Offshore certification timelines:NORSOK and DNV-GL validation for modified separator designs under revised pressure vessel codes consumes 14-22 months, misaligning with operator decommissioning deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oil and Gas Separation Market |
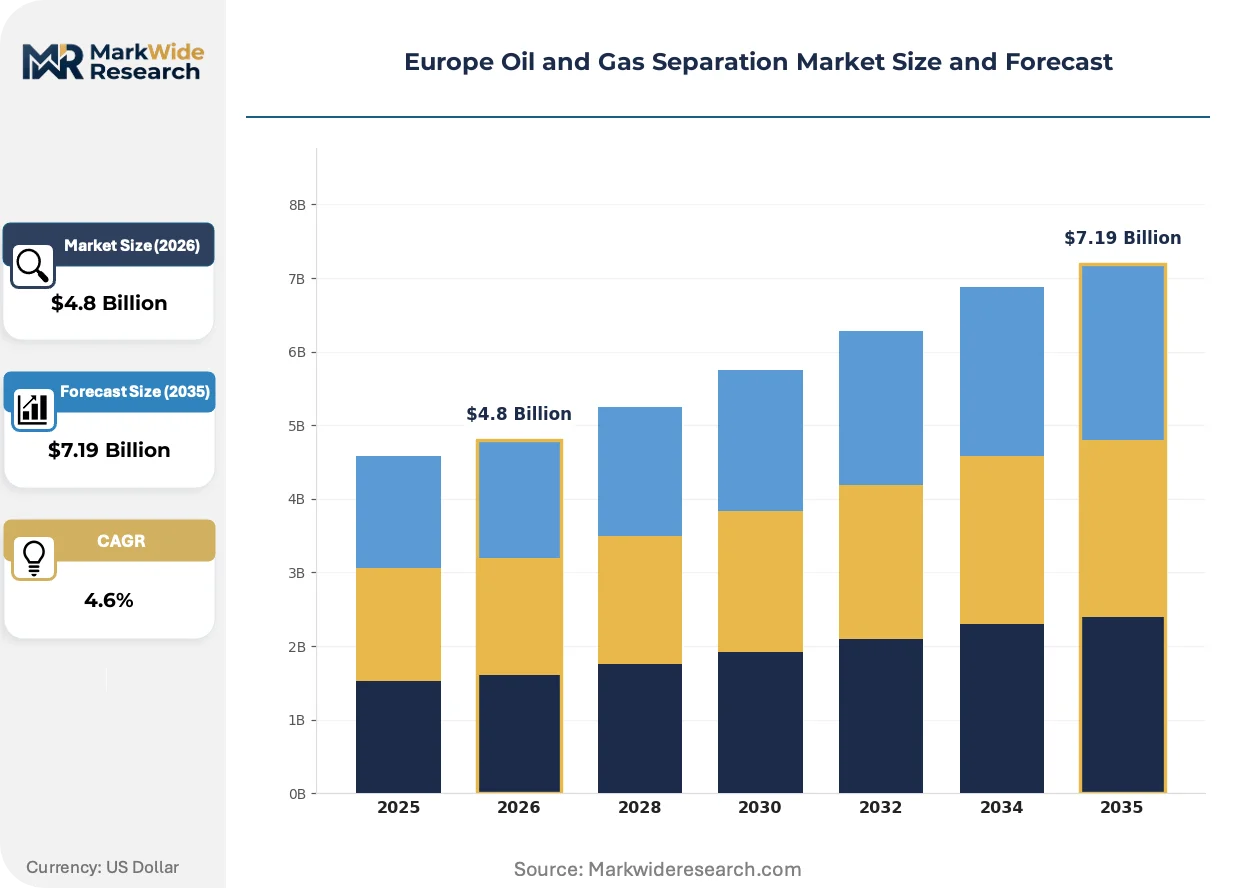
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gravity Separation, Cyclonic Separation, Membrane Separation, Electrostatic Separation Equipment Type: Separators, Filter Systems, Scrubbers, Heat Exchangers Application: Oil Recovery, Gas Processing, Water Treatment, Enhanced Oil Recovery End User: Oil Refineries, Petrochemical Plants, Offshore Platforms, Onshore Facilities |
| Companies Covered | Alfa Laval AB, Schlumberger Limited, TechnipFMC plc, Air Liquide, Honeywell International Inc., Evonik Industries AG, GEA Group Aktiengesellschaft, Frames Energy Systems BV, Linde plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oil and Gas Separation Market Strategic Shifts & Innovations
Electrostatic and membrane separation architectures are displacing conventional gravity vessels across European gas processing chains, while digital instrumentation layers reconfigure how operators monitor phase separation efficiency in real time.
Compact electrostatic coalescers for high water-cut crude treatment are decentralizing separation architecture on North Sea platforms. Equinor and Shell deploy these units in retrofitted module slots where gravity vessel footprint expansion proves impossible. The technology is decentralizing process train layouts, enabling distributed separation stages rather than centralized large-vessel halls.
F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants force glycol dehydration and dew point control unit redesigns across United Kingdom and Norwegian gas terminals. ECHA compliance deadlines compress equipment procurement windows while elevating membrane-based dehydration alternatives. Gas processing operators in St. Fergus and Nyhamna terminals accelerate pilot deployments of ceramic membrane contactors to preempt refrigerant availability constraints.
Service unbundling now separates separator hardware from performance-based aftermarket contracts. North Sea operators in the United Kingdom sector increasingly procure vessel packages without mandatory OEM maintenance agreements, instead awarding condition-monitoring services to specialized digital analytics firms. This pattern concentrates in mature basin developments where capital discipline overrides traditional bundled procurement preferences.
Europe Oil and Gas Separation Market Segmentation
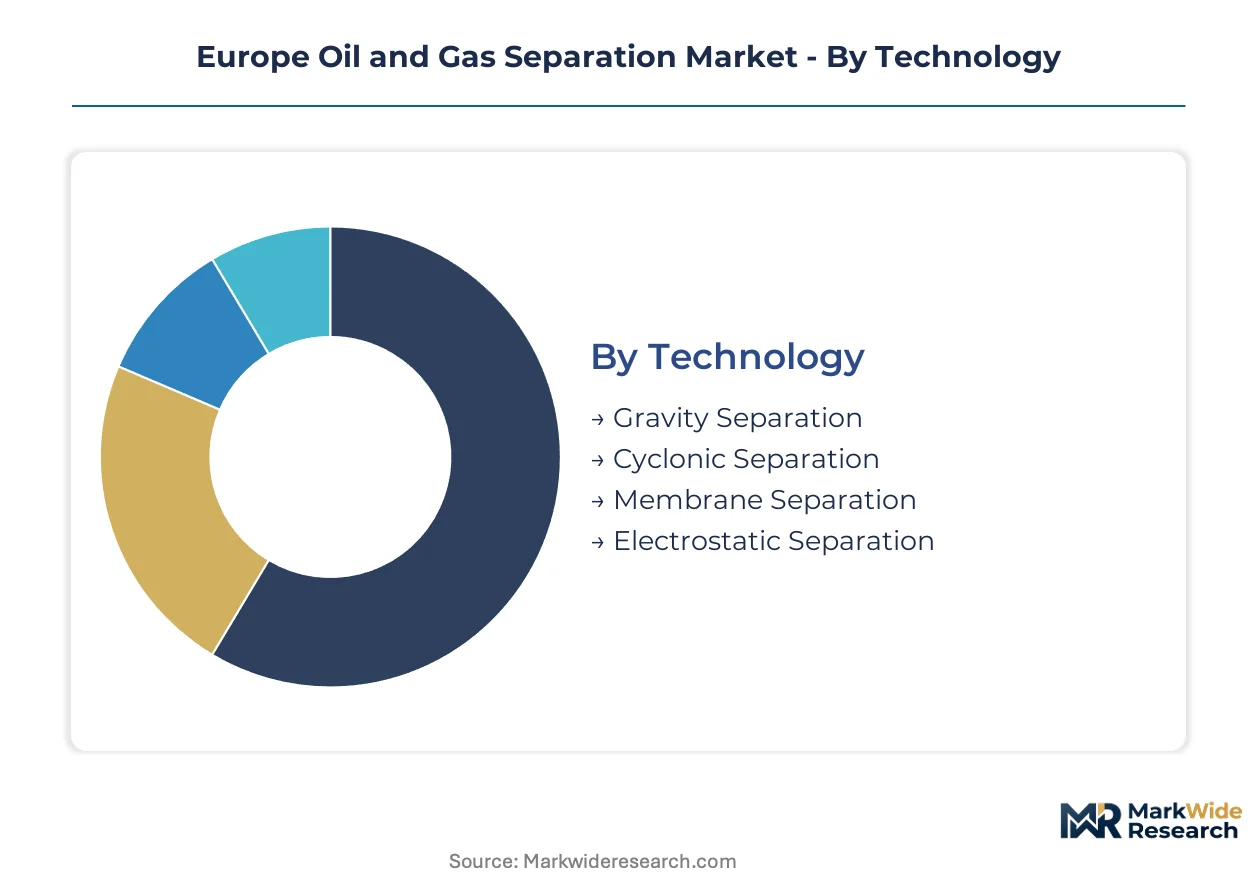
Technology selection in European oil and gas separation hinges on water-cut profiles, platform constraints, and emissions compliance. Equipment procurement patterns diver sharply between brownfield retrofits and greenfield developments across the North Sea basin.
Technology:
Buyers differentiate primarily by footprint limitations and produced water complexity rather than upfront capital cost.
- Gravity Separation:Conventional vessel-based systems using density differentials dominate onshore terminals and legacy offshore platforms. Norwegian and United Kingdom operators maintain substantial installed bases at St. Fergus and Sullom Voe, though replacement cycles lengthen as operators defer capital for subsea processing alternatives.
- Electrostatic Separation:High-voltage coalescing fields break emulsions in high water-cut crudes from mature North Sea fields. Shell and Equinor deploy compact electrostatic units in retrofitted module slots where gravity vessel expansion proves structurally impossible.
- Membrane Separation:Ceramic and polymeric membranes remove CO2 and H2S in gas processing trains. ECHA compliance deadlines and F-Gas Regulation phase-downs accelerate pilot deployments at Nyhamna and other Norwegian terminals.
- Cyclonic Separation:Centrifugal force separation occupies motion-sensitive offshore niches. Compact hydrocyclones handle bulk water removal on floating production vessels where vessel sloshing compromises gravity-based performance.
Volume sits with gravity systems; growth tilts toward electrostatic architectures.
Equipment Type:
Procurement concentration tracks brownfield replacement cycles and regulatory-driven upgrade mandates.
- Separators:Two-phase and three-phase pressure vessels constitute the core installed base. Dutch and Danish regulators now require sub-15 ppm oil-in-water discharge standards, accelerating separator refurbishment at North Sea platforms approaching decommissioning deadlines.
- Filter Systems:Coalescing and cartridge filters provide polishing-stage protection downstream of primary separation. United Kingdom sector operators increasingly unbundle filter maintenance from OEM agreements, awarding condition-monitoring contracts to specialized analytics firms.
- Scrubbers:Gas-liquid and dry scrubbers remove entrained droplets and solid contaminants. F-Gas Regulation constraints force glycol dehydration system redesigns across United Kingdom and Norwegian gas terminals.
- Heat Exchangers:Shell-and-tube and plate configurations control separation temperatures. Super-duplex stainless steel supply concentration from Nordic and German fabricators extends lead times for sour service applications.
Separators capture the largest equipment spend; filter systems are climbing fastest on digital unbundling trends.
Application:
End-use prioritization reflects basin maturity and regulatory discharge requirements.
- Oil Recovery:Primary separation of crude from formation fluids and gas. Mature North Sea fields with escalating water cuts drive demand for compact electrostatic retrofits at United Kingdom and Norwegian platforms.
- Water Treatment:Produced water polishing and reinjection conditioning. Netherlands and Denmark enforce the strictest oil-in-water discharge limits, concentrating membrane and flotation unit deployments.
- Gas Processing:Acid gas removal and dehydration for pipeline specification. F-Gas Regulation refrigerant phase-downs push St. Fergus and Nyhamna terminals toward membrane contactor alternatives.
- Enhanced Oil Recovery:CO2 separation and reinjection gas conditioning. Norwegian deepwater developments integrate subsea processing modules that cannibalize traditional topside separation demand.
Oil recovery dominates current application spend; water treatment is expanding most quickly on tightening North Sea discharge rules.
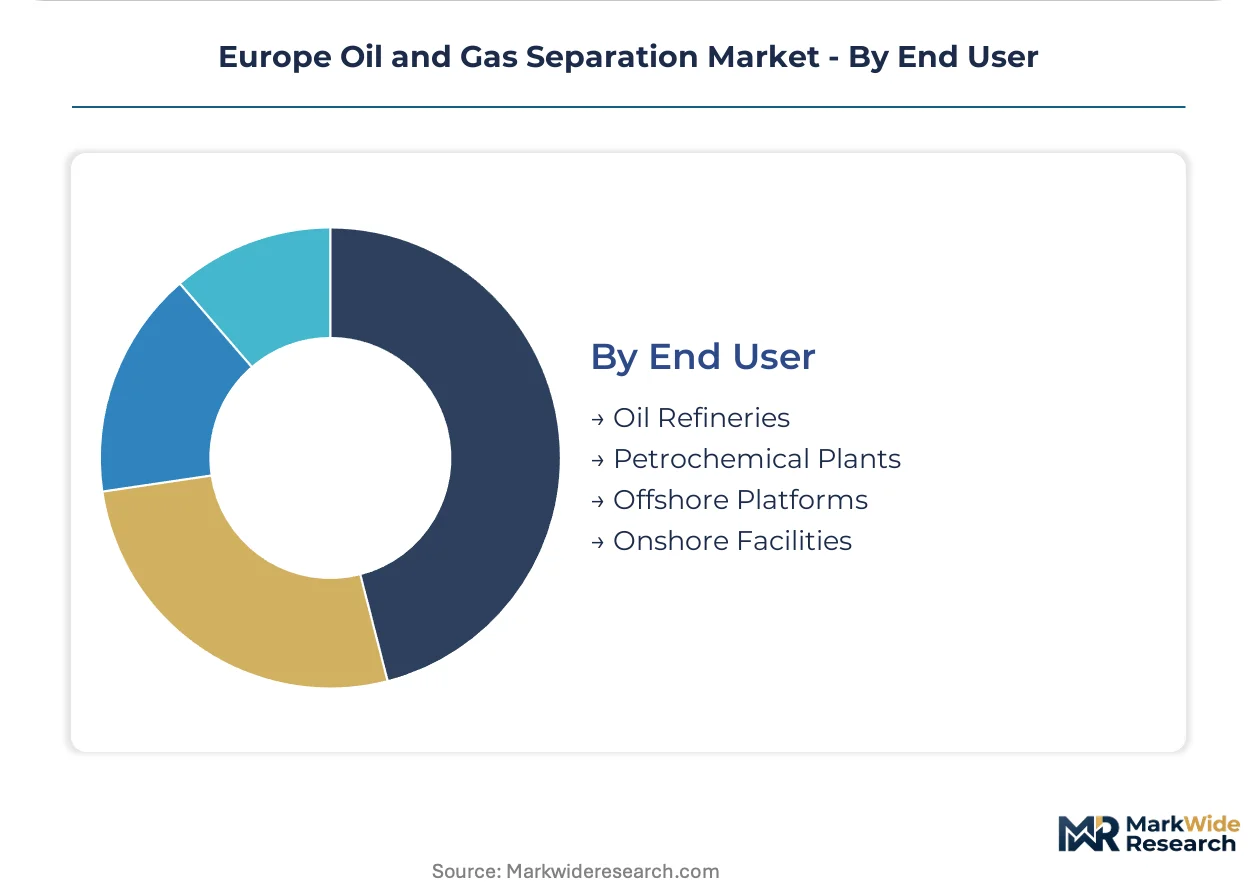
End User:
Facility type determines certification requirements, maintenance access, and technology substitution risk.
- Offshore Platforms:Fixed and floating installations in the North Sea. NORSOK and DNV-GL validation timelines of 14-22 months misalign with operator decommissioning deadlines, compressing retrofit procurement windows.
- Oil Refineries:Downstream crude conditioning and intermediate processing. REACH chemical compliance on hexavalent chromium coatings and elastomer compounds forces material requalification extending engineering cycles.
- Onshore Facilities:Gas terminals and processing plants in Norway, the United Kingdom, and the Netherlands. Groningen field decommissioning and adjacent small-field tiebacks create demand for modular, transportable separation skids.
- Petrochemical Plants:Feedstock preparation and intermediate separation stages. Carbon border adjustment mechanisms from 2026 favor European-fabricated equipment with embedded emissions documentation.
Offshore platforms anchor equipment volumes; onshore facilities are gaining share fastest on modular deployment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in North Sea jurisdictions where brownfield redevelopment timelines and decommissioning deadlines compress replacement cycles. Norway, the United Kingdom, and the Netherlands together account for the dominant share of separator deployments across European offshore and onshore facilities.
Norway
Deepwater subsea processing developments at Johan Sverdrup and Snøhvit drive demand for compact separation modules with integrated gas recovery systems. The Norwegian Petroleum Directorate enforces methane intensity benchmarks that accelerate electrostatic separator retrofits on mature platforms. Stavanger anchors the supplier ecosystem, with fabrication yards at Ågotnes and Verdal producing super-duplex vessels for sour service applications.
United Kingdom
North Sea assets at Buzzard and Forties require high water-cut handling equipment as fields mature beyond original design parameters. The North Sea Transition Authority mandates net-zero operational emissions by 2050, forcing operators toward membrane-based dehydration alternatives at St. Fergus and Sullom Voe terminals. Aberdeen maintains its position as the primary procurement hub, though engineering validation cycles now stretch 14-22 months under revised NORSOK codes.
Netherlands
Groningen field decommissioning and adjacent small-field tiebacks create demand for modular, transportable separation skids with rapid deployment capabilities. The State Supervision of Mines enforces sub-15 ppm oil-in-water discharge standards that drive membrane and flotation unit deployments. Rotterdam and Den Helder concentrate fabrication and maintenance capabilities for North Sea operators seeking brownfield upgrade packages.
Denmark
Tyra field redevelopment and surrounding marginal field tiebacks sustain separator replacement demand through 2030. The Danish Energy Agency aligns with EU Green Deal methane benchmarks, accelerating gas recovery system integrations on aging platforms. Esbjerg serves as the logistics and equipment staging point for Danish North Sea operations, with suppliers positioning modular units for rapid platform installation.
Germany
Industrial gas processing at Wilhelmshaven and chemical cluster demand for feedstock conditioning sustain niche separation equipment procurement. ECHA REACH compliance deadlines on hexavalent chromium coatings and elastomer compounds force material requalification for vessels serving petrochemical applications. The Ruhr industrial corridor and Bavarian chemical parks represent concentrated end-use demand for high-pressure separation systems.
Europe Oil and Gas Separation Market Key Industry Players
Technology licensing and integrated system bundling dominate the current landscape as fabricators seek to differentiate beyond commodity vessel supply. The vendor base concentrates around three tiers: multinational energy service conglomerates with subsea processing portfolios, European industrial equipment specialists with centrifugal separation heritage, and regional fabricators focused on modular skid packages. Strategic archetypes include full-stream integrators bundling separation with compression and pumping, technology licensors monetizing electrostatic and membrane patents, and fabrication-heavy contractors executing brownfield retrofit execution. M&A activity targets digital monitoring capabilities, while strategic partnerships with subsea distribution specialists address topsides-subsea integration gaps.
Among Swedish and Anglo-Dutch industrial groups, Alfa Laval AB and TechnipFMC plc occupy positions anchoring distinct competitive vectors. Alfa Laval represents the centrifugal separation heritage archetype, leveraging in-house fabrication capabilities to secure premium offshore contract positions. TechnipFMC exemplifies the full-stream integrator model, bundling separation modules with subsea infrastructure for North Sea brownfield redevelopment. Schlumberger Limited sits within the technology-licensor tier, sustaining positioning through digital monitoring integrations across processing trains. These three entities collectively illustrate how European separation procurement favors suppliers with demonstrable project execution scale and regulatory compliance documentation.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Schlumberger Limited |
| TechnipFMC plc |
| Air Liquide |
| Honeywell International Inc. |
| Evonik Industries AG |
| GEA Group Aktiengesellschaft |
| Frames Energy Systems BV |
| Linde plc |
| Others |
Cost & Logistics Intelligence
Super-duplex stainless steel feedstock costs cascade through fabrication tiers to separate premium NORSOK-certified vessels from standard offshore packages, with Nordic and German mill concentration amplifying price volatility for sour-service applications across North Sea brownfield awards.
Pricing Analysis
Volume concentrates in commoditized gravity vessels where margin compression runs deepest, while premium electrostatic and membrane systems command pricing power through integrated digital monitoring and extended validation documentation. Price differentiation hinges on DNV-GL certification tier and after-sales service bundling, with unbundled filter maintenance contracts eroding OEM pricing power in the United Kingdom sector. Cost compression in standard vessel fabrication intensifies as Asian competitors face carbon border adjustment disadvantages from 2026. National oil companies with decommissioning deadlines prove least price-sensitive; independent operators on marginal Dutch and Danish fields exhibit highest procurement cost discipline.
Supply Chain Analysis
Single-source vulnerability sits with Nordic and German super-duplex stainless suppliers for sour-service pressure vessels, exposing fabricators to alloy availability disruptions. Manufacturing gravity centers on Norway, the United Kingdom, and the Netherlands, with Ågotnes, Verdal, and Aberdeen anchoring fabrication clusters. Raw material dependencies span nickel-chromium-molybdenum alloys, high-voltage transformer components for electrostatic units, and ceramic membrane substrates. Tariff exposure on Chinese-sourced electrical components represents the dominant structural risk. Distribution runs through EPC contractors and direct operator procurement for brownfield retrofit packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH chemical restrictions and F-Gas Regulation phase-downs erect barrier-to-entry moats favoring incumbent fabricators with established ECHA documentation and NORSOK validation track records.
For Market Incumbents: Anticipate subsea processing substitution threats by deepening captive fabrication capabilities at Ågotnes and Verdal, while accelerating digital twin integration to shift revenue toward performance-guaranteed service agreements that lock out modular skid competitors on Norwegian brownfield awards.
For New Entrants and Emerging Players: Enter via Netherlands onshore gas treatment modularization, where Groningen field decommissioning and small-field tiebacks create white-space demand for rapid-deployment skids without legacy NORSOK validation burdens, leveraging transportable unit design as the primary go-to-market wedge against fixed-fabrication incumbents.
For Investors and Strategic Acquirers: ECHA compliance deadline acceleration is the leading indicator that material requalification capabilities will concentrate acquisition value in fabricators with pre-validated elastomer and coating portfolios, positioning electrostatic technology licensors with digital monitoring assets as the priority target archetype over commodity vessel suppliers across the mid-decade window.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Super-Duplex Supply | Nordic mill partnerships secure alloy access against 18-month lead time volatility for sour-service vessels. |
| Digital Twin Platform Development | Physics-based separation modeling with real-time sensor networks enables predictive maintenance contract transitions. |
| Membrane Dehydration Pilot Scale-Up | Ceramic contactor deployments at Nyhamna and St. Fergus preempt F-Gas Regulation refrigerant availability constraints. |
| Modular Skid Standardization | Transportable unit designs capture Netherlands onshore gas treatment demand from Groningen decommissioning timelines. |
| ECHA Compliance Documentation Investment | Pre-validated material portfolios accelerate engineering cycles against REACH hexavalent chromium and elastomer restrictions. |
Research Approach
Multi-period observation of brownfield award volumes, regulatory compliance deadline shifts, and technology substitution rates anchored the trend analysis, supplemented by interviews with offshore platform engineering directors, EPC contractor procurement leads, fabrication yard operations managers, and Norwegian Petroleum Directorate regulatory affairs specialists. Secondary validation drew from NORSOK standard revision filings, ECHA restriction proposal databases, EU Green Deal methane intensity benchmark publications, and North Sea decommissioning timeline disclosures. Bottom-up equipment deployment tallies triangulated against top-down operator capital expenditure patterns.
Segment-weighting approaches applied differential growth assumptions across technology types, with electrostatic and membrane architectures receiving higher trajectory coefficients than gravity vessel replacement cycles. Modeled dimensions spanned separation technology, equipment type, application end-use, and facility category across the projection horizon. CAGRs derived from equipment unit economics and operator spending pattern elasticity estimates, incorporating subsea processing substitution risk and carbon border adjustment mechanism phase-in effects as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU methane intensity penalty implementation or super-duplex supply disruption scenarios. Forecasts reflect documented assumptions on regulatory enforcement timelines and technology pilot success rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Offshore Decommissioning Services Market