
 Marine Mining Market | 2026-2036
Marine Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Mining Market Intelligence
Modular extraction system design is recalibrating buyer choice across the marine mining value chain, shifting procurement from standalone equipment toward integrated seabed-to-surface packages. BHP Group leverages its deepwater engineering heritage to anchor technology partnerships in the Clarion-Clipperton Zone. China Molybdenum sustains aggressive licensing positioning through bilateral agreements with Pacific island states. Rio Tinto competes via specialized polymetallic sulfide assessment capabilities in Papua New Guinea waters.
Marine mining encompasses the mechanical extraction of mineral deposits from ocean floors, typically at depths exceeding 4,000 meters where manganese nodules, cobalt crusts, and polymetallic sulfides concentrate through geochemical precipitation over millions of years; hydraulic dredging and remote operated vehicles constitute the dominant operational modalities for seafloor disturbance and material recovery. Polymetallic sulfides command premium development attention due to their high copper-gold-zinc concentrations and proximity to active hydrothermal vents, while manganese nodules occupy the largest volume pipeline given their distribution across abyssal plains and established processing metallurgy. Rare earth elements from cobalt-rich crusts represent the fastest-growing extraction target, driven by magnet supply requirements in offshore wind turbine manufacturing.
The International Seabed Authority's developing exploitation code shapes operational licensing timelines and environmental baseline requirements for contractors in international waters, while national regulators such as Papua New Guinea's Mineral Resources Authority and the Cook Islands Seabed Minerals Authority govern territorial seabed concessions through domestic permitting frameworks. Stakeholders must monitor the divergence between ISA multilateral standards and unilateral national legislation, as this regulatory fragmentation will determine where capital deployment achieves earliest operational clearance.
Market Dynamics
Modular seabed-to-surface extraction packages are displacing standalone equipment procurement, forcing contractors to restructure capital deployment around integrated system architectures rather than discrete component sourcing.
Growth Catalysts
- Renewable energy mineral demand:Offshore wind turbine manufacturers require cobalt-rich crusts for permanent magnet production, creating guaranteed offtake channels for seabed mineral contractors.
- International Seabed Authority exploitation code:Draft regulations are clarifying licensing pathways for contractors in international waters, reducing regulatory uncertainty that previously stalled project financing.
- Bilateral seabed agreements:Pacific island states are negotiating direct concession frameworks with mining contractors, bypassing multilateral bottlenecks and accelerating territorial claim development.
Market Restraints
- Deepwater engineering cost structure:Remote operated vehicles and hydraulic dredging systems require specialized subsea pressure-rated components that concentrate supply among a limited set of marine engineering fabricators.
- Polymetallic sulfide deposit concentration:High-grade copper-gold-zinc formations cluster near active hydrothermal vents in Papua New Guinea waters, creating geographic dependency for premium extraction targets.
- Environmental baseline data scarcity:Contractors face extended survey timelines to establish pre-disturbance ecological conditions as required by the International Seabed Authority's developing standards.
Strategic Opportunities
- Cook Islands territorial licensing:The national Seabed Minerals Authority has established domestic permitting frameworks that offer faster operational clearance than international waters under ISA jurisdiction.
- Rare earth element magnet supply chains:Cobalt-rich crust extraction for offshore wind manufacturing represents an emerging application with dedicated offtake potential from turbine OEMs.
- Autonomous underwater vehicle convergence:Integration of AI-driven navigation with seafloor mapping systems is reducing survey costs and expanding exploitable deposit identification.
Industry Challenges
- Deep-sea robotics skill scarcity:Maintenance and operation of hydraulic dredging systems at abyssal depths requires specialized marine engineering expertise that outpaces current training pipeline output.
- Seabed-to-surface integration complexity: Contractors must synchronize subsea extraction, riser transport, and surface vessel processing without established interoperability standards across equipment vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Mining Market |
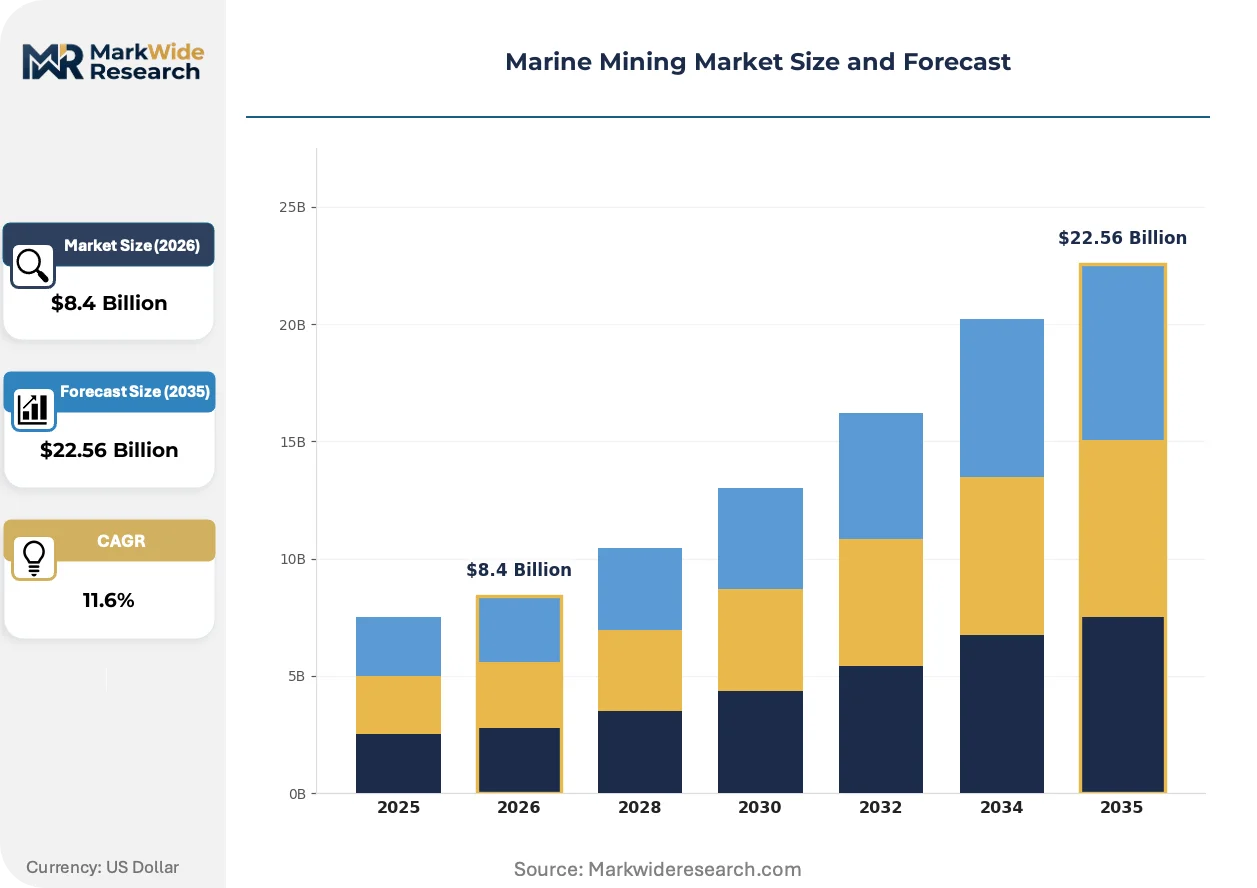
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.56 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manganese Nodules, Polymetallic Sulfides, Cobalt-rich Crusts, Rare Earth Elements Extraction Technology: Hydraulic Dredging, Continuous Line Bucket, Remote Operated Vehicles, Submersible Mining Machines End Use Industry: Electronics Manufacturing, Renewable Energy, Aerospace, Chemical Production Deployment Environment: Deep Seabed, Continental Slopes, Abyssal Plains, Seamounts |
| Companies Covered | Freeport-McMoRan, China Molybdenum, Glencore, ArcelorMittal Mining, MMC Norilsk Nickel, BHP Group, Newmont Corporation, Sibanye-Stillwater, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Mining Market Strategic Shifts & Innovations
Operational modalities across the marine mining value chain are converging around autonomous systems and integrated environmental monitoring, compressing the gap between exploration and commercial extraction timelines.
Autonomous underwater vehicles equipped with real-time geochemical sensors are absorbing the reconnaissance function previously performed by crewed submersibles and surface-tethered ROVs. Exploration contractors in the Clarion-Clipperton Zone are deploying these systems for continuous nodule density mapping at depths exceeding four thousand meters. The structural consequence is a collapse in survey cost per square kilometer, enabling smaller contractors to compete for concession blocks against capital-intensive incumbents.
The International Seabed Authority's developing exploitation regulations are mandating environmental baseline protocols that exceed prior voluntary industry guidelines. Contractors must now demonstrate pre-disturbance ecological conditions across benthic communities before disturbance permits issue. Segments targeting polymetallic sulfides near active hydrothermal vents face the steepest compliance burden given the biological sensitivity of these ecosystems.
Offshore wind turbine manufacturers are consolidating magnet mineral procurement around vertically integrated seabed-to-refinery supply commitments. Buyers are displacing spot-market rare earth purchasing with long-term offtake agreements tied to specific crust extraction projects. This pattern is most visible in European renewable energy supply chains, where OEMs face tightened due diligence requirements under the EU Green Deal's critical raw materials sourcing standards.
Marine Mining Market Segmentation
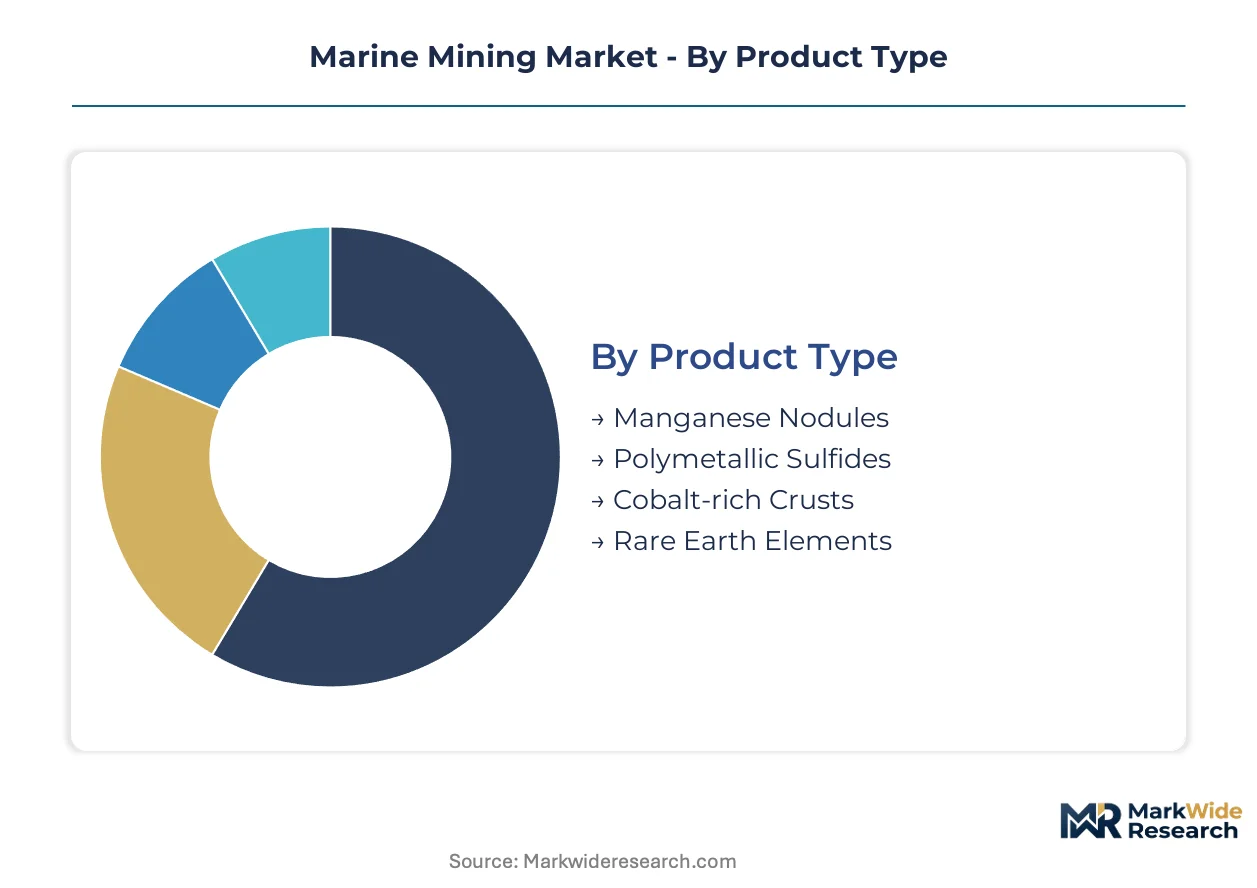
Segmentation in marine mining reveals how deposit chemistry, extraction depth, and end-use specifications concentrate capital deployment. Buyers select extraction configurations based on mineral grade thresholds and proximity to processing infrastructure rather than standalone equipment performance.
Product Type:
Deposit chemistry determines processing metallurgy requirements and offtake contract terms.
- Manganese Nodules:Spherical concretions containing nickel, copper, and cobalt distributed across abyssal plains at 4,000-6,000 meter depths. Battery-grade nickel demand from electric vehicle cathode manufacturers concentrates development interest in the Clarion-Clipperton Zone.
- Polymetallic Sulfides:Massive sulfide deposits with elevated copper-gold-zinc concentrations forming near active hydrothermal vents. Papua New Guinea's territorial waters host the most advanced development projects due to shallower extraction depths and established port infrastructure.
- Cobalt-rich Crusts:Ferromanganese layers precipitated on seamount slopes containing rare earth elements and tellurium.
- Rare Earth Elements:Concentrated outputs from crust processing and nodule leaching circuits.
Volume sits with manganese nodules; growth tilts toward polymetallic sulfides.
Extraction Technology:
Operational modality selection hinges on seafloor stability and water depth pressure ratings.
- Hydraulic Dredging:High-volume slurry pumping systems deploying suction heads across soft sediment substrates. Contractors in the Cook Islands' exclusive economic zone favor this approach for nodule collection given predictable seabed conditions.
- Remote Operated Vehicles:Tethered robotic systems performing precision cutting and collection at hydrothermal vent sites. China Molybdenum deploys ROV-dependent architectures for polymetallic sulfide extraction where deposit geometry demands selective mining.
- Continuous Line Bucket:Mechanical scooping chains traversing the seafloor in linear patterns.
- Submersible Mining Machines:Autonomous tracked vehicles operating without surface tethering.
Capital deployment favors hydraulic dredging; technology evolution centers on submersible mining machines.
End Use Industry:
Downstream specification requirements dictate mineral purity thresholds and processing investment.
- Electronics Manufacturing:High-purity copper and rare earth elements for semiconductor and circuit board production. Taiwanese and South Korean electronics conglomerates are negotiating direct offtake agreements with seabed contractors to secure non-Chinese supply chains.
- Renewable Energy:Permanent magnet minerals for offshore wind turbine generators. European turbine OEMs under EU Green Deal due diligence mandates are sourcing cobalt and rare earth elements through vertically integrated seabed-to-refinery contracts.
- Aerospace:Titanium and rare earth alloys for jet engine and airframe applications.
- Chemical Production:Manganese and cobalt feedstocks for catalyst and pigment manufacturing.
Electronics manufacturing commands current volume; renewable energy claims the steepest expansion trajectory.
Deployment Environment:
Water depth and substrate stability determine equipment pressure ratings and operational windows.
- Deep Seabed:Environments below 4,000 meters where manganese nodules concentrate on sediment surfaces. The International Seabed Authority's developing exploitation code governs contractor access to these international waters.
- Abyssal Plains:Flat sediment-covered regions spanning millions of square kilometers with consistent nodule distribution. Exploration contractors favor these environments for predictable resource estimation and lower geohazard risk.
- Continental Slopes:Transition zones between continental shelves and deep ocean floors where cobalt-rich crusts form on rock outcrops.
- Seamounts:Underwater volcanic peaks rising from abyssal plains with steep gradients and hard substrate surfaces.
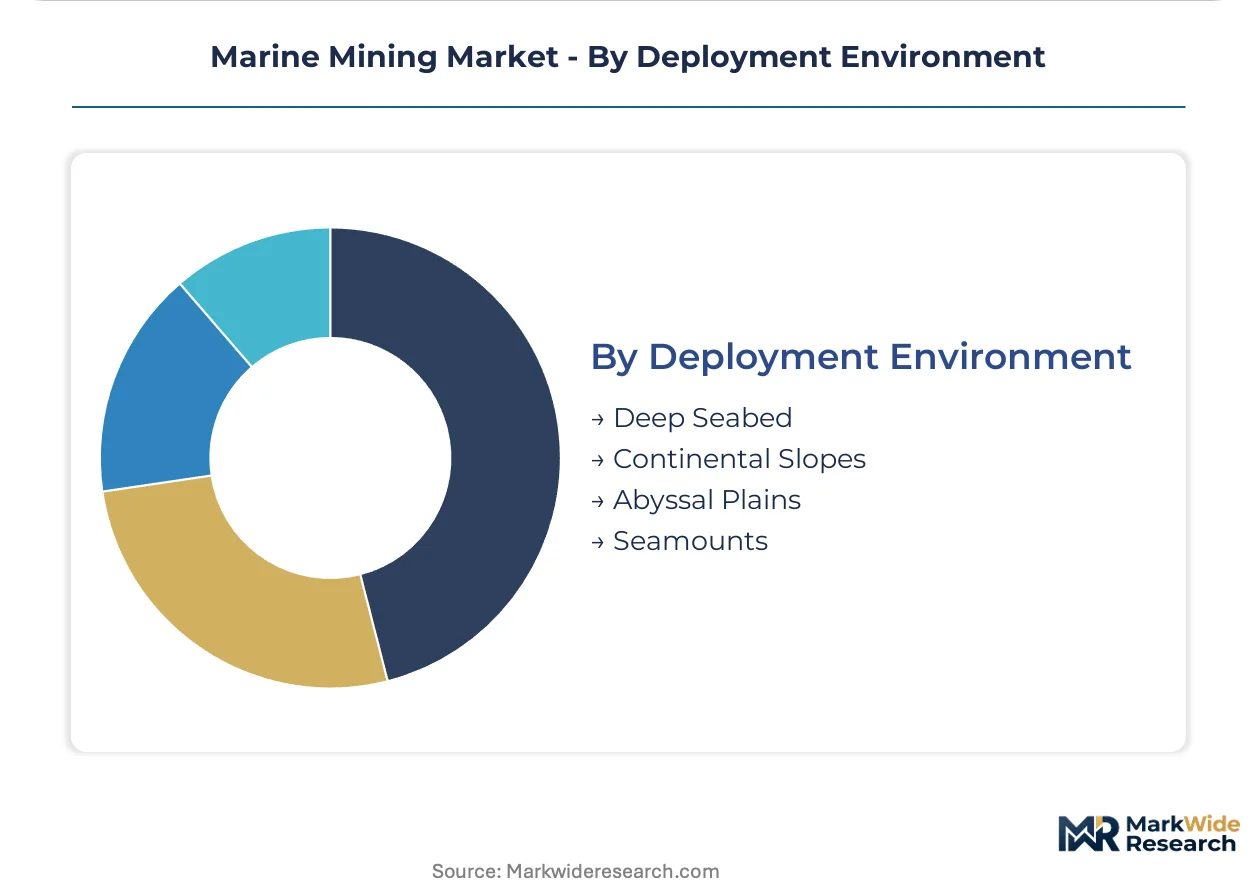
Abyssal plains attract exploration investment; seamounts present the highest technical barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Clarion-Clipperton Zone's contractor licensing framework concentrates exploration investment across multiple Pacific jurisdictions. National seabed authorities in island states compete with the International Seabed Authority's multilateral regime to attract capital deployment.
China
State-owned contractors dominate ISA-registered exploration contracts for polymetallic nodules in the Clarion-Clipperton Zone. The Ministry of Natural Resources coordinates seabed resource strategy through bilateral agreements with Pacific island states. Qingdao hosts the country's primary deep-sea engineering research cluster where pressure-rated mining component testing occurs.
Papua New Guinea
Shallow-water polymetallic sulfide deposits attract development interest from copper-gold concentrate offtakers. The Mineral Resources Authority governs territorial seabed concessions through domestic permitting frameworks independent of ISA jurisdiction. Port Moresby anchors the regulatory administration while New Ireland Province hosts the most advanced seabed sulfide assessment projects.
Cook Islands
The national Seabed Minerals Authority established faster domestic licensing pathways than international waters under ISA governance. Manganese nodule deposits across the exclusive economic zone draw hydraulic dredging system contractors seeking operational certainty. Avarua serves as the administrative center for concession negotiations with seabed mining ventures.
United States
Deepwater engineering contractors in Houston and San Diego supply pressure-rated subsea components to international seabed ventures. NOAA coordinates environmental baseline research requirements for domestic contractors operating beyond territorial waters. The Pacific Northwest hosts autonomous underwater vehicle manufacturers supplying exploration contractors in the Clarion-Clipperton Zone.
Marine Mining Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the marine mining value chain. The contractor base concentrates around three strategic archetypes: integrated mining majors leveraging terrestrial expertise, state-sponsored entities securing resource access through bilateral agreements, and specialized engineering firms supplying seabed-to-surface system components. Competitive positioning hinges on licensing portfolio depth and environmental compliance track records. Dominant competitive moves include strategic partnerships with Pacific island states and technology licensing arrangements for deepwater extraction systems.
Within the integrated mining major tier, BHP Group and Rio Tinto occupy positions defined by polymetallic resource assessment capabilities. State-sponsored contractors exemplified by China Molybdenum anchor the licensing-agreement vector through bilateral seabed arrangements. These three entities represent distinct strategic postures: diversified major, Anglo-Australian polymetallic specialist, and Chinese state-backed resource security player.
| Leading Market Players |
|---|
| Freeport-McMoRan |
| China Molybdenum |
| Glencore |
| ArcelorMittal Mining |
| MMC Norilsk Nickel |
| BHP Group |
| Newmont Corporation |
| Sibanye-Stillwater |
| Rio Tinto |
| Others |
Cost & Logistics Intelligence
Captive seabed-to-surface integration anchors both supply security and pricing power for marine mining contractors, as control over extraction systems, riser transport, and surface processing eliminates margin leakage to third-party equipment vendors while the International Seabed Authority's environmental baseline mandates concentrate compliant capacity among capitalized incumbents.
Pricing Analysis
Short lead-time premiums dominate contractor pricing structures, with integrated seabed-to-surface packages commanding 15-25% markups over standalone equipment procurement due to synchronization risk absorption by single-source providers. Price differentiation hinges on environmental compliance certification tier and depth-rated component quality grade, with ISA-registered contractors capturing sustained premiums against non-certified competitors. Cost compression in hydraulic dredging systems is intensifying because subsea pressure-rated component supply concentrates among limited marine engineering fabricators in Houston and Qingdao. State-sponsored contractors exhibit lowest price sensitivity due to resource security mandates, while independent exploration ventures face acute margin pressure from extended survey timelines.
Supply Chain Analysis
Domestic content mandates in Papua New Guinea and the Cook Islands are reshaping contractor sourcing patterns, requiring local operational presence and workforce development as licensing preconditions that fragment global equipment procurement. Supply concentrates in China, the United States, and Norway for pressure-rated subsea robotics, hydraulic dredging components, and autonomous underwater vehicle platforms. Raw material dependencies include high-strength titanium alloys, synthetic fiber tether cables, and rare earth magnet assemblies for propulsion systems. Single-source vulnerability runs through specialized subsea valve and pump manufacturers serving abyssal depth ratings. Distribution runs through integrated mining majors and state-sponsored entities rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine mining market operates as a cost-of-compliance story where the International Seabed Authority's developing exploitation code erects barrier-to-entry moats favoring contractors with established environmental baseline capabilities and capital reserves for extended pre-disturbance survey timelines.
For Market Incumbents: Extend licensing portfolio depth through bilateral seabed agreements with Pacific island states before ISA multilateral frameworks crystallize, while deepening backward integration into pressure-rated component manufacturing to offset supply concentration risk among Houston and Qingdao fabricators facing capacity constraints. For New Entrants and Emerging Players: Direct-to-turbine-OEM digital channels offer the most penetrable route for cobalt-rich crust offtake, bypassing established commodity traders by securing vertically integrated seabed-to-refinery commitments with European renewable energy manufacturers under EU Green Deal due diligence mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated mining majors seeking polymetallic sulfide assessment capabilities; long-term viability over the next decade rests on regulatory clearance velocity rather than resource grade alone. Watch ISA exploitation code finalization as the decisive inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bilateral Seabed Agreement | Cook Islands and Papua New Guinea licensing frameworks bypass ISA multilateral bottlenecks for faster operational clearance. |
| Environmental Baseline Investment | Pre-disturbance ecological survey capabilities satisfy ISA developing standards and differentiate compliant contractors. |
| Autonomous System Integration | AI-driven underwater vehicle convergence reduces exploration costs and expands exploitable deposit identification in the Clarion-Clipperton Zone. |
| Vertical Refinery Partnership | Seabed-to-surface-to-refinery offtake commitments secure turbine OEM procurement under EU Green Deal sourcing standards. |
| Deepwater Engineering Acquisition | Pressure-rated component fabricators in Houston and Qingdao represent critical supply chain control points for system integration. |
Research Approach
Multi-period observation of contractor licensing timelines, environmental survey expenditure patterns, and bilateral agreement formation anchored the trend analysis, supplemented by interviews with deepwater engineering procurement directors, seabed minerals authority regulators, autonomous underwater vehicle manufacturers, and offshore wind turbine OEM supply chain managers. Secondary validation drew from International Seabed Authority contractor registry filings, Pacific island state seabed minerals legislation, SEC 10-K disclosures from integrated mining majors, and EU Green Deal critical raw materials implementation guidance. Bottom-up project pipeline assessment triangulated against top-down mineral demand modeling from battery and renewable energy end-use sectors.
Input-output matrices structured the forecast architecture across the analysis window, with segmentation dimensions spanning deposit chemistry type, extraction technology modality, water depth environment, and end-use industry specification. CAGRs derived from mineral demand elasticity coefficients applied to electric vehicle cathode and offshore wind turbine manufacturing growth trajectories, cross-referenced against licensing capacity constraints under ISA and national regulatory frameworks. Industry-specific inputs included polymetallic sulfide grade distribution curves and manganese nodule density mapping coverage expansion rates from autonomous survey systems.
The model holds under stable ISA regulatory development timelines and sustained renewable energy manufacturing expansion; deviation in seabed moratorium enactment or deepwater robotics supply disruption would shift contractor revenue trajectories. Forecasts reflect documented assumptions regarding environmental compliance cost curves and bilateral agreement negotiation velocities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Oil Rig Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Indonesia Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market