
 Offshore Drilling Riser Market | 2026-2036
Offshore Drilling Riser Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Drilling Riser Market Analytics
IMO 2023 greenhouse gas reduction targets are pivoting offshore operators toward riser systems with lower embodied carbon and enhanced fatigue life. TechnipFMC plc leverages integrated engineering-to-installation capabilities across deepwater projects. Baker Hughes sustains technology leadership in managed pressure drilling riser interfaces. Schlumberger Limited anchors its position through digital twin and predictive maintenance offerings for riser integrity management.
An offshore drilling riser is a tubular conduit connecting a subsea wellhead to a surface drilling platform, typically fabricated from high-strength steel or titanium alloys with wall thicknesses engineered to withstand hydrostatic pressures exceeding 2,000 meters water depth while maintaining structural integrity under dynamic vessel motion. Its primary purpose is to provide a pressurized pathway for drilling fluids, casing strings, and completion tools between the seabed and the rig. Steel catenary risers dominate mature deepwater basins due to proven fatigue performance and lower capital intensity, while flexible risers capture fastest-growing share in ultra-deepwater tiebacks where vessel motion tolerance proves critical. Hybrid riser configurations concentrate margin pools where operators balance steel riser cost efficiency with buoyancy-supported lazy wave geometries for extreme depth applications.
Bureau of Safety and Environmental Enforcement standards govern riser design verification and blowout preventer integration testing for US Gulf of Mexico operations, while NORSOK D-010 and ISO 13628-7 establish international baseline specifications for subsea production systems including riser mechanical connectors and fatigue analysis protocols. These frameworks shape demand by mandating redundant barrier designs, real-time monitoring systems, and third-party certification that elevate engineering requirements and consolidate procurement toward qualified suppliers. Stakeholders must monitor how evolving methane detection mandates and subsea electrification roadmaps redefine riser instrumentation specifications and qualification timelines.
Market Dynamics
The offshore drilling riser market is restructuring around water depth capability thresholds as operators push into 3,000-meter frontiers where steel catenary fatigue limits force material innovation and hybrid architecture adoption.
Growth Catalysts
- Brazil Pre-Salt Development:Petrobras and international consortium drilling programs in the Santos Basin are mandating riser systems rated for 2,500-meter water depths with high-pressure high-temperature tolerances.
- IMO 2023 GHG Strategy:The International Maritime Organization's revised greenhouse gas reduction framework is accelerating specification of titanium alloy riser joints with lower embodied carbon than conventional steel grades.
- Managed Pressure Drilling Integration:Advanced riser gas handler systems are enabling closed-loop drilling in narrow-margin deepwater formations previously classified as undrillable.
Market Restraints
- Titanium Alloy Supply Concentration:Specialty titanium forging capacity concentrates among Japanese and Russian suppliers, exposing procurement timelines to geopolitical disruption and alloy price volatility.
- NORSOK D-010 Certification Burden:Third-party verification requirements for subsea production system connectors extend qualification timelines by 18-24 months for new riser designs.
- Flexible Rier Cost Premium:Unbonded dynamic riser systems from established suppliers command 40-60% capital cost premiums over steel alternatives in 1,500-meter applications.
Strategic Opportunities
- West African Ultra-Deepwater:Mauritania and Senegal offshore gas developments are specifying hybrid riser configurations for 2,800-meter water depths where no installed base exists.
- Subsea Electrification Mandates:Norway's offshore electrification roadmap is creating demand for riser-integrated power and fiber optic umbilical channels in new field developments.
- Digital Twin Convergence:Real-time riser integrity monitoring fused with predictive analytics is opening performance-based contracting models for brownfield life extension projects.
Industry Challenges
- Fatigue Analysis Specialist Shortage:Deepwater riser engineering requires combined hydrodynamic and fracture mechanics expertise that remains concentrated among a limited pool of qualified analysts.
- Legacy BOP Stack Compatibility:New high-fatigue steel grades require interface recertification with existing subsea blowout preventer configurations, complicating rig fleet deployment flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Drilling Riser Market |
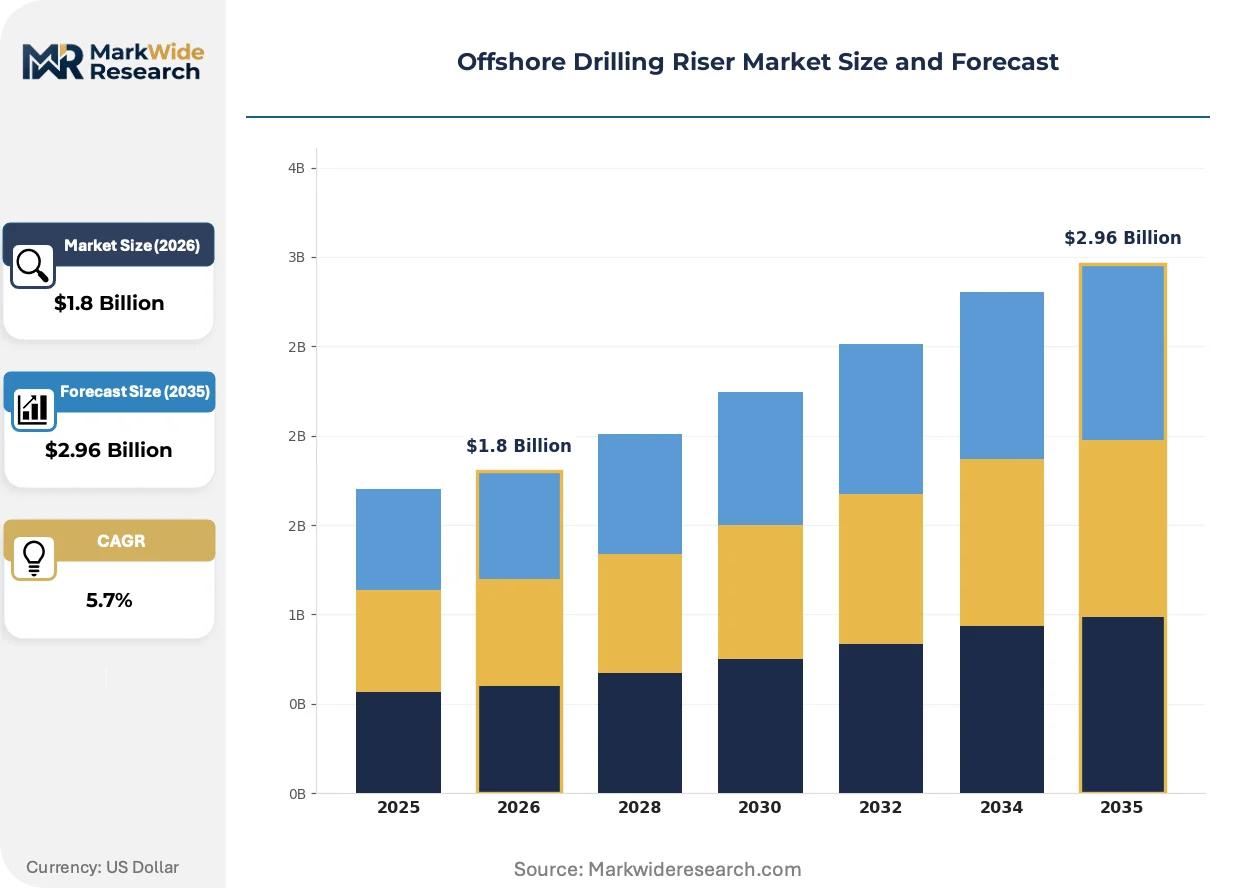
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Risers, Steel Catenary Risers, Lazy Wave Risers, Hybrid Risers Application: Exploration, Production, Subsea Processing, Transportation Installation Method: Wet Installation, Dry Installation, Reel-Lay Installation, J-Lay Installation End User: Oil & Gas Companies, Independent Operators, Service Providers, Government Agencies |
| Companies Covered | TechnipFMC plc, Schlumberger Limited, Tenaris, Baker Hughes, Aker Solutions, Subsea 7, Weatherford, Dril-Quip, Inc., Parker Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Drilling Riser Market Evolving Landscape
Material science breakthroughs and real-time monitoring architectures are compressing the performance gap between steel and hybrid riser systems while regulatory pressure on carbon intensity reshapes supplier qualification criteria.
Composite armor flexible risers with carbon fiber tensile reinforcement layers are decentralizing the engineering trade-off between vessel motion tolerance and pressure containment capacity. Petrobras and supermajor operators in Brazil's pre-salt fields are deploying these systems in 2,200-meter configurations previously dominated by steel catenary designs. The technology is decentralizing procurement decisions from pure capital cost optimization toward total lifecycle fatigue performance metrics.
REACH regulation amendments on persistent organic pollutants are restricting legacy hydraulic fluid chemistries used in riser tensioner systems, forcing European operators toward synthetic ester and water-glycol alternatives. The industrial consequence is accelerated qualification timelines for seal and packing materials compatible with new fluid specifications. North Sea developments are responding fastest, with Norwegian operators mandating bio-based hydraulic fluids in all new riser tensioning contracts.
Integrated drilling contractor packages are compressing traditional riser procurement cycles as supermajors consolidate vendor lists under single-point-responsibility frameworks. The segment being disrupted is standalone riser engineering procurement, replaced by bundled drilling system contracts where riser specification is subordinate to integrated well delivery performance guarantees. This pattern is most visible in US Gulf of Mexico lease rounds, where integrated drilling contractors now specify riser configurations without separate owner engineering review.
Offshore Drilling Riser Market Segmentation
Riser procurement decisions diverge sharply across water depth thresholds, installation logistics, and operator risk tolerance. Understanding these splits reveals where engineering margins concentrate and which configurations capture replacement cycles versus greenfield specifications.
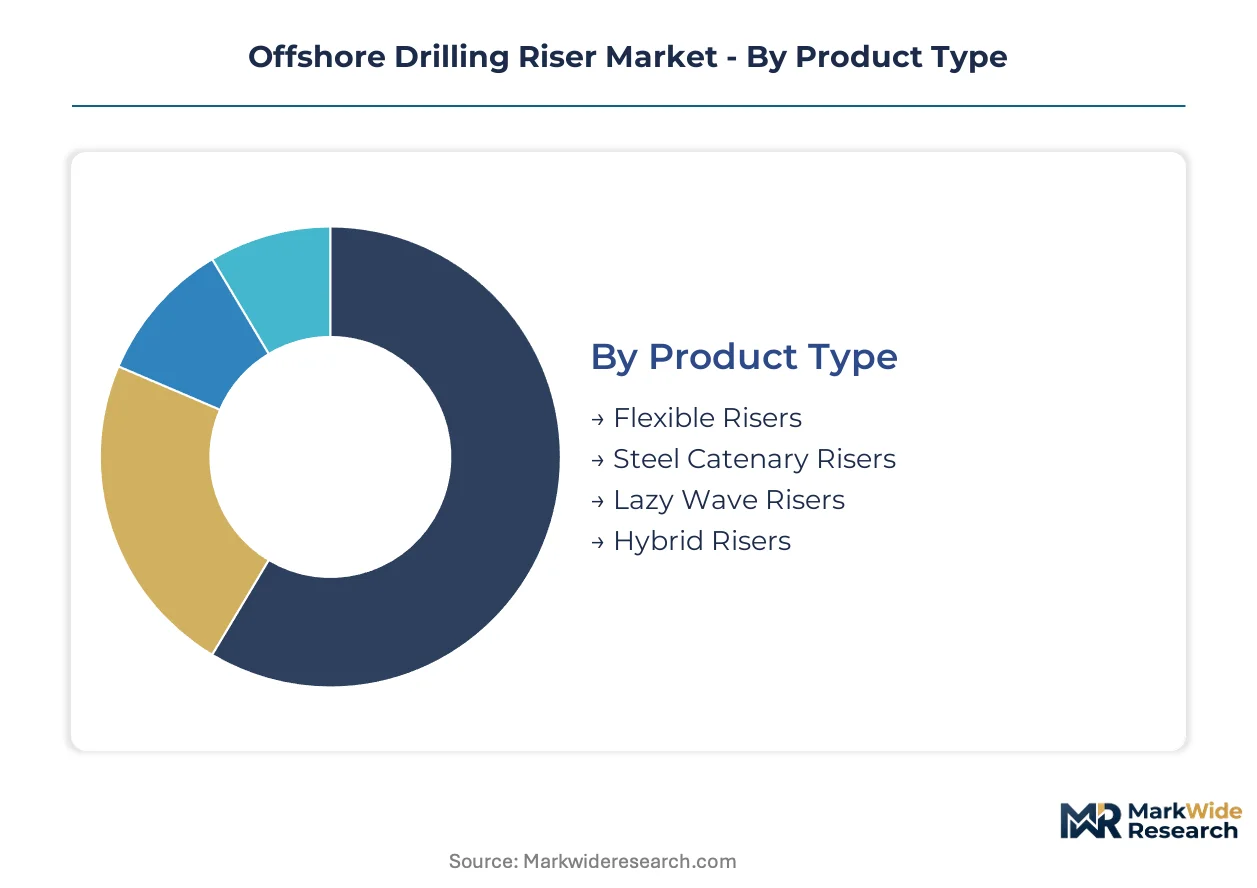
Product Type:
Buyers differentiate primarily by fatigue performance requirements versus capital efficiency trade-offs at target water depths.
- Flexible Risers:Unbonded dynamic systems with helical steel armor and polymer barrier layers tolerate vessel motion in ultra-deepwater tiebacks. Demand clusters in Brazil's pre-salt Santos Basin where Petrobras deploys these configurations beyond 2,200 meters, driven by vessel motion tolerance requirements that steel cannot match.
- Steel Catenary Risers:High-strength steel tubulars in free-hanging catenary geometry dominate mature deepwater basins with proven fatigue databases and lower installed cost. Gulf of Mexico operators favor these for 1,500-meter developments where installation infrastructure and weld inspection protocols are standardized.
- Lazy Wave Risers:Buoyancy-supported steel configurations reduce top tension and fatigue damage in intermediate depths.
- Hybrid Risers:Combined steel riser base with flexible jumper connections to floating platforms.
Volume sits with Steel Catenary Risers; growth tilts toward Flexible Risers.
Application:
Revenue concentration follows field lifecycle stage, with exploration commanding premium day rates and production driving installed base expansion.
- Exploration:Temporary riser systems for wildcat drilling in frontier basins require rapid deployment and retrieval capabilities. West African ultra-deepwater campaigns off Mauritania and Senegal specify exploration-rated hybrid configurations for 2,800-meter water depths where no production infrastructure exists.
- Production:Permanent riser installations for hydrocarbon export from subsea wells to surface facilities. Norway's offshore electrification roadmap is mandating production risers with integrated power and fiber optic umbilical channels, reshaping procurement specifications for new field developments.
- Subsea Processing:Risers connecting seabed separation and boosting equipment to host platforms.
- Transportation:Export risers for pipeline tie-ins and offloading systems.
Procurement value concentrates in Production; specification innovation is climbing the fastest in Exploration.
Installation Method:
Contractor fleet capabilities and weather window constraints determine method selection more than riser design itself.
- Wet Installation:Subsea assembly of riser joints with diver or remotely operated vehicle support. Shallow-water Gulf of Mexico shelf developments rely on wet installation where diving spreads remain cost-competitive and hurricane recovery demands rapid reconnection capability.
- Reel-Lay Installation:Continuous pipe spooling from shore-based fabrication facilities enables high-speed offshore deployment. North Sea operators prefer reel-lay for bundled production riser and flowline installations that minimize offshore welding and inspection time.
- Dry Installation:Deck-level assembly with subsequent overboarding in protected conditions.
- J-Lay Installation:Near-vertical pipe laying from specialized vessels for deepwater steel risers.
Reel-Lay dominates brownfield tiebacks; J-Lay secures ultra-deepwater greenfield share.
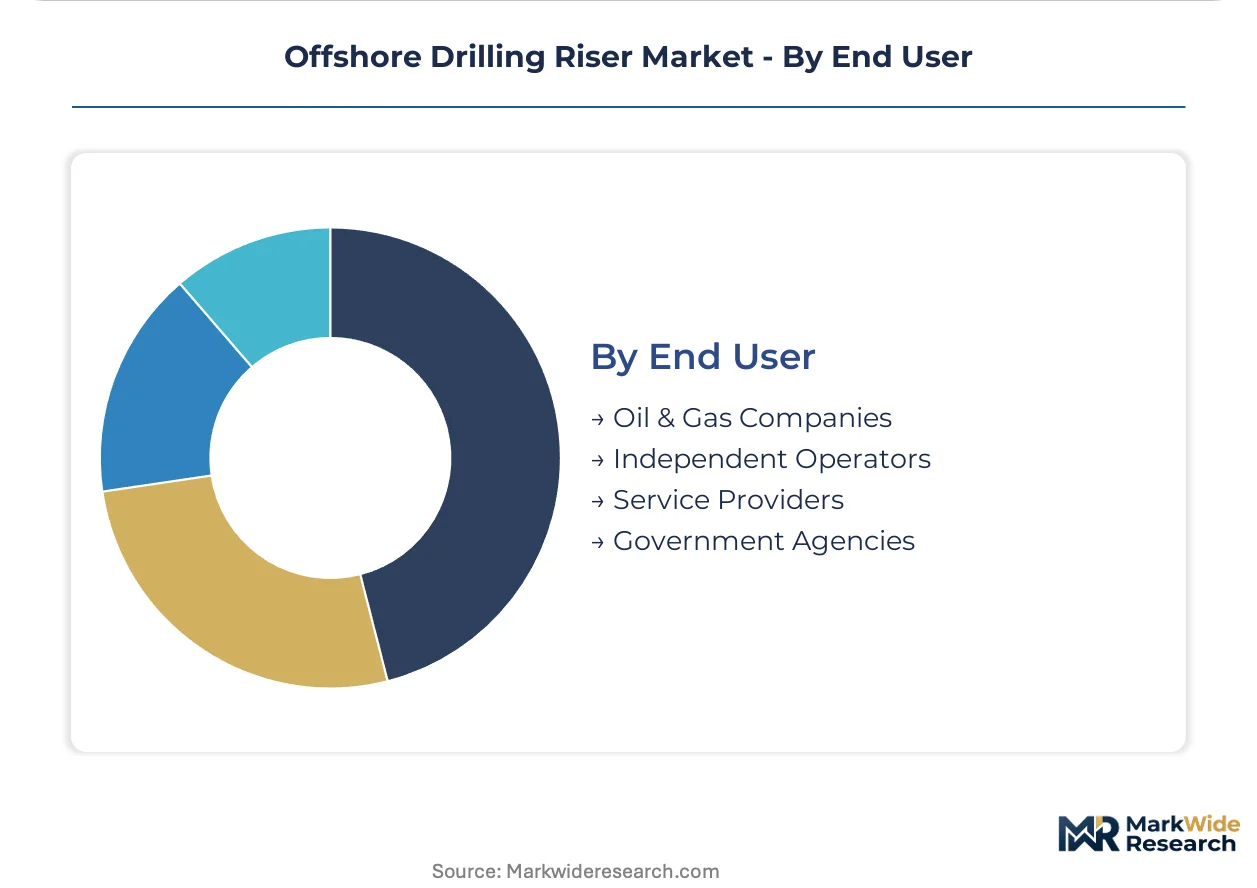
End User:
Capital allocation discipline and in-house engineering depth separate integrated supermajors from fleet-dependent independents.
- Oil & Gas Companies:Integrated supermajors and national oil companies with proprietary riser specifications and long-term supplier frameworks. Petrobras maintains dedicated riser engineering centers in Rio de Janeiro that specify custom fatigue criteria beyond industry standards for pre-salt developments.
- Independent Operators:Smaller exploration and production companies without captive drilling assets. US Gulf of Mexico independents rely on drilling contractor riser packages, ceding specification control to integrated service providers under single-point-responsibility contracts.
- Service Providers:Drilling contractors and installation specialists owning and operating riser inventory.
- Government Agencies:State-backed entities regulating offshore leasing and safety compliance.
Specification authority rests with Oil & Gas Companies; fleet ownership concentrates among Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of high-performance riser systems while manufacturing concentrates among specialized forging facilities in Japan and Russia. Brazil's pre-salt developments drive premium specification demand. Norway mandates the most stringent integration standards for subsea electrification.
United States
Bureau of Safety and Environmental Enforcement standards govern riser design verification and blowout preventer integration testing for Gulf of Mexico operations. The regulator mandates redundant barrier designs and real-time monitoring systems that elevate engineering requirements. Houston anchors the largest concentration of drilling contractor headquarters specifying integrated riser packages under single-point-responsibility frameworks.
Brazil
Petrobras and international consortium drilling programs in the Santos Basin mandate riser systems rated for 2,500-meter water depths with high-pressure high-temperature tolerances. ANP regulatory frameworks require third-party certification for subsea production system connectors. Rio de Janeiro hosts dedicated riser engineering centers specifying custom fatigue criteria beyond industry standards for pre-salt developments.
Norway
The country's offshore electrification roadmap creates demand for riser-integrated power and fiber optic umbilical channels in new field developments. NORSOK D-010 standards establish international baseline specifications for subsea production systems including riser mechanical connectors. Stavanger clusters engineering expertise for hybrid riser configurations balancing steel cost efficiency with buoyancy-supported lazy wave geometries.
Japan
Specialty titanium forging capacity concentrates among Japanese suppliers, exposing procurement timelines to geopolitical disruption and alloy price volatility. METI industrial policy supports advanced materials development for extreme depth applications. Osaka and Nagoya host metallurgical facilities supplying high-fatigue steel grades requiring interface recertification with existing subsea blowout preventer configurations.
United Kingdom
North Sea operators prefer reel-lay installation for bundled production riser and flowline installations minimizing offshore welding time. REACH regulation amendments restrict legacy hydraulic fluid chemistries used in riser tensioner systems. Aberdeen anchors the primary cluster of drilling contractors and installation specialists owning and operating riser inventory for brownfield tiebacks.
Offshore Drilling Riser Market Competitive Landscape
The competitive structure tilts toward integrated engineering-to-installation providers with captive forging relationships. Tiered specialization separates full-system integrators from component specialists and regional fabrication houses. Two dominant strategic archetypes define positioning: integrated technology licensors bundling riser specification into drilling performance contracts, and independent forging specialists supplying alloy joints to multiple integrators. Competitive moves concentrate on capacity expansion in titanium alloy forging and strategic partnerships for ultra-deepwater qualification programs.
Among the integrated tier, TechnipFMC plc and Schlumberger Limited exemplify full-system positioning spanning engineering through installation. Baker Hughes occupies a specialist position in managed pressure drilling riser interfaces. These three entities anchor the premium specification segment where procurement shifts toward bundled drilling system contracts with performance guarantees.
| Leading Market Players |
|---|
| TechnipFMC plc |
| Schlumberger Limited |
| Tenaris |
| Baker Hughes |
| Aker Solutions |
| Subsea 7 |
| Weatherford |
| Dril-Quip, Inc. |
| Parker Hannifin Corp |
| Others |
Value Network & Pricing Analysis
Composite armor flexible riser deployment in Brazil's pre-salt basins simultaneously compresses lifecycle cost economics and concentrates procurement leverage among operators with captive vessel fleets. This technology transition rewards integrated engineering-to-installation providers while marginalizing standalone component suppliers unable to bundle performance guarantees.
Pricing Analysis
Margin tightening in steel catenary riser tiers reflects titanium alloy feedstock volatility and extended NORSOK D-010 certification timelines. Project-based long-term contracting dominates, with price differentiation anchored in fatigue-grade certification and integrated installation bundling. Independent operators exhibit highest price sensitivity, ceding specification authority to drilling contractors under single-point-responsibility frameworks. Cost-down pressure on flexible riser systems accelerates as Petrobras consolidates vendor lists and demands lifecycle performance warranties.
Supply Chain Analysis
Specialist welding and fracture mechanics expertise scarcity in Japan and Russia constrains forging capacity expansion for high-fatigue steel grades and titanium alloys. Raw material flows draw from seabed ore concentrates, polymer barrier layers, and carbon fiber tensile reinforcement. Single-source vulnerability concentrates in Japanese titanium forging facilities, exposing procurement timelines to geopolitical disruption. Distribution runs through integrated drilling contractor networks rather than standalone equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NORSOK D-010 and Bureau of Safety and Environmental Enforcement compliance requirements erect substantial barrier-to-entry moats, consolidating procurement toward pre-qualified suppliers with verified fatigue databases and third-party certification track records.
For Market Incumbents: Anchor market position through captive titanium alloy forging relationships and backward integration into predictive maintenance software stacks. Defend against emerging composite armor specialists by accelerating qualification timelines for hybrid riser configurations in West African ultra-deepwater frontiers. Prioritize certification investment in bio-based hydraulic fluid compatibility for North Sea electrification mandates. For New Entrants and Emerging Players: Capture specification influence in Mauritania and Senegal exploration campaigns where no installed base exists and operator engineering depth remains thin. Target independent operators in US Gulf of Mexico shelf developments seeking rapid deployment capabilities outside integrated contractor frameworks. Lead with digital twin-enabled performance contracting that shifts revenue from equipment sale to uptime guarantees. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated drilling contractors seeking to bundle riser specification into single-point-responsibility contracts. Long-term viability favors suppliers with demonstrated ultra-deepwater qualification records and captive materials science capabilities. Monitor ANP regulatory amendments on subsea connector certification as inflection signal for procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Titanium Alloy Forging Capacity Expansion | Captive supply of high-fatigue joints secures qualification timelines for Petrobras pre-salt programs. |
| Digital Twin Platform Integration | Real-time riser integrity monitoring enables performance-based contracting for brownfield life extension. |
| Composite Armor Qualification Program | Carbon fiber tensile reinforcement unlocks 2,200-meter configurations previously dominated by steel. |
| Subsea Electrification Partnership | Integrated power and fiber optic umbilical channels capture Norway's offshore electrification roadmap. |
| Managed Pressure Drilling Interface Development | Advanced riser gas handler systems enable closed-loop drilling in narrow-margin deepwater formations. |
Research Methodology
Regulatory filings from the Bureau of Safety and Environmental Enforcement, ANP certification databases, and NORSOK D-010 technical standards formed the secondary backbone for compliance requirement mapping. Primary interviews with riser engineering directors, drilling contractor procurement leads, subsea installation specialists, and fatigue analysis consultants combined with customs trade data and SEC equipment supplier disclosures. Bottom-up project pipeline tracking and top-down operator capital expenditure analysis enabled triangulation across data sources.
Historical trendline analysis of water depth capability thresholds and material adoption curves informed projection modeling across the analysis window. Segmentation dimensions included riser product type, application lifecycle stage, installation method, and end-user capital allocation discipline. CAGRs derived from regression analysis of fleet deployment schedules and field development sanctioning patterns. Industry-specific inputs incorporated IMO greenhouse gas strategy implementation timelines and subsea electrification roadmap milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium alloy supply disruption and West African exploration success rates. Forecasts reflect documented assumptions regarding Petrobras pre-salt drilling cadence and supermajor integrated contracting consolidation. Material deviation in ANP regulatory stringency or Japanese forging capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market