
 Offshore Remote Monitoring Solutions Market | 2026-2036
Offshore Remote Monitoring Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Remote Monitoring Solutions Market Analytics
The EU Green Deal is decoupling legacy offshore operations from cost-competitive monitoring by mandating real-time emissions and safety transparency. Honeywell International Inc. leverages its industrial automation heritage to anchor predictive maintenance platforms across North Sea installations. Siemens AG sustains technology leadership through edge-computing architectures purpose-built for subsea connectivity. Emerson Electric Co. differentiates via deep vertical integration into sensor hardware and analytics software.
Offshore remote monitoring solutions encompass sensor networks, telemetry systems, and analytics platforms that collect, transmit, and process operational data from fixed and floating assets beyond coastal infrastructure. These systems typically integrate satellite, acoustic, and fiber-optic communication links to bridge distances exceeding 200 nautical miles while withstanding corrosive marine environments. IoT-enabled sensor arrays dominate current deployments, though AI-driven predictive diagnostics represent the fastest-expanding technology segment as operators seek to reduce unplanned downtime. Cloud-based architectures capture growing share among newer renewable energy installations, while hybrid deployments persist across legacy oil and gas platforms where intermittent connectivity demands local data buffering.
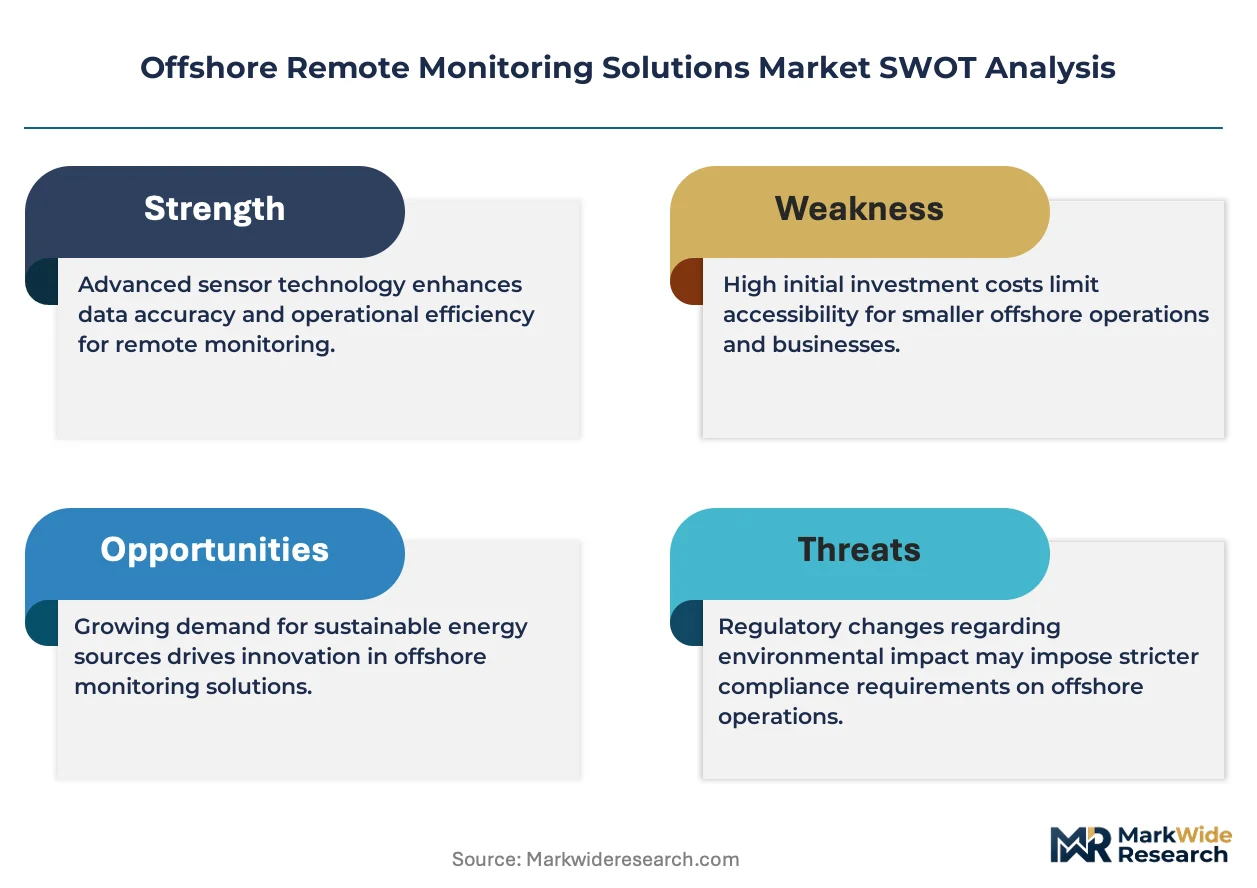
The US Coast Guard and Bureau of Safety and Environmental Enforcement impose equipment certification standards that shape platform design requirements for Gulf of Mexico operators. Norway's Petroleum Safety Authority and the UK's Health and Safety Executive enforce functional safety protocols that directly determine sensor redundancy and failover specifications. Stakeholders must weigh regulatory divergence against platform standardization economics as offshore monitoring obligations tighten across jurisdictions.
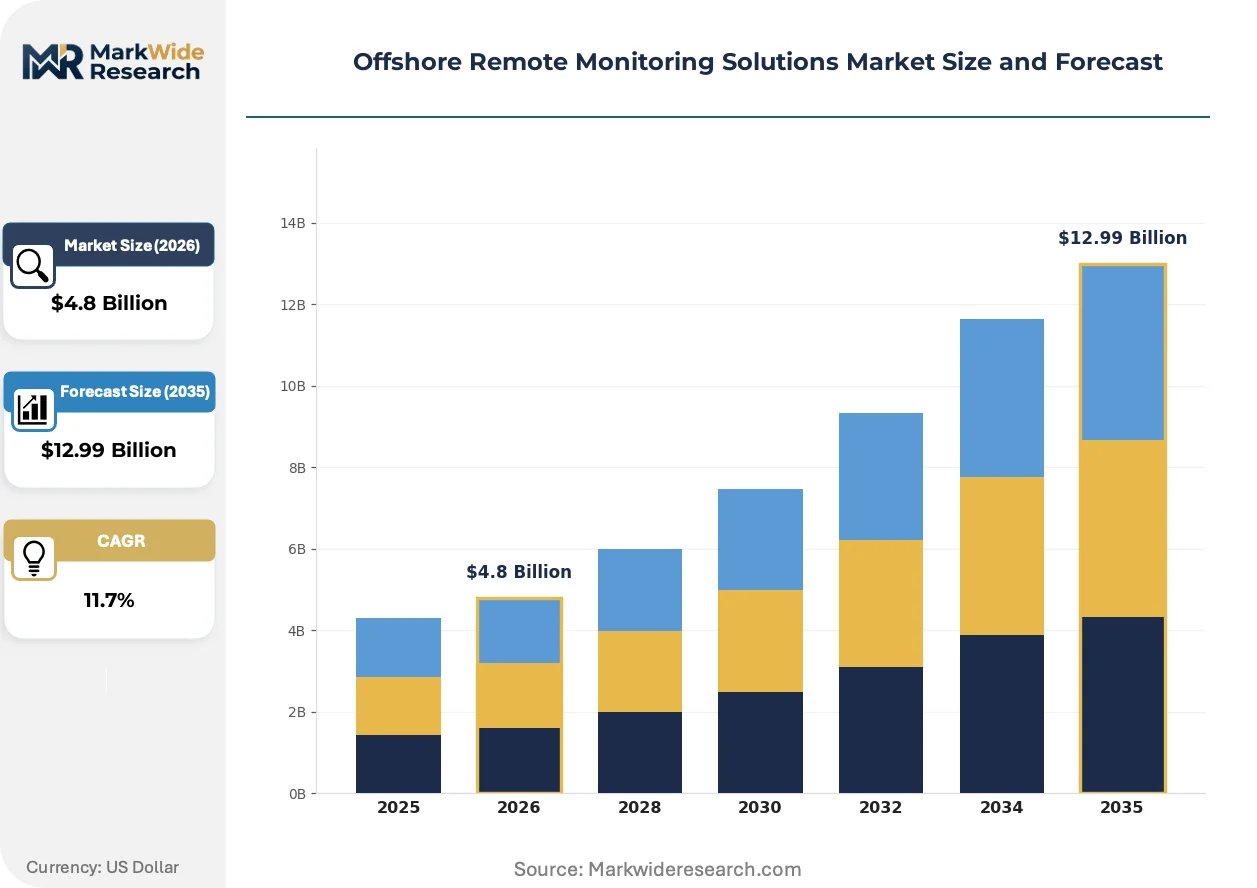
Market Dynamics
The EU Green Deal's emissions transparency mandates are compressing deployment timelines for offshore asset operators, forcing simultaneous upgrades across sensor networks, telemetry infrastructure, and cloud analytics platforms to maintain operating licenses.
Growth Catalysts
- EU Green Deal compliance deadlines:Offshore wind and oil and gas operators in the North Sea must install continuous emissions monitoring systems to satisfy the EU Green Deal's maritime transparency requirements.
- Floating offshore wind expansion:Turbine deployments in deeper waters beyond fixed-foundation limits require satellite-reliant monitoring architectures that expand addressable platform demand.
- Edge computing maturation:Localized data processing at subsea nodes reduces bandwidth costs and enables real-time anomaly detection for dispersed North Sea arrays.
Market Restraints
- Subsea cable supply concentration:Fiber-optic umbilical manufacturing concentrates among a limited supplier base in Norway and the United Kingdom, creating procurement bottlenecks for large-scale deployments.
- Corrosion-resistant alloy costs:Titanium and super-duplex stainless steel sensor housings face price volatility tied to nickel and molybdenum commodity markets, compressing hardware margins.
- REACH substance restrictions:The European Chemicals Agency's evolving substance authorization list limits certain coating and sealant chemistries used in marine electronics manufacturing.
Strategic Opportunities
- Hydrogen platform monitoring:Offshore electrolyzer installations for green hydrogen production create demand for hydrogen-specific pressure and purity sensors in North Sea energy hubs.
- Carbon capture and storage integration:Subsea CO2 injection sites require new seismic and pressure monitoring modalities that extend platform functionality beyond traditional oil and gas applications.
- CSRD-aligned data services:The EU Corporate Sustainability Reporting Directive creates subscription demand for emissions verification analytics from asset owners seeking audit-ready documentation.
Industry Challenges
- Subsea robotics technician scarcity:Deployment and maintenance of autonomous underwater vehicles for sensor calibration requires specialized marine robotics expertise that outpaces training pipeline output.
- Legacy SCADA integration complexity:Brownfield oil platforms operate decades-old control systems that resist seamless interfacing with modern IoT telemetry architectures without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Remote Monitoring Solutions Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Big Data Service Type: Data Analysis, Predictive Maintenance, System Integration, Cybersecurity End User: Oil & Gas, Maritime, Renewable Energy, Utilities Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Honeywell International Inc., Siemens AG, Emerson Electric Co., Schneider Electric SE, ABB Ltd., National Oilwell Varco, Kongsberg Gruppen, Schlumberger Limited, Subsea 7 S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Remote Monitoring Solutions Market Evolving Landscape
Digital twin architectures are merging physics-based simulation with live sensor feeds to compress maintenance decision cycles for subsea infrastructure operators.
Digital twin platforms are integrating finite-element stress models with real-time vibration and corrosion sensor data from North Sea wind turbine foundations. Offshore operators in Norway and the United Kingdom are deploying these systems at pilot scale before full-fleet rollout. The technology is integrating predictive maintenance workflows that previously required separate engineering teams and manual data reconciliation.
The EU AI Act's risk classification framework is imposing documentation and validation requirements on automated diagnostic algorithms used in safety-critical offshore monitoring. Vendors must now maintain technical file repositories demonstrating conformity assessment for AI-driven anomaly detection systems. North Sea operators are responding by segregating AI tool deployments between safety-critical and non-critical monitoring functions to manage compliance burden.
Asset owners are consolidating vendor relationships around integrated platform providers capable of delivering sensor hardware, edge computing, and cloud analytics under unified service agreements. This procurement compression displaces point-solution contracts that previously fragmented responsibility across telemetry, software, and maintenance specialists. The shift is most pronounced among German offshore wind developers seeking single-accountability structures for warranty and performance guarantees.
Offshore Remote Monitoring Solutions Market Segmentation
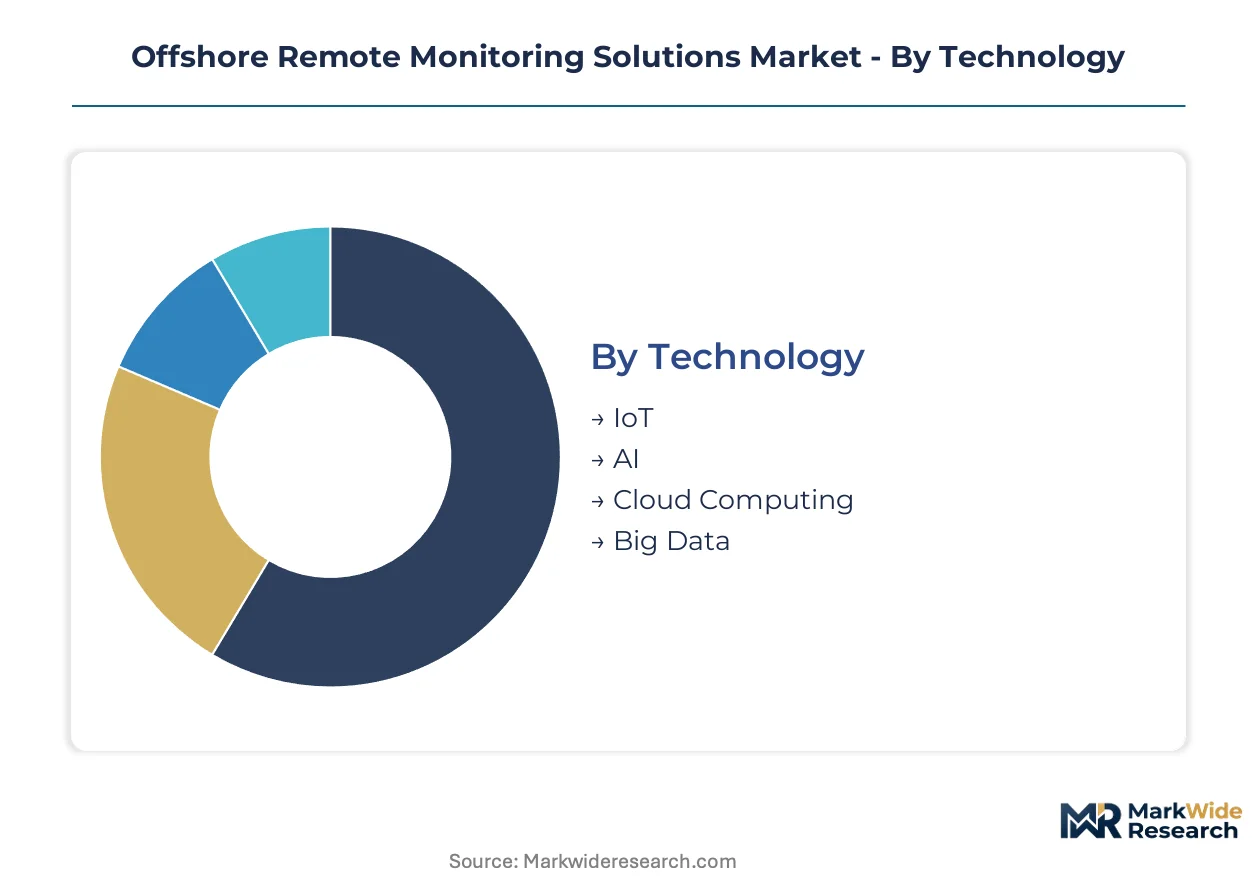
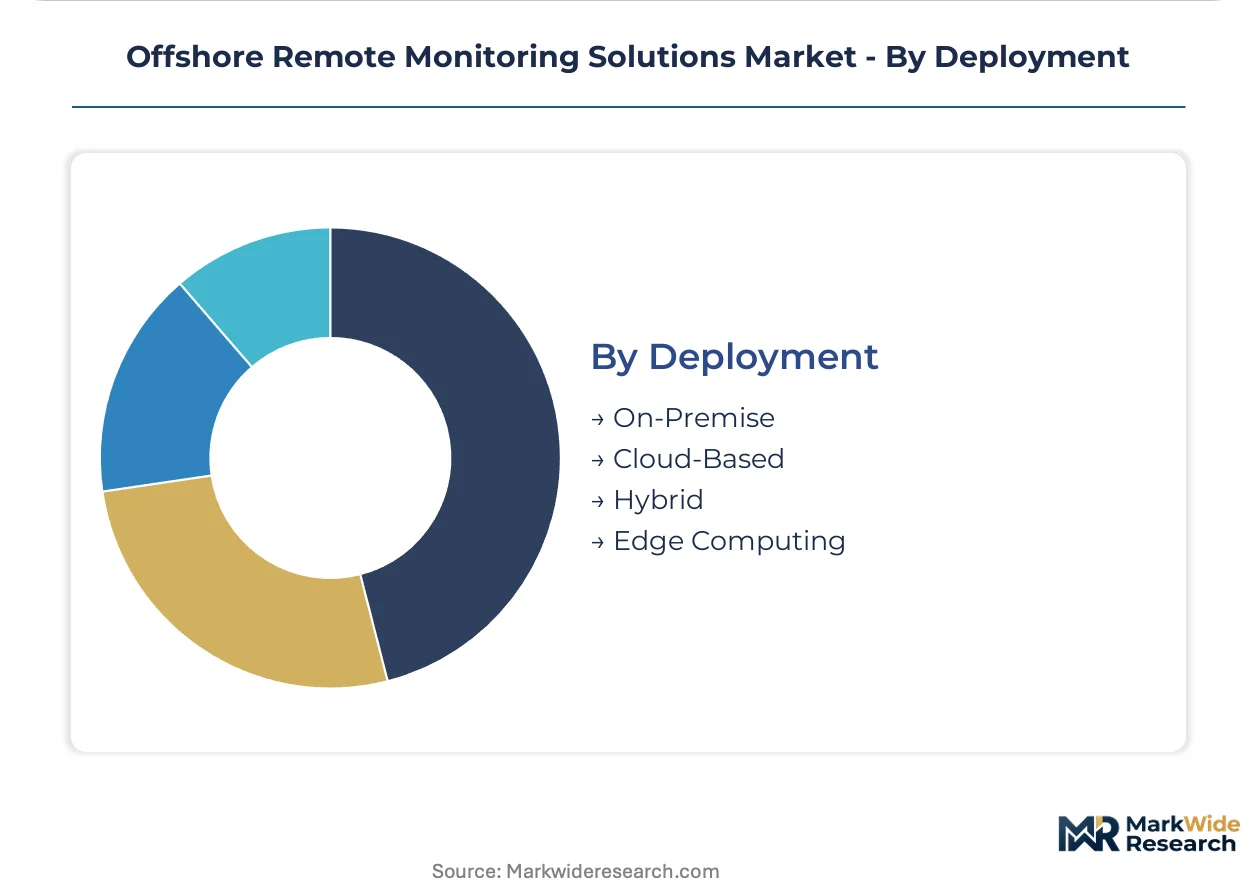
Offshore remote monitoring solutions fragment across four dimensions that determine procurement priorities and vendor selection criteria. Technology choices dictate hardware durability requirements in corrosive marine environments. Deployment models balance connectivity constraints against real-time analytics needs for dispersed North Sea assets.
Technology:
Technology selection separates operators pursuing incremental sensor upgrades from those rebuilding monitoring architecture around predictive capabilities.
- IoT:Sensor networks combining satellite, acoustic, and fiber-optic links bridge distances exceeding 200 nautical miles. Norwegian and UK offshore wind developers deploy IoT arrays for turbine performance monitoring across dispersed North Sea arrays, driven by EU Green Deal emissions transparency mandates.
- AI:Machine learning algorithms process vibration, corrosion, and thermal data to flag subsea infrastructure anomalies before failure. Floating offshore wind installations in deeper waters prioritize AI-driven predictive diagnostics to reduce unplanned downtime where maintenance vessel dispatch costs escalate.
- Cloud Computing:Centralized data lakes enable fleet-level benchmarking across multiple offshore assets. Cloud architectures capture growing share among newer renewable energy installations seeking scalable storage without capital-intensive on-premise infrastructure.
- Big Data:Historical operational datasets train diagnostic models and optimize maintenance scheduling. Oil and gas operators with decades of subsea production records leverage big data analytics to extend asset life on mature North Sea platforms.
Volume sits with IoT sensor networks; growth tilts toward AI predictive diagnostics.
Service Type:
Service procurement patterns reflect whether asset owners retain analytics capabilities in-house or outsource to platform specialists.
- Data Analysis:Raw sensor streams transform into actionable operational intelligence through statistical and visualization tools. German offshore wind developers subscribe to third-party data analysis services to satisfy CSRD-aligned emissions verification requirements without building internal teams.
- Predictive Maintenance:Algorithmic failure forecasting compresses maintenance decision cycles and reduces emergency repair frequency. Predictive maintenance contracts expand fastest among floating wind operators facing helicopter and vessel access constraints in deeper North Sea waters.
- System Integration:Middleware development bridges legacy SCADA systems with modern IoT telemetry architectures. Brownfield oil platforms require extensive integration services to connect decades-old control systems to cloud analytics platforms.
- Cybersecurity:Network segmentation and encryption protocols protect subsea communication links from intrusion. Cybersecurity services gain priority as offshore monitoring systems interconnect with shore-based corporate networks and third-party cloud providers.
Revenue concentrates in data analysis subscriptions; predictive maintenance claims the steepest expansion trajectory.
End User:
End user verticals diverge in sensor redundancy requirements, regulatory compliance burdens, and acceptable latency thresholds.
- Oil & Gas:Exploration and production platforms monitor subsea wellheads, flowlines, and processing equipment for pressure integrity and leak detection. Norway's Petroleum Safety Authority and the UK's Health and Safety Executive enforce functional safety protocols that determine sensor failover specifications for North Sea operators.
- Maritime:Vessel operators track engine performance, fuel consumption, and emissions for fleet optimization and regulatory reporting. Maritime demand concentrates among container and tanker fleets serving EU ports subject to Green Deal maritime transparency requirements.
- Renewable Energy:Offshore wind farms monitor turbine mechanical health, foundation structural integrity, and electrical output. Renewable energy developers in Germany, Norway, and the United Kingdom drive platform demand as offshore wind capacity multiplies.
- Utilities:Grid-connected offshore assets require synchronization monitoring and power quality assessment. Utility operators prioritize cybersecurity and grid code compliance in monitoring specifications.
Deployment value clusters with oil and gas incumbents; renewable energy installations are expanding most quickly.
Deployment:
Deployment architecture selection hinges on connectivity reliability, data sovereignty requirements, and edge processing latency needs.
- On-Premise:Local servers store and process operational data without external network dependency. Legacy oil and gas platforms maintain on-premise deployments where intermittent satellite connectivity demands local data buffering.
- Cloud-Based:External data centers host analytics platforms with elastic compute scaling. Cloud-based architectures dominate newer renewable energy installations seeking to avoid capital expenditure on shore-based infrastructure.
- Hybrid:Critical data processes locally while non-urgent analytics migrate to cloud environments. Hybrid deployments persist across brownfield assets transitioning from legacy systems to modern architectures.
- Edge Computing:Subsea nodes execute data processing at the sensor location to reduce bandwidth costs and enable real-time anomaly detection. Edge computing maturation supports floating offshore wind expansion beyond fixed-foundation limits.
Installed base favors hybrid configurations; edge computing gains share fastest among deepwater installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore remote monitoring solutions concentrate where North Sea energy infrastructure multiplies and regulatory mandates tighten fastest. Norway, the United Kingdom, and Germany together absorb the dominant share of platform deployments.
Norway
Equinor and Aker BP drive floating offshore wind and subsea oilfield automation investments. The Petroleum Safety Authority enforces functional safety protocols that mandate sensor redundancy for subsea wellhead monitoring. Bergen and Stavanger anchor the supplier ecosystem where Kongsberg Gruppen and local sensor fabricators cluster around deepwater technology development.
United Kingdom
Offshore wind capacity expansion in Scottish waters and the North Sea generates turbine performance monitoring demand. The Health and Safety Executive imposes failover specifications for subsea infrastructure that shape procurement decisions. Aberdeen maintains its position as the primary service hub where system integrators and AUV operators support North Sea asset deployments.
Germany
Offshore wind developers in the Baltic and North Seas seek unified service agreements for warranty accountability. The Federal Maritime and Hydrographic Agency enforces installation certification standards that filter platform vendor eligibility. Bremerhaven and Hamburg concentrate manufacturing and port logistics for floating foundation deployments requiring satellite-reliant monitoring architectures.
United States
Gulf of Mexico oil and gas operators modernize aging platforms under Bureau of Safety and Environmental Enforcement equipment certification requirements. The Coast Guard imposes communication reliability standards for offshore asset tracking. Houston anchors the vendor ecosystem where industrial automation specialists and subsea service companies coordinate brownfield retrofit programs.
China
State-owned offshore oil developers and emerging floating wind projects expand subsea monitoring procurement. The Ministry of Ecology and Environment tightens emissions disclosure requirements for maritime energy assets. Qingdao and Shanghai concentrate domestic sensor manufacturing and system integration capacity for South China Sea deployments.
Offshore Remote Monitoring Solutions Market Competitive Landscape
North American industrial conglomerates anchor one tier; European engineering specialists hold differentiated positions in subsea and maritime applications. Market structure tilts toward consolidated platform providers capable of delivering integrated sensor, edge, and cloud architectures under single accountability. Three archetypes dominate: diversified automation multinationals, subsea technology pure-plays, and energy service integrators. Competitive moves concentrate on strategic partnerships for floating wind qualification and portfolio diversification into hydrogen platform monitoring.
Within the diversified automation tier, Honeywell International Inc. and Siemens AG exemplify integrated platform providers spanning industrial software and hardware domains. Emerson Electric Co. occupies a position among sensor-to-cloud specialists with captive analytics development. These three entities represent the consolidation vector as asset owners compress vendor relationships around unified service agreements.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Emerson Electric Co. |
| Schneider Electric SE |
| ABB Ltd. |
| National Oilwell Varco |
| Kongsberg Gruppen |
| Schlumberger Limited |
| Subsea 7 S.A. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EU Green Deal-compliant platforms and legacy monitoring systems manifests in both pricing premiums and supplier qualification requirements. Buyers face tiered procurement economics where functional safety certification from Norway's Petroleum Safety Authority or the UK's Health and Safety Executive commands substantial hardware and integration premiums, while non-certified alternatives face exclusion from North Sea project pipelines.
Pricing Analysis
Volume concentrates in commoditized IoT sensor networks while margins accrue to AI-driven predictive maintenance platforms. Pricing stratifies across premium-certified, standard-compliant, and economy-tier monitoring systems based on functional safety certification level and after-sales service bundling. Cost compression in sensor hardware is intensifying because titanium and super-duplex stainless steel commodity volatility erodes manufacturer margins. Renewable energy developers exhibit the highest price sensitivity as they scale fleet deployments, whereas oil and gas operators prioritize reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by North Sea operators for critical subsea components constrain procurement flexibility and extend vendor qualification timelines. Fiber-optic umbilical manufacturing concentrates in Norway and the United Kingdom, while titanium alloy processing and edge-computing semiconductor fabrication draw from specialized suppliers in Germany and the United States. Single-source vulnerability in corrosion-resistant alloy supply creates exposure to nickel and molybdenum price swings. Distribution runs through system integrators in Aberdeen, Stavanger, and Bremerhaven who coordinate multi-vendor platform assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in offshore remote monitoring solutions is becoming a vertical-integration race, with control over sensor hardware fabrication and captive edge-computing development determining margin capture.
For Market Incumbents: Anticipate displacement pressure from integrated platform specialists by securing captive supply of titanium sensor housings and super-duplex stainless steel components. Consolidate vendor relationships around unified service agreements that bundle hardware warranty with predictive analytics subscriptions. Functional safety certification investment represents the priority defensive lever against non-compliant competitors. For New Entrants and Emerging Players: AI-first anomaly detection algorithms offer entry leverage into floating offshore wind monitoring where maintenance vessel access constraints inflate downtime costs. White-space targets include hydrogen platform electrolyzer monitoring and carbon capture and storage seismic sensing applications. Partnerships with established subsea robotics service providers in Bergen or Aberdeen accelerate credibility building. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-to-cloud platform specialists given EU AI Act documentation requirements and CSRD-aligned data services demand. Long-term viability favors vendors with demonstrated floating wind qualification and backward integration into corrosion-resistant alloy supply. The signal to watch is contract award velocity for North Sea floating foundation deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Hardware Backward Integration | Captive titanium alloy supply insulates margin from commodity volatility in Norwegian manufacturing. |
| Floating Wind Qualification Partnership | Joint development with Equinor or Aker BP accelerates certification for deeper-water turbine monitoring. |
| EU AI Act Technical File Investment | Documentation repositories enable automated diagnostic algorithm deployment in safety-critical applications. |
| Hydrogen Platform Sensor Development | Pressure and purity monitoring capabilities extend addressable market into North Sea electrolyzer installations. |
| CSRD-Aligned Data Service Launch | Emissions verification analytics subscriptions capture recurring revenue from German offshore wind developers. |
Research Methodology
Independent corroboration across offshore wind farm operators, subsea robotics technicians, and system integration engineers underwrites the qualitative findings in this study. Primary interviews with asset managers at Equinor and Aker BP, procurement leads at German offshore wind developers, and platform engineers at Kongsberg Gruppen combined with secondary validation from EU Green Deal regulatory filings, Petroleum Safety Authority safety notices, and Health and Safety Executive equipment certification databases. Bottom-up deployment estimates and top-down market sizing triangulate volume figures across the analysis window.
Rate-of-change decomposition separates technology adoption velocity from end-user expansion patterns and regulatory compliance deadlines across the projection horizon. The analytical framework models segmentation across IoT, AI, cloud computing, and big data technology tiers; data analysis, predictive maintenance, system integration, and cybersecurity service types; oil and gas, maritime, renewable energy, and utilities end users; and on-premise, cloud-based, hybrid, and edge computing deployment architectures. CAGRs derive from installer capacity buildout schedules and functional safety mandate implementation timelines.
Several conditions sit outside the modeled scope, including unannounced REACH substance restriction amendments, abrupt nickel and molybdenum commodity price dislocations, and geopolitical disruption of subsea cable manufacturing. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency and floating offshore wind project financing availability. Deviation in subsea robotics technician training pipeline output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market