
 United Arab Emirates Oil and Gas Upstream Market | 2026-2036
United Arab Emirates Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Oil and Gas Upstream Market Analytics
Multi-source contracting for drilling services is recalibrating procurement patterns across UAE offshore blocks. Abu Dhabi National Oil Company (ADNOC) leverages its integrated drilling subsidiary to retain operational control over major fields. TotalEnergies SE competes through deepwater exploration partnerships in Lower Zakum and Umm Shaif. BP PLC specializes in sour gas extraction technologies at the Shah field development.
United Arab Emirates Oil and Gas Upstream encompasses exploration, drilling, production, and development activities targeting hydrocarbon reservoirs beneath UAE territorial waters and onshore concessions, typically operating at reservoir depths exceeding 2,000 meters with bottom-hole temperatures surpassing 150°C. The sector serves domestic power generation, industrial feedstock supply, and export-oriented liquefied natural gas production. Enhanced Oil Recovery technology commands substantial capital allocation as mature fields require pressure maintenance and tertiary extraction methods to sustain plateau output. Offshore Platforms represent the most capital-intensive production category, with subsea tieback systems gaining preference for marginal field developments. Conventional production methods still dominate UAE barrel volumes, though Gas-to-Liquids processing capacity is expanding at Ruwais industrial complex.
MOHAP oversees occupational health standards across upstream installations, while ADNOC's technical specifications enforce well integrity and emissions thresholds that shape contractor qualification requirements. The country's national petroleum regulator coordinates concession terms and production quotas that determine field development sequencing. Stakeholders must monitor sour gas capacity expansions and carbon capture integration mandates that will reshape project economics and partnership structures.
Market Dynamics
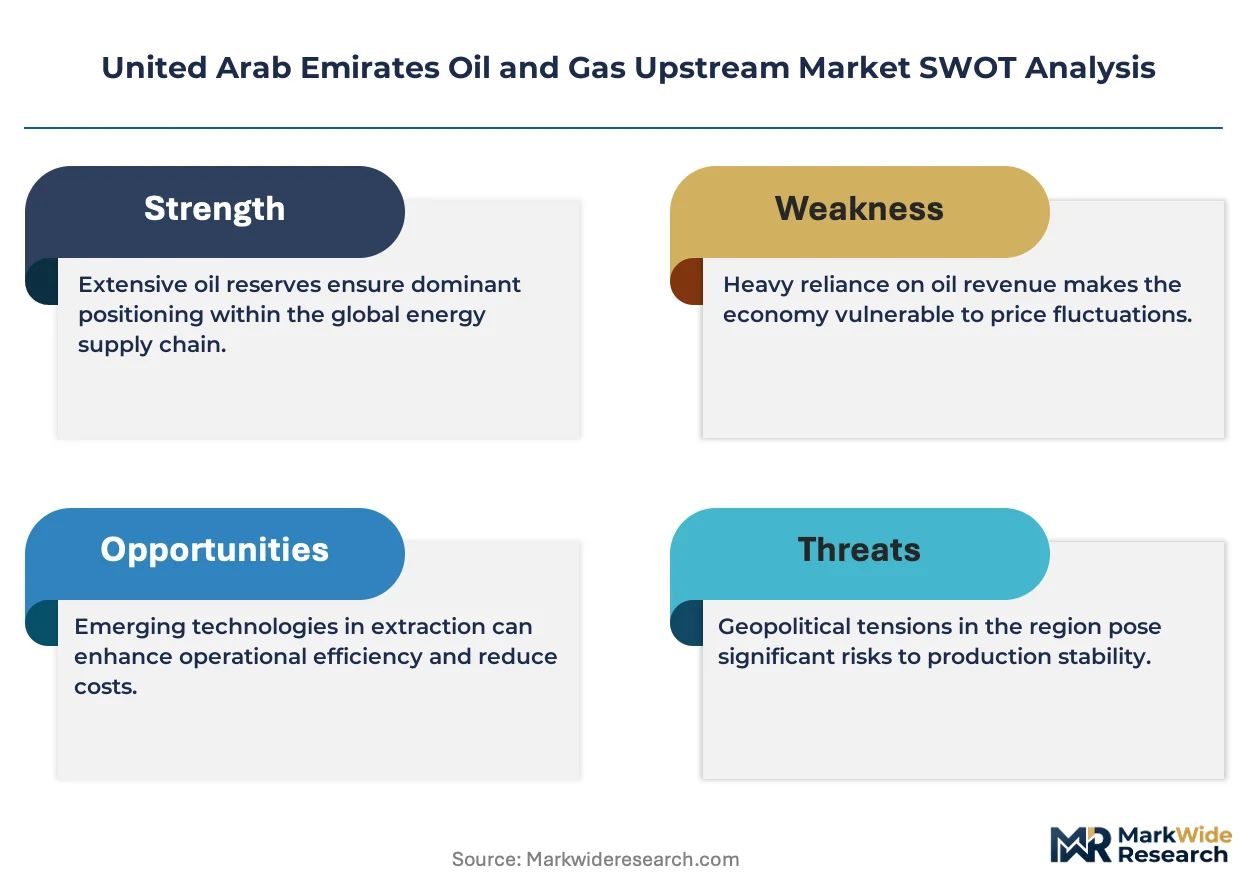
ADNOC's accelerated sour gas development programs are recalibrating capital allocation across UAE upstream operations, forcing contractors to demonstrate enhanced recovery capabilities and carbon capture integration at reservoir depths exceeding 2,000 meters.
Growth Catalysts
- Enhanced Oil Recovery Mandates:ADNOC's technical specifications now require tertiary extraction methods for mature fields, creating sustained demand for pressure maintenance systems and thermal recovery units.
- Power Generation Expansion:Domestic utilities are expanding offtake from offshore fields, anchoring production plateau targets and justifying infrastructure investments at Umm Shaif and Lower Zakum.
- Lower Zakum Deepwater Licensing:Abu Dhabi emirate's concentrated exploration licensing rounds are attracting international partners with subsea tieback expertise for marginal field developments.
Market Restraints
- Sour Gas Processing Costs:Hydrogen sulfide removal requirements at Shah field and associated fields impose capital-intensive amine treatment systems that compress project returns.
- Specialized Equipment Concentration:High-pressure high-temperature drilling equipment suppliers cluster in Houston and Aberdeen, creating supply bottlenecks for UAE offshore campaigns.
- Reservoir Complexity:Bottom-hole temperatures surpassing 150°C limit conventional completion technologies, forcing extended qualification timelines for downhole tools.
Strategic Opportunities
- Carbon Capture Integration:ADNOC's emissions thresholds and MOHAP occupational standards are creating bundled procurement for CO2 compression and sequestration alongside production facilities.
- Ruwais Gas-to-Liquids Expansion:Industrial feedstock demand at the Ruwais complex is expanding processing capacity, opening offtake agreements for associated gas from offshore platforms.
- Artificial Lift Convergence:Electrical submersible pump manufacturers are integrating permanent magnet motor technology with real-time monitoring systems, reducing intervention frequency in high-temperature wells.
Industry Challenges
- High-Pressure Well Integrity Certification:ADNOC's technical specifications for sour service metallurgy require extended qualification cycles that delay first production from new drills.
- Subsea Installation Vessel Availability:Heavy-lift capacity for platform installations concentrates with a limited contractor pool, compressing project windows around weather-sensitive seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Oil and Gas Upstream Market |
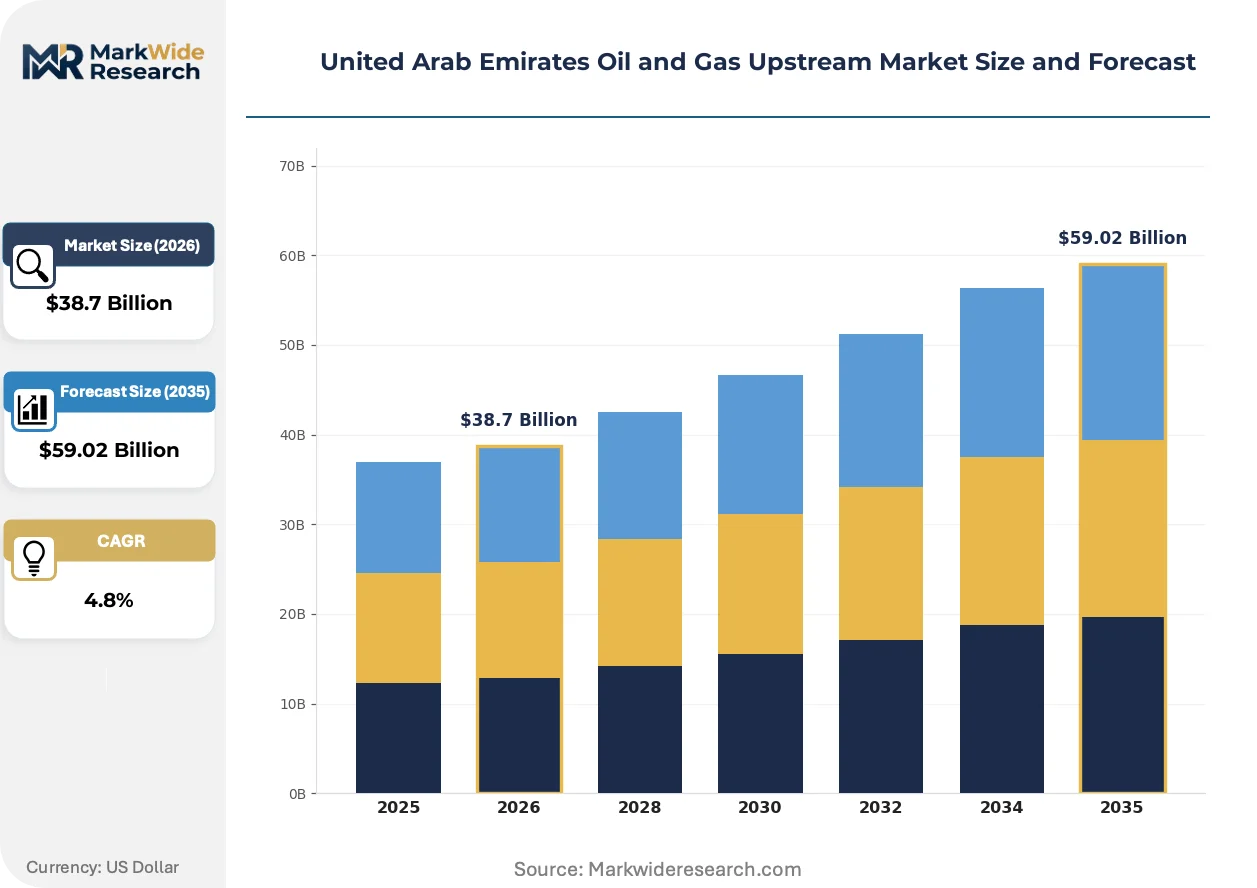
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Development Technology: Artificial Lift, Enhanced Oil Recovery, Subsea Systems, Offshore Platforms Production Method: Conventional, Unconventional, Gas-to-Liquids, Oil Sands End User: Independent Operators, State-Owned Entities, Contractors, Supply Chain Providers |
| Companies Covered | Exxon Mobil Corporation, Occidental Petroleum Corp, Abu Dhabi National Oil Company (ADNOC), China National Petroleum Corp (CNPC), INPEX Corp, TotalEnergies SE, ENI SpA, China Petroleum & Chemical Corp (Sinopec), BP PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Oil and Gas Upstream Market Evolving Landscape
Digital reservoir characterization and autonomous drilling systems are displacing conventional interpretation workflows across UAE offshore concessions, compressing decision cycles from months to weeks.
Managed pressure drilling technology is expanding into high-pressure carbonate formations beneath Abu Dhabi territorial waters. ADNOC Drilling deploys these systems across major fields to maintain constant bottom-hole pressure and eliminate lost circulation events. The technology is expanding into marginal field developments previously deemed uneconomic due to narrow drilling windows.
MOHAP occupational health standards now mandate real-time exposure monitoring for hydrogen sulfide at all sour gas facilities. The regulation forces integration of wearable sensors with centralized safety systems, accelerating procurement of connected worker platforms. Offshore platforms face the steepest compliance timelines due to evacuation complexity.
Integrated service contracting is displacing discrete equipment procurement across UAE upstream operations. Operators now bundle drilling, completion, and artificial lift services under single accountability structures, compressing vendor management overhead. Abu Dhabi emirate's largest fields show the most pronounced shift, with ADNOC favoring partners offering full-field development responsibility.
United Arab Emirates Oil and Gas Upstream Market Segmentation
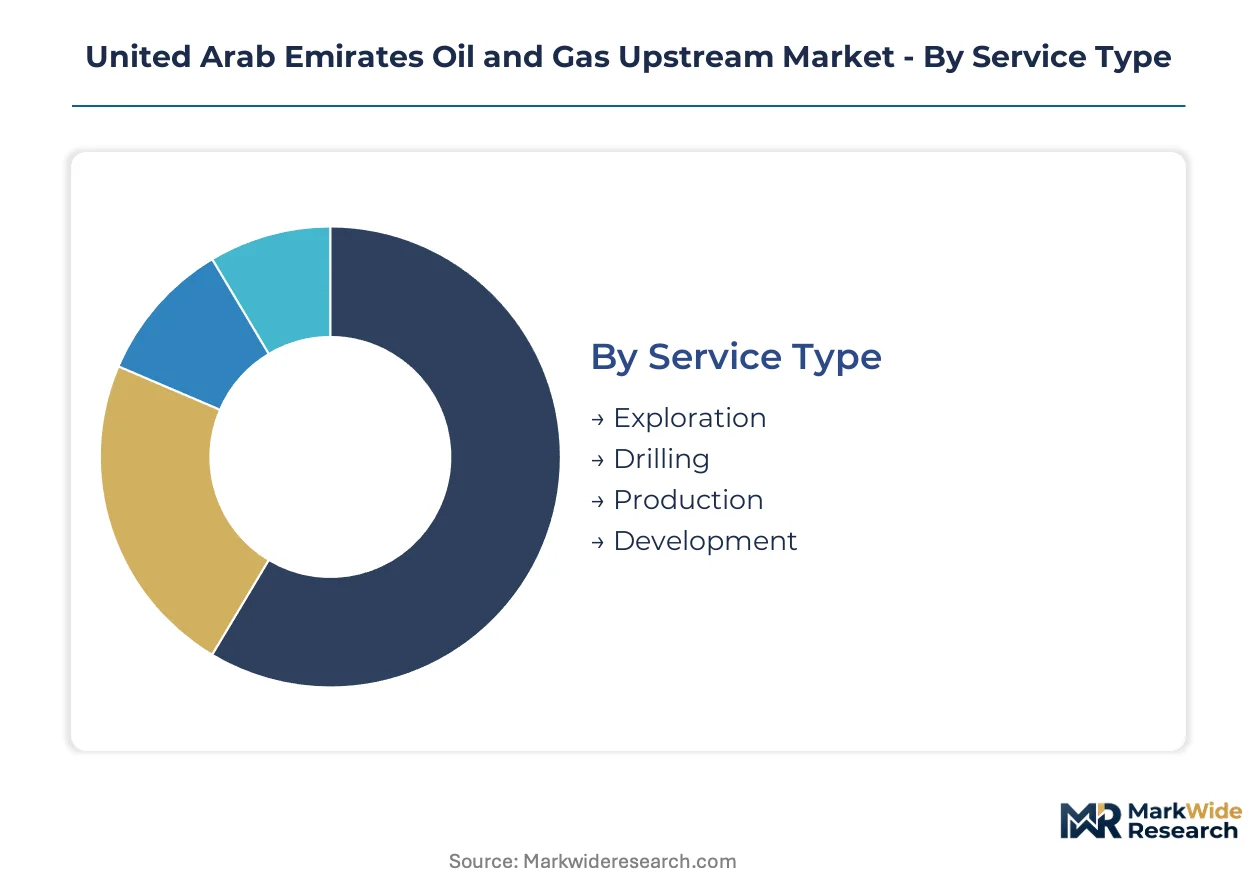
UAE upstream segmentation reveals capital allocation priorities across four operational dimensions. Each category carries distinct procurement patterns and contractor qualification requirements tied to ADNOC's technical specifications.
Service Type:
Capital intensity varies sharply across the service spectrum, with development and production commanding the largest upfront commitments relative to exploration.
- Development:Field infrastructure deployment including well completion, surface facilities, and tie-in systems absorbs sustained capital allocation. ADNOC's sour gas expansion programs concentrate demand here, particularly at Shah field and associated high-pressure carbonate formations.
- Drilling:Managed pressure drilling systems and high-temperature completion technologies dominate procurement. ADNOC Drilling retains operational control over major fields, while international partners compete through deepwater exploration partnerships.
- Production:Sustained demand for pressure maintenance systems and tertiary extraction methods at mature fields. Enhanced recovery mandates from ADNOC's technical specifications shape contractor selection.
- Exploration:Seismic acquisition and appraisal drilling in Abu Dhabi emirate licensing rounds. Lower Zakum deepwater blocks attract partners with subsea tieback expertise.
Development absorbs the bulk of installed capacity; drilling is expanding most quickly.
Technology:
Technology selection tracks reservoir complexity, with high-pressure high-temperature applications driving premium procurement tiers.
- Enhanced Oil Recovery:Tertiary extraction methods including thermal recovery and chemical flooding dominate mature field economics. ADNOC mandates pressure maintenance systems for fields exceeding 2,000 meter depths with bottom-hole temperatures surpassing 150°C.
- Offshore Platforms:Fixed and floating production facilities represent the most capital-intensive category. Subsea tieback systems gain preference for marginal field developments at Umm Shaif and Lower Zakum.
- Artificial Lift:Electrical submersible pumps with permanent magnet motor technology reduce intervention frequency. Real-time monitoring integration addresses MOHAP occupational standards for high-temperature wells.
- Subsea Systems:Subsea tieback expertise opens marginal fields previously deemed uneconomic. Heavy-lift installation vessel availability constrains deployment windows around weather-sensitive seasons.
Offshore platforms absorb the bulk of installed capacity; enhanced oil recovery is climbing the fastest.
Production Method:
Production method segmentation reflects feedstock destination, with Ruwais industrial complex offtake agreements shaping associated gas processing priorities.
- Conventional:Dominant barrel volume source across UAE territorial waters. Standard well completion and surface processing equipment meets baseline ADNOC technical specifications.
- Gas-to-Liquids:Expanding processing capacity at Ruwais industrial complex creates dedicated offtake demand. Associated gas from offshore platforms feeds synthetic fuel production.
- Unconventional:Tight gas and shale applications remain limited in UAE geology. High-pressure fracturing equipment suppliers cluster outside the region, creating procurement bottlenecks.
- Oil Sands:Minimal relevance to UAE reservoir characteristics. Thermal extraction methods find no commercial application in Abu Dhabi carbonate formations.
Conventional methods absorb the bulk of installed capacity; gas-to-liquids is gaining share fastest.
End User:
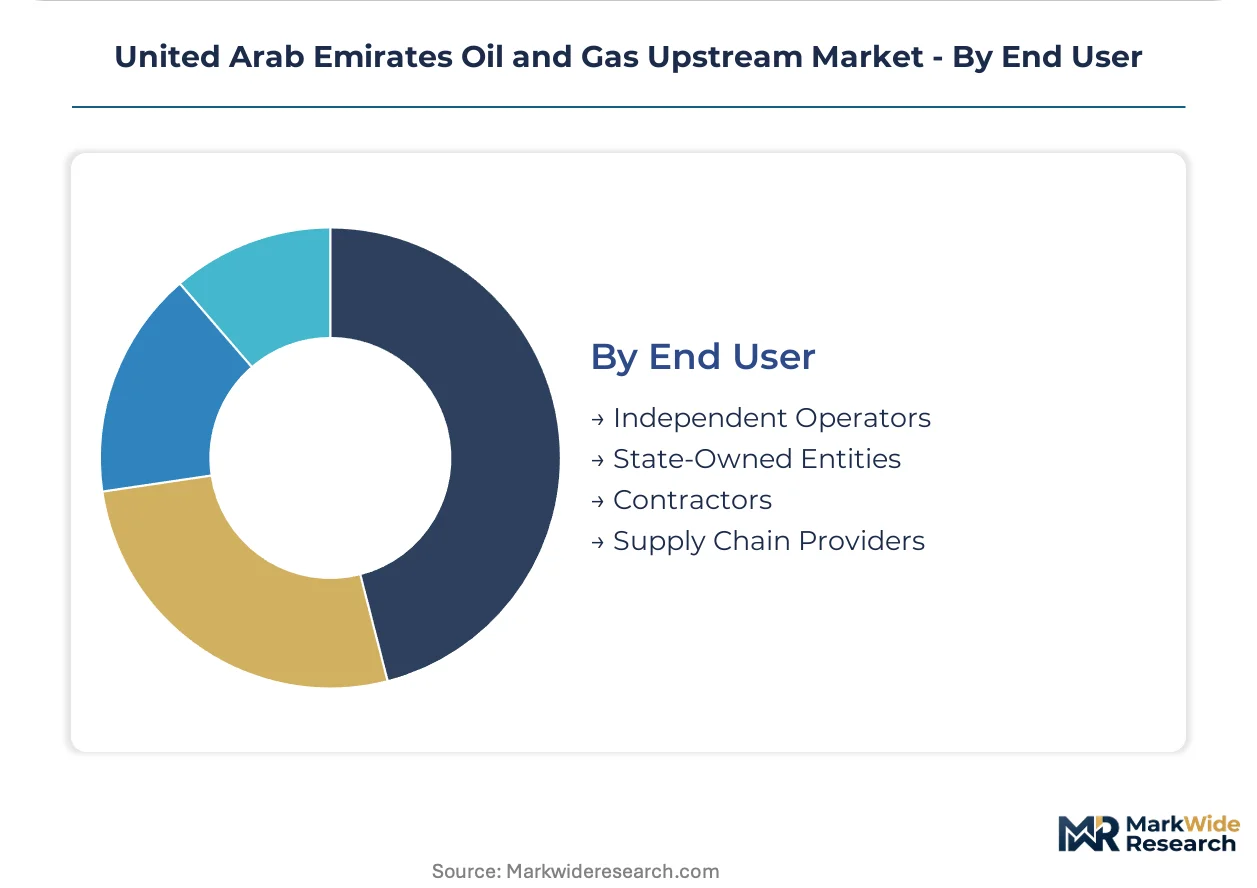
End user segmentation reveals contracting authority concentration, with procurement patterns shifting toward bundled service accountability.
- State-Owned Entities:ADNOC controls concession terms and production quotas determining field development sequencing. Integrated drilling subsidiary retains operational control over major fields.
- Contractors:International drilling and completion service providers compete through multi-source contracting arrangements. Full-field development responsibility increasingly determines partner selection.
- Independent Operators:Limited presence in Abu Dhabi emirate's concentrated licensing structure. Marginal field developments offer entry points for specialized subsea operators.
- Supply Chain Providers:High-pressure high-temperature equipment suppliers face extended qualification timelines. Houston and Aberdeen manufacturing clusters create supply bottlenecks for offshore campaigns.
State-owned entities absorb the bulk of installed capacity; contractors are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi emirate anchors UAE upstream capacity through carbonate reservoirs beneath the Arabian Gulf. Dubai and Sharjah maintain secondary processing infrastructure. Northern Emirates contain limited exploratory acreage.
Abu Dhabi
ADNOC controls concession sequencing across Upper Zakum, Lower Zakum, and Umm Shaif fields. MOHAP enforces hydrogen sulfide exposure limits at sour gas facilities. The Ruwais industrial complex processes associated gas into synthetic fuels and chemical feedstocks.
Dubai
Fateh field production supplies domestic desalination and power generation utilities. Dubai Petroleum Establishment operates under emirate-level regulatory frameworks distinct from federal ADNOC oversight. Jebel Ali port serves as the primary logistics hub for offshore drilling equipment imports.
Sharjah
Onshore tight gas developments at Sajaa and Kahaif fields expand unconventional production. The emirate's petroleum council licenses blocks to international partners with hydraulic fracturing expertise. Hamriyah Free Zone hosts service company regional headquarters.
Northern Emirates
Ras Al Khaimah and Fujairah hold frontier exploration acreage with limited seismic coverage. Federal energy regulations coordinate licensing terms across these less-developed blocks. Fujairah's strategic location outside the Strait of Hormuz supports crude oil storage and export diversification.
United Arab Emirates Oil and Gas Upstream Market Competitive Landscape
Global majors compete with regional champions across concession partnerships and technology provision. ADNOC retains operational control through integrated subsidiaries while international partners contribute deepwater and sour gas expertise. Three archetypes dominate: state-backed national champions, integrated supermajors with carbonate specialization, and niche subsea technology providers. Partnership restructuring and integrated service contracting represent the primary competitive vectors reshaping vendor relationships.
Among state-backed entities, Abu Dhabi National Oil Company anchors domestic capacity and concession authority. Exxon Mobil Corporation and TotalEnergies SE exemplify the supermajor tier competing through deepwater exploration partnerships. BP PLC occupies a specialized position in sour gas extraction technologies at high-pressure carbonate formations.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Occidental Petroleum Corp |
| Abu Dhabi National Oil Company (ADNOC) |
| China National Petroleum Corp (CNPC) |
| INPEX Corp |
| TotalEnergies SE |
| ENI SpA |
| China Petroleum & Chemical Corp (Sinopec) |
| BP PLC |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers like ADNOC anchor procurement discipline through integrated drilling subsidiaries, concentrating supply negotiations around long-term offtake frameworks that compress contractor margins while securing operational control over Shah field and Lower Zakum developments. This ownership pattern feeds into pricing structures where bundled service accountability displaces discrete equipment procurement, forcing international partners to absorb carbon capture integration costs within development contracts.
Pricing Analysis
Warranty and service bundling separates integrated field development packages from unbundled drilling equipment procurement, with ADNOC's technical specifications mandating extended qualification cycles that inflate upfront costs. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade for sour service metallurgy and bottom-hole temperature ratings. Pricing pressure stems from multi-source contracting arrangements that force drilling service providers to compete on full-field development responsibility rather than equipment alone. National oil companies show least price sensitivity due to strategic energy security mandates, while independent subsea operators face acute margin compression on marginal field tieback projects.
Supply Chain Analysis
Reverse-logistics flows for high-pressure drilling equipment concentrate refurbishment activity in Houston and Aberdeen, creating secondary supply nodes for UAE offshore campaigns. Manufacturing clusters in the United States, United Kingdom, and Singapore anchor production of managed pressure drilling systems and high-temperature completion technologies. Raw material dependencies center on specialized alloy steel, permanent magnet motors, and amine treatment chemicals for hydrogen sulfide removal. Single-source vulnerability runs through heavy-lift installation vessel availability, which compresses project windows around weather-sensitive seasons. Distribution runs through Jebel Ali port for equipment imports and Ruwais industrial complex for processed feedstock offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where ADNOC's accelerated sour gas mandates and carbon capture integration requirements force weaker contractors without full-field development capabilities toward exit or acquisition.
For Market Incumbents: Cement operational control through backward integration into artificial lift manufacturing and subsea installation vessel partnerships, insulating against margin erosion from bundled procurement mandates. Deepen captive supply of high-temperature completion technologies to reduce qualification timelines that delay first production. Prioritize certification investment for MOHAP hydrogen sulfide exposure compliance to secure offshore platform contracts with steep compliance deadlines. For New Entrants and Emerging Players: Launch via specialized subsea tieback expertise targeting marginal field developments at Lower Zakum and Northern Emirates frontier blocks where ADNOC seeks partners with narrow drilling window capabilities. Target the independent operator segment in Sharjah tight gas developments where hydraulic fracturing expertise opens licensing opportunities outside ADNOC's direct control. Pursue channel partnerships with Hamriyah Free Zone service company clusters to establish regional headquarters without concession bidding overhead. For Investors and Strategic Acquirers: Distressed-cycle entries favor niche subsea technology providers with permanent magnet motor integration capabilities in Abu Dhabi emirate, where artificial lift convergence creates acquisition premiums. Long-term viability centers on contractors capable of bundling carbon capture compression with production facilities across the analysis window. Watch for inflection signals in ADNOC's concession term restructuring that favors integrated service accountability over discrete equipment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Bundled drilling, completion, and artificial lift accountability compresses vendor management overhead at ADNOC's largest fields. |
| Carbon Capture Integration | CO2 compression and sequestration procurement bundled with production facilities reshapes project economics at Shah field. |
| Subsea Tieback Expansion | Marginal field developments at Umm Shaif and Lower Zakum open revenue streams for specialized installation contractors. |
| Gas-to-Liquids Capacity Buildout | Ruwais industrial complex expansion creates dedicated offtake demand for associated gas from offshore platforms. |
| Managed Pressure Drilling Deployment | High-pressure carbonate formation access eliminates lost circulation events and extends economic reach into marginal blocks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drilling operations managers, subsea project engineers, EPC procurement leads, and MOHAP compliance officers. ADNOC technical specifications, MOHAP occupational health standards, and Abu Dhabi petroleum council licensing terms provided regulatory validation. Bottom-up field-level production data and top-down emirate capacity assessments underwent cross-referencing against IEA upstream investment databases and customs import records for high-pressure equipment.
Data-stream reconciliation across service type, technology, production method, and end user dimensions generated volume and value outputs throughout the forecast period. Segmentation modeling incorporated reservoir depth tiers, sour gas processing requirements, and carbon capture integration mandates as industry-specific forecast inputs. CAGRs derived from production plateau targets, licensing round sequencing, and infrastructure deployment timelines reported by state-owned entities and concession partners.
The model assumes a particular technology adoption path; alternative pathways for autonomous drilling systems and digital reservoir characterization would alter the outlook if deployment accelerates beyond managed pressure drilling expansion timelines. Forecasts reflect assumptions regarding ADNOC's concession restructuring pace and international partner retention through sour gas development phases. Practitioners should monitor heavy-lift vessel availability constraints and hydrogen sulfide exposure regulation tightening for early signals of supply bottleneck intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market