
 Offshore Decommissioning Services Market | 2026-2036
Offshore Decommissioning Services Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Decommissioning Services Market Analytics
Market Context
The gap between integrated full-service contracts and single-scope commodity bids is repositioning how operators procure decommissioning work. Heerema Marine Contractors leverages its fleet of heavy-lift vessels to dominate platform removal in the North Sea. Aker Solutions ASA anchors its competitiveness through specialized well plugging and abandonment engineering capabilities.
Technical Definition and Segments
Offshore decommissioning services encompass the engineered dismantlement, removal, and environmental remediation of subsea production systems, fixed and floating platforms, and associated pipeline networks, typically involving cutting operations at depths exceeding 100 meters using explosive or mechanical severing methods. Well plugging commands the largest share of project value due to regulatory mandates for permanent zonal isolation, while robotics represents the fastest-expanding technology category as operators deploy autonomous underwater vehicles for seabed surveys and cutting operations in deep water deployments where diver access proves impractical.
Regulatory Outlook
OSPAR Decision 98/3 and BSEE regulations in the United States govern platform removal and site clearance standards, with compliance costs directly shaping contractor selection criteria and technology investment priorities. The UK's Petroleum Act and associated decommissioning security agreements enforce financial liability timelines that accelerate project scheduling and capital allocation decisions. Stakeholders must monitor how evolving carbon accounting rules and circular economy mandates for material recovery reshape contract scopes and equipment specifications.
Market Dynamics
The North Sea's accelerating platform retirement wave is compressing contractor availability and forcing operators into multi-year booking commitments for heavy-lift vessel capacity.
Growth Catalysts
- OSPAR Decision 98/3:The complete removal mandate for steel jacket structures in the Northeast Atlantic is extending project scopes beyond topside recovery to full seabed clearance.
- Subsea robotics:Autonomous underwater vehicles with diamond wire cutting capabilities are unlocking deepwater decommissioning in the Gulf of Mexico previously classified as uneconomic.
- UK tax relief:Petroleum Revenue Tax abolition and decommissioning expenditure relief are improving project net present value for marginal field operators.
Market Restraints
- Heavy-lift vessel scarcity:The global fleet of semi-submersible crane vessels capable of single-lift platform removal numbers fewer than twelve units, creating booking bottlenecks.
- Specialized steel grades:S355 and S420 offshore structural steels require controlled cutting environments that limit contractor pool and extend mobilization timelines.
- BSEE financial assurance:Decommissioning bond requirements for US outer continental shelf operators are trapping capital and constraining portfolio restructuring flexibility.
Strategic Opportunities
- Floating production decommissioning:Brazil's pre-salt FPSO fleet approaching design life end represents a fifteen-year demand runway for integrated mooring and hull removal services.
- Circular economy mandates:EU Waste Framework Directive material recovery targets are creating premium pricing for contractors with onshore dismantlement and steel reprocessing capabilities.
- Well P&A technology convergence:Rigless abandonment systems combining coiled tubing and wireline interventions are opening subsea well plug markets to lower-tier service providers.
Industry Challenges
- Diver-qualified welder shortage:Commercial saturation diving certification programs in the UK and Norway are producing insufficient replacement capacity for an aging workforce.
- Legacy documentation gaps:Platform as-built drawings from the 1970s and 1980s often lack seabed stability data, forcing costly pre-removal geotechnical surveys.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Decommissioning Services Market |
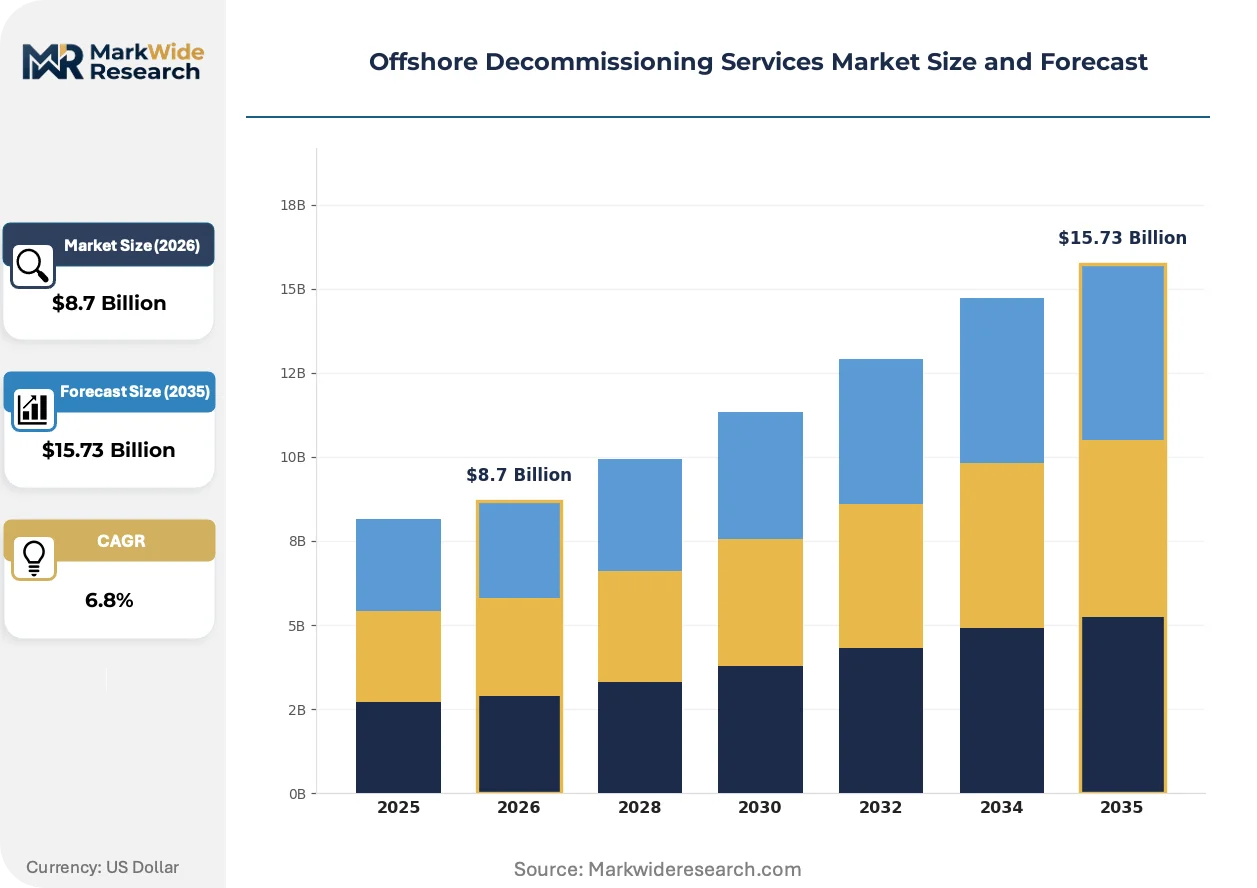
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Well Plugging, Platform Removal, Pipeline Decommissioning, Site Clearance Technology: Mechanical, Chemical, Hybrid, Robotics End User: Oil Companies, Government Agencies, Environmental Organizations, Contractors Deployment: Onshore, Offshore, Inland Waters, Deep Water |
| Companies Covered | TechnipFMC PLC, Heerema Marine Contractors, Allseas Group SA, Saipem SpA, Subsea 7 SA, Boskalis Westminster NV, Aker Solutions ASA, Petrofac Ltd, DEME Offshore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Decommissioning Services Market Evolving Landscape
Robotic systems are displacing human intervention in hazardous subsea environments while regulatory pressure on marine ecosystems accelerates precision cutting requirements.
Diamond wire cutting technology is rewriting execution economics for jacket severing operations. North Sea operators facing complete removal mandates under OSPAR are adopting this method for controlled pile cutting at mudline without explosive charges. The technology is compressing project schedules from seasonal weather windows to year-round operations.
REACH restrictions on hexavalent chromium coatings are forcing coating removal process redesign across European decommissioning yards. Industrial consequence includes mandatory containment systems for abrasive blasting operations. UK and Norwegian dismantlement facilities are investing in closed-loop water treatment to maintain accreditation.
Integrated service contracting is displacing fragmented procurement of well abandonment, platform removal, and site clearance scopes. Major operators in the UK Central North Sea are bundling decade-long decommissioning programs under single accountability structures. This consolidation is most visible among supermajors with multi-asset late-life portfolios.
Offshore Decommissioning Services Market Segmentation
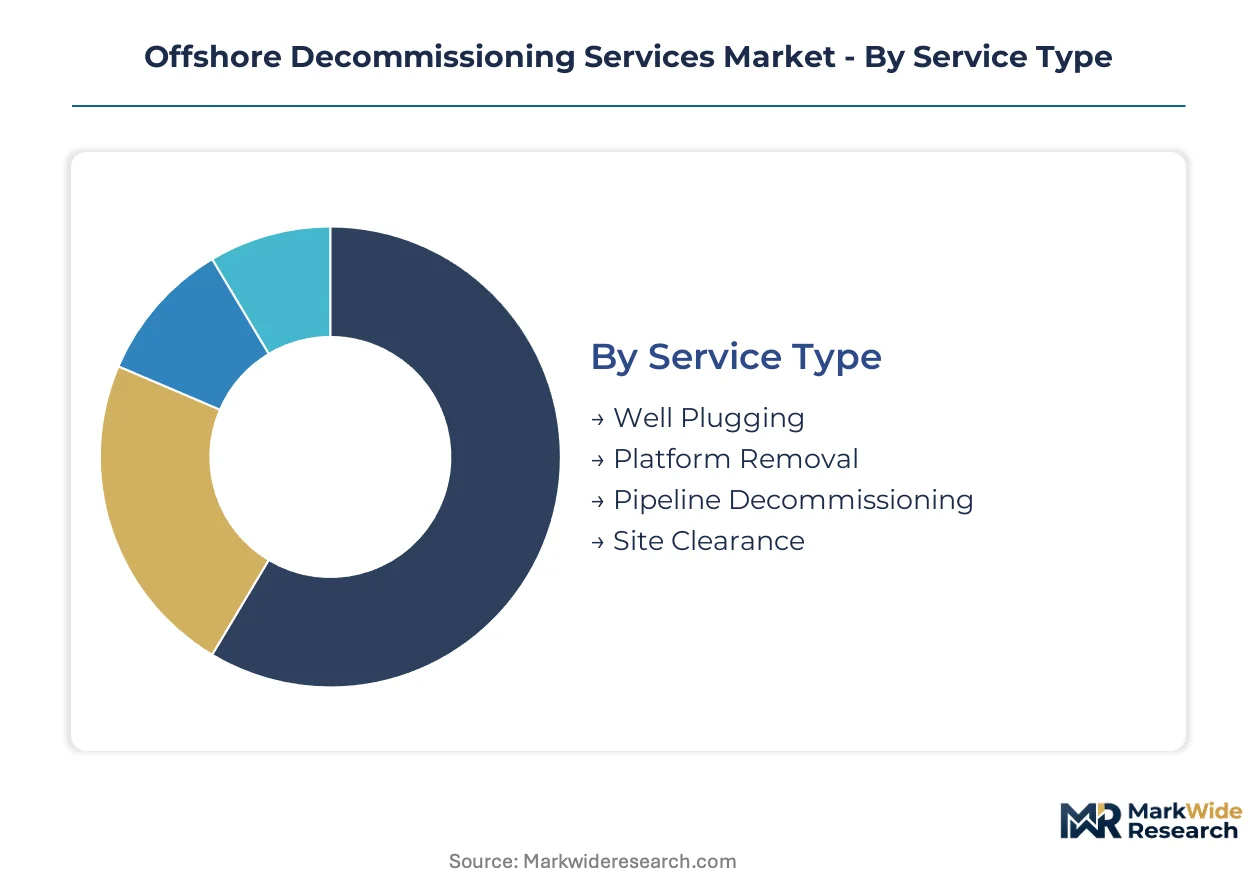
Decommissioning procurement patterns diverge sharply between integrated full-field programs and discrete scope contracts. Technology selection across service types determines contractor qualification tiers and capital intensity requirements.
Service Type:
Mechanical severing capabilities and permanent zonal isolation specifications define contractor eligibility for each service category.
- Well Plugging:Cement and mechanical barrier systems achieve permanent reservoir isolation across multiple geological zones. UK North Sea operators bundle well P&A into decade-long framework agreements due to Petroleum Act liability timelines.
- Platform Removal:Single-lift heavy-lift operations and piece-small dismantlement methods compete based on jacket weight and seabed conditions. Gulf of Mexico fixed platform retirements are compressing semi-submersible crane vessel availability into multi-year booking windows.
- Pipeline Decommissioning:Subsea pipeline flushing, cutting, and burial or removal per OSPAR and BSEE standards.
- Site Clearance:Seabed debris removal and verification surveying for regulatory sign-off.
Mature deployment sits with Well Plugging. Newer deployment is concentrated in Platform Removal.
Technology:
Cost tier separation between diver-dependent and diverless systems is accelerating contractor capability investments.
- Mechanical:Diamond wire cutting and abrasive water jet systems sever steel piles and conductors without explosive charges. North Sea operators facing OSPAR complete removal mandates are adopting this method for year-round mudline cutting operations.
- Robotics:Autonomous underwater vehicles with manipulator arms and cutting tools execute subsea interventions without saturation diving. Deep water Gulf of Mexico decommissioning previously classified as uneconomic is now accessible through robotic deployment.
- Chemical:Thermite cutting and chemical severing methods for specific metallurgical constraints.
- Hybrid:Combined mechanical-robotic systems integrating surface vessel control with subsea automation.
Mechanical systems dominate current project volumes. Robotics deployment is expanding most quickly into frontier water depths.
End User:
Customer type determines risk allocation structures and contracting complexity.
- Oil Companies:Supermajors and independents holding field equity bear decommissioning liability under joint operating agreements. UK marginal field operators are accelerating retirement schedules following Petroleum Revenue Tax abolition and decommissioning expenditure relief improvements.
- Government Agencies:National oil companies and energy ministries in Brazil and Mexico are building captive decommissioning capabilities for pre-salt FPSO fleets approaching design life.
- Environmental Organizations:NGOs monitoring OSPAR compliance and marine ecosystem remediation outcomes.
- Contractors:Service companies subcontracting specialized scopes from lead operators.
Oil Companies retain the dominant procurement role. Government Agency direct contracting is gaining share in Latin American markets.
Deployment:
Water depth classification dictates technology selection and regulatory jurisdiction.
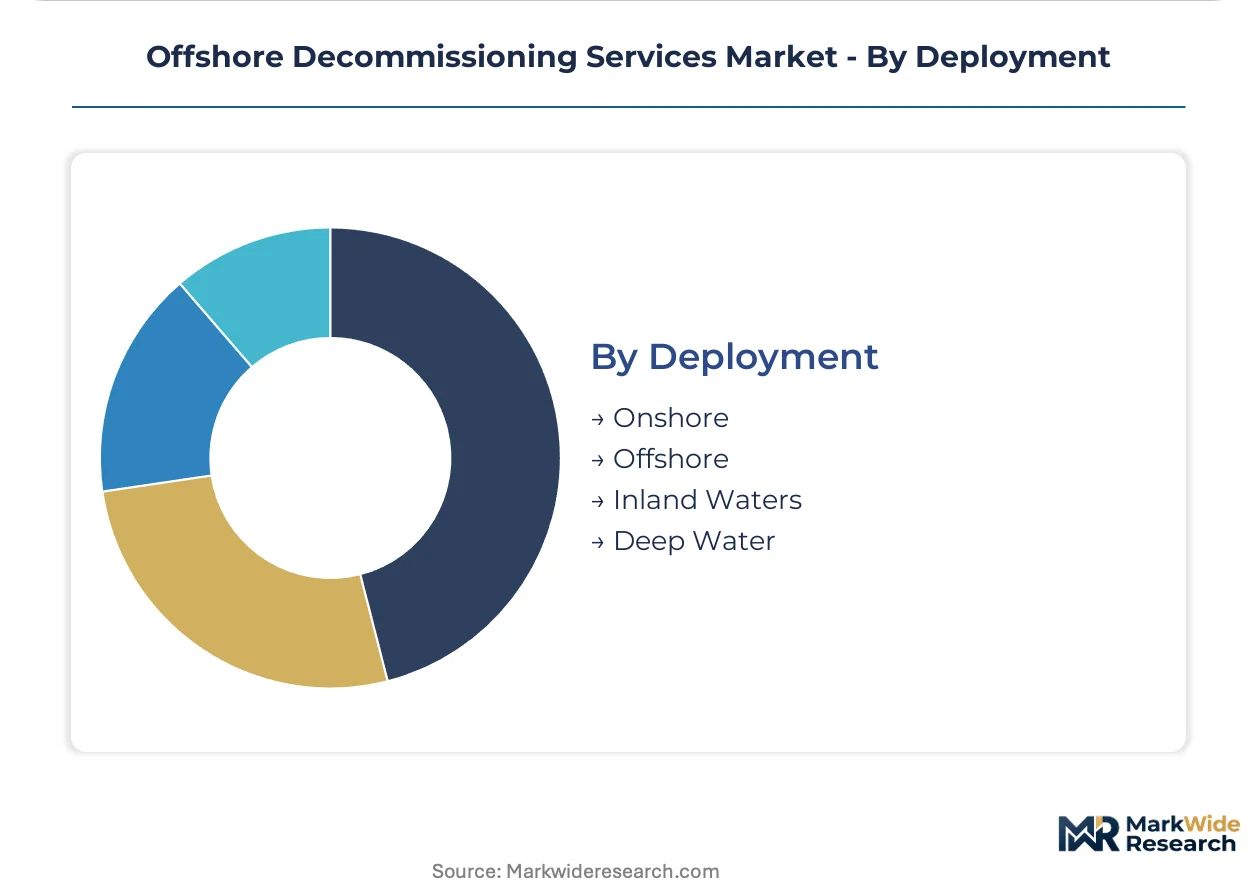
- Offshore:Continental shelf decommissioning in 100-500 meter depths constitutes the core revenue base. UK and Norwegian North Sea platforms dominate current activity volumes with OSPAR-mandated complete removal programs.
- Deep Water:Subsea production system decommissioning below 500 meters requires robotic and remotely operated vehicle intervention. Brazil's pre-salt FPSO fleet approaching design life end represents a fifteen-year demand runway for integrated mooring and hull removal services.
- Onshore:Yard-based platform dismantlement and material reprocessing under EU Waste Framework Directive circular economy mandates.
- Inland Waters:Lake and coastal decommissioning with modified equipment specifications.
Offshore deployment commands current contractor capacity. Deep Water activity shows the steepest expansion trajectory as pre-salt fields mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aberdeen anchors the global decommissioning services trade, hosting the densest concentration of engineering consultancies and heavy-lift vessel operators serving North Sea platform retirements. The city's cluster feeds directly into UK Continental Shelf abandonment programs worth billions in contracted value annually.
United Kingdom
The UK Continental Shelf holds the world's largest inventory of end-of-life fixed platforms, with over 470 installations requiring complete removal under OSPAR mandates. HM Revenue and Customs administers decommissioning expenditure relief that improves project economics for marginal field operators. Aberdeen's supply base compresses procurement timelines for North Sea heavy-lift campaigns.
Norway
Statoil-operated fields and independent equity holders are accelerating platform removal schedules ahead of OSPAR compliance deadlines. The Norwegian Petroleum Directorate enforces stringent financial security requirements through decommissioning bonds. Stavanger's engineering corridor concentrates subsea cutting technology providers and well abandonment specialists.
United States
Gulf of Mexico fixed platform retirements are compressing semi-submersible crane vessel availability into multi-year booking windows. BSEE administers decommissioning bond requirements and site clearance standards for outer continental shelf operators. Houston's energy corridor houses the primary contractor procurement offices for Gulf abandonment programs.
Brazil
Pre-salt FPSO fleets approaching design life end are creating sustained demand for integrated mooring and hull removal services. Petrobras and international equity partners face ANP-mandated decommissioning security agreements. Rio de Janeiro's offshore engineering cluster is building captive decommissioning capabilities for deepwater production system retirements.
Netherlands
Southern North Sea gas platform retirements are expanding contractor activity in shallow-water abandonment markets. The State Supervision of Mines enforces OSPAR-aligned complete removal standards for steel jacket structures. Rotterdam's port infrastructure supports heavy-lift vessel mobilization and onshore dismantlement operations under EU Waste Framework Directive mandates.
Offshore Decommissioning Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across heavy-lift vessel ownership and well engineering specialization. The market structures into three tiers: integrated full-service contractors commanding framework agreements, specialized well plugging and abandonment engineers, and single-scope commodity providers bidding discrete scopes. Two strategic archetypes dominate competitive positioning—fleet-heavy marine contractors with semi-submersible crane vessels, and engineering-heavy specialists with proprietary well barrier technologies. Capacity booking wars and technology licensing partnerships represent the dominant competitive moves as operators secure multi-year vessel commitments.
Among European marine contractors, Heerema Marine Contractors, Allseas Group SA, and Saipem SpA exemplify the fleet-heavy archetype with semi-submersible crane vessel ownership. These entities occupy positions where heavy-lift capacity scarcity creates pricing leverage against operators facing OSPAR-mandated removal deadlines. Aker Solutions ASA represents the engineering-heavy specialist tier, anchoring well plugging and abandonment capabilities through proprietary barrier system designs. The competitive tension between these archetypes is reshaping procurement patterns as supermajors consolidate decade-long decommissioning programs under single accountability structures.
| Leading Market Players |
|---|
| TechnipFMC PLC |
| Heerema Marine Contractors |
| Allseas Group SA |
| Saipem SpA |
| Subsea 7 SA |
| Boskalis Westminster NV |
| Aker Solutions ASA |
| Petrofac Ltd |
| DEME Offshore |
| Others |
Value Network & Pricing Analysis
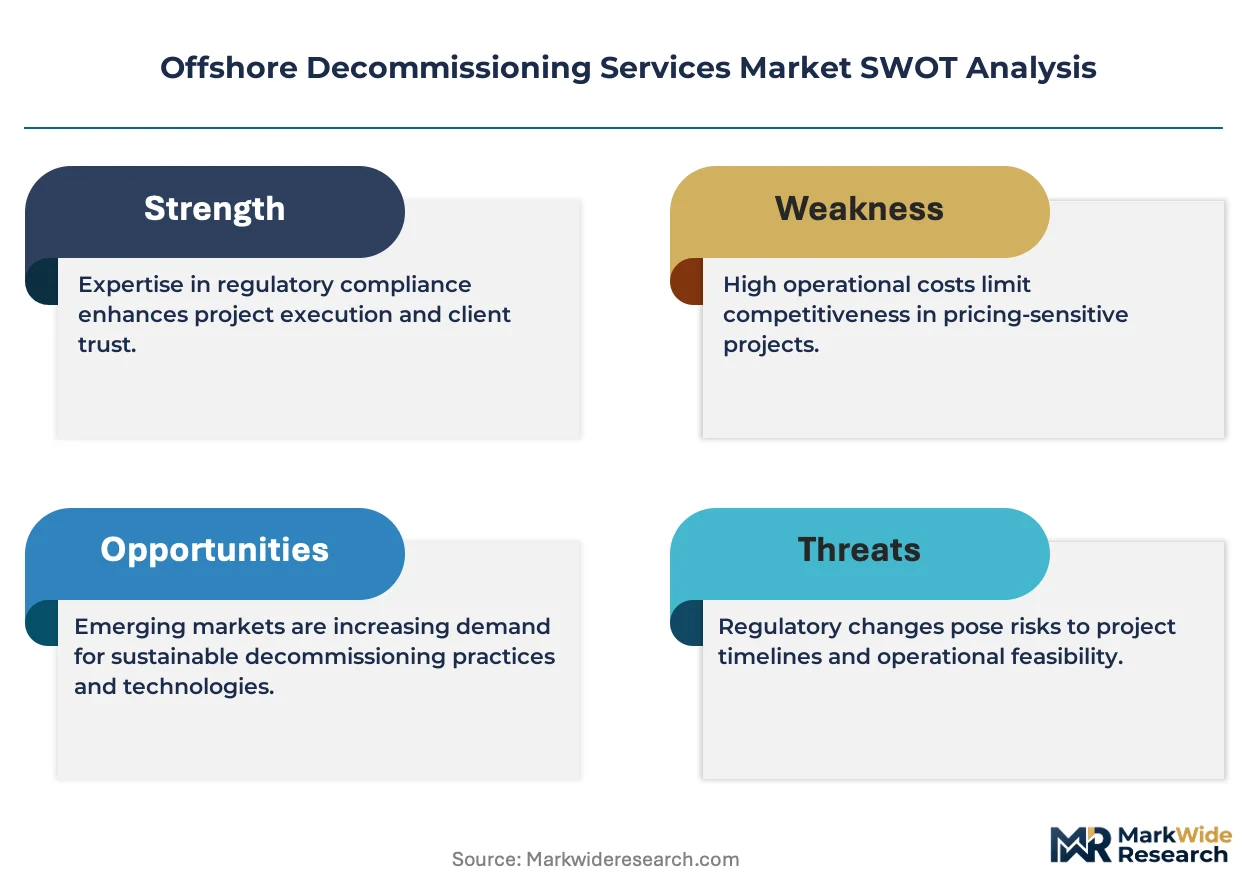
Heavy-lift vessel day rates cascade through contractor bidding tiers as the dominant cost component, with semi-submersible crane vessel scarcity in the North Sea and Gulf of Mexico feeding premium pricing into integrated full-field contracts while marginal operators absorb residual spot-market volatility.
Pricing Analysis
Outcome-based pricing anchored to platform removal completion timelines dominates integrated contracting, with Heerema Marine Contractors and Allseas Group SA commanding premiums tied to single-lift execution guarantees. Price differentiation separates fleet-owning marine contractors from engineering-specialist well abandonment providers, with certification grade for OSPAR compliance and BSEE financial assurance status acting as tier gates. Cost compression in commodity scope bidding is intensifying because surplus jack-up barge capacity from offshore wind construction is cross-training into decommissioning markets. National oil companies in Brazil and Mexico exhibit lowest price sensitivity due to captive security agreement structures, while UK marginal field operators face acute budget constraints under Petroleum Revenue Tax abolition timelines.
Supply Chain Analysis
OSPAR and BSEE certification requirements gate contractor qualification, with only twelve global semi-submersible crane vessels meeting heavy-lift specifications for complete jacket removal. Geographic supply concentration centers on the Netherlands, Norway, and Singapore for vessel mobilization and subsea robotics manufacturing. Raw material dependencies encompass S355 and S420 offshore structural steels, diamond wire cutting consumables, and saturation diving life support systems. Single-source vulnerability runs through European heavy-lift vessel ownership, where booking commitments now extend across multi-year windows. Distribution feeds from Aberdeen and Stavanger engineering clusters through operator procurement offices in Houston and Rio de Janeiro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semi-submersible crane vessel scarcity props pricing power for fleet owners, with fewer than twelve globally qualified units creating structural bottlenecks that compress operator negotiating leverage across the North Sea and Gulf of Mexico.
For Market Incumbents: Cement multi-year framework agreements with UK and Norwegian operators before pre-salt FPSO decommissioning demand peaks in Brazil. Fleet-heavy contractors should anchor backward integration into diamond wire cutting technology to capture margin from mechanical severing operations, while engineering specialists must defend against rigless well abandonment systems threatening conventional P&A market share. For New Entrants and Emerging Players: Enter via subsea robotics deployment partnerships targeting deepwater Gulf of Mexico fields previously classified as uneconomic for diver-dependent methods. The most penetrable white-space sits in well plugging and abandonment for marginal North Sea fields where rigless coiled tubing systems open scope to lower-tier service providers. A go-to-market angle combining ANP certification pathway investment with Petrobras vendor qualification accelerates Brazilian market access. For Investors and Strategic Acquirers: Distressed-cycle entries favor engineering-heavy specialists with proprietary well barrier technologies in the UK North Sea, where Petroleum Revenue Tax abolition is accelerating marginal field retirement schedules. Long-term viability over a five-to-ten year window hinges on robotics capability convergence and circular economy accreditation for EU dismantlement yards. The signal to watch is ANP-mandated decommissioning security agreement enforcement triggering captive capability buildout among Brazilian service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Capacity Expansion | Heavy-lift vessel additions in Singapore and Rotterdam compress multi-year booking windows for North Sea operators. |
| Robotics Technology Licensing | AUV diamond wire cutting partnerships unlock deepwater Gulf of Mexico fields below 500 meters. |
| Circular Economy Certification | EU Waste Framework Directive accreditation for Rotterdam dismantlement yards commands material recovery premiums. |
| Well P&A Technology Convergence | Rigless abandonment systems combining coiled tubing and wireline interventions displace conventional rig-dependent methods. |
| ANP Vendor Qualification | Petrobras security agreement compliance opens fifteen-year demand runway for pre-salt FPSO decommissioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with OSPAR compliance databases, BSEE decommissioning bond filings, and UK Continental Shelf production statistics providing foundational market sizing. Primary interviews with heavy-lift vessel operators, well abandonment engineering directors, and national oil company procurement officers validated demand assumptions and technology adoption timelines. Bottom-up project pipeline aggregation across the UK, Norway, United States, and Brazil reconciled against top-down expenditure forecasts from energy ministry decommissioning security agreements.
Data-stream reconciliation across vessel day-rate indices, contractor backlog disclosures, and regulatory mandate timelines informed the analytical framework. Segmentation dimensions modeled encompass service type, technology category, water depth deployment, and end-user archetype across the projection horizon. CAGRs derived from contracted project value aggregation and announced framework agreement durations, with heavy-lift vessel availability curves and OSPAR compliance deadline clustering acting as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated North Sea platform retirement schedules or Brazilian pre-salt field maturation delays. Forecasts reflect assumptions regarding regulatory enforcement consistency and vessel delivery timelines from Singapore and South Korean shipyards. A model refresh is warranted upon material change in ANP decommissioning security agreement implementation or EU circular economy mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market