
 Thermal Recovery Market | 2026-2036
Thermal Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Recovery Market Analytics
The EPA's methane emissions standards for oil and gas operations is restructuring capital allocation across thermal recovery project portfolios. Siemens Energy leverages its turbine-generator integration capabilities to dominate high-efficiency cogeneration installations in heavy oil fields. General Electric competes through advanced reservoir monitoring systems that optimize steam-to-oil ratios. Ormat Technologies specializes in binary cycle equipment that converts waste heat from thermal recovery operations into dispatchable electricity.
Thermal recovery encompasses engineered systems that extract hydrocarbons from viscous reservoirs by injecting heated fluids—typically steam at 300°C to 340°C—to reduce crude viscosity and enable flow toward production wells. These systems serve the primary commercial purpose of unlocking heavy oil and bitumen deposits that resist conventional primary and secondary extraction methods. Steam injection technology anchors the largest installed base across mature heavy oil basins, while geothermal applications represent the fastest-expanding segment as operators seek to repurpose depleted wells for renewable heat and power generation. Oil and gas companies command the dominant share of procurement spending, though power generation firms are deepening their involvement through integrated thermal-electric project structures.
The EPA enforces methane performance standards under the Clean Air Act that shape equipment specifications and leak detection protocols for thermal recovery facilities. China's MEE implements dual carbon targets that restrict approval of new high-emission thermal projects while accelerating geothermal transition pathways. Alberta's energy regulator mandates steam-to-oil ratio reporting that directly influences project economics and operating permits. Stakeholders must monitor how carbon border adjustment mechanisms and evolving CCS integration requirements reshape project returns across competing basins.
Market Dynamics
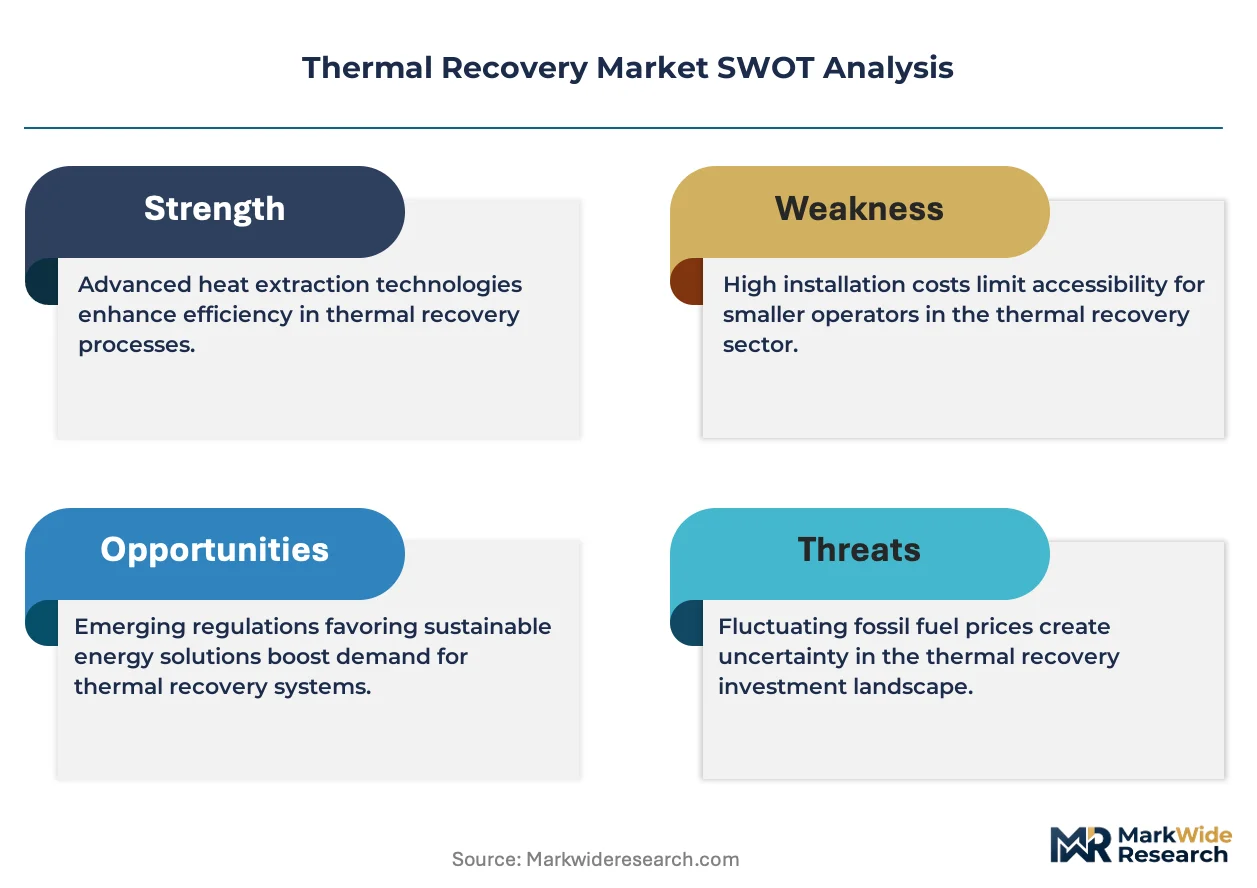
Steam-to-oil ratio mandates from Alberta's energy regulator are compressing project economics and forcing operators to prioritize reservoir monitoring precision over brute-force steam injection volumes.
Growth Catalysts
- Steam-Assisted Gravity Drainage:Heavy oil extraction operators in Canada deploy SAGD systems to unlock bitumen deposits that resist conventional recovery methods, driving sustained equipment procurement cycles.
- EPA Methane Performance Standards:Leak detection protocol upgrades under Clean Air Act enforcement are mandating sensor network investments across Permian Basin thermal facilities.
- Geothermal Repurposing:Depleted well conversion for renewable heat and power generation is expanding addressable infrastructure for binary cycle equipment suppliers.
Market Restraints
- Natural Gas Price Volatility:Steam generation costs swing with Henry Hub pricing, exposing project returns to fuel input cost instability that operators cannot fully hedge.
- China MEE Dual Carbon Restrictions:New high-emission thermal project approvals face tightening scrutiny under national carbon peak and neutrality targets, constraining greenfield development.
- Electrification Substitution:Solar thermal and electric heating pilots for low-temperature extraction threaten steam injection's dominance in marginal reservoir applications.
Strategic Opportunities
- Venezuela Orinoco Belt:Sanction relief scenarios could unlock stranded heavy oil reserves requiring substantial thermal recovery infrastructure buildout.
- Carbon Capture Integration:CCS tax credits under the US Inflation Reduction Act are incentivizing co-located capture equipment at steam generation facilities.
- Binary-Flash Hybrid Systems:Convergence of organic Rankine cycle technology with traditional steam injection is enabling waste heat-to-power revenue streams at operating sites.
Industry Challenges
- Reservoir Engineer Scarcity:Specialized geoscience talent capable of optimizing steam chamber development commands premium compensation that strains mid-cap operator budgets.
- Steam Generator Fabrication Lead Times:Pressure vessel certification delays from ASME and provincial authorities extend project commissioning schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Recovery Market |
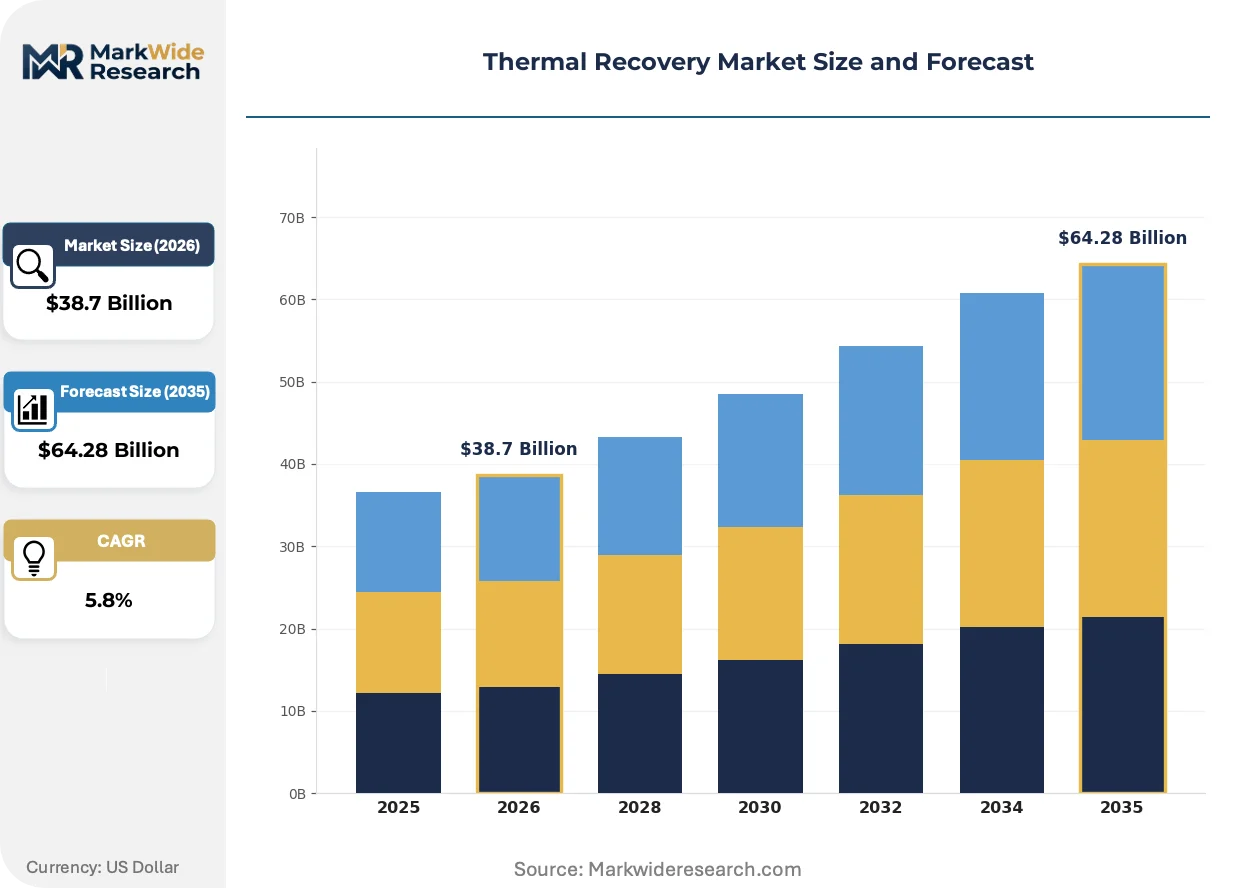
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Steam Injection, Gas Injection, Hot Water Injection, Geothermal Application: Heavy Oil Extraction, Enhanced Oil Recovery, Thermal Energy Storage, Geothermal Heating End User: Oil & Gas Companies, Power Generation Firms, Industrial Users, Government Agencies Service Type: Consulting Services, Equipment Supply, Project Management, Maintenance Services |
| Companies Covered | Siemens Energy, General Electric, ABB Ltd., Mitsubishi Heavy Industries Ltd., Ormat Technologies Inc., Turboden S.p.A., Bosch Industriekessel GmbH, IHI Corporation, Wood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Recovery Market Evolving Landscape
Digital reservoir characterization is displacing empirical steam allocation rules, enabling real-time injection optimization that directly responds to formation heterogeneity and regulatory efficiency mandates.
Electromagnetic-heating assisted recovery is unifying radio frequency and resistive heating methods into single-wellbore systems. Heavy oil operators in California's Kern County are piloting these hybrid configurations to reduce water handling intensity. The technology is unifying thermal efficiency metrics with environmental compliance reporting, compressing the traditional separation between production engineering and regulatory documentation functions.
REACH chemical restrictions on corrosion inhibitors are forcing reformulation of boiler water treatment chemicals across EU-connected supply chains. Industrial consequence includes accelerated qualification timelines for alternative chemistries at steam generation facilities. Heavy oil projects in the North Sea and continental Europe are responding by pre-qualifying dual-source additive suppliers to avoid single-source regulatory exposure.
Integrated service contracts are consolidating equipment procurement, steam generation operations, and reservoir management under single-vendor accountability structures. This displaces the traditional segmented purchasing model where operators self-integrated discrete vendor packages. The shift is most visible in Alberta's oil sands, where major producers are bundling 10-15 year steam supply agreements with real-time performance guarantees tied to steam-to-oil ratio outcomes.
Thermal Recovery Market Segmentation
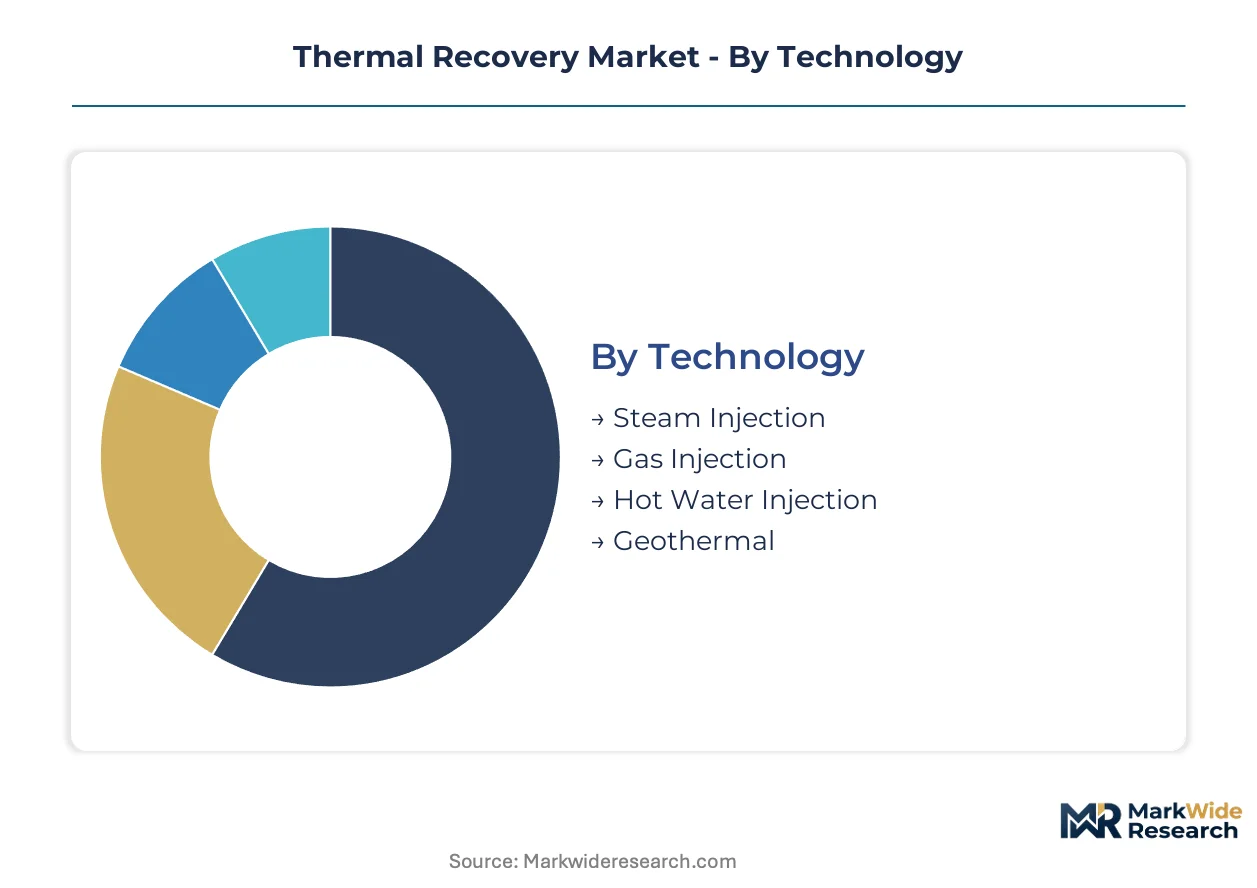
Thermal recovery segmentation reflects the tension between standardized steam injection platforms and customized reservoir-specific configurations. Equipment suppliers and service providers must calibrate their portfolios across this spectrum to capture value in both mature basins and frontier developments.
Technology:
The customization-vs-standardization spectrum spans fully engineered steam systems at one extreme and modular geothermal units at the other, with intermediate technologies offering configurable pressure-temperature profiles.
- Steam Injection:Systems inject saturated steam at 300°C to 340°C through dual-horizontal well pairs to reduce heavy oil viscosity. Demand concentrates in Alberta's oil sands where SAGD operations require continuous steam supply with precise pressure control. Steam-to-oil ratio mandates from the Alberta Energy Regulator are forcing technology upgrades toward higher thermal efficiency.
- Gas Injection:In-situ combustion and flue gas injection methods oxidize residual hydrocarbons to generate heat within the formation. Operators in California's Kern County deploy these systems where water scarcity restricts steam-based alternatives. Air quality regulations from California's South Coast Air Quality Management District shape equipment specifications and emissions control investments.
- Hot Water Injection:Lower-temperature thermal flooding suits shallow, low-viscosity heavy oil reservoirs. The technology offers standardized skid-mounted units with faster deployment timelines than steam systems.
- Geothermal:Binary cycle and flash steam systems repurpose depleted wells for renewable power generation. Installations in Nevada's Great Basin demonstrate commercial viability for oil field waste heat recovery.
Leading the category by volume: Steam Injection. Growing fastest: Geothermal.
Application:
Cost tier segmentation separates capital-intensive greenfield developments from operational efficiency investments in mature fields.
- Heavy Oil Extraction:Primary commercial deployment targets bitumen and extra-heavy crude in Canada's oil sands and Venezuela's Orinoco Belt. Steam-assisted gravity drainage dominates new project development. EPA methane performance standards are restructuring leak detection investments across Permian Basin thermal facilities.
- Enhanced Oil Recovery:Tertiary recovery methods extend productive life of mature conventional fields. Cyclic steam stimulation in California's Midway-Sunset field illustrates economic thresholds for thermal EOR deployment. Reservoir heterogeneity demands customized injection patterns and real-time monitoring.
- Thermal Energy Storage:Molten salt and pressurized water systems buffer intermittent renewable generation. Industrial facilities in Texas integrate these systems with combined heat and power operations.
- Geothermal Heating:Direct-use applications supply district heating and industrial process heat. Projects in Iceland and Turkey demonstrate scalable deployment models for sedimentary basin heat extraction.
Highest capital intensity: Heavy Oil Extraction. Fastest policy tailwinds: Geothermal Heating.
End User:
Customer type segmentation distinguishes integrated oil majors with captive engineering capabilities from specialized power generators seeking turnkey solutions.
- Oil & Gas Companies:Integrated majors and independent operators command procurement authority for field development and production optimization. Canadian Natural Resources and Suncor Energy anchor demand for SAGD infrastructure in Alberta.
- Power Generation Firms:Utilities and independent power producers invest in waste heat recovery and geothermal assets. Ormat Technologies and Enel Green Power develop binary cycle installations at operating thermal recovery sites.
- Industrial Users:Refineries and petrochemical facilities purchase thermal energy for process heating. Gulf Coast operators integrate with steam methane reforming and coking operations.
- Government Agencies:State-owned enterprises and national oil companies direct strategic reserve development. PDVSA in Venezuela and Saudi Aramco shape long-term technology adoption pathways.
Dominant procurement volume: Oil & Gas Companies. Fastest contract structure evolution: Power Generation Firms.
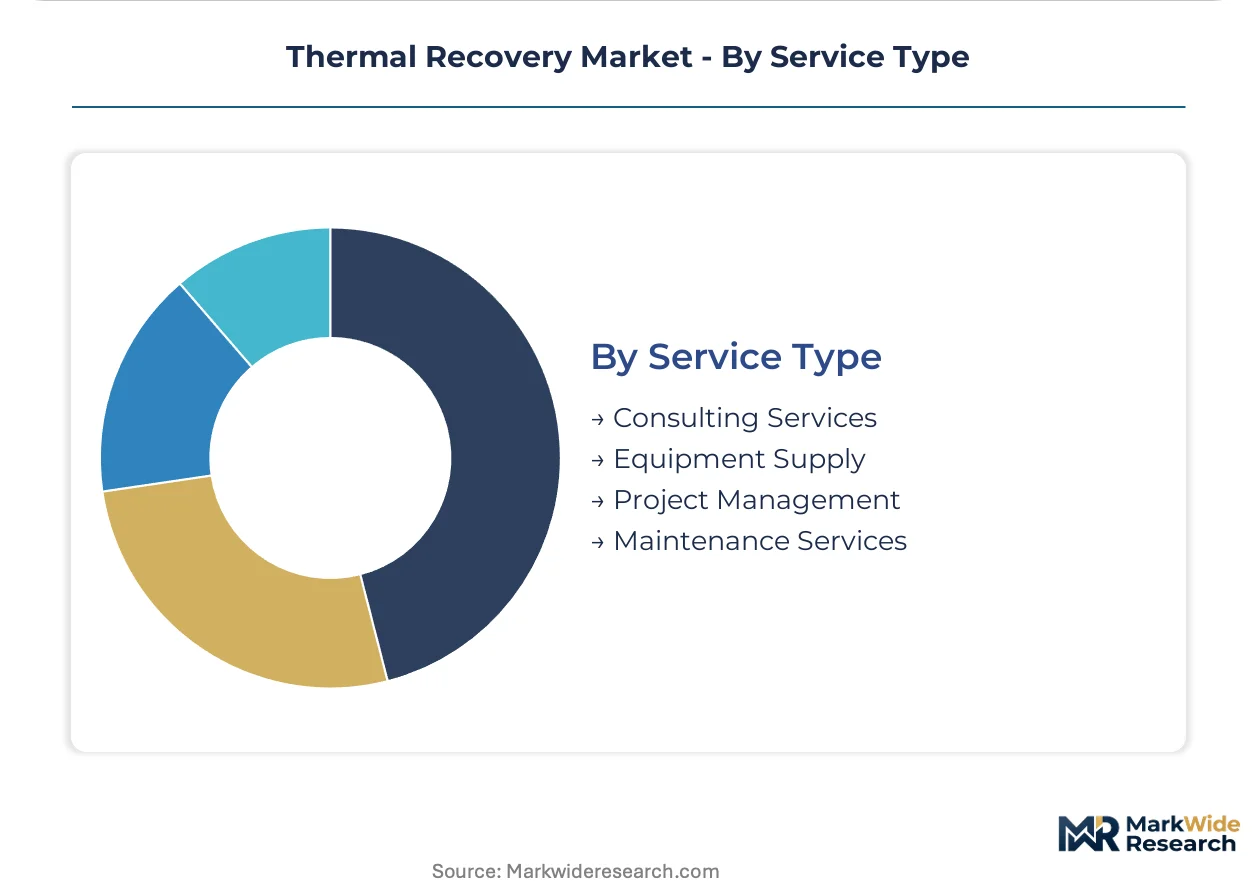
Service Type:
Margin structure varies across advisory services with high intellectual property content versus commoditized maintenance with labor intensity.
- Consulting Services:Reservoir simulation, thermal process design, and regulatory compliance advisory command premium pricing. Firms like Schlumberger and Halliburton deploy specialized geoscience talent for steam chamber optimization.
- Equipment Supply:Steam generators, heat exchangers, and downhole hardware constitute capital expenditure core. ASME pressure vessel certification requirements extend fabrication lead times.
- Project Management:Integrated EPC contracts consolidate engineering, procurement, and construction accountability. Alberta's oil sands producers favor 10-15 year performance-based agreements.
- Maintenance Services:Scheduled turnaround and predictive maintenance contracts reduce unplanned downtime. Sensor network deployments enable condition-based servicing.
Highest margin concentration: Consulting Services. Steepest expansion trajectory: Project Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alberta's Athabasca oil sands corridor anchors thermal recovery infrastructure deployment, with Fort McMurray's SAGD clusters driving sustained equipment procurement cycles across the 2026-2035 forecast window.
United States
The Permian Basin's Delaware and Midland sub-basins concentrate steam-flood operations for heavy oil recovery. EPA methane performance standards under the Clean Air Act mandate optical gas imaging surveys and continuous monitoring equipment at thermal facilities. Houston's energy corridor hosts engineering procurement centers that specify high-efficiency cogeneration packages for West Texas deployments.
Canada
Steam-assisted gravity drainage dominates capital allocation in Alberta's oil sands regions. The Alberta Energy Regulator enforces steam-to-oil ratio reporting thresholds that directly shape project economics and operating permit renewals. Calgary's corporate headquarters district anchors procurement decision-making for SAGD infrastructure serving Fort McMurray production clusters.
Venezuela
The Orinoco Belt's heavy oil reserves represent stranded capacity awaiting thermal recovery infrastructure buildout. Sanction relief scenarios would unlock substantial steam injection and upgrading equipment demand. Puerto La Cruz and José industrial complexes maintain dormant fabrication capacity for pressure vessel and generator assembly.
China
Liaohe and Xinjiang oil fields deploy thermal stimulation for heavy oil reserves in northeastern and western provinces. The Ministry of Ecology and Environment implements dual carbon targets that restrict new high-emission thermal approvals while accelerating geothermal transition pathways. Sinopec's engineering subsidiaries in Beijing and Shanghai pilot binary cycle waste heat recovery at operating steam facilities.
Germany
REACH chemical restrictions on corrosion inhibitors force reformulation of boiler water treatment chemicals across EU-connected supply chains. Industrial clusters in the Ruhr region and Bavaria pre-qualify dual-source additive suppliers to avoid single-source regulatory exposure. Munich-based engineering consultancies specialize in thermal process optimization for North Sea heavy oil projects.
Thermal Recovery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with turbine-generator specialists commanding pricing power that fabrication-only vendors cannot match. The vendor base organizes into three functional tiers: full-system integrators, component specialists, and regional service providers. Siemens Energy and General Electric occupy the integrator tier. Mitsubishi Heavy Industries and IHI Corporation anchor the heavy fabrication segment. Competitive dynamics center on long-term performance contracts and ASME pressure vessel certification speed.
Within the full-system integrator tier, Siemens Energy and General Electric represent the archetype of turbine-generator bundling capability. Ormat Technologies exemplifies binary cycle specialization for waste heat recovery applications. Among Japanese industrial conglomerates, Mitsubishi Heavy Industries and IHI Corporation occupy positions in heavy pressure vessel fabrication and power generation equipment. These named entities anchor competitive positioning without implying specific market share figures or strategic initiatives beyond their visible industry roles.
| Leading Market Players |
|---|
| Siemens Energy |
| General Electric |
| ABB Ltd. |
| Mitsubishi Heavy Industries Ltd. |
| Ormat Technologies Inc. |
| Turboden S.p.A. |
| Bosch Industriekessel GmbH |
| IHI Corporation |
| Wood |
| Others |
Value Network & Pricing Analysis
Specialized reservoir engineers concentrated in Calgary and Houston command compensation premiums that widen spreads between premium-tier integrated service contracts and commoditized equipment-only procurement. Labor-cost differentials between these engineering hubs and fabrication centers in East Asia feed directly into three-tier pricing structures across thermal recovery project portfolios.
Pricing Analysis
Performance-guarantee pricing tied to steam-to-oil ratio outcomes anchors value-based contracts in Alberta's oil sands, where Suncor Energy and Canadian Natural Resources bundle long-term steam supply with real-time reservoir optimization. Pricing stratifies across ASME-certified premium systems, provincial-standard mid-tier packages, and economy-grade hot water injection units for shallow reservoirs. Cost compression in the economy tier intensifies as solar thermal pilots threaten marginal steam applications. Independent operators in California's Kern County exhibit highest price sensitivity, while integrated majors prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Alberta's local-content mandates for provincial energy projects are reshaping sourcing patterns for pressure vessel fabrication and downhole hardware procurement. Manufacturing gravity centers on Germany for precision turbine components, Japan for heavy pressure vessels from Mitsubishi Heavy Industries and IHI Corporation, and South Korea for modular steam generator skids. Supply chains draw from nickel-alloy steel feedstock, specialized corrosion inhibitors, and high-temperature seals. Single-source vulnerability concentrates in ASME-certified forging capacity. Distribution runs through integrated EPC contractors that consolidate engineering, procurement, and construction accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal recovery vendors are accelerating vertical-integration races to capture margin pools across steam generation, reservoir management, and carbon capture equipment. Captive engineering talent and fabrication capacity represent the decisive upstream levers.
For Market Incumbents: Hedge against electrification substitution by deepening geothermal repurposing capabilities and securing long-term ASME certification capacity. Siemens Energy and General Electric should expand binary cycle integration to defend against Ormat Technologies' waste heat specialization. Reservoir engineer scarcity in Calgary threatens project execution timelines. For New Entrants and Emerging Players: Begin with modular geothermal conversion kits for depleted Permian Basin wells, where lease operators lack capital for full SAGD infrastructure. Target California's cyclic steam stimulation operators with electromagnetic-heating hybrid systems that reduce water handling intensity. Lead with sensor-network-as-a-service offerings that satisfy EPA methane monitoring mandates without upfront capital burden. For Investors and Strategic Acquirers: The window for entry favors mid-cap fabrication specialists with captive pressure vessel certification speed. Five-to-ten year viability hinges on carbon capture integration capabilities at steam generation facilities. Watch Alberta Energy Regulator steam-to-oil ratio threshold tightening as the inflection signal for efficiency-technology acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Binary Cycle Integration | Ormat Technologies leverages organic Rankine cycle technology to convert waste heat into dispatchable electricity at operating thermal sites. |
| ASME Certification Expansion | Pressure vessel fabrication lead times from eight to fourteen months reward vendors with redundant certified capacity across multiple provinces. |
| Carbon Capture Co-location | US Inflation Reduction Act tax credits incentivize CCS equipment installation at steam generation facilities serving heavy oil extraction. |
| Electromagnetic-Heating Pilot Scale-Up | Radio frequency and resistive heating hybrids in California's Kern County reduce water handling intensity for regulatory compliance. |
| Geothermal Well Repurposing | Depleted well conversion for renewable power generation expands addressable infrastructure for binary cycle equipment suppliers. |
Research Methodology
Regulatory filings from the EPA and Alberta Energy Regulator, EIA thermal recovery production statistics, and ASME pressure vessel certification databases formed the secondary backbone for this analysis. Primary interviews with reservoir engineering directors at SAGD operators, procurement leads at integrated oil majors, EPC contract managers, and geothermal project developers triangulated against customs data for steam generator imports and provincial permitting records. Bottom-up equipment shipment tracking and top-down energy sector capex analysis cross-validated market sizing across the analysis window.
Historical trendline analysis of steam-to-oil ratio compliance costs and methane detection equipment deployment rates informed projection frameworks. Segmentation modeling spanned technology type, application intensity, end-user integration depth, and regional regulatory cluster. CAGRs derived from unit economics analysis of greenfield SAGD projects and brownfield geothermal conversions. Forecast inputs included Henry Hub natural gas price scenarios and China MEE dual carbon approval velocity assumptions.
Sanction relief timelines for Venezuela, carbon border adjustment mechanism implementation, and breakthrough electrification technology cost curves are the dominant revision risks to thermal recovery infrastructure demand. Forecasts reflect assumptions about regulatory enforcement continuity and reservoir engineering labor market tightness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Thermal Energy Storage
China Thermal Power Plant Market
Thermal Energy Storage
United States Thermal Power Market
Thermal Energy Storage
Thermal Energy Storage (TES) Market
Thermal Energy Storage
Europe Thermal Energy Storage Market
Thermal Energy Storage
North America Thermal Power Market
Thermal Energy Storage
Europe District Heating Market
Thermal Energy Storage
Molten Salt Thermal Energy Storage (TES) Market
Thermal Energy Storage
North America Thermal Energy Storage Market
Thermal Energy Storage
Middle-East and Africa Thermal Power Market
Thermal Energy Storage
Solar Thermal Fuel Market
Thermal Energy Storage
Russia Thermal Power Market
Thermal Energy Storage
Asia-Pacific Thermal Energy Storage Market
Thermal Energy Storage
Ice Thermal Storage Systems Market
Thermal Energy Storage
Africa Thermal Energy Storage Market
Thermal Energy Storage
Southeast Asia Thermal Power Market