
 Brazil Offshore Oil & Gas Upstream Market | 2026-2036
Brazil Offshore Oil & Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Offshore Oil & Gas Upstream Market Insights
ANP's local content requirements is hardening the cost-of-entry calculus for international operators bidding in Brazilian concession rounds. Petrobras leverages its pre-salt operational dominance to sustain production leadership across ultra-deepwater fields. Shell competes through differentiated floating production system expertise in the Santos Basin. ExxonMobil anchors its Brazil portfolio with disciplined exploration targeting high-impact subsalt structures.
Brazil Offshore Oil & Gas Upstream encompasses crude oil and natural gas extraction activities conducted in marine environments beyond the country's territorial coastline, typically employing subsea wellheads connected to floating production storage and offloading vessels operating at water depths exceeding 1,500 meters. The primary industrial purpose centers on delivering hydrocarbon feedstock to domestic refineries and LNG export terminals. Floating production systems command the largest installed base among technology segments, reflecting Brazil's world-leading deployment of FPSO vessels in ultra-deepwater pre-salt provinces. Subsea systems represent the fastest-expanding technology category as operators push wellheads farther from host platforms to access remote reservoir compartments. National oil companies retain dominant client-type positioning through Petrobras's statutory preference rights in pre-salt development, while independent operators carve margin pools in mature post-salt concessions.
ANP licensing rounds, BNDES financing conditionalities, and IBAMA environmental licensing shape market access timelines and capital deployment patterns for upstream participants. ANP's local content mandates force technology suppliers to establish Brazilian manufacturing partnerships or absorb substantial bid penalties. BNDES cost-of-capital advantages flow predominantly to contractors meeting domestic supply-chain thresholds. Stakeholders must monitor pre-salt unit cost trajectories against break-even assumptions as reservoir complexity escalates in northern Santos Basin extensions.
Market Dynamics
ANP's escalating local content mandates are compressing international operator margins while Petrobras consolidates pre-salt operational control through statutory preference rights in ultra-deepwater concessions.
Growth Catalysts
- Pre-salt reservoir expansion:Northern Santos Basin extensions unlock billion-barrel-class accumulations, drawing capital from petrochemical refiners seeking captive feedstock security.
- FPSO vessel deployment:Brazil's world-leading fleet of floating production storage and offloading units enables economically viable development at water depths exceeding 2,000 meters.
- ANP concession rounds:Regular licensing cycles under Brazil's petroleum regulator create predictable access windows for upstream participants targeting subsalt structures.
Market Restraints
- Steel and subsea equipment cost volatility:Specialized high-grade alloys and subsea trees face supply concentration from limited global fabricators, amplifying project budget uncertainty.
- Domestic supply chain bottlenecks:ANP-mandated local content thresholds force technology suppliers into Brazilian manufacturing partnerships or substantial bid penalties, extending procurement timelines.
- Reservoir complexity escalation:Carbonate-hosted pre-salt formations exhibit heterogeneous flow characteristics that challenge standard development assumptions and recovery factor projections.
Strategic Opportunities
- Northeast Brazil frontier basins:Potiguar and Ceará offshore provinces remain underexplored relative to Santos Basin, offering first-mover positioning for independent operators.
- Electrification of FPSO power systems:Shore-to-ship power connections and onboard battery storage converge to reduce offshore carbon intensity and diesel consumption.
- BNDES green financing windows:Brazil's national development bank channels preferential cost-of-capital toward contractors meeting domestic supply-chain and emissions thresholds.
Industry Challenges
- Subsea systems integration complexity:Remote wellhead placement demands sophisticated tieback engineering to connect distant reservoir compartments to host platforms.
- IBAMA environmental licensing timelines:Federal environmental agency approval processes for ultra-deepwater drilling campaigns extend project sanctioning cycles unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Offshore Oil & Gas Upstream Market |
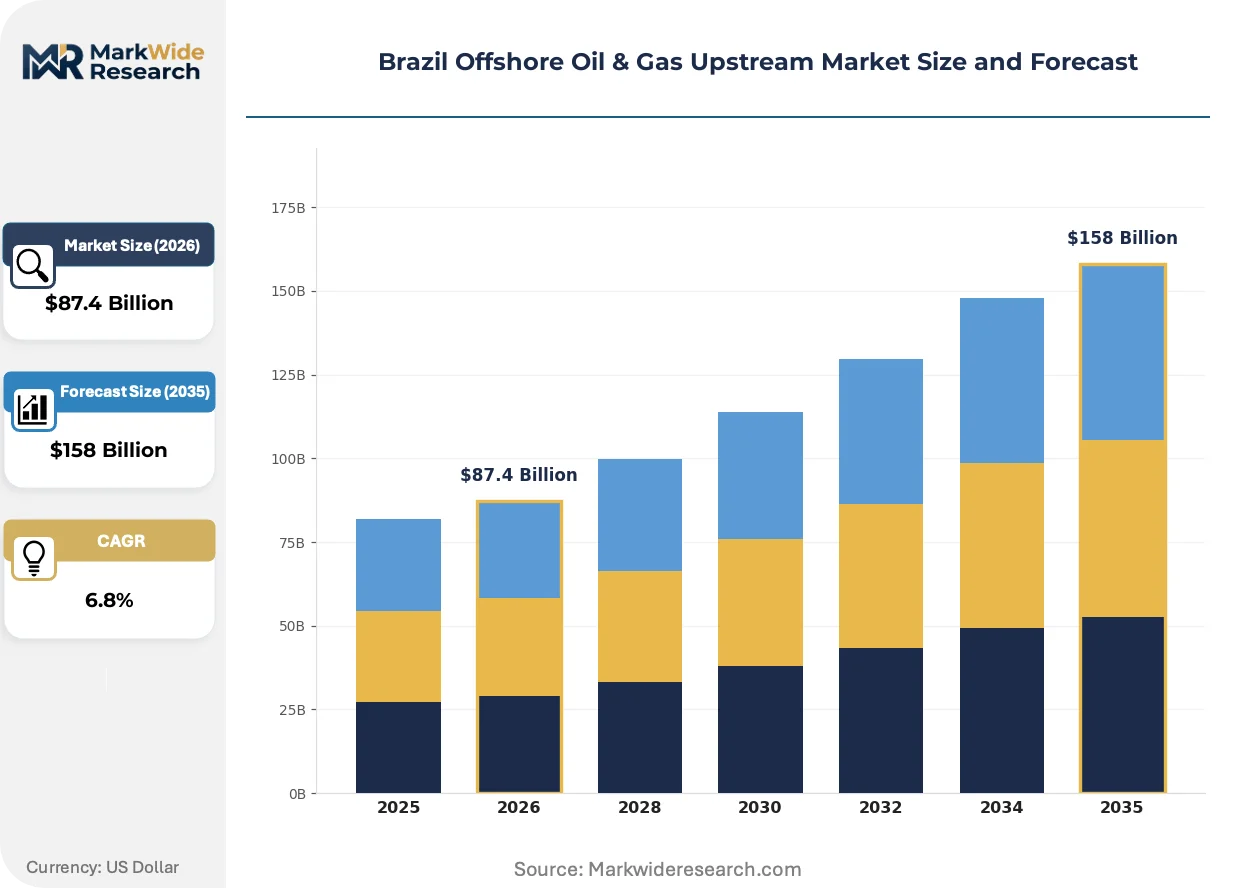
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Decommissioning Technology: Floating Production Systems, Subsea Systems, Wellhead Platforms, Rigid Risers Client Type: National Oil Companies, Independent Operators, Service Providers, Joint Ventures Installation: Onshore Facilities, Offshore Platforms, Subsea Installations, Supply Base |
| Companies Covered | Petrobras, Shell, ExxonMobil, BP, TotalEnergies, Chevron, Equinor, Enauta Participacoes, Murphy Oil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Offshore Oil & Gas Upstream Market Trends and Innovations
Digital reservoir characterization and autonomous subsea operations are compressing development cycles in Brazil's ultra-deepwater provinces, while regulatory pressure on emissions intensifies technology substitution patterns.
All-electric subsea production systems are electrifying conventional hydraulic control architectures across Santos Basin pre-salt fields. Petrobras and international partners are accelerating deployment of electric actuators and subsea processing modules to eliminate hydraulic fluid leaks and reduce topside footprint. This technology is electrifying capital allocation decisions by enabling longer step-out distances from host facilities and reducing subsea infrastructure weight.
ANP's revised local content calculation methodology tightens domestic sourcing requirements for subsea equipment and floating production system hull fabrication. The regulation forces technology suppliers to deepen Brazilian manufacturing partnerships or absorb scoring penalties in concession bidding. International operators are responding by pre-qualifying domestic yards and engineering firms ahead of licensing round participation.
Integrated service contracting is consolidating previously fragmented procurement of drilling, completion, and subsea installation services. Major operators are shifting from discrete vendor relationships to single-source accountability models covering full field development cycles. This pattern is most visible in Santos Basin pre-salt projects where reservoir complexity demands seamless coordination between exploration and production phases.
Brazil Offshore Oil & Gas Upstream Market Segmentation
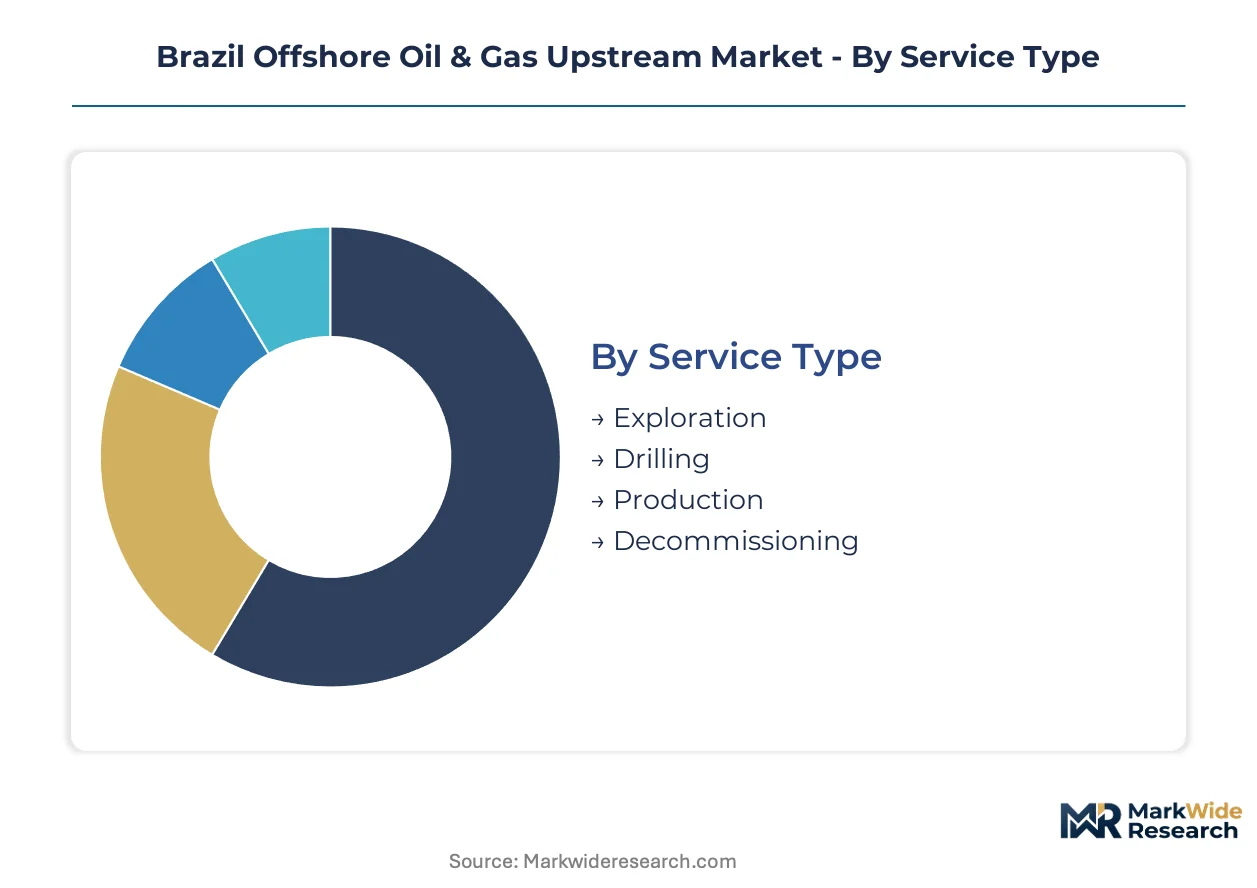
Segmentation reveals how capital allocation priorities diverge across Brazil's offshore upstream value chain. Service type concentration shapes contractor selection criteria, while technology choices determine break-even economics in ultra-deepwater pre-salt development.
Service Type:
Supply concentration tilts toward production-phase services as Santos Basin fields mature from exploration into full development.
- Exploration:Seismic acquisition and subsalt imaging services target carbonate reservoir characterization in northern Santos Basin extensions. Demand clusters around Petrobras-operated ultra-deepwater blocks where reservoir complexity demands advanced geophysical interpretation.
- Drilling:Extended-reach drilling and managed pressure systems tackle salt overburden challenges at water depths exceeding 2,000 meters. Santos Basin pre-salt campaigns consume the majority of floater rig days as independent operators accelerate appraisal programs.
- Production:Artificial lift optimization and subsea boosting maintain flow rates from high-pressure carbonate reservoirs.
- Decommissioning:Platform removal and well abandonment services address mature Campos Basin assets approaching end-of-field life.
Today's leader: Production. Tomorrow's challenger: Decommissioning.
Technology:
Cost tier stratification separates proven floating systems from emerging subsea electrification architectures demanding premium engineering margins.
- Floating Production Systems:FPSO hulls and topsides processing modules constitute the dominant capital category across Brazilian ultra-deepwater development. Petrobras maintains the world's largest operational fleet, with newbuild orders concentrating in domestic yards meeting ANP local content thresholds.
- Subsea Systems:All-electric subsea trees and multiphase boosting stations enable step-out distances beyond 15 kilometers from host facilities. Northern Santos Basin extensions drive fastest adoption as reservoir compartmentalization demands distributed processing architecture.
- Wellhead Platforms:Fixed jacket structures serve shallow-water post-salt developments in southern Santos and Campos Basins.
- Rigid Risers:Steel catenary and top-tensioned riser systems connect subsea wells to floating production hulls.
Today's anchor: Floating Production Systems. Tomorrow's expansion vector: Subsea Systems.
Client Type:
Customer type concentration reflects statutory preference rights that reserve pre-salt participation for designated operator categories.
- National Oil Companies:Petrobras exercises statutory priority rights in pre-salt concessions, commanding dominant procurement volume across ultra-deepwater service and technology categories. ANP production-sharing agreements reinforce NOC positioning through carried interest structures.
- Independent Operators:ExxonMobil, Shell, and Equinor compete for non-pre-salt concessions and farm-in opportunities where local content compliance costs are manageable. These operators concentrate exploration budgets on high-impact subsalt structures outside Petrobras preference zones.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes deliver integrated drilling and completion packages under single-source contracting models.
- Joint Ventures:Consortia structures combine NOC equity with international operator technical capabilities in specific block developments.
Today's volume driver: National Oil Companies. Tomorrow's competitive pressure: Independent Operators.
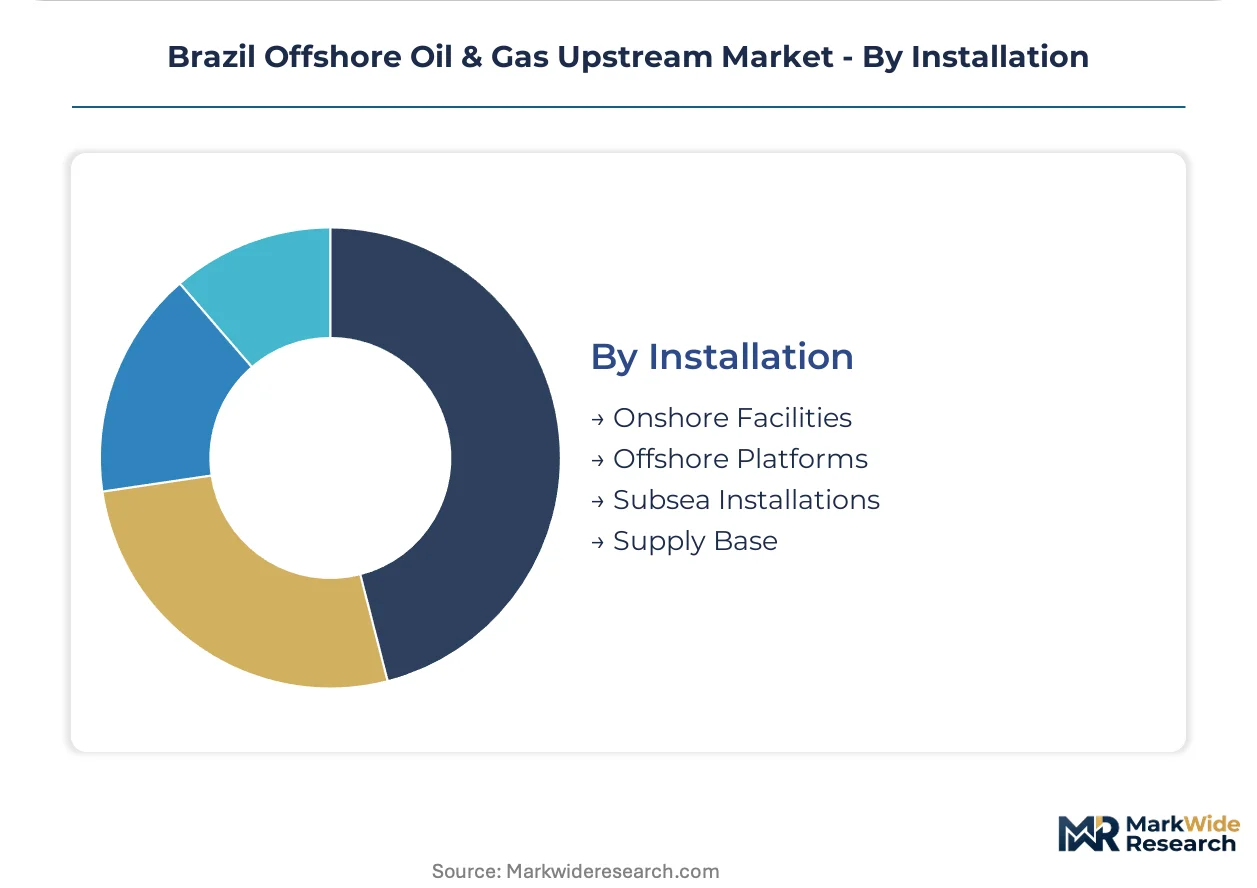
Installation:
Geography of installation activity tracks the northward migration of development focus from mature Campos Basin toward frontier Santos Basin extensions.
- Offshore Platforms:FPSO mooring, dynamic positioning, and hull integration activities concentrate in southern Santos Basin where water depths exceed 2,000 meters. Domestic fabrication yards in Rio de Janeiro state capture the majority of topsides module construction.
- Subsea Installations:Subsea tree deployment, flowline lay, and umbilical installation services expand most quickly as step-out distances increase. Northern Santos Basin pre-salt fields drive demand for reel-lay vessels and heavy-lift capability.
- Onshore Facilities:Pipeline landfall terminals and gas processing plants support domestic supply obligations under ANP concession terms.
- Supply Base:Macaé and Rio de Janeiro port infrastructure provides logistics hubs for offshore campaign mobilization.
Today's infrastructure anchor: Offshore Platforms. Tomorrow's activity surge: Subsea Installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized offshore engineering talent clusters in Rio de Janeiro state anchor Brazil's upstream operational capacity. Macaé and Niterói host the densest concentrations of subsea technicians and FPSO fabrication specialists. This workforce distribution shapes capital deployment patterns across Brazilian maritime basins.
Santos Basin
Pre-salt carbonate reservoirs drive the majority of greenfield investment into southern São Paulo state waters. ANP production-sharing agreements govern development rights in this ultra-deepwater province. The Itajaí and Rio de Janeiro industrial corridors supply subsea trees and umbilical systems for field installations exceeding 2,000 meter depths.
Campos Basin
Mature post-salt fields generate decommissioning service demand as platforms approach end-of-field life. IBAMA environmental licensing timelines extend well abandonment campaign schedules unpredictably. Macaé port infrastructure supports rig mobilization for late-life reservoir management and artificial lift optimization programs.
Sergipe-Alagoas Basin
Frontier deepwater exploration targets pre-salt analogs along Brazil's northeastern continental margin. BNDES financing conditionalities favor contractors meeting domestic supply-chain thresholds for appraisal drilling. Aracaju logistics bases provide staging capacity for seismic acquisition and exploration well campaigns.
Potiguar Basin
Shallow-water legacy production sustains marginal operational activity in Rio Grande do Norte state waters. Independent operators pursue farm-in opportunities outside Petrobras preference zones. Natal supply bases accommodate workover rig deployments and subsea intervention vessel calls.
Ceará Basin
Underexplored deepwater blocks attract exploration budgets targeting high-impact subsalt structures. ANP concession rounds create predictable access windows for international operators seeking frontier positioning. Fortaleza port infrastructure supports offshore campaign mobilization with expanding heavy-lift capabilities.
Brazil Offshore Oil & Gas Upstream Market Competitive Landscape
The competitive structure tilts toward national operator dominance with international majors competing for non-pre-salt concessions. Petrobras exercises statutory preference rights that reserve pre-salt participation, compressing available margin pools for independent players. Two strategic archetypes define positioning: integrated NOCs with carried interest structures, and capital-disciplined independents targeting high-impact exploration. Competitive moves concentrate on integrated service contracting and domestic manufacturing partnerships to satisfy ANP local content mandates.
Within the NOC tier, Petrobras anchors operational control through its pre-salt fleet dominance and statutory bidding advantages. Among international majors, Shell and ExxonMobil occupy positions defined by floating production system expertise and disciplined subsalt exploration targeting respectively. These companies exemplify the independent operator archetype competing outside Petrobras preference zones through differentiated technical capabilities and concession round participation strategies.
| Leading Market Players |
|---|
| Petrobras |
| Shell |
| ExxonMobil |
| BP |
| TotalEnergies |
| Chevron |
| Equinor |
| Enauta Participacoes |
| Murphy Oil |
| Others |
Pricing and Supply Chain Analysis
ANP-mandated local content thresholds force international operators into Brazilian manufacturing partnerships or substantial bid penalties, compelling supply chain reconfiguration that compresses margins and extends procurement timelines across ultra-deepwater project development.
Pricing Analysis
Integrated service contracting dominates pricing structures across Santos Basin pre-salt developments, bundling drilling, completion, and subsea installation under single-source accountability models. Price differentiation hinges on ANP local content compliance scores and FPSO hull fabrication domestic sourcing ratios. Cost compression in subsea equipment procurement is intensifying because steel alloy supply concentration from limited global fabricators amplifies budget uncertainty. Independent operators exhibit highest price sensitivity due to thinner margin reserves against Petrobras's statutory preference rights.
Supply Chain Analysis
Direct-to-FPSO-fabricator channels handle Petrobras fleet demand, while tiered distributor networks serve independent operator procurement. Supply concentrates in Brazil, South Korea, and Singapore for FPSO hull construction and topsides module fabrication. The chain draws from specialized high-grade steel alloys, subsea trees, and dynamic positioning systems. Single-source vulnerability in subsea tree manufacturing from Norwegian and Brazilian fabricators poses structural risk. Distribution runs through Macaé and Rio de Janeiro port infrastructure for offshore campaign mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's offshore upstream market functions as a stable compounder anchored by pre-salt reservoir scale and predictable ANP licensing cycles that sustain capital deployment visibility across the projection horizon.
For Market Incumbents: Acquire subsea electrification technology capabilities to counter displacement from all-electric subsea system adoption. Deepen backward integration into Brazilian fabrication yards to satisfy ANP local content mandates and defend procurement volume against independent operator competition. For New Entrants and Emerging Players: Domestic engineering partnerships provide the fastest route to concession round qualification without absorbing local content scoring penalties. Target Ceará Basin exploration blocks where Petrobras preference rights do not apply and frontier positioning commands premium technical service margins. For Investors and Strategic Acquirers: Asymmetric upside sits with subsea technology specialists holding ANP-certified Brazilian manufacturing partnerships. Five-to-ten year viability rests on electrification capability depth rather than conventional hydraulic system legacy. Watch pre-salt unit cost trajectories against break-even assumptions as northern Santos Basin extensions escalate reservoir complexity.| Strategic Initiative | Industry Significance |
|---|---|
| ANP Local Content Compliance Investment | Brazilian fabrication yard partnerships eliminate bid penalties and unlock BNDES financing access. |
| Subsea Electrification Technology Licensing | All-electric subsea trees enable longer step-out distances from host FPSO facilities. |
| FPSO Fleet Expansion | Newbuild orders concentrate in domestic yards meeting ANP hull sourcing thresholds. |
| Integrated Service Contracting Consolidation | Single-source accountability models reduce coordination friction across exploration-to-production cycles. |
| Frontier Basin Exploration Partnership | Ceará and Potiguar farm-in opportunities bypass Petrobras pre-salt preference zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Petrobras procurement executives, ANP regulatory affairs leads, FPSO fabrication yard managers, and subsea technology supplier commercial directors with secondary validation from ANP concession round documentation, BNDES financing disclosure records, and IBAMA environmental licensing databases. Bottom-up project sanctioning timelines and top-down basin-level investment flows were triangulated to anchor volume estimates.
Comparable historical development cycles from 2015-2020 pre-salt ramp-up anchored the forecast window against current northern Santos Basin extension timelines. The analytical framework modeled service type, technology category, client type, and installation geography segmentation dimensions across the projection horizon. CAGRs were derived from unit cost trajectory analysis and capital commitment visibility schedules. Forecast inputs incorporated FPSO orderbook conversion rates and subsea tree delivery lead times.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANP local content rule revisions and IBAMA environmental licensing timeline variability. Outputs reflect documented assumptions around pre-salt recovery factors and break-even oil price thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market