
 Middle East and Africa Offshore Energy Market | 2026-2036
Middle East and Africa Offshore Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Offshore Energy Market Foresight
Aftermarket service revenue is fragmenting across the Middle East and Africa Offshore Energy Market as operators defer greenfield capex and stretch asset life. Saudi Aramco leverages its integrated service arm to capture lifecycle contracts across the Arabian Gulf. TotalEnergies sustains competitive positioning through subsea technology leadership in West African deepwater. ExxonMobil anchors its regional presence via long-term production-sharing agreements in Nigerian offshore blocks.
Offshore energy encompasses hydrocarbon extraction and renewable power generation from submerged or floating installations in marine environments, typically operating at water depths from 30 meters to over 3,000 meters using steel-jacketed platforms, tension-leg systems, or semi-submersible hulls designed to withstand corrosive saltwater, cyclonic loading, and subsurface pressure regimes. The primary purpose centers on accessing hydrocarbon reservoirs and wind resources inaccessible from land-based infrastructure. Seismic imaging commands substantial upfront investment as operators prioritize pre-drilling risk reduction across frontier basins off Mozambique and Namibia. Subsea systems represent the fastest-expanding technology category as tieback architectures eliminate surface facility costs in marginal fields. Floating platforms dominate capital allocation in ultra-deepwater plays where fixed structures prove economically unviable.
Saudi Arabia's national petroleum regulator and South Africa's Petroleum Agency enforce environmental impact standards and decommissioning bonds that shape field development sequencing. Nigeria's Department of Petroleum Resources mandates local content thresholds that redirect procurement toward domestic fabrication yards and vessel operators. The EU Green Deal's carbon border adjustments and the International Maritime Organization's emission controls increasingly condition access to European offtake markets for regional LNG exports. Stakeholders must weigh stranded asset exposure against accelerated electrification timelines when committing to multi-decade offshore developments.
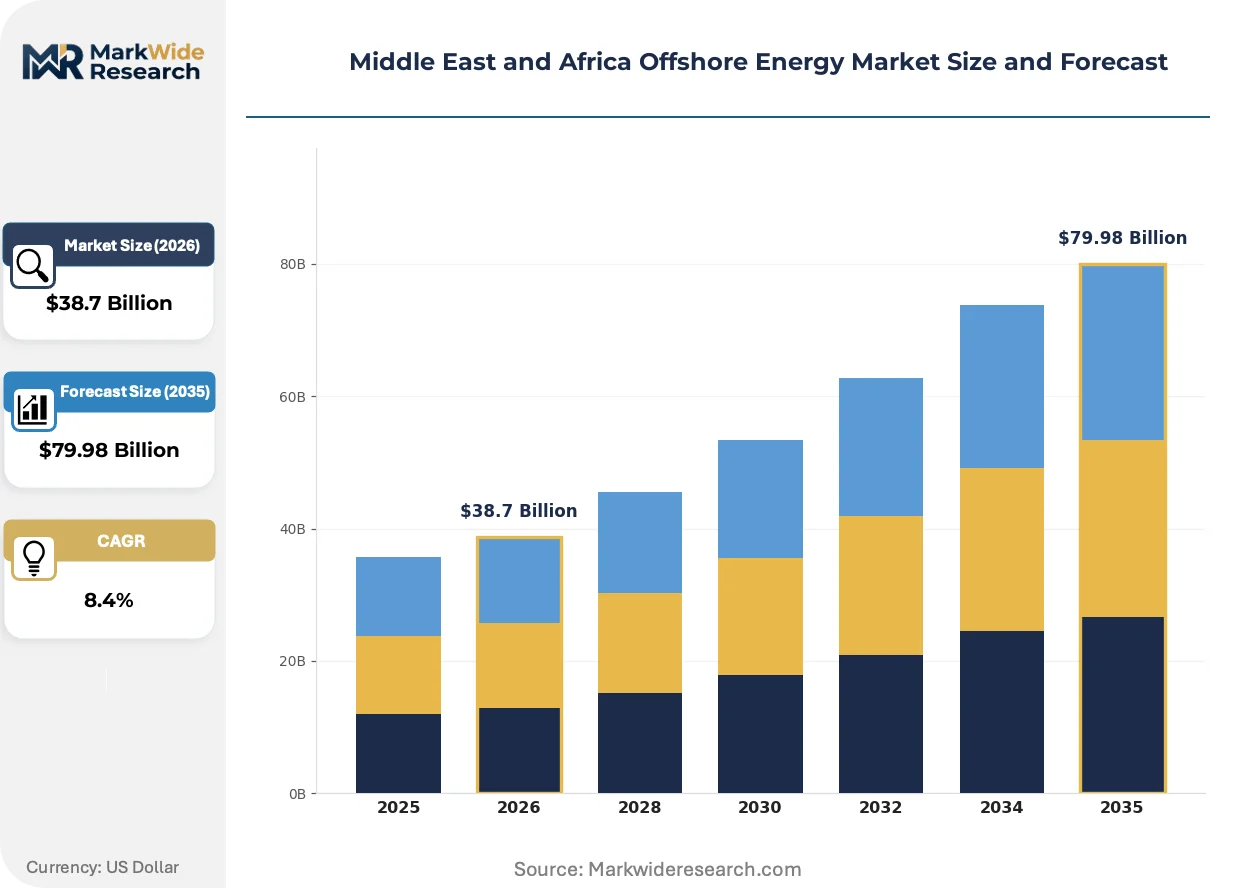
Market Dynamics
Floating platform technology advances are compressing breakeven economics in deepwater fields across the Arabian Gulf and West Africa, while Saudi Arabia and Nigeria tighten local content mandates that redirect procurement toward domestic fabrication yards.
Growth Catalysts
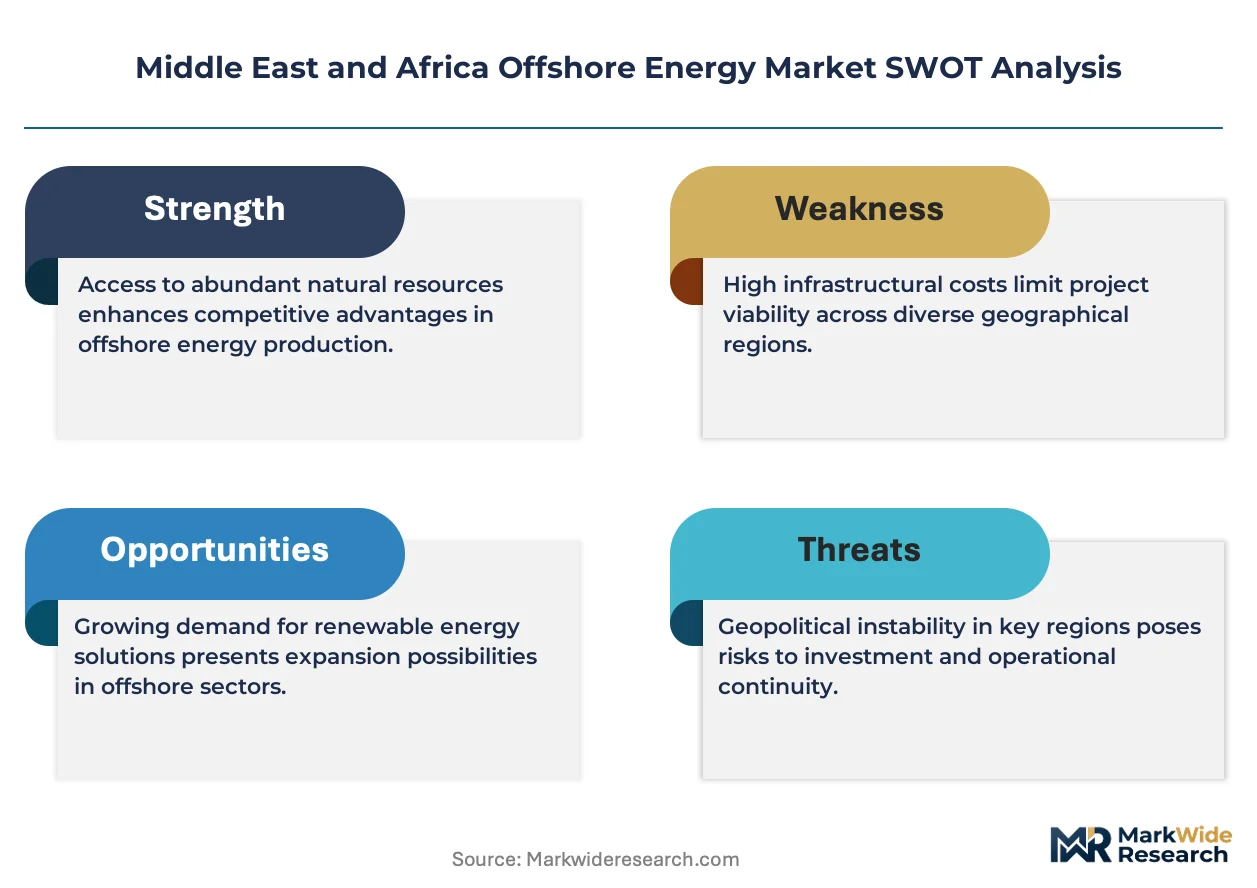
- Offshore wind mandates:South Africa's Renewable Energy Independent Power Producer Procurement Programme creates procurement obligations for coastal industrial zones seeking baseload alternatives to coal-fired grid supply.
- Subsea tieback architectures:Marginal field operators deploy subsea production systems to eliminate surface facility capital expenditure and extend field life in mature basins.
- EU Green Deal carbon border adjustments:European LNG offtake contracts increasingly condition access on emission intensity benchmarks, accelerating investment in carbon capture integration at Middle Eastern liquefaction terminals.
Market Restraints
- Steel cost volatility:Jacket platform fabrication depends on specialized high-strength steel grades subject to commodity price swings and long-lead procurement cycles from East Asian mills.
- Deepwater technical limitations:Pressure ratings and metallurgical constraints in ultra-deepwater blowout preventers restrict drilling access to reservoirs below 3,000 meters water depth in frontier basins off Mozambique.
- Decommissioning bond requirements:South Africa's Petroleum Agency mandates upfront financial assurance for platform removal that extends project payback periods and strains operator balance sheets.
Strategic Opportunities
- Namibian frontier basins:Underexplored deepwater blocks offer first-mover positioning for operators with proprietary seismic imaging and extended-reach drilling capabilities.
- Floating solar-wind hybrid platforms:Convergence of photovoltaic arrays with offshore wind turbines enables round-the-clock power generation for desalination and industrial load centers in the Arabian Gulf.
- Local content incentives:Nigeria's Department of Petroleum Resources procurement thresholds create captive demand for domestic vessel operators and subsea equipment fabricators.
Industry Challenges
- Subsea robotics technician shortage:Autonomous underwater vehicle maintenance and remote-operated vehicle piloting require specialized training pipelines that regional technical institutes have not scaled to meet.
- Legacy platform integration:Brownfield automation retrofits on aging steel-jacketed installations face cable routing constraints and topside weight limitations that complicate sensor deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Offshore Energy Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Maintenance, Decommissioning Technology: Seismic Imaging, Subsea Systems, Drilling Equipment, Floating Platforms End User: Oil Companies, Service Providers, Government Agencies, Research Institutions Installation: Onshore Facilities, Offshore Platforms, Marine Terminals, Subsea Infrastructure |
| Companies Covered | Nigerian National Petroleum Company Limited, ExxonMobil, Abu Dhabi National Oil Company, CNOOC, TotalEnergies, Saudi Aramco, General Electric, Petrobras, Chevron Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Offshore Energy Market Shifts & Advancements
Digital twin platforms and autonomous inspection systems are compressing operational expenditure curves while regulatory pressure on methane intensity and decommissioning liability reshapes capital allocation timelines across the region.
Subsea digital twin technology is digitizing reservoir-to-facility performance modeling by creating real-time virtual replicas of production systems. National oil companies in Saudi Arabia and integrated majors in Nigerian deepwater blocks are deploying these platforms to optimize artificial lift scheduling and predict equipment failure before intervention. This capability is digitizing maintenance workflows that previously required manned platform visits and extended production shutdowns.
Saudi Arabia's national petroleum regulator has implemented environmental impact assessment protocols that mandate continuous methane monitoring and third-party verification for all new offshore developments. The regulation compresses project sanction timelines by requiring baseline ecological surveys before seismic acquisition permits issue. Floating platform developers in the Arabian Gulf shallow-water blocks are responding by integrating optical gas imaging into platform design specifications to preempt compliance retrofit costs.
Integrated service contracting is displacing fragmented equipment procurement as national oil companies seek single-source accountability for subsea system performance. Saudi Aramco's lifecycle contracting model bundles engineering, procurement, construction, and installation with twenty-year maintenance obligations. This consolidation is most visible in the Arabian Gulf, where operators previously sourced risers, manifolds, and umbilicals from separate vendors with incompatible warranty terms.
Middle East and Africa Offshore Energy Market Segmentation
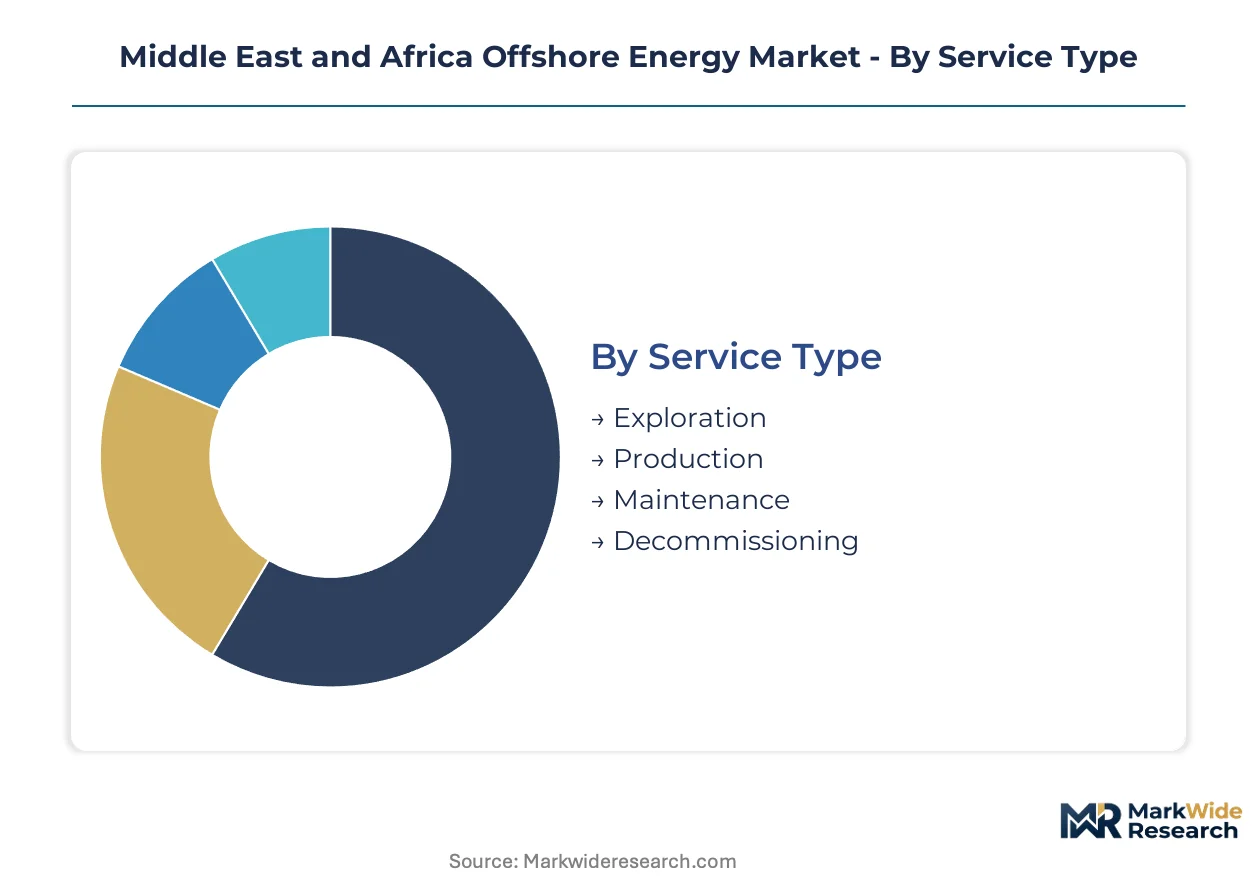
Segmentation of the Middle East and Africa Offshore Energy Market reveals divergent service intensities and technology adoption curves across the value chain. Understanding these divisions clarifies where capital concentrates and where lifecycle revenue pools form.
Service Type:
After-sales-service intensity varies sharply across the offshore energy lifecycle, with maintenance and decommissioning commanding sustained personnel deployment while exploration remains transaction-driven.
- Exploration:Seismic surveying and wildcat drilling operations demand specialized vessel charters and geophysical interpretation services. Nigerian operators concentrate exploration spending in the Niger Delta deepwater fairway where pre-salt imaging complexity drives proprietary technology acquisition.
- Production:Reservoir management and artificial lift operations generate recurring engineering demand across Saudi Arabia's Arabian Gulf shallow-water blocks. Dayrate contracts for floating production storage and offloading vessels anchor revenue visibility for integrated service providers.
- Maintenance:Brownfield integrity management and subsea intervention sustain aftermarket revenue streams.
- Decommissioning:Platform removal and site restoration obligations escalate as North Sea-equivalent liabilities migrate to African basins.
Production holds the largest share; momentum sits with decommissioning.
Technology:
Capital allocation across technology categories tracks water depth economics and reservoir complexity, with deeper plays demanding more sophisticated equipment packages.
- Seismic Imaging:Multi-azimuth and wide-azimuth acquisition systems resolve subsalt geometries in Mozambique's Rovuma Basin. Contractors deploy ocean-bottom node arrays where towed-streamer coverage proves inadequate for fractured carbonate targets.
- Subsea Systems:Manifolds, risers, and flowlines enable tieback architectures that eliminate surface facility capital in marginal West African fields. Electrically actuated wet-mate connectors reduce installation vessel time and improve recovery economics.
- Drilling Equipment:Managed pressure drilling systems and dual-gradient capabilities address narrow drilling windows.
- Floating Platforms:Semi-submersible hulls and tension-leg platforms unlock ultra-deepwater developments.
Subsea systems capture dominant investment; floating platforms are climbing the fastest as frontier basins mature.
End User:
Procurement authority and risk-bearing capacity distribute unevenly across stakeholder categories, shaping contract structures and payment terms.
- Oil Companies:International oil companies and national oil companies hold field equity and dictate technology specifications. Saudi Aramco's integrated project delivery model bundles long-term service obligations with initial capital deployment.
- Service Providers:Drilling contractors and subsea installation firms operate on fixed-price or dayrate arrangements with limited upside participation.
- Government Agencies:Petroleum regulators and environmental ministries enforce licensing conditions and local content thresholds.
- Research Institutions:Universities and national laboratories contribute geophysical interpretation and materials testing capabilities.
Oil companies retain procurement dominance; service providers face margin compression from integrated contracting trends.
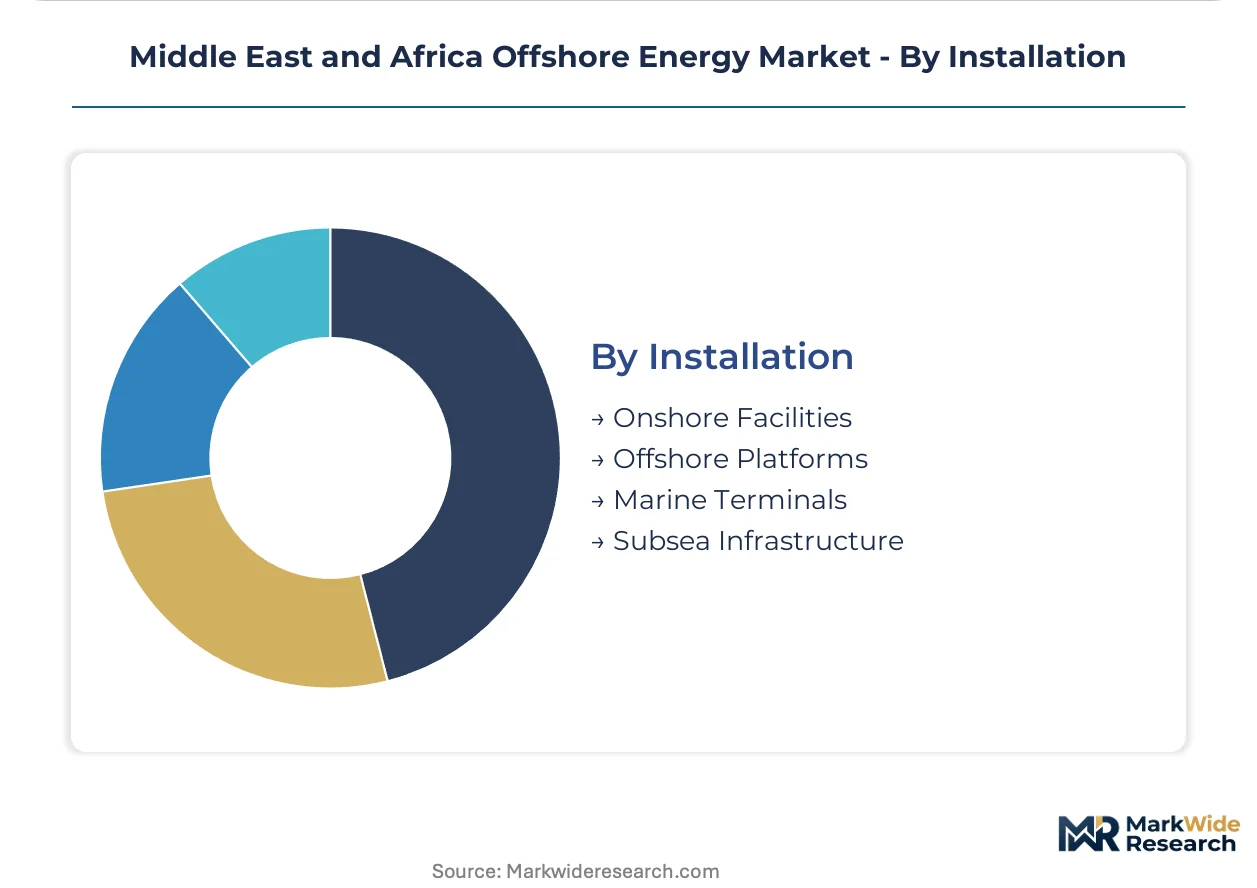
Installation:
Physical asset location determines supply chain logistics, regulatory jurisdiction, and exposure to marine operational risks.
- Onshore Facilities:Fabrication yards and module assembly sites in Nigeria and the UAE supply jacket platforms and topside modules. Local content mandates redirect procurement toward domestic yards with limited heavy-lift capacity.
- Offshore Platforms:Fixed steel jackets dominate Saudi Arabia's shallow-water developments while floating systems proliferate in West African deepwater.
- Marine Terminals:Single-point mooring systems and offshore loading buoys handle crude export logistics.
- Subsea Infrastructure:Pipelines, umbilicals, and manifolds form production networks that extend field life without surface facility expansion.
Offshore platforms represent the largest installed base; subsea infrastructure shows the steepest expansion trajectory as tieback economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Nigeria and Angola exhibit acute price sensitivity as low-margin operators stretch field economics, while Saudi Arabian and UAE national oil companies absorb premium technology costs without volume elasticity.
Saudi Arabia
Arabian Gulf shallow-water redevelopment and offshore gas expansion drive sustained equipment procurement. The national petroleum regulator mandates continuous methane monitoring and third-party environmental verification before seismic permits issue. Ras Tanura fabrication clusters anchor jacket platform construction for domestic and regional export markets.
Nigeria
Niger Delta deepwater tieback projects and marginal field rehabilitation sustain subsea system demand. The Department of Petroleum Resources enforces local content thresholds redirecting vessel and fabrication procurement toward domestic yards. Lagos-anchored fabrication clusters supply jacket platforms and topside modules under accelerated permitting timelines.
United Arab Emirates
Upper Zakum offshore expansion and sour gas development sustain long-term production infrastructure demand. ADNOC's integrated project delivery model bundles engineering, procurement, and installation with multi-decade maintenance obligations. Abu Dhabi fabrication yards supply modular platform components for Arabian Gulf developments.
South Africa
Renewable Energy Independent Power Producer Procurement Programme obligations for coastal industrial zones create offshore wind procurement mandates. The Petroleum Agency requires upfront decommissioning bonds extending project payback periods for hydrocarbon developments. Cape Town marine engineering clusters service subsea robotics and autonomous inspection system deployment.
Mozambique
Rovuma Basin deepwater gas discoveries and LNG export terminal construction sustain frontier basin exploration spending. Multi-azimuth seismic acquisition permits require baseline ecological surveys compressing exploration timelines. Maputo technical service clusters support ocean-bottom node deployment and geophysical interpretation for subsalt imaging.
Middle East and Africa Offshore Energy Market Competitive Landscape
Capability concentration sits with integrated national oil companies commanding lifecycle service bundling; scale advantage sits with international majors deploying proprietary subsea technology across multiple basins. The vendor structure stratifies into three tiers: state-backed national champions with captive domestic demand, integrated majors leveraging technology leadership for production-sharing access, and specialized service contractors operating on fixed-price dayrate arrangements. Competitive positioning hardens around integrated service contracting and local content compliance capabilities.
Within the national champion tier, Saudi Aramco and Nigerian National Petroleum Company Limited exemplify state-backed operators capturing lifecycle revenue through integrated project delivery. Among international majors, TotalEnergies occupies a position exemplifying subsea technology leadership in West African deepwater, while ExxonMobil anchors its regional presence through long-term production-sharing agreements in Nigerian offshore blocks.
| Leading Market Players |
|---|
| Nigerian National Petroleum Company Limited |
| ExxonMobil |
| Abu Dhabi National Oil Company |
| CNOOC |
| TotalEnergies |
| Saudi Aramco |
| General Electric |
| Petrobras |
| Chevron Corporation |
| Others |
Supply & Pricing Matrix
Ras Tanura fabrication clusters anchor jacket platform construction capacity for the Arabian Gulf, concentrating supply-side leverage among Saudi Aramco's integrated service arm and compressing margins for independent equipment vendors competing on aftermarket contracts.
Pricing Analysis
Extended maintenance contracts and lifecycle service agreements capture the dominant share of lifetime value as operators defer greenfield capital expenditure. Three-tier pricing structure across integrated service bundling, standalone equipment procurement, and spot repair services reflects differentiation by local content compliance depth and technology certification tier. Pricing pressure stems from Nigerian and Angolan operators stretching asset economics in marginal field rehabilitation. International oil companies exhibit lowest price sensitivity; domestic fabrication yards face acute cost compression.
Supply Chain Analysis
Lamprell and UAE-based engineering contractors hold concentrated capacity for modular platform fabrication and topside integration. High-strength steel plate draws from East Asian mills, subsea umbilicals feed from European specialist manufacturers, and drilling riser systems hinge on U.S. Gulf Coast forging capacity. Single-source vulnerability in blowout preventer metallurgy creates procurement chokepoints for ultra-deepwater developments. Distribution runs through national oil company tender processes and integrated project delivery frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in aftermarket service tiers as deferred capital expenditure and stretched asset life create niches for specialized maintenance and decommissioning contractors.
For Market Incumbents: Harden integrated service contracting capabilities to preempt margin erosion from standalone equipment vendors. Deepen backward integration into subsea robotics maintenance and autonomous inspection system deployment. Capture lifecycle revenue through twenty-year maintenance obligations bundled with initial capital deployment, neutralizing emerging specialist contractors competing on spot repair dayrates.
For New Entrants and Emerging Players: Namibian frontier basin geophysical interpretation and ocean-bottom node deployment represent the most penetrable entry point given limited incumbent seismic imaging presence. Nigerian domestic vessel operations under local content mandates offer second-tier opportunity through joint venture structures with established fabrication yards. Lead with proprietary extended-reach drilling technology licensing to secure production-sharing participation without full capital burden.
For Investors and Strategic Acquirers: Long-term, this sits as a decommissioning liability play because North Sea-equivalent platform removal obligations are migrating to African basins with limited local technical capacity. Target mid-cap subsea intervention specialists with established relationships to Nigerian National Petroleum Company Limited and Angola's national oil company. Monitor decommissioning bond requirement tightening by South Africa's Petroleum Agency as inflection signal for accelerated liability recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Saudi Aramco's lifecycle bundling eliminates warranty fragmentation and captures twenty-year revenue visibility. |
| Carbon Capture Integration | EU Green Deal emission benchmarks condition Middle Eastern liquefaction terminal access and reshape capital allocation. |
| Subsea Robotics Capability Buildout | Autonomous underwater vehicle maintenance addresses technician shortage constraining West African deepwater operations. |
| Local Content Joint Ventures | Nigerian Department of Petroleum Resources procurement thresholds redirect vessel charter revenue toward domestic operators. |
| Floating Platform Technology Licensing | Semi-submersible hull designs unlock ultra-deepwater economics in Mozambique's Rovuma Basin frontier plays. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with offshore project engineers, subsea equipment procurement leads, national oil company planning officers, and marine fabrication yard managers; and secondary validation through EIA international energy statistics, IEA offshore investment outlooks, FERC LNG export filings, and project development database tracking across the Arabian Gulf and West African basins. Bottom-up field-level production estimates and top-down regional expenditure surveys underwent iterative triangulation.
Forecast inputs incorporated water depth economics, reservoir complexity tiers, and regulatory compliance cost escalation across the projection horizon. Segmentation dimensions modeled include service type intensity, technology category capital allocation, end-user procurement authority, and installation location supply chain logistics. CAGRs derived from regression analysis against historical offshore sanctioning patterns and Brent crude price sensitivity bands.
Macroeconomic conditions sit as an overlay; deviation in Brent crude futures curves and East Asian steel plate pricing would shift the trajectory. Forecasts reflect assumptions on local content mandate enforcement continuity and EU carbon border adjustment implementation timing. Quarterly review of Saudi Aramco and ADNOC tender issuance patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
FPSO Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market