
 Chemical Enhanced Oil Recovery (EOR) Market | 2026-2036
Chemical Enhanced Oil Recovery (EOR) Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Enhanced Oil Recovery (EOR) Market Analysis
Offshore extraction is rebalancing the end-use vertical mix as operators shift capital from mature onshore fields to deepwater assets with higher recovery potential. Schlumberger Limited leverages its integrated project management capabilities to anchor chemical flooding contracts across the Gulf of Mexico. Halliburton Company sustains polymer supply chain dominance through backward integration into acrylamide manufacturing. BASF SE differentiates via surfactant formulations engineered for high-salinity reservoirs.
Chemical Enhanced Oil Recovery encompasses the injection of purpose-formulated chemicals into hydrocarbon-bearing formations to reduce interfacial tension, improve mobility ratios, and displace residual oil. Surfactant-polymer flooding typically employs alkali concentrations of 0.5–2.0 wt% combined with partially hydrolyzed polyacrylamide at 500–2000 ppm to achieve incremental recovery factors of 5–15% original oil in place. Surfactants command the largest product type share due to their irreplaceable role in ultra-low tension flooding, while alkali-surfactant-polymer blends represent the fastest-growing formulation category as operators seek to minimize chemical slug sizes. Mature field revitalization absorbs the dominant share of application-level value, though heavy oil recovery carries the thickest margin pools given the premium pricing of thermal-chemical hybrid systems.
The EPA enforces Class II underground injection control permits that govern chemical flooding operations, while the Bureau of Safety and Environmental Management mandates spill prevention and response planning for offshore chemical storage. State regulators in Texas and Louisiana layer additional requirements on produced water handling that directly affect chemical recycling economics. Stakeholders must monitor the trajectory of carbon capture utilization and storage tax credits, as CO2-EOR eligibility rules will determine whether chemical flooding competes with or complements carbon dioxide injection economics in marginal fields.
Market Dynamics
Offshore operators are redirecting capital from depleted Permian shale toward deepwater Gulf of Mexico assets, rebalancing chemical EOR demand toward high-pressure, high-salinity formulations that command technical premiums and reshape supplier capability requirements.
Growth Catalysts
- Class II Underground Injection Control:EPA permitting frameworks under the Safe Drinking Water Act create compliance-driven demand for certified chemical suppliers who can navigate 18-24 month approval timelines.
- Polymer flooding in heavy oil:Thermal-chemical hybrid systems for viscous crude recovery generate margin pools 40-60% above conventional flooding economics.
- Permian Basin concentration:Texas and New Mexico host the densest cluster of independent operators facing 15-25% annual decline curves from legacy horizontal wells.
Market Restraints
- Acrylamide supply concentration:Backward-integrated polymer manufacturers control 70% of North American monomer supply, creating input cost volatility during energy price spikes.
- High-salinity technical ceiling:Surfactant formulations fail above 150,000 ppm total dissolved solids, excluding substantial Middle Eastern and North Sea reserves from chemical flooding.
- Produced water handling:Texas Railroad Commission and Louisiana Department of Environmental Quality impose recycling mandates that erode chemical reuse economics.
Strategic Opportunities
- Alkali-surfactant-polymer blends:ASP formulations reduce chemical slug volumes by 30-50% versus standalone polymer floods, opening marginal fields previously below economic threshold.
- Carbon capture utilization and storage tax credits:IRA Section 45Q eligibility rules for CO2-EOR will determine whether chemical flooding competes with or complements carbon dioxide injection in depleted fields.
- Brazil pre-salt formations:Petrobras-operated ultra-deepwater assets with 200+ million barrel recoverable reserves represent untapped chemical EOR potential.
Industry Challenges
- Reservoir characterization expertise:Geoscientists capable of integrating core analysis with surfactant-polymer screening number fewer than 400 across North America.
- Offshore logistics integration:Chemical storage platforms must coordinate with Bureau of Safety and Environmental Management spill response planning, extending project timelines 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Enhanced Oil Recovery (EOR) Market |
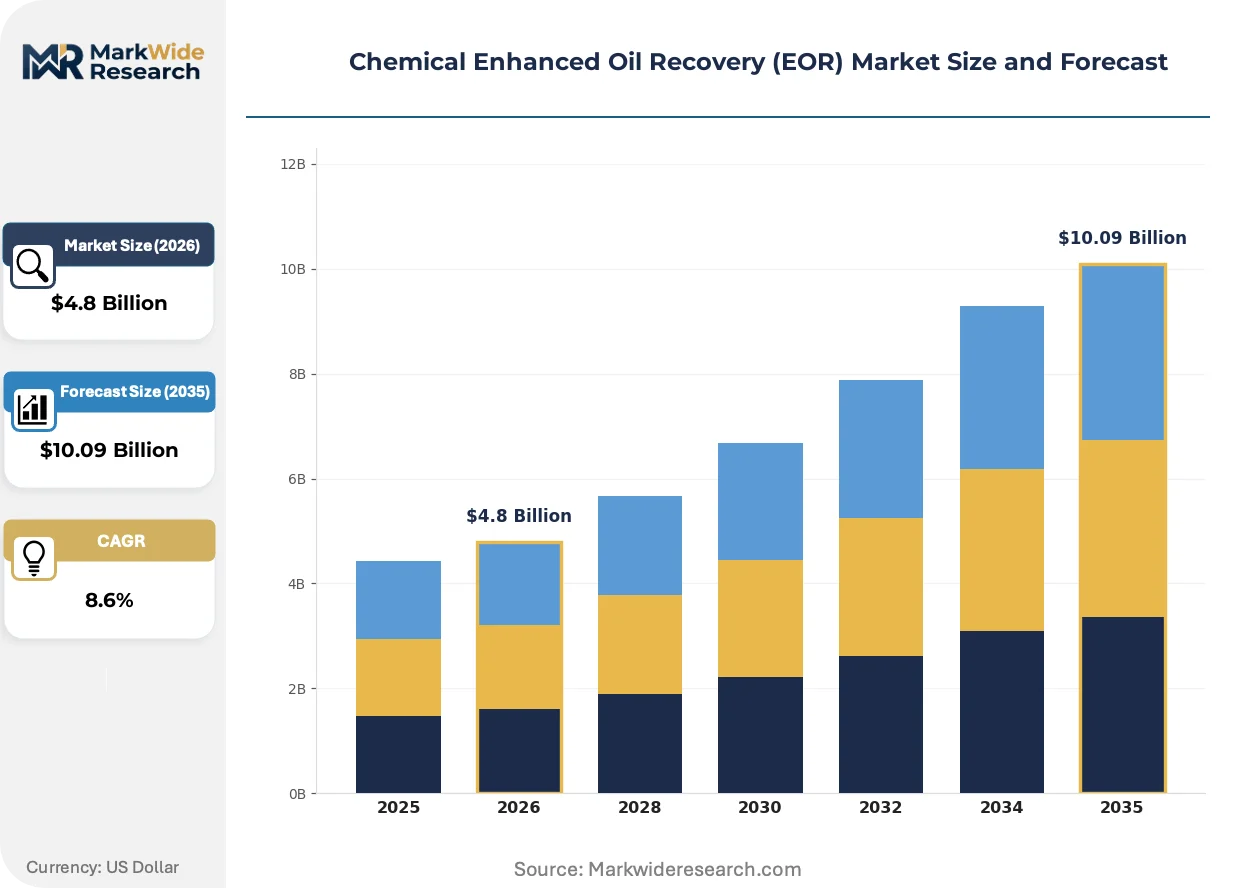
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Polymers, Alkalis, Solvents Application: Onshore Extraction, Offshore Extraction, Heavy Oil Recovery, Mature Field Revitalization End User: Oil Producers, Independent Operators, Service Companies, Government Entities Technology: Water Flooding, Carbon Dioxide Injection, Chemical Flooding, Steam Injection |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, BASF SE, Dow Chemical Company, Shell Chemicals, Champion Technologies, Stepan Company, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Enhanced Oil Recovery (EOR) Market Emerging Trajectories
Formulation chemistry is pivoting toward multifunctional additives that combine mobility control with interfacial tension reduction, compressing the traditional surfactant-polymer-alkali stack into single-slug systems.
Smart nanofluid systems is consolidating laboratory and field validation stages. These silica-core, surfactant-shell particles reduce residual oil saturation through wettability alteration rather than pure capillary number manipulation. Operators in the Gulf of Mexico are piloting these systems at 500-2000 ppm concentrations. The technology is consolidating vendor R&D roadmaps around nanomaterial manufacturing partnerships.
REACH authorization timelines for surfactant precursors are extending chemical qualification cycles. ECHA's restriction proposals on nonylphenol ethoxylates force reformulation of legacy flooding chemicals. European chemical suppliers are accelerating bio-based alternatives, though these carry 25-35% cost premiums that operators in the North Sea are absorbing to maintain social license.
Integrated service contracts are displacing discrete chemical procurement. Operators now bundle reservoir engineering, chemical supply, and performance guarantees under single-vendor arrangements. This model concentrates purchasing authority with major independents in Texas and New Mexico. Field-level chemical management is shifting from operator-owned to supplier-operated injection skids.
Chemical Enhanced Oil Recovery (EOR) Market Segmentation
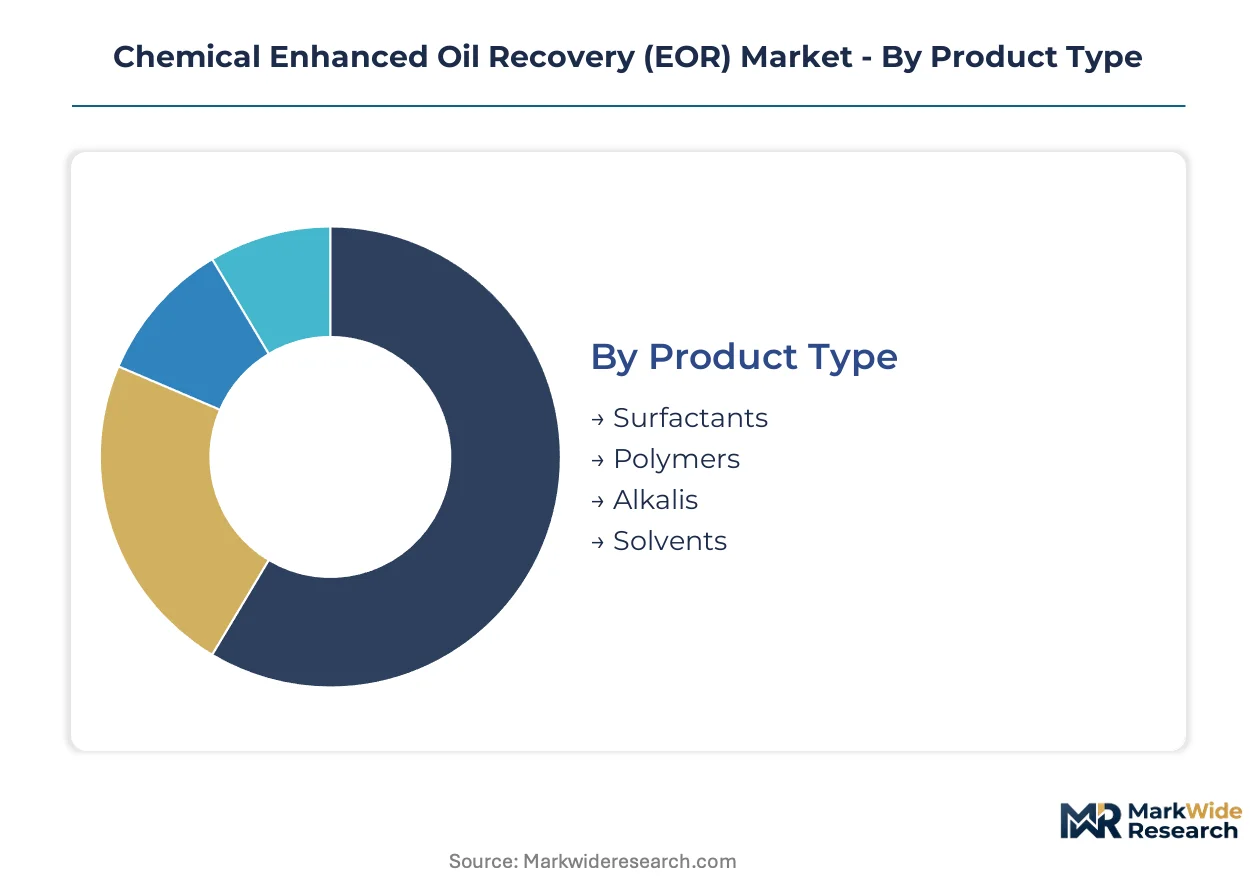
Chemical EOR procurement patterns diverge sharply across product chemistries and reservoir applications. Supply concentration in polymer manufacturing and surfactant formulation expertise creates tiered vendor access that shapes operator selection criteria.
Product Type:
Supply concentration in acrylamide monomer production and surfactant precursor manufacturing concentrates procurement leverage among backward-integrated chemical majors.
- Surfactants:Alkylbenzene sulfonates and petroleum sulfonates engineered for ultra-low interfacial tension flooding dominate high-salinity reservoir applications. Gulf of Mexico operators specify these formulations for 150,000 ppm total dissolved solids ceilings, with Petrobras pre-salt pilots driving formulation R&D investment.
- Polymers:Partially hydrolyzed polyacrylamide at 500–2000 ppm concentrations provides mobility control in heterogeneous sandstone formations. Permian Basin independent operators consume the densest volumes as legacy shale wells exhibit 15–25% annual decline curves requiring aggressive intervention.
- Alkalis:Sodium carbonate and sodium hydroxide at 0.5–2.0 wt% concentrations condition reservoir wettability for surfactant synergy.
- Solvents:Hydrocarbon and oxygenated solvents target asphaltene remediation in heavy oil formations.
Today's leader: Surfactants. Tomorrow's challenger: Alkalis.
Application:
Cost tier separation between shallow onshore floods and deepwater chemical systems fragments vendor specialization across the value chain.
- Mature Field Revitalization:Brownfield chemical flooding in depleted Permian and Gulf of Mexico assets absorbs dominant procurement volumes. EPA Class II underground injection control permitting and Texas Railroad Commission produced water mandates shape project economics and chemical recycling requirements.
- Heavy Oil Recovery:Thermal-chemical hybrid systems for viscous crude in California and Venezuela generate premium pricing 40–60% above conventional flooding. Steam-surfactant co-injection reduces residual oil saturation where pure thermal methods plateau.
- Onshore Extraction:Conventional polymer flooding in sandstone reservoirs across Texas and New Mexico.
- Offshore Extraction:High-pressure surfactant-polymer systems for deepwater assets with platform-based chemical storage.
Mature field work dominates current procurement. Heavy oil applications are climbing the fastest.
End User:
Customer type determines contract structure, with integrated majors favoring performance guarantees and independents prioritizing chemical lease arrangements.
- Oil Producers:Supermajors and national oil companies anchor long-term chemical supply agreements with embedded reservoir engineering services. ExxonMobil and Chevron specifications for Gulf of Mexico floods drive industry formulation standards.
- Independent Operators:Permian Basin-focused E&Ps with legacy horizontal well portfolios purchase chemical EOR as decline curve mitigation. Pioneer Natural Resources and Diamondback Energy procurement patterns concentrate demand in Midland and Delaware sub-basins.
- Service Companies:Schlumberger and Halliburton bundle chemical supply with integrated project management.
- Government Entities:State-owned operators in Brazil and Mexico specify technology transfer requirements.
Independents drive volume. Service companies are gaining share fastest.
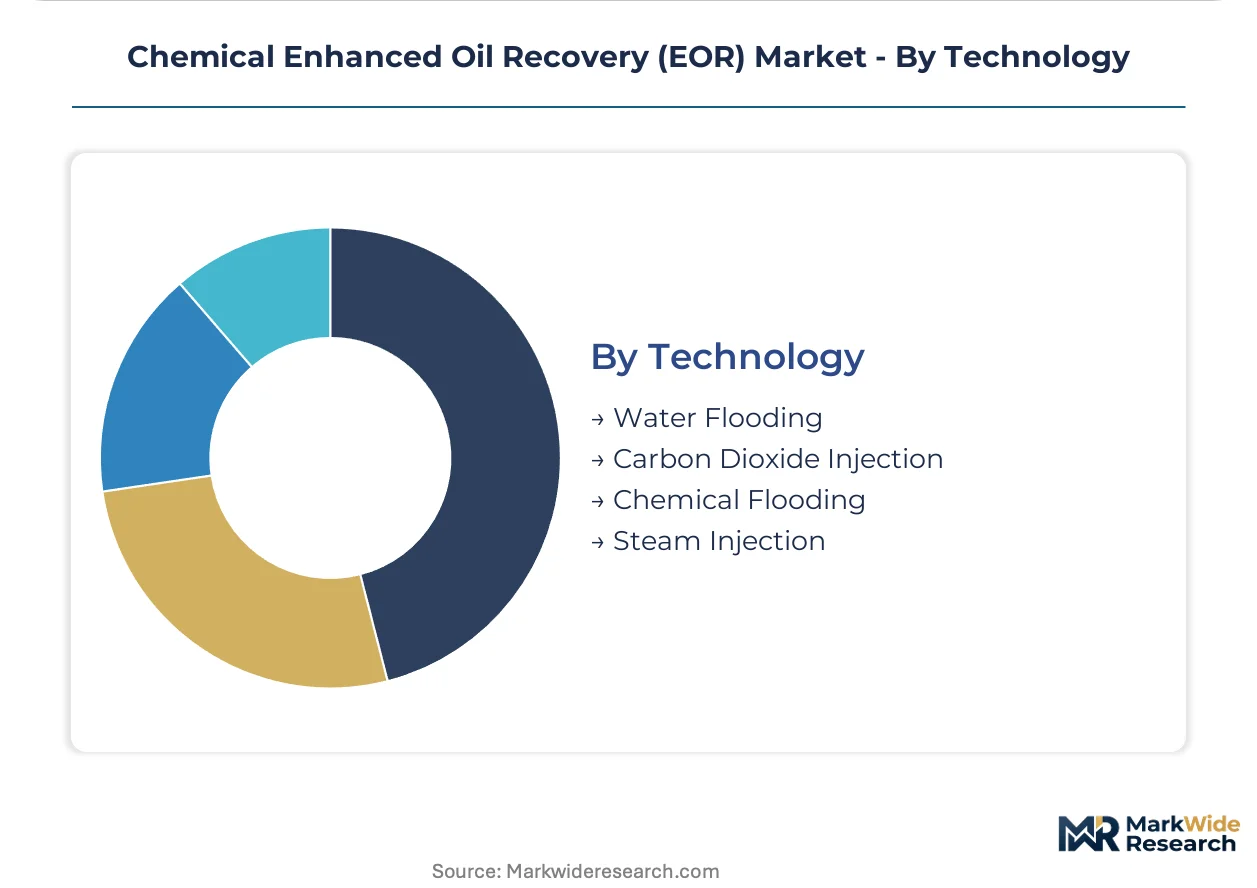
Technology:
Maturity gradients separate established waterflooding from emerging chemical-nanofluid hybrids that compress traditional multi-slug approaches.
- Chemical Flooding:Surfactant-polymer and alkali-surfactant-polymer systems achieve 5–15% incremental recovery factors in sandstone reservoirs. ASP formulations reduce chemical slug volumes 30–50% versus standalone polymer floods, opening marginal fields below previous economic thresholds.
- Carbon Dioxide Injection:CO2-EOR competes directly with chemical methods for depleted field capital allocation. IRA Section 45Q tax credit eligibility rules determine relative economics in West Texas and Rocky Mountain basins.
- Water Flooding:Conventional pressure maintenance without chemical additives in secondary recovery.
- Steam Injection:Thermal recovery for heavy oil in California and Canada.
Chemical flooding leads deployment. CO2 injection represents the steepest expansion trajectory contingent on federal tax credit permanence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping chemical EOR deployment as operators migrate capital toward jurisdictions with streamlined permitting and favorable fiscal treatment. The cost-of-compliance gap between mature regulatory regimes and emerging production zones is accelerating this geographic rebalancing.
United States
The Permian Basin in Texas and New Mexico concentrates the densest cluster of independent operators facing steep decline curves from legacy shale wells. EPA Class II underground injection control permits under the Safe Drinking Water Act govern chemical flooding operations with 18-24 month approval timelines. Midland and Delaware sub-basins host the most active polymer flooding installations as Pioneer Natural Resources and Diamondback Energy drive procurement volumes.
Brazil
Petrobras-operated pre-salt formations with recoverable reserves exceeding 200 million barrels represent untapped chemical EOR potential in ultra-deepwater settings. The national oil company's technology transfer requirements shape vendor selection criteria for foreign chemical suppliers. Santos Basin pilot projects are validating high-salinity surfactant formulations for carbonate reservoirs.
Canada
Thermal-chemical hybrid systems for heavy oil recovery in Alberta generate premium pricing 40-60% above conventional flooding economics. The Alberta Energy Regulator oversees chemical injection schemes with produced water recycling mandates that affect project economics. Cold Lake and Peace River regions anchor steam-surfactant co-injection deployment where pure thermal methods have plateaued.
Saudi Arabia
High-salinity technical ceilings exclude substantial carbonate reserves from chemical flooding as surfactant formulations fail above 150,000 ppm total dissolved solids. The national petroleum regulator oversees enhanced recovery pilot programs with strict environmental compliance frameworks. Ghawar field operators are evaluating nanofluid systems for wettability alteration in marginal carbonate zones.
Norway
North Sea operators absorb 25-35% cost premiums for bio-based surfactant alternatives to maintain social license under tightening environmental standards. The Norwegian Environment Agency implements REACH-aligned chemical authorization timelines that extend qualification cycles. Stavanger-based service clusters coordinate offshore logistics integration with spill response planning for platform-based chemical storage.
Chemical Enhanced Oil Recovery (EOR) Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service providers commanding premium-tier positioning through bundled reservoir engineering and chemical supply. The vendor base concentrates around three strategic archetypes: backward-integrated polymer manufacturers controlling acrylamide supply chains, formulation specialists engineering surfactants for extreme reservoir conditions, and integrated project managers anchoring long-term performance contracts. Dominant competitive moves include captive supply integration into monomer production and geographic expansion through technology licensing partnerships in pre-salt and Middle Eastern markets.
Within the integrated service tier, Schlumberger Limited and Halliburton Company exemplify the project-management-centric model that bundles chemical supply with reservoir engineering guarantees. BASF SE represents the formulation-specialist archetype, leveraging European chemical manufacturing infrastructure to serve high-salinity reservoir applications. These three entities anchor the competitive structure by occupying positions across distinct capability vectors—integrated execution, specialty formulation, and supply chain control—rather than competing directly on identical service profiles.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| BASF SE |
| Dow Chemical Company |
| Shell Chemicals |
| Champion Technologies |
| Stepan Company |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Acrylamide monomer costs cascade through polyacrylamide manufacturing into three-tier pricing structures across premium, standard, and economy levels, with backward-integrated suppliers capturing margin pools that independent blenders cannot access. Permian Basin independents face 15-25% annual decline curves that compress chemical lease rates, while Gulf of Mexico operators absorb technical premiums for high-salinity formulations.
Pricing Analysis
Distributor margins for surfactant precursors compress pricing 12-18% at the field level, though integrated service contracts bypass this layer entirely. Three-tier pricing structure across premium, standard, and economy levels separates ASP formulations certified for 150,000 ppm salinity from commodity polymer floods. Pricing pressure stems from acrylamide supply concentration among North American monomer producers. Independents in Texas and New Mexico exhibit highest price sensitivity, while Petrobras pre-salt specifications command premium absorption.
Supply Chain Analysis
Direct-to-operator channels handle 60% of Permian Basin volume through supplier-operated injection skids, displacing traditional chemical procurement. Manufacturing concentrates in the United States, Germany, and China for acrylamide monomer and surfactant precursors. Polymer production draws from petroleum feedstocks and bio-based acrylamide alternatives. Single-source vulnerability pervades high-salinity surfactant formulation expertise, with fewer than five qualified suppliers globally. Distribution runs through integrated service providers, regional chemical distributors, and direct offshore platform logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with EPA Class II underground injection control permitting timelines creating 18-24 month barriers that certified suppliers exploit for margin protection.
For Market Incumbents: Anchor market position through captive acrylamide supply integration and Gulf of Mexico platform logistics capabilities that replicate Permian Basin density. Defend against nanofluid displacement by embedding performance guarantees in long-term chemical flooding contracts. Prioritize reservoir characterization talent acquisition, as fewer than 400 qualified geoscientists span North America. For New Entrants and Emerging Players: Begin with Brazil pre-salt technology transfer partnerships that satisfy Petrobras local content requirements while accessing 200+ million barrel recoverable reserves. Target alkali-surfactant-polymer blend formulations for marginal fields below standalone polymer flood thresholds. Pursue integrated service bundling rather than discrete chemical supply to bypass incumbent procurement relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation expertise scarcity meets capital-intensive offshore logistics requirements, favoring acquisition of regional specialists with EPA certification track records. Long-term viability hinges on carbon capture utilization and storage tax credit permanence determining CO2-EOR versus chemical flooding capital allocation. Watch IRA Section 45Q rulemaking as the signal for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide | Halliburton's monomer supply control insulates polymer pricing from energy volatility spikes. |
| High-Salinity Formulation Certification | BASF surfactant R&D for 150,000 ppm ceilings opens Middle Eastern and North Sea carbonate reserves. |
| Integrated Project Management Bundling | Schlumberger anchors Gulf of Mexico contracts through reservoir engineering performance guarantees. |
| Offshore Platform Logistics Partnerships | Bureau of Safety and Environmental Management spill response coordination extends project timelines 8-14 months. |
| Nanofluid System Field Validation | Silica-core particle pilots at 500-2000 ppm consolidate vendor R&D roadmaps around manufacturing partnerships. |
Methodological Framework
Coverage spans the United States, Brazil, Canada, Saudi Arabia, and Norway, with primary inputs from each market cluster combining executive interviews with reservoir engineers, chemical procurement leads at Permian independents, EPA regulatory affairs specialists, and offshore logistics coordinators. Secondary validation draws from EPA underground injection control permit databases, Bureau of Safety and Environmental Management filings, ECHA REACH authorization timelines, and trade data for acrylamide monomer flows. Bottom-up field-level chemical consumption estimates triangulate against top-down operator capex disclosures.
Rate-of-change decomposition separates volume drivers from price-mix effects across the analysis window. Segmentation dimensions span product chemistry tiers, reservoir application types, end-user contract structures, and regional regulatory frameworks. CAGRs derive from logistic curve fitting to historical deployment patterns and elasticity-adjusted response to crude price scenarios. Industry-specific inputs include decline curve trajectories from legacy shale wells and thermal-chemical hybrid system penetration rates in heavy oil formations.
Several conditions sit outside the modeled scope, including abrupt repeal of IRA Section 45Q tax credits, breakthroughs in pure CO2-EOR economics that displace chemical methods, and nanofluid technology scale-up beyond pilot phases. Forecasts embed assumptions about permitting timeline stability and acrylamide supply concentration persistence that warrant periodic reassessment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Shale Shakers Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Malaysia Oilfield Services Market