
 Ecuador Oil and Gas Downstream Market | 2026-2036
Ecuador Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Ecuador Oil and Gas Downstream Market Foresight
Transport fleets is rotating toward higher-volume fuel purchasing contracts as fuel retailers cede share in the buyer mix. EP Petroecuador anchors national refining capacity through its control of the Esmeraldas refinery complex. Petroamazonas EP leverages upstream crude allocations to secure feedstock priority for domestic processing. OCP Ecuador operates the heavy crude pipeline linking Amazonian production to Pacific export terminals, sustaining throughput economics for coastal refiners.
Ecuador oil and gas downstream encompasses crude oil refining, petrochemical conversion, and finished product distribution through pipeline, marine, and road networks, with refining units typically processing Napo heavy crude at API gravities below 20 degrees. The sector's primary purpose is transforming extracted hydrocarbons into transport fuels, industrial feedstocks, and construction materials for domestic consumption and export. Refined petroleum dominates product type output as the mature revenue base, while specialty chemicals captures expanding margin pools from industrial diversification. Fuel distribution leads application throughput by volume, though additive blending is gaining traction as specification standards tighten.
Ecuador's Ministry of Energy and Non-Renewable Natural Resources sets downstream pricing and product quality mandates, while the country's environmental regulator enforces refinery emissions thresholds that shape capital allocation toward sulfur recovery and wastewater treatment. Compliance with these frameworks determines refinery operating permits and access to coastal export quotas. Stakeholders must monitor feedstock slate flexibility and regulatory enforcement intensity as the decisive variables for facility-level profitability.
Market Dynamics
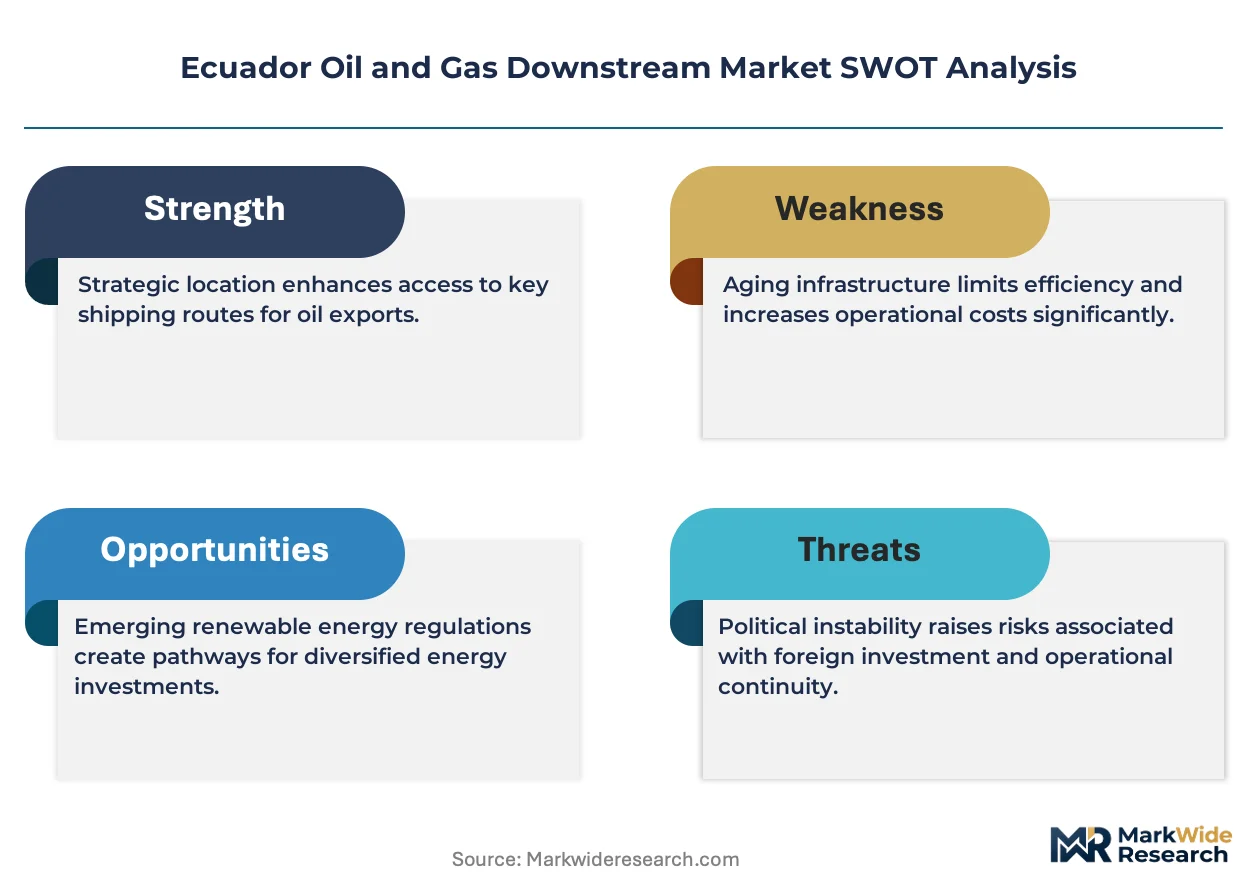
EP Petroecuador's monopoly over the Esmeraldas refinery complex concentrates national refining capacity, forcing private distributors to compete on logistics efficiency rather than processing margin.
Growth Catalysts
- Fleet Modernization Mandates:Transport operators are retiring aging diesel units and expanding LPG-compatible vehicle purchases, tightening fuel quality specifications issued by Ecuador's Ministry of Energy and Non-Renewable Natural Resources.
- Pipeline Terminal Expansion:OCP Ecuador's heavy crude pipeline infrastructure sustains throughput economics for coastal refiners, anchoring feedstock security for Pacific-facing processing facilities.
- Cleaner Product Slate Requirements:Sulfur recovery and wastewater treatment investments are accelerating as the country's environmental regulator enforces emissions thresholds for refinery operating permits.
Market Restraints
- Single-Refinery Concentration:National processing capacity depends entirely on the Esmeraldas complex, creating supply vulnerability to unplanned maintenance or feedstock disruptions.
- Napo Heavy Crude Processing Constraints:Refining units configured for API gravities below 20 degrees face limited flexibility to process lighter domestic or imported crudes during price arbitrage windows.
- Import Dependency for Specialty Products:Petrochemical conversion capacity gaps force reliance on foreign supply for industrial feedstocks and construction material precursors.
Strategic Opportunities
- Additive Blending Infrastructure:Fuel retailers can capture margin expansion by investing in specification-grade blending capabilities as quality mandates tighten across the coastal refining corridor.
- Guayaquil Maritime Hub Development:Port terminal modernization offers throughput expansion for refined product exports to regional Pacific markets.
- Industrial Diversification into Specialty Chemicals:Petrochemical conversion investments can access expanding margin pools from construction and manufacturing feedstock demand.
Industry Challenges
- Refinery Emissions Compliance Timelines:Sulfur recovery unit upgrades and wastewater treatment overhauls require capital deployment against compressed permitting deadlines.
- Feedstock Slate Flexibility Engineering:Processing units designed for Napo heavy crude require significant reconfiguration to handle alternative crude grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecuador Oil and Gas Downstream Market |
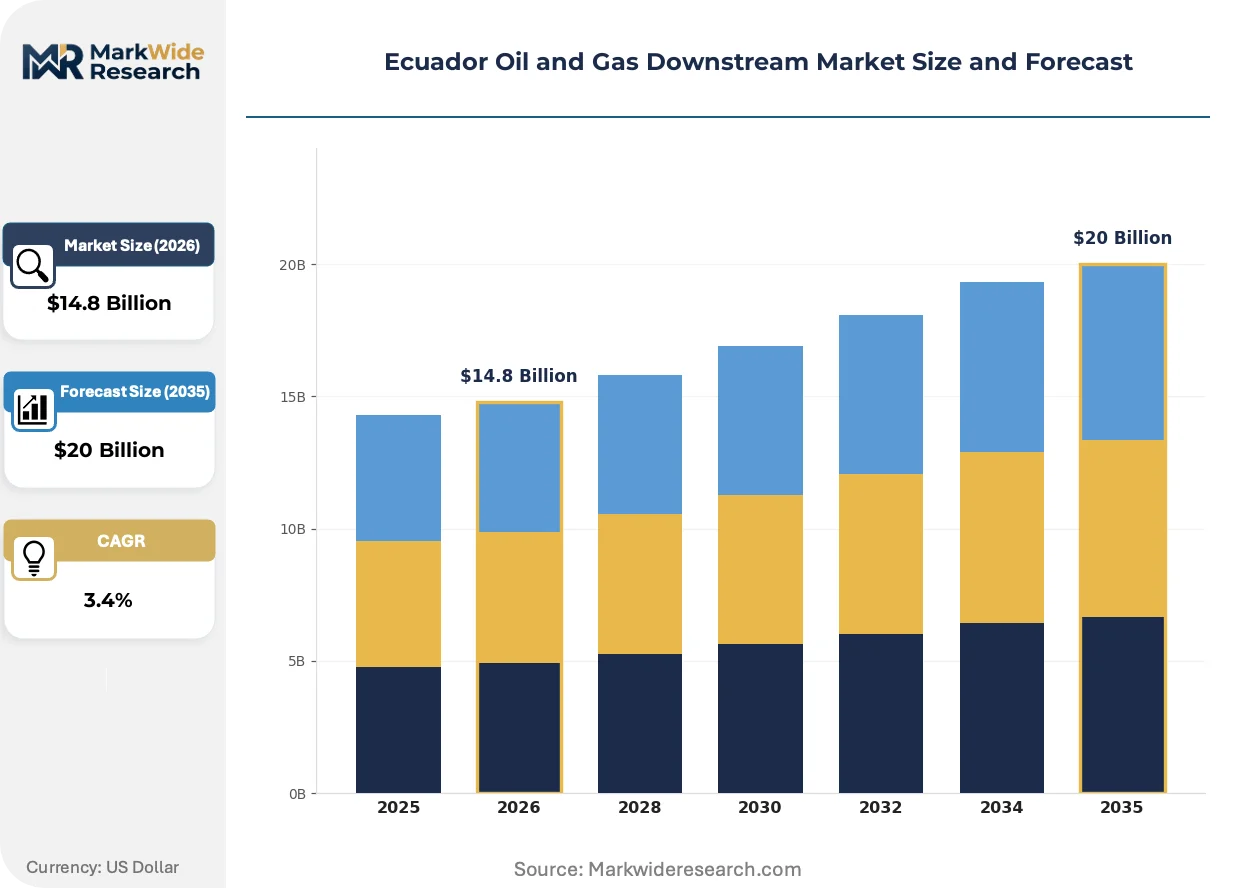
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Petroleum, Petrochemicals, Lubricants, Asphalt, Liquefied Petroleum Gas, Specialty Chemicals Application: Fuel Distribution, Petrochemical Production, Asphalt Manufacturing, Lubricant Formulation, Gas Processing, Additive Blending End User: Fuel Retailers, Chemical Manufacturers, Construction Firms, Marine Operators, Power Generation Companies, Transport Fleets Distribution Channel: Fuel Stations, Bulk Terminals, Direct Supply Contracts, Wholesale Distributors, Pipeline Networks, Exporters |
| Companies Covered | Total S.A., OCP Ecuador, EP Petroecuador, Ecuadorian Oil Fleet, Refineria Esmeraldas, Petroamazonas EP, Royal Dutch Shell Plc, Transporte de Petroquimicos EP, Eni SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecuador Oil and Gas Downstream Market Shifts & Advancements
Digital metering and automated dispensing infrastructure is reshaping fuel retail operations, compressing transaction costs and enabling real-time inventory management across the coastal distribution network.
Hydroprocessing catalyst formulations optimized for high-sulfur heavy crude feeds are supplanting conventional fixed-bed systems in refinery revamp projects. EP Petroecuador is piloting these units at Esmeraldas to meet diesel sulfur specifications without full reconstruction. The technology is compressing capital intensity for compliance upgrades while extending catalyst cycle lengths.
Ecuador's Ministry of Energy and Non-Renewable Natural Resources has tightened fuel quality specifications for transport diesel and LPG, forcing importers and blenders to certify product batches against updated sulfur and particulate standards. Distribution terminals in Guayaquil are responding by segregating storage tanks for specification-grade versus standard product lines.
Transport fleet operators are consolidating fuel purchasing under annual volume contracts with direct refinery offtake, bypassing traditional retail networks. Large logistics companies in the Quito-Guayaquil corridor are leading this shift, negotiating delivered-fuel pricing that reflects pipeline terminal access rather than pump retail economics.
Ecuador Oil and Gas Downstream Market Segmentation
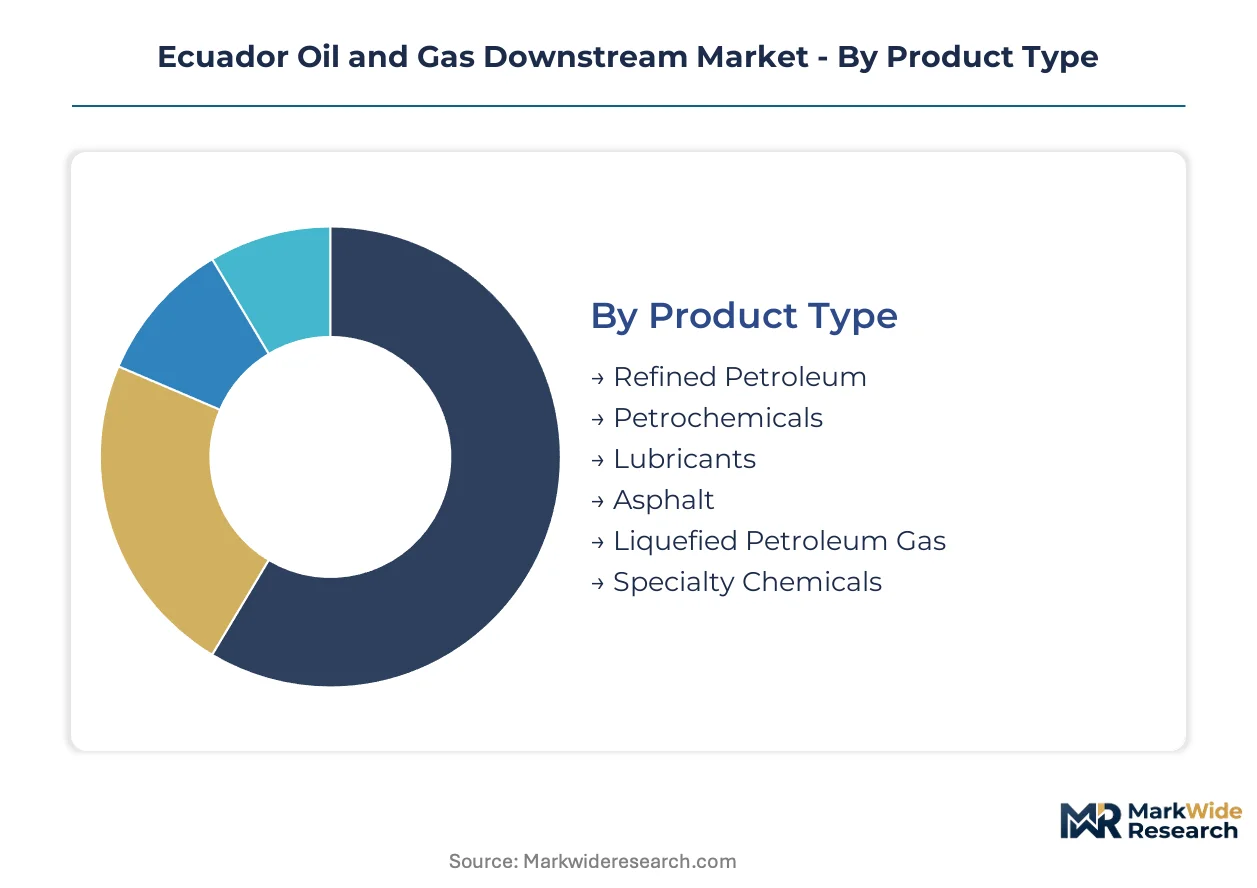
Segmentation in Ecuador's downstream oil and gas sector reveals how product flows, customer procurement patterns, and channel economics concentrate margin capture. Each dimension exposes structural bottlenecks and expansion corridors that determine facility-level profitability.
Product Type:
Refined products move predominantly through coastal pipeline terminals and bulk storage facilities, while specialty chemicals and LPG bypass traditional retail networks for direct industrial offtake.
- Refined Petroleum:Gasoline, diesel, and fuel oil constitute the volume base, processed from Napo heavy crude at API gravities below 20 degrees. Transport fleets along the Quito-Guayaquil corridor absorb the majority of diesel output under annual volume contracts.
- Petrochemicals:Ethylene, propylene, and aromatic intermediates serve as industrial feedstocks. Domestic conversion capacity gaps force reliance on imported precursors for construction and manufacturing applications.
- Lubricants:Industrial and automotive formulations blend base oils with additive packages. Marine operators in Guayaquil port represent concentrated demand for high-viscosity marine lubricants.
- Asphalt:Paving-grade and roofing asphalts derive from vacuum residue processing. Road construction programs in the coastal provinces drive seasonal procurement spikes.
- Liquefied Petroleum Gas:Propane-butane mixtures for residential cooking and transport fuel. Fleet modernization mandates are accelerating LPG-compatible vehicle purchases across urban transport networks.
- Specialty Chemicals:Solvents, surfactants, and performance additives for industrial applications. Additive blending operations are gaining traction as fuel quality specifications tighten.
Refined petroleum dominates installed base. Specialty chemicals is where expansion concentrates.
Application:
Application segments stratify by capital intensity and regulatory exposure, with fuel distribution and gas processing commanding the highest throughput volumes.
- Fuel Distribution:Pipeline, marine, and road networks deliver finished products to retail and bulk customers. EP Petroecuador's monopoly over the Esmeraldas refinery complex forces private distributors to compete on logistics efficiency.
- Petrochemical Production:Crude oil fractionation and catalytic conversion yield chemical intermediates. The coastal refining corridor lacks integrated petrochemical complexes, constraining domestic value addition.
- Asphalt Manufacturing:Air blowing and blending of vacuum residue produce construction-grade binders. Public infrastructure budgets in Guayas and Manabí provinces determine demand cyclicality.
- Lubricant Formulation:Base oil blending with additive packages for automotive and industrial specifications. Direct supply contracts with mining and marine operators bypass wholesale channels.
- Gas Processing:LPG extraction and treatment from refinery off-gas streams. Sulfur recovery investments are accelerating as environmental enforcement tightens.
- Additive Blending:Detergent, dispersant, and cetane improver incorporation into finished fuels. Fuel retailers are capturing margin expansion by investing in specification-grade blending capabilities.
Fuel distribution anchors volume throughput. Additive blending is climbing the fastest as quality mandates intensify.
End User:
End user concentration reflects Ecuador's economic structure, with transport and construction sectors driving fuel and asphalt demand respectively.
- Fuel Retailers:Service station networks and card-operated dispensing infrastructure. Digital metering systems are compressing transaction costs across the coastal distribution network.
- Chemical Manufacturers:Industrial consumers of solvents, monomers, and process chemicals. Import dependency for specialty product precursors creates supply chain vulnerability.
- Construction Firms:Asphalt pavers, roofing contractors, and infrastructure developers. Government road programs in the coastal corridor sustain bulk asphalt procurement.
- Marine Operators:Bunker fuel and lubricant consumers at Pacific port terminals. Guayaquil maritime hub development offers throughput expansion for refined product exports.
- Power Generation Companies:Fuel oil and diesel consumers for thermal electricity production. Grid stability requirements sustain residual fuel oil offtake despite renewable substitution.
- Transport Fleets:Logistics operators consolidating purchasing under direct refinery contracts. Large companies are negotiating delivered-fuel pricing that reflects pipeline terminal access.
Transport fleets dominate procurement volume growth. Chemical manufacturers face the steepest input cost pressure from import dependency.
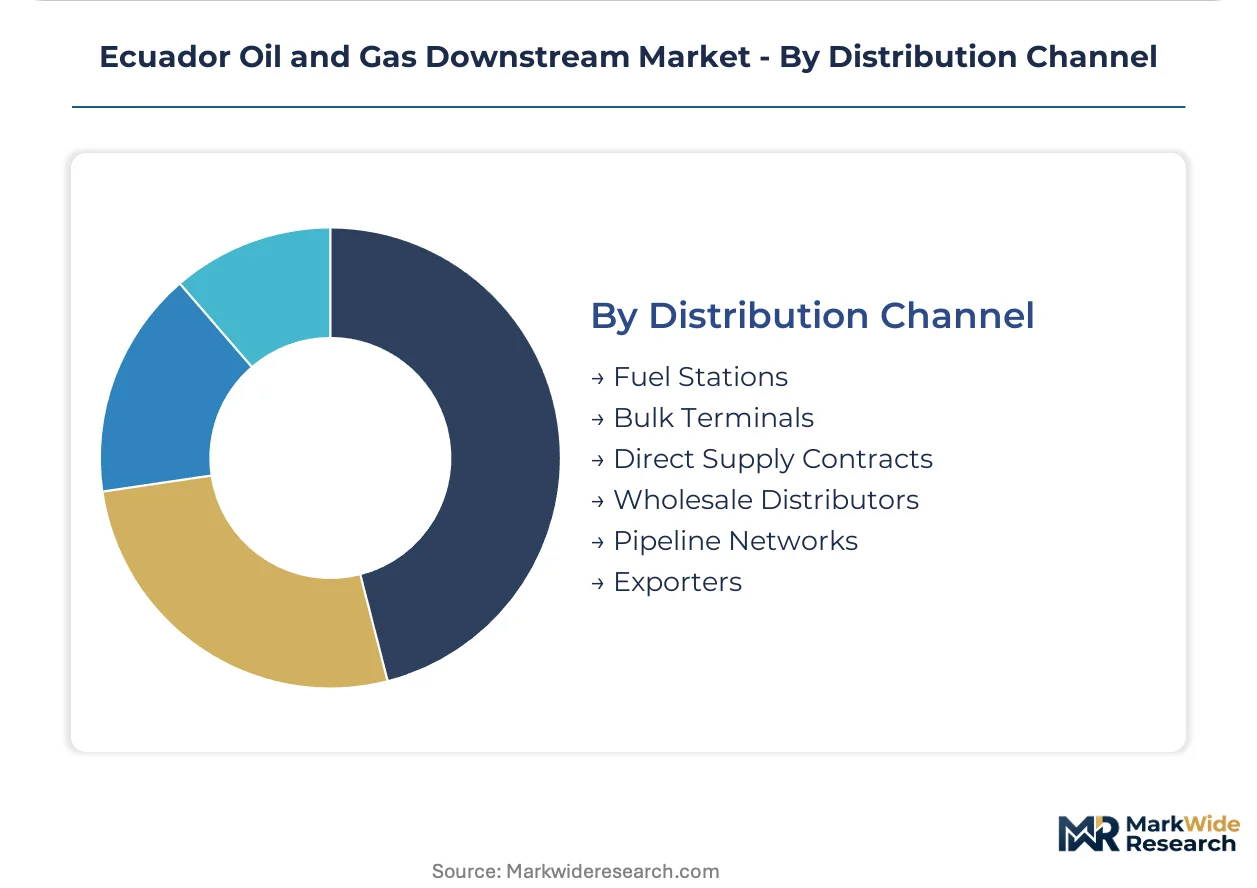
Distribution Channel:
Channel selection determines working capital requirements and margin capture, with direct contracts and bulk terminals displacing traditional retail networks for large consumers.
- Fuel Stations:Retail dispensing infrastructure with automated payment and inventory systems. Network coverage concentrates in urban centers along the Pan-American Highway corridor.
- Bulk Terminals:Coastal storage facilities with marine loading capabilities. Guayaquil and Esmeraldas terminals anchor Pacific-facing refined product logistics.
- Direct Supply Contracts:Annual volume agreements between refiners and large industrial consumers. Transport fleet consolidation into direct offtake is compressing traditional retailer margins.
- Wholesale Distributors:Intermediate logistics providers serving fragmented retail and commercial accounts. Margin pressure from direct contracting is forcing consolidation among regional distributors.
- Pipeline Networks:Crude and product transmission infrastructure linking production to processing and export. OCP Ecuador's heavy crude pipeline sustains feedstock security for coastal refiners.
- Exporters:Maritime bulk shippers serving regional Pacific markets. Port terminal modernization offers capacity expansion for refined product export volumes.
Direct supply contracts are gaining share fastest. Fuel stations retain the broadest geographic coverage despite volume erosion to bulk channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SOTE pipeline system and OCP heavy crude pipeline anchor Ecuador's downstream geography, linking Amazonian production to Pacific coastal refineries. Maritime access through Guayaquil and Esmeraldas terminals concentrates processing capacity and export logistics along a narrow coastal corridor.
Esmeraldas Province
Refinery operations and maritime terminal throughput dominate provincial economic activity. Ecuador's Ministry of Energy and Non-Renewable Natural Resources enforces fuel quality specifications that shape capital allocation at the Esmeraldas refinery complex. The city of Esmeraldas anchors the coastal refining corridor where hydroprocessing catalyst upgrades are compressing compliance timelines.
Guayas Province
Transport fleet consolidation into direct refinery contracts is compressing traditional fuel retailer margins across the Quito-Guayaquil corridor. The country's environmental regulator enforces refinery emissions thresholds that determine operating permits for coastal facilities. Guayaquil's maritime hub development offers throughput expansion for refined product exports to regional Pacific markets.
Los Ríos Province
Agricultural processing and road freight logistics sustain diesel demand across provincial transport networks. Pipeline terminal access agreements determine delivered-fuel pricing for large logistics operators. The Babahoyo-Quevedo corridor represents a distribution bottleneck where wholesale distributors face consolidation pressure from direct contracting trends.
Manabí Province
Road construction programs and public infrastructure budgets drive seasonal asphalt procurement spikes across coastal provinces. Sulfur recovery investments are accelerating as environmental enforcement tightens on refinery off-gas processing. The Portoviejo-Manta corridor concentrates construction materials demand from government road programs.
Pichincha Province
Digital metering infrastructure and automated dispensing systems are compressing transaction costs across urban fuel retail networks. Fleet modernization mandates are accelerating LPG-compatible vehicle purchases within Quito's urban transport network. The capital's concentration of corporate logistics headquarters drives annual volume contract negotiations with direct refinery offtake.
Ecuador Oil and Gas Downstream Market Competitive Landscape
Listed leaders compete with private specialists across infrastructure control and feedstock access. State-controlled EP Petroecuador dominates national refining capacity through its monopoly over the Esmeraldas complex, forcing private distributors to compete on logistics efficiency rather than processing margin. Three archetypes define competitive positioning: state-owned integrated operators controlling upstream-throughput chains, international majors leveraging trading expertise for import supply, and specialized logistics providers optimizing terminal and fleet operations. Capacity expansion and strategic partnerships represent the dominant competitive moves, with terminal modernization and pipeline access agreements determining market participation.
Among state-controlled integrated operators, EP Petroecuador and Petroamazonas EP occupy positions exemplifying upstream-throughput coordination, with crude allocation authority securing feedstock priority for domestic processing. International majors including Total S.A. and Eni SpA represent trading-based supply archetypes, anchoring refined product import flows to fill domestic specialty product gaps. These groupings illustrate how control over physical infrastructure separates margin capture from commodity trading participation.
| Leading Market Players |
|---|
| Total S.A. |
| OCP Ecuador |
| EP Petroecuador |
| Ecuadorian Oil Fleet |
| Refineria Esmeraldas |
| Petroamazonas EP |
| Royal Dutch Shell Plc |
| Transporte de Petroquimicos EP |
| Eni SpA |
| Others |
Supply & Pricing Matrix
Ecuador's Ministry of Energy and Non-Renewable Natural Resources fuel quality specifications gate both refinery operating permits and price differentiation between specification-grade and standard product batches. The regulatory framework forces distributors to segregate storage tanks and certify product quality, creating tiered margin structures that reward compliance investment while compressing margins for undifferentiated supply.
Pricing Analysis
Volume-discount tiering structures dominate procurement between transport fleets and coastal refiners, with annual offtake contracts commanding delivered-fuel pricing that reflects pipeline terminal access rather than pump retail economics. Price differentiation rests on sulfur content certification and geographic delivery cost to the Quito-Guayaquil corridor. Cost compression in standard-grade diesel is intensifying because fleet operators are consolidating purchasing under direct refinery agreements. Small fuel retailers exhibit the highest price sensitivity, while large logistics operators with dedicated terminal access show the least.
Supply Chain Analysis
Inventory cycles at Guayaquil and Esmeraldas bulk terminals compress to days rather than weeks as transport fleets accelerate direct contracting and bypass wholesale channels. Geographic supply concentrates in Ecuador's Amazonian production basins and Pacific coastal refining corridor, with limited alternative crude sourcing from regional Latin American producers. Raw material dependencies center on Napo heavy crude feedstock, hydroprocessing catalyst formulations, and imported specialty chemical precursors. Single-refinery vulnerability at the Esmeraldas complex constitutes the dominant structural risk. Distribution runs through pipeline networks, coastal marine terminals, and contracted road fleets serving direct industrial offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ecuador downstream sector rewards operators who control specification-grade blending capabilities and pipeline terminal access, while scarcity of licensed additive blending infrastructure constrains new competitor entry. Feedstock allocation authority and emissions compliance engineering represent the decisive capability gaps separating margin capture from commodity participation.
For Market Incumbents: Shield processing margins by securing long-term crude supply agreements with Petroamazonas EP before feedstock allocation priorities shift. Accelerate sulfur recovery unit upgrades ahead of compressed environmental permitting deadlines to defend operating license continuity. Vertical integration into additive blending operations at Guayaquil terminals captures specification-grade premium pools as quality mandates tighten. For New Entrants and Emerging Players: Certification fast-track through Ecuador's Ministry of Energy and Non-Renewable Natural Resources specification-grade product approval offers the most penetrable entry path. Target additive blending infrastructure investments in the coastal refining corridor where incumbent capacity constraints create supply gaps. Pursue direct supply contracts with mid-sized transport fleets bypassed by large fleet consolidation trends. For Investors and Strategic Acquirers: Sulfur recovery compliance deadlines reshape the acquisition landscape by forcing capital deployment timelines that separate viable from stranded refining assets. Five-to-ten year viability hinges on feedstock slate flexibility engineering and environmental permit renewal trajectories. Target acquisition archetypes include specialized logistics providers with pipeline terminal access agreements. The signal to watch is enforcement intensity from Ecuador's environmental regulator on refinery emissions thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Hydroprocessing Catalyst Upgrade | EP Petroecuador pilots high-sulfur optimized formulations at Esmeraldas to compress diesel sulfur compliance timelines without full reconstruction. |
| Pipeline Terminal Access Agreement | OCP Ecuador heavy crude infrastructure sustains throughput economics and feedstock security for Pacific-facing coastal refiners. |
| Additive Blending Capacity Buildout | Fuel retailers capture specification-grade margin expansion as Ecuador's Ministry of Energy tightens transport diesel quality mandates. |
| Direct Supply Contract Consolidation | Large logistics operators in the Quito-Guayaquil corridor negotiate delivered-fuel pricing reflecting pipeline terminal access. |
| Maritime Hub Modernization | Guayaquil port terminal expansion offers throughput growth for refined product exports to regional Pacific markets. |
Research Methodology
Cross-validation between primary interviews with refinery operations managers, fuel procurement directors at transport fleets, environmental compliance officers, and pipeline logistics coordinators anchors the qualitative findings. Secondary validation draws from Ecuador's Ministry of Energy regulatory filings, environmental permit databases, customs trade records for refined product imports, and SEC disclosures from international majors with regional trading operations. Bottom-up capacity utilization data and top-down macroeconomic demand indicators triangulate market sizing.
Sensitivity analysis around crude price volatility and regulatory enforcement intensity frames the forecast uncertainty. The analytical framework segments by product type, application, end user, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation of fleet modernization mandates, refinery throughput constraints, and coastal infrastructure expansion timelines. Modeled inputs include Napo heavy crude availability, sulfur recovery investment cycles, and LPG-compatible vehicle penetration rates.
Underlying assumptions cover sustained enforcement of fuel quality specifications and pipeline terminal access continuity, with deviation risk concentrated in regulatory enforcement intensity and unplanned refinery maintenance events. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market