
 Offshore Oilfield Services Market | 2026-2036
Offshore Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Oilfield Services Market Analytics
Integrated well construction services is expanding as the dominant commercial layer, bundling drilling, completion, and intervention into multi-year contractual frameworks that transfer operational risk from operators to service companies. Schlumberger Limited leverages its digital drilling platform to anchor long-term partnerships with national oil companies in complex offshore provinces. Transocean LTD sustains the industry's largest fleet of ultra-deepwater drillships, positioning it to capture the most technically demanding assignments. Baker Hughes Company differentiates through subsea production systems that integrate with topside infrastructure.
Offshore oilfield services encompass the specialized engineering, equipment, and labor required to drill, complete, maintain, and abandon wells in marine environments, typically operating at water depths from 30 meters to over 3,000 meters using dynamically positioned rigs and subsea blowout preventers rated to 20,000 psi. Drilling Services commands the largest revenue share due to rig day-rate structures and extended well durations, while Intervention Services represents the fastest-expanding category as aging subsea installations require more frequent workover and plug-and-abandonment activity. Deep Water deployment absorbs disproportionate capital allocation, with ultra-deepwater frontiers in Guyana and Mozambique attracting integrated service contracts that span multiple segment categories.
The US Bureau of Safety and Environmental Enforcement enforces subsea containment requirements that shape BOP testing protocols and emergency response capabilities, while Norway's Petroleum Safety Authority mandates barrier management standards that influence contractor selection criteria in the North Sea. Brazil's ANP local content rules constrain foreign equipment sourcing and compel service providers to deepen domestic supply chain partnerships. Stakeholders must monitor how regulatory divergence across the US Gulf of Mexico, Norway, and Brazil affects the economics of standardized versus region-customized service offerings.
Market Dynamics
Integrated drilling and completion packages are compressing project timelines and transferring operational risk from operators to full-service contractors, fundamentally restructuring how deepwater projects are tendered and executed across Brazil, Norway, and the US Gulf of Mexico.
Growth Catalysts
- BOP reliability mandates:The US Bureau of Safety and Environmental Enforcement enforces subsea containment requirements that accelerate replacement cycles for blowout preventers and emergency response systems.
- Pre-salt basin complexity:Brazil's ultra-deepwater frontiers require integrated service contracts bundling drilling, completion, and intervention into multi-year frameworks.
- Digital drilling platforms:Real-time downhole monitoring and predictive maintenance algorithms reduce non-productive time on ultra-deepwater assignments.
Market Restraints
- Capital intensity of drillship construction:Newbuild ultra-deepwater rigs require $500 million-plus commitments with decade-long payback horizons, concentrating fleet ownership among a handful of contractors.
- ANP local content rules:Brazil's national petroleum regulator mandates domestic supply chain participation that constrains equipment sourcing flexibility and inflates project costs.
- Subsea installation aging:Workover and plug-and-abandonment demand on 1980s-era North Sea infrastructure outpaces available intervention vessel capacity.
Strategic Opportunities
- Guyana-Suriname basin expansion:ExxonMobil-led discoveries in this underpenetrated province are attracting integrated service contracts spanning multiple segment categories.
- Electrification of offshore platforms:Subsea power distribution and shore-based electricity supply create new engineering scopes for cable-lay and topside modification specialists.
- Carbon capture readiness:Norway's CO2 storage licensing framework positions depleted reservoirs for repurposing, requiring well integrity verification and monitoring services.
Industry Challenges
- BOP technician scarcity:Specialized skills for 20,000 psi-rated blowout preventer maintenance and subsea electronics repair outpace training pipeline output.
- Legacy well abandonment liability:Thousands of uneconomic subsea installations require P&A execution without original drilling records or cement evaluation data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Oilfield Services Market |
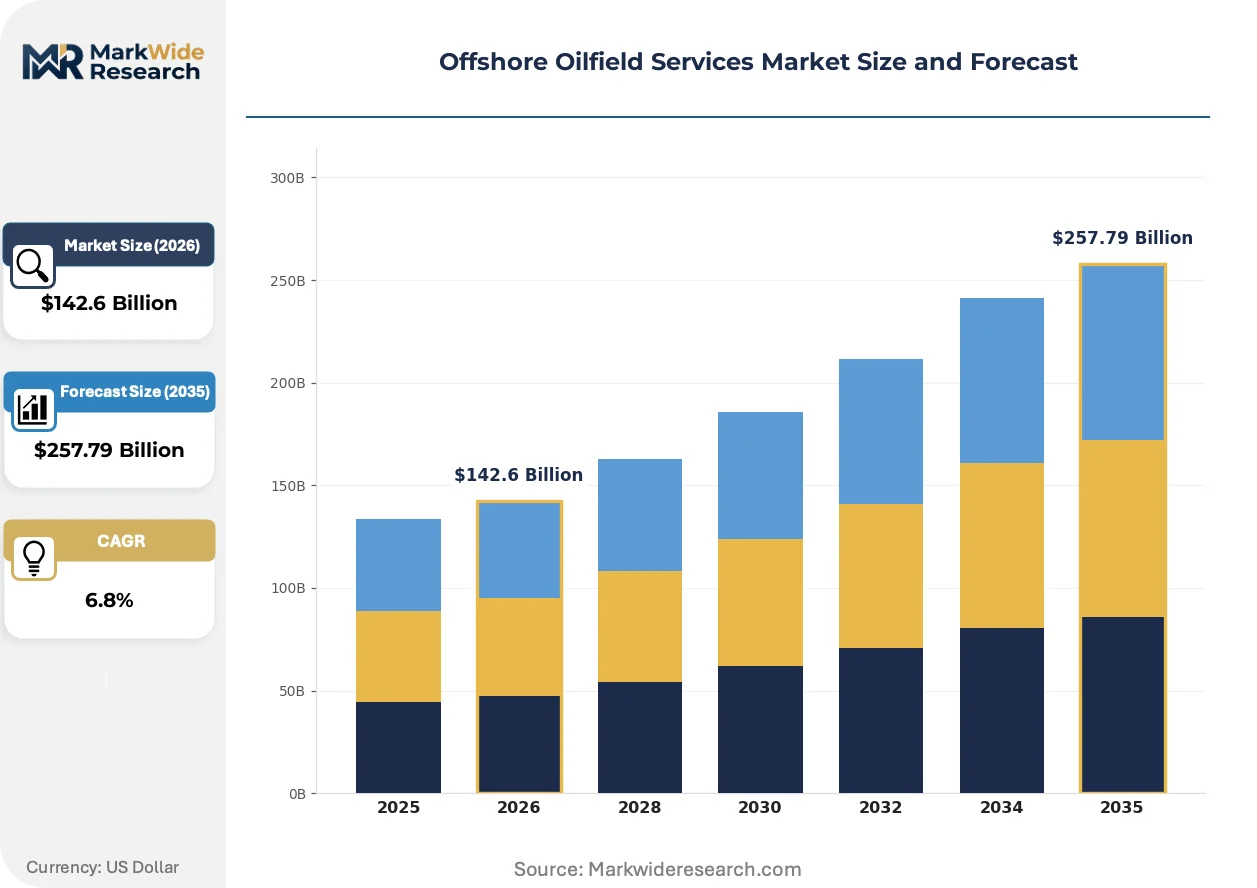
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $257.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Completion Services, Production Services, Intervention Services Equipment Type: Rigs, Subsea Equipment, Surface Equipment, Offshore Supply Vessels Deployment Mode: Onshore, Shallow Water, Deep Water, Ultra Deep Water Client Type: Independent Operators, National Oil Companies, International Oil Companies, Service Providers |
| Companies Covered | Transocean LTD, Weatherford International, Schlumberger Limited, Saipem S.p.A., National Oilwell Varco, Halliburton Company, TechnipFMC, Petrofac Limited, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Oilfield Services Market Evolving Landscape
Digitalization and electrification are converging to reshape offshore service delivery models, with real-time data transmission and remote operations reducing platform personnel counts while expanding the scope of shore-based technical support.
Managed pressure drilling systems are overtaking conventional riser-based approaches in ultra-deepwater environments. These closed-loop circulation technologies maintain precise bottom-hole pressure regardless of formation influx or lost circulation events. Petrobras and ExxonMobil are deploying these systems in Brazil's pre-salt carbonate reservoirs where narrow drilling windows previously caused multiple sidetracks. The technology is compressing well construction duration by eliminating contingency casing strings and reducing kick detection response times from minutes to seconds.
The EU Green Deal and Norway's carbon neutrality targets for 2050 are mandating emissions disclosure across offshore supply chains. Contractors must now report Scope 1 and 2 emissions to qualify for North Sea tenders, with penalty clauses for exceedance. Drillship operators are responding with hybrid power systems combining battery storage with dual-fuel engines, while subsea service vessels trial ammonia and methanol propulsion. This regulatory pressure is accelerating retirement of older, less efficient assets.
Performance-based contracting is displacing traditional day-rate structures in deepwater drilling. Operators now tie contractor compensation to specific metrics including spud-to-spud time, mechanical downtime, and safety incident rates. This model transfers more operational risk to service companies while aligning incentives across project phases. The shift is most visible in the US Gulf of Mexico where integrated majors have consolidated vendor lists and standardized key performance indicators across their drilling programs.
Offshore Oilfield Services Market Segmentation
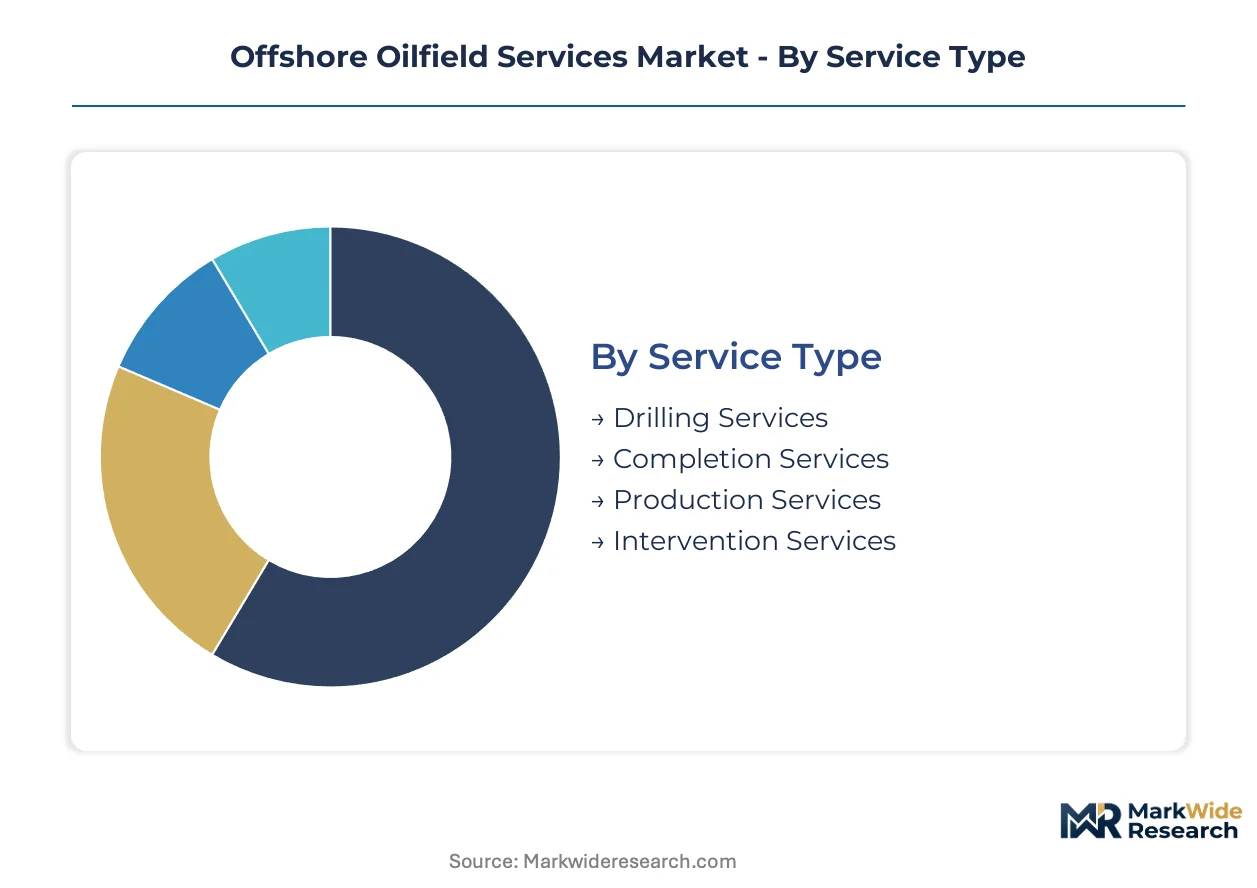
Offshore oilfield services fragment across four distinct axes that determine contract structure, capital intensity, and risk allocation. Service type governs revenue recognition and operational liability. Deployment mode dictates equipment specifications and regulatory jurisdiction. Understanding these splits reveals where integrated providers capture premium economics versus where commoditized competition erodes margins.
Service Type:
Drilling commands volume share through rig day-rate structures, while intervention captures premium expansion as subsea infrastructure ages.
- Drilling Services:Encompasses wellbore construction from spud to total depth using dynamically positioned drillships and semi-submersible rigs. Brazil's pre-salt basins and Guyana's Stabroek block absorb the majority of ultra-deepwater drilling demand under multi-year contractual frameworks. Today's leader: Drilling Services. Tomorrow's challenger: Intervention Services.
- Completion Services:Covers wellbore preparation for hydrocarbon flow including casing, cementing, perforating, and subsea tree installation. Norway's northern continental shelf and the US Gulf of Mexico concentrate demand for high-pressure high-temperature completions where barrier integrity standards from the Petroleum Safety Authority and Bureau of Safety and Environmental Enforcement elevate technical requirements.
- Production Services:Sustains hydrocarbon extraction through artificial lift, subsea processing, and topside maintenance.
- Intervention Services:Expands most quickly as 1980s-era North Sea installations and early deepwater Gulf of Mexico assets require workover, stimulation, and plug-and-abandonment execution.
Service bundling favors full-scope contractors in frontier basins while mature provinces sustain standalone specialists.
Equipment Type:
Rigs absorb the majority of capital deployment, though subsea equipment generates superior margins through technology differentiation.
- Rigs:Ultra-deepwater drillships and semi-submersible platforms deliver well construction capability at water depths exceeding 1,500 meters. Fleet ownership concentrates among a handful of contractors due to $500 million-plus newbuild costs and decade-long payback horizons. Today's anchor: Rigs. Tomorrow's margin capture: Subsea Equipment.
- Subsea Equipment:Comprises blowout preventers, subsea production trees, manifolds, and umbilicals operating at pressures up to 20,000 psi. Norway's CO2 storage licensing framework and Brazil's pre-salt development are accelerating demand for subsea boosting and processing systems that extend field life.
- Surface Equipment:Includes topside processing modules, drilling packages, and living quarters installed on fixed platforms and floating production facilities.
- Offshore Supply Vessels:Delivers cargo, personnel, and subsea intervention support to drilling and production installations.
Equipment procurement increasingly favors integrated packages that reduce interface risk between subsea and topside systems.
Deployment Mode:
Deep water and ultra-deep water absorb disproportionate capital allocation despite representing a minority of well count.
- Deep Water:Operating between 400 and 1,500 meters water depth, this tier hosts the majority of current offshore production outside the Middle East. Brazil's pre-salt carbonate reservoirs and Angola's Block 17 developments anchor demand for floating production storage and offloading vessels paired with subsea tiebacks.
- Ultra Deep Water:Extends beyond 1,500 meters into frontier provinces including Guyana, Suriname, and Mozambique where integrated service contracts span multiple technical disciplines. ExxonMobil-led discoveries in the Stabroek block exemplify the multi-billion-dollar development commitments this tier attracts.
- Shallow Water:Mature basins in the Gulf of Mexico shelf and Southeast Asia sustain jackup rig demand for well maintenance and recompletion.
- Onshore:Excluded from offshore service scope but referenced for contractual comparison and technology transfer.
Deployment economics favor ultra-deepwater frontier development where resource scale justifies technical complexity.
Client Type:
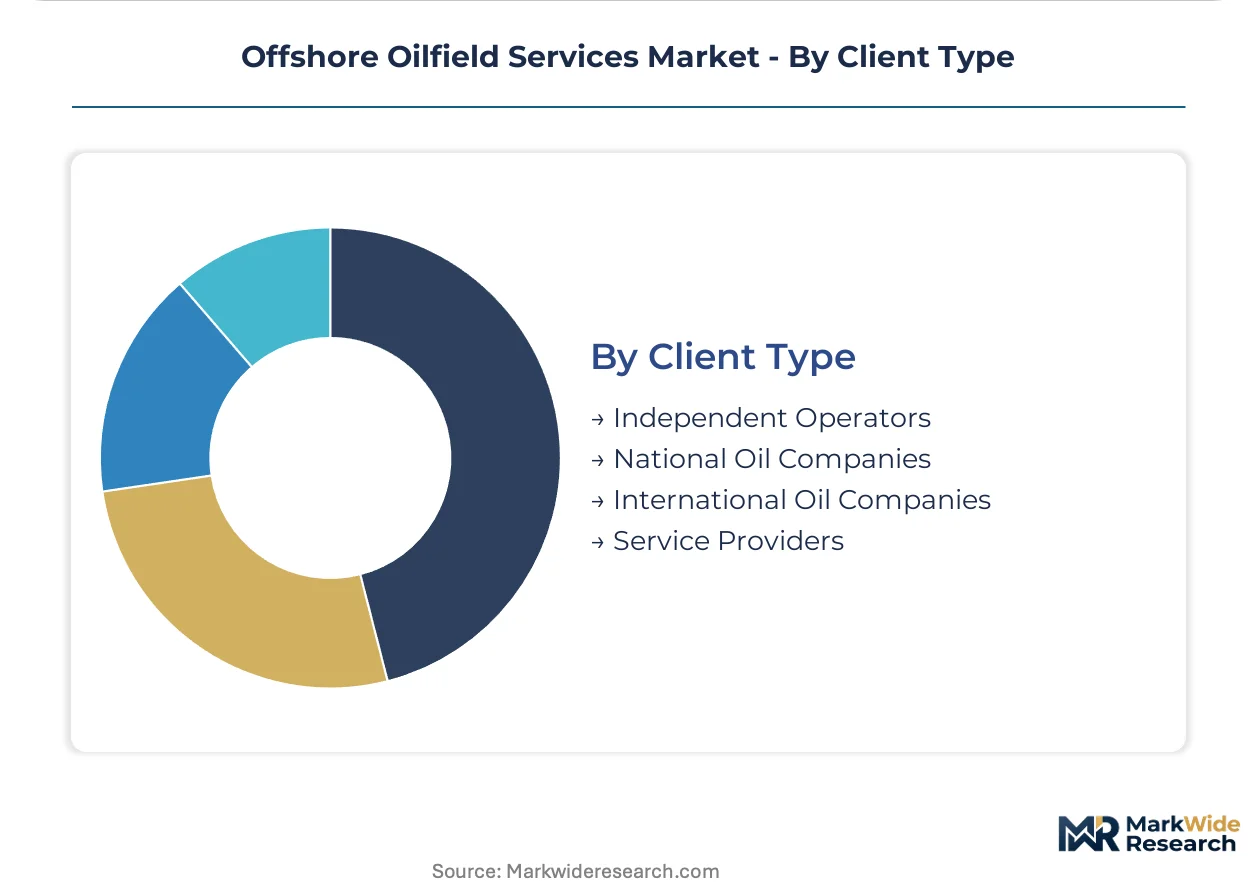
National oil companies and international oil companies diverge in contracting philosophy, risk tolerance, and local content requirements.
- International Oil Companies:ExxonMobil, Shell, and BP consolidate vendor relationships through performance-based contracts tying compensation to spud-to-spud time and mechanical downtime metrics. These operators drive standardization across the US Gulf of Mexico and Guyana-Suriname basin developments.
- National Oil Companies:Petrobras, Equinor, and Saudi Aramco anchor demand in their respective domestic basins while imposing local content mandates that reshape supply chain configuration. Brazil's ANP rules constrain foreign equipment sourcing and compel service providers to deepen domestic partnerships.
- Independent Operators:Smaller capital bases limit these players to non-operated positions or marginal field developments with shorter payback requirements.
- Service Providers:Subcontractor tier executing specialized scopes under prime contractor direction.
Contractor qualification standards diverge most sharply between national oil companies with local content mandates and international oil companies with global performance benchmarks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting deepwater investment toward jurisdictions with clearer permitting timelines and stable fiscal terms. Brazil, Norway, and the United States capture disproportionate capital flows as operators flee cost-of-compliance escalation elsewhere.
Brazil
Pre-salt carbonate reservoirs anchor ultra-deepwater drilling demand under Petrobras-led consortium structures. ANP local content rules compel foreign service providers to deepen domestic supply chain partnerships, reshaping procurement patterns. The Santos Basin cluster near Rio de Janeiro concentrates floating production storage and offloading vessel construction and subsea equipment integration activity.
Norway
CO2 storage licensing and electrification mandates are creating new engineering scopes for well integrity verification and platform power distribution. The Petroleum Safety Authority enforces barrier management standards that elevate contractor qualification criteria across the northern continental shelf. Stavanger anchors subsea technology development and subsea boosting system manufacturing for North Sea and export markets.
United States
Gulf of Mexico ultra-deepwater frontiers sustain integrated drilling and completion contract demand from ExxonMobil and Shell. The Bureau of Safety and Environmental Enforcement mandates BOP reliability protocols and subsea containment capabilities that accelerate equipment replacement cycles. Houston concentrates corporate headquarters, engineering design centers, and specialist technical training facilities for deepwater service delivery.
Guyana
ExxonMobil-led Stabroek block discoveries are attracting multi-billion-dollar development commitments and integrated service contracts spanning multiple technical disciplines. The country's nascent regulatory framework offers faster permitting timelines relative to mature basins. Georgetown serves as the logistical coordination hub for offshore supply vessel operations and personnel mobilization.
United Kingdom
Aging North Sea infrastructure from the 1980s is driving plug-and-abandonment and workover demand that outpaces available intervention vessel capacity. The North Sea Transition Authority imposes decommissioning security obligations that reshape contractor liability structures. Aberdeen maintains its position as the primary subsea engineering and remote operations technology development center.
Offshore Oilfield Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated full-service providers capturing premium economics in frontier basins while standalone specialists defend positions in mature provinces. The vendor base concentrates around a handful of drillship owners due to $500 million-plus newbuild costs and decade-long payback horizons. Three archetypes dominate: fleet-scale contractors with ultra-deepwater assets, technology-integrated service companies with digital platforms, and subsea equipment specialists with high-pressure system capabilities. Competitive dynamics center on multi-year contractual frameworks and performance-based compensation structures.
Among fleet-scale drillship operators, Transocean LTD and Saipem S.p.A. occupy positions defined by ultra-deepwater asset concentration and technical assignment complexity. Schlumberger Limited exemplifies the technology-integrated archetype through digital drilling platform deployment. Baker Hughes Company sits within the subsea equipment tier, differentiated by production system integration capabilities with topside infrastructure.
| Leading Market Players |
|---|
| Transocean LTD |
| Weatherford International |
| Schlumberger Limited |
| Saipem S.p.A. |
| National Oilwell Varco |
| Halliburton Company |
| TechnipFMC |
| Petrofac Limited |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Petrobras-led procurement consolidation in Brazil's pre-salt basins is compressing vendor margins and forcing service providers to absorb more operational risk through integrated contract structures. This buyer concentration reshapes how contractors structure pricing across drilling, completion, and intervention bundles.
Pricing Analysis
Direct-to-operator contracting eliminates distributor markups and compresses channel margins to single-digit percentages. Performance-based compensation structures now dominate ultra-deepwater assignments, with day-rate premiums tied to spud-to-spud efficiency and mechanical downtime metrics. Price differentiation hinges on BOP reliability certification tiers and digital platform integration depth. Cost compression in standard drilling packages is intensifying as fleet oversupply in the Gulf of Mexico erodes baseline rates. National oil companies exhibit highest price sensitivity due to local content mandate compliance costs, while international oil companies prioritize technical performance over rate negotiation.
Supply Chain Analysis
API certification and BSEE qualification gating restrict subsea equipment sourcing to a narrow tier of approved manufacturers. Manufacturing concentrates in the United States, Norway, and Brazil, with Houston, Stavanger, and Rio de Janeiro anchoring fabrication clusters for high-pressure systems. Supply chains draw from specialized steel forging in Japan, subsea electronics from the United Kingdom, and synthetic rope manufacturing from the Netherlands. Single-source vulnerability pervades 20,000 psi-rated BOP stack production, where only two qualified suppliers serve the Atlantic basin. Distribution runs through prime contractor logistics hubs rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore oilfield services function as a stable compounder anchored by irreversible pre-salt basin development timelines and regulatory-mandated equipment replacement cycles. Deepwater resource extraction generates predictable multi-year contract visibility.
For Market Incumbents: To counter fleet-scale competitors consolidating ultra-deepwater drillship ownership, anchor market position through backward integration into subsea equipment manufacturing and captive control over BOP maintenance technician training pipelines. Deepen vertical integration by acquiring specialized intervention vessel operators facing capacity constraints in the North Sea plug-and-abandonment market.
For New Entrants and Emerging Players: Norway's CO2 storage licensing framework opens a window for well integrity verification specialists to capture monitoring and abandonment services around depleted reservoir repurposing. Target Guyana's nascent regulatory environment where faster permitting timelines reduce incumbent advantage. Enter through joint venture structures with established logistics providers to bypass capital barriers in offshore supply vessel ownership.
For Investors and Strategic Acquirers: Asymmetric upside sits with subsea technology specialists holding 20,000 psi system capabilities and digital drilling platform intellectual property. Long-term viability centers on contractors positioned across the full well lifecycle from spud through abandonment. Watch BOP reliability mandate enforcement intensity as the inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contract Expansion | Multi-year frameworks with Petrobras transfer operational risk and lock in revenue visibility. |
| Subsea Equipment Manufacturing Scale-Up | Domestic production in Brazil satisfies ANP local content rules and reduces import dependency. |
| Digital Platform Deployment | Real-time downhole monitoring systems reduce non-productive time on pre-salt carbonate reservoirs. |
| Technician Training Pipeline Investment | Specialized BOP maintenance skills scarcity constrains fleet utilization and commands premium pricing. |
| Intervention Vessel Capacity Addition | Plug-and-abandonment demand in the North Sea outpaces available specialized asset supply. |
Research Methodology
Bottom-up operator capex modeling reconciled against top-down rig fleet utilization tracking forms the analytical core of this study. Primary interviews with drilling contract managers, subsea procurement leads, BOP maintenance supervisors, and regulatory compliance officers at operators and service companies were validated against secondary sources including BSEE incident databases, ANP production reports, Petroleum Safety Authority barrier management audits, and offshore vessel tracking registries. Triangulation across these inputs ensures demand-side and supply-side estimates converge.
Historical trendline analysis of rig day-rate movements, contract backlog duration, and equipment replacement cycles established baseline growth patterns across the projection horizon. Segmentation modeling incorporated service type, equipment category, deployment water depth, and client archetype dimensions. CAGRs were derived from fitted trend extrapolation adjusted for regulatory mandate timing and basin-specific project sanctioning velocity. Forecast inputs included Petrobras pre-salt development schedules, Equinor electrification investment commitments, and ExxonMobil Guyana phase expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement shifts or prolonged oil price dislocation. Model outputs reflect assumptions around BOP replacement cycle acceleration, local content rule stability, and frontier basin project sanctioning rates. A model refresh is warranted upon material change in BSEE subsea containment mandate interpretation or ANP procurement regulation revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
South America Offshore Energy Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market