
 Uzbekistan Oil and Gas Downstream Market | 2026-2036
Uzbekistan Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Uzbekistan Oil and Gas Downstream Market Analytics
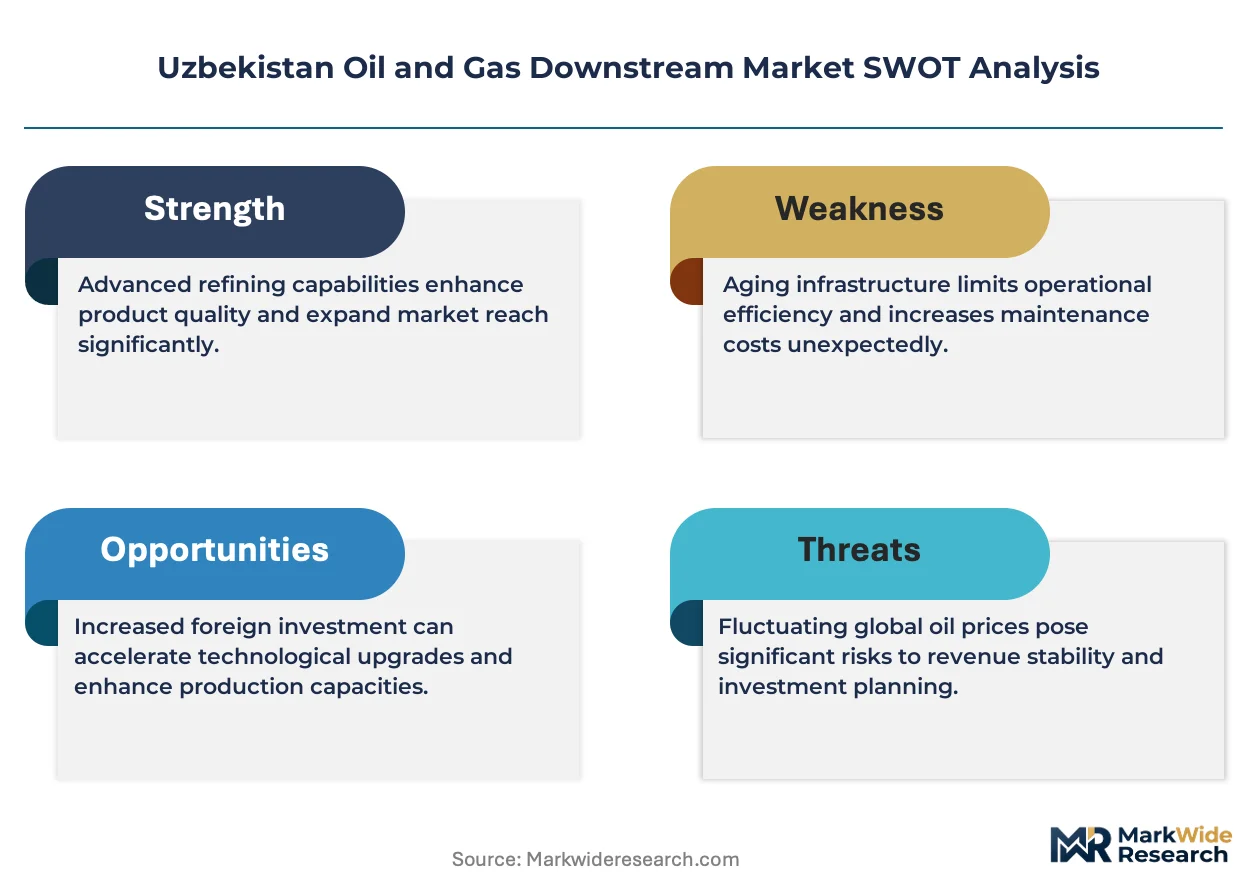
Synthetic lubricant formulations are displacing conventional mineral bases in Uzbekistan's automotive and industrial sectors, and this shift is realigning product economics across the downstream value chain. JSC Uzbekneftegaz leverages its integrated refining and distribution infrastructure to dominate domestic fuel supply. Lukoil Uzbekistan anchors its position through technology transfer from Russian hydrocracking expertise. Jizzakh Petroleum JV competes as the country's newest refining entrant with modern conversion capacity.
Uzbekistan oil and gas downstream operations encompass crude oil refining, petroleum product distribution, retail marketing, and petrochemical manufacturing, with modern refineries targeting sulfur content below 10 parts per million in transportation fuels to meet tightening specifications. The primary purpose is converting raw hydrocarbons into usable energy products and chemical feedstocks for domestic consumption and regional export. Refining capacity leads the service type structure as the foundational value-creation stage, while petrochemicals represents the fastest-growing segment as Uzbekistan pursues import substitution for plastics and synthetic materials. Gasoline and diesel together occupy the core product type margin pool, though jet fuel is gaining structural importance with Tashkent International Airport's hub expansion.
Uzbekistan's State Inspection for Control in Use of Petroleum Products enforces Euro-5 fuel standards, while the Committee on Industrial Safety regulates refinery operations and environmental compliance. These frameworks are forcing upgrades to hydrocracking and catalytic reforming units while restricting market access for non-compliant product imports. Stakeholders must monitor regulatory enforcement consistency and the pace of technology retrofit commitments across the existing refinery base.
Market Dynamics
Uzbekistan's downstream sector faces structural compression from Euro-5 fuel standards enforcement, which mandates sulfur content below 10 parts per million and forces capital-intensive hydrocracker upgrades across all domestic refineries.
Growth Catalysts
- Jizzakh Petroleum JV capacity expansion:Modern conversion units enable higher-yield gasoline production for domestic automotive fuel suppliers seeking cleaner blendstocks.
- State Inspection for Control in Use of Petroleum Products:Euro-5 adoption creates regulatory pull for desulfurization technology retrofits at existing refineries.
- Tashkent International Airport hub growth:Jet fuel demand is accelerating from expanded international route networks and cargo operations.
Market Restraints
- Crude import dependency:Uzbekistan relies on Russian and Kazakh pipeline deliveries, exposing margins to transit tariff volatility and geopolitical supply interruptions.
- Deep conversion technology gaps:Legacy FCC units lack residue hydrocracking capability, capping diesel yield and forcing fuel oil production.
- Central Asian product arbitrage:Lower-cost Russian gasoline and diesel imports pressure domestic refinery gate pricing during seasonal oversupply periods.
Strategic Opportunities
- Fergana Valley petrochemical integration:Proximity to cotton-textile and packaging industries creates captive demand for polyethylene and polypropylene derivatives.
- Synthetic lubricant formulation partnerships:Technology transfer agreements with Russian and Chinese additive suppliers enable premium product localization.
- Surkhandarya regional retail network gaps:Underdeveloped fuel station infrastructure along Afghanistan-border trade corridors offers first-mover positioning.
Industry Challenges
- Hydrocracker catalyst procurement expertise:Local engineering teams lack experience in noble-metal catalyst loading and sulfiding protocols for high-pressure units.
- Euro-5 compliance timeline compression:Refineries must complete sulfur plant revamps and hydrogen network expansions before enforcement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uzbekistan Oil and Gas Downstream Market |
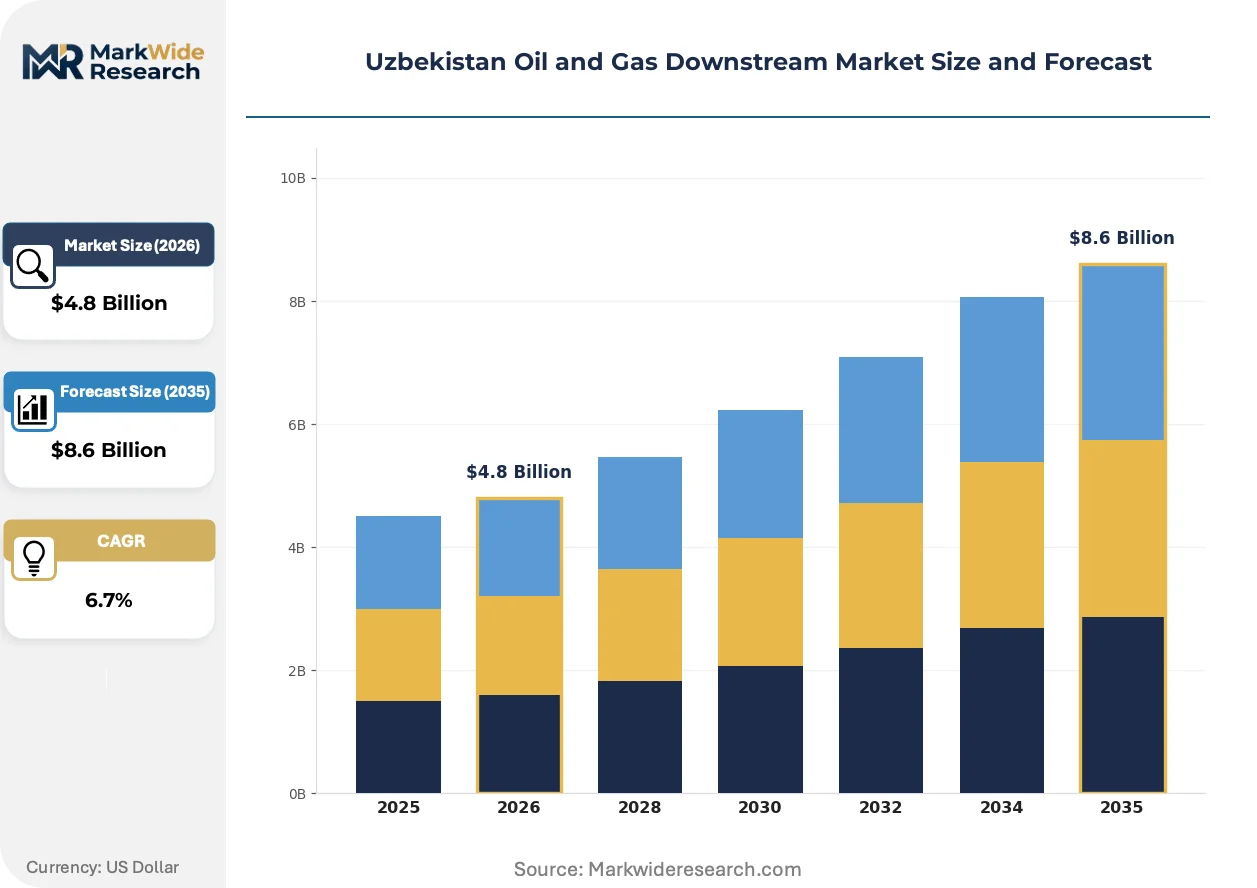
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Refining, Distribution, Retail, Petrochemicals Product Type: Gasoline, Diesel, Jet Fuel, Lubricants End User: Automotive, Aviation, Industrial, Residential Technology: Hydrocracking, Alkylation, Catalytic Reforming, Gas-to-Liquids |
| Companies Covered | Sanoat Energetika Guruhi LLC (SEG), Petroliam Nasional Berhad, JSC Uzbekneftegaz, Lukoil Uzbekistan, Sasol Limited, PJSC Gazprom, Jizzakh Petroleum JV, China National Petroleum Corporation (CNPC), TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uzbekistan Oil and Gas Downstream Market Evolving Landscape
Digital refinery optimization and synthetic fuel formulations are restructuring Uzbekistan's downstream competitive landscape. Technology adoption patterns diverge between state-controlled incumbents and newer joint ventures.
Residue hydrocracking technology is rewriting conversion economics at Uzbekistan's newest refining complex. Automotive fuel suppliers are prioritizing hydrocracker output for low-sulfur gasoline blending. This process upgrade is compressing the margin premium previously captured by imported clean fuels.
Uzbekistan's State Inspection for Control in Use of Petroleum Products enforces Euro-5 standards through batch testing and retail station audits. Refineries must certify each product slate against sulfur, benzene, and aromatics limits. The Tashkent industrial corridor faces the tightest compliance scrutiny due to population density and air quality monitoring.
Long-term offtake contracts are displacing spot procurement for jet fuel and petrochemical feedstocks. Airlines and polymer processors seek volume security through 3-5 year supply agreements with fixed differentials. This pattern concentrates most visibly around Tashkent International Airport and the Fergana Valley textile clusters.
Uzbekistan Oil and Gas Downstream Market Segmentation
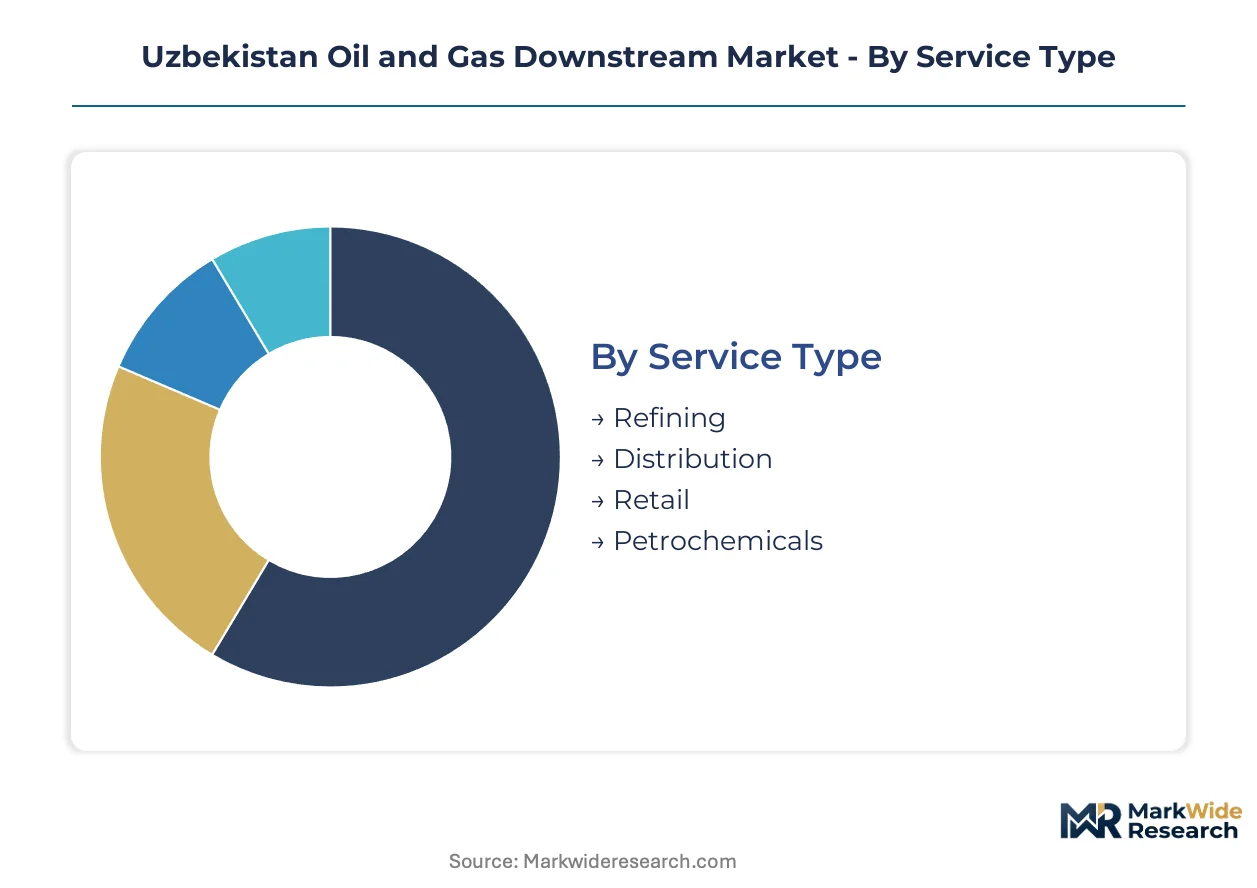
Downstream segmentation in Uzbekistan reveals how capital allocation and regulatory pressure concentrate across distinct operational layers. Each category exposes different vulnerability points to Euro-5 compliance timelines and crude import dependency.
Service Type:
Standardized infrastructure dominates refining and distribution, while petrochemicals and retail allow greater customization to local demand patterns.
- Refining:Centralized processing of domestic and imported crude through hydrocracking and catalytic reforming units. Capacity concentrates at the Jizzakh Petroleum JV complex and legacy Uzbekneftegaz facilities in the Fergana Valley, with sulfur reduction mandates driving unit retrofit schedules.
- Petrochemicals:Polymer production and synthetic material manufacturing represent the fastest-growing service layer. Fergana Valley textile and packaging clusters generate captive offtake for polyethylene derivatives, reducing import dependence for plastics feedstock.
- Distribution:Pipeline and rail networks move refined products from refining centers to consumption corridors. State-controlled infrastructure limits third-party access to storage and terminal capacity.
- Retail:Fuel station networks and lubricant sales points serve end consumers directly. Surkhandarya border regions show infrastructure gaps along Afghanistan trade routes.
Most installed capacity flows through Refining. Expansion is steepest in Petrochemicals.
Product Type:
Margin concentration follows transportation fuel demand, with aviation and industrial lubricants occupying premium pricing tiers.
- Gasoline:Primary automotive fuel subject to Euro-5 sulfur limits below 10 parts per million. Tashkent and Samarkand urban corridors drive blendstock demand for cleaner formulations.
- Diesel:Heavy transport and agricultural machinery fuel facing similar desulfurization requirements. Legacy FCC units cap yield potential, forcing fuel oil production that compresses overall refinery economics.
- Jet Fuel:Aviation kerosene for Tashkent International Airport's expanding hub operations. Long-term offtake contracts with international carriers provide volume visibility.
- Lubricants:Synthetic formulations displace mineral bases in automotive and industrial applications. Technology transfer agreements enable localized production of premium additive packages.
Volume leadership sits with Gasoline. Value expansion runs fastest in Lubricants.
End User:
Customer concentration spans mobility services, heavy industry, and household energy with diverging specification sensitivity.
- Automotive:Passenger and commercial vehicle fleets consuming gasoline and diesel. Euro-5 enforcement raises quality requirements for fuel suppliers serving Tashkent's dense vehicle population.
- Aviation:Airlines and cargo operators at Tashkent International Airport driving jet fuel procurement. Hub expansion creates structural demand growth distinct from ground transport cycles.
- Industrial:Manufacturing, mining, and construction sectors using diesel and lubricants. Fergana Valley cotton-textile clusters generate process heat and machinery maintenance demand.
- Residential:Liquefied petroleum gas and kerosene for heating and cooking in rural and peri-urban areas. Seasonal consumption patterns differ from commercial demand profiles.
Automotive absorbs the largest product volume. Aviation shows the steepest demand trajectory.
Technology:
Capital intensity and technical complexity separate mature conversion processes from emerging synthetic fuel pathways.
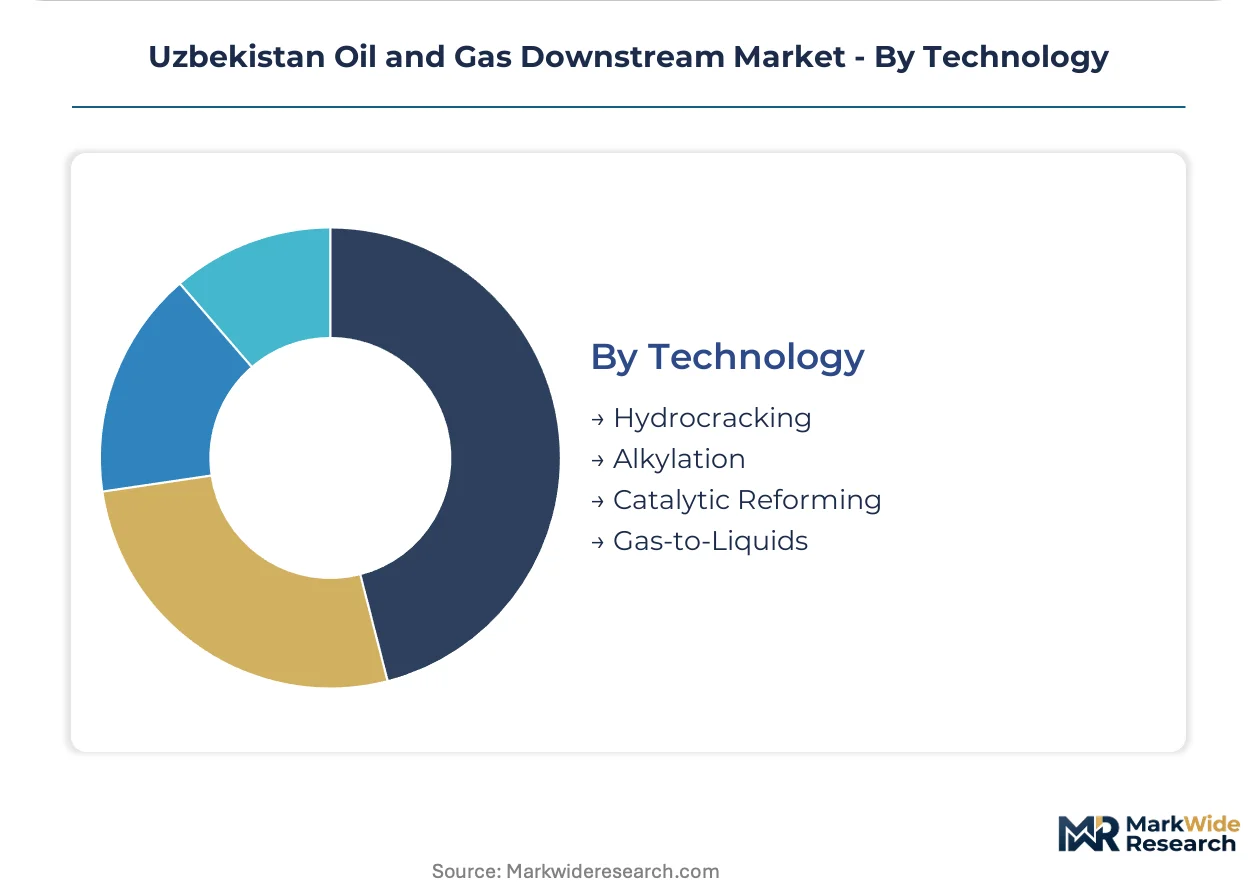
- Hydrocracking:High-pressure hydrogen addition breaking heavy fractions into lighter, low-sulfur products. Jizzakh Petroleum JV deployment enables gasoline yield expansion meeting Euro-5 specifications.
- Catalytic Reforming:Octane enhancement for gasoline blending through platinum-rhenium catalyst systems. Existing units require revamp to handle tighter benzene and aromatics limits.
- Alkylation:Acid-catalyzed combination of light olefins and isobutane for high-octane gasoline components. Limited current deployment creates technology gap for premium fuel production.
- Gas-to-Liquids:Fischer-Tropsch synthesis converting natural gas to synthetic diesel and lubricant bases. Uzbekistan's gas reserves support pilot project evaluation for fuel independence.
Hydrocracking commands the dominant installed base. Gas-to-Liquids attracts the most exploratory capital commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Fergana Valley industrial corridor anchors Uzbekistan's downstream processing capacity, with petrochemical feedstock demand expanding across Central Asian trade routes. State-led infrastructure investments are reshaping fuel distribution networks toward Afghanistan-border corridors and Tashkent's aviation hub.
Tashkent Metro and Industrial Belt
Automotive fuel consumption concentrates in Tashkent's dense vehicle population, where Euro-5 sulfur limits below 10 parts per million are enforced through batch testing protocols. The State Inspection for Control in Use of Petroleum Products operates its strictest compliance audits in this air quality-monitored zone. Tashkent International Airport's hub expansion is accelerating jet fuel procurement through long-term offtake contracts with international carriers.
Fergana Valley
Cotton-textile and packaging clusters generate captive demand for polyethylene and polypropylene derivatives, reducing import dependence for plastics feedstock. Uzbekneftegaz maintains legacy refining infrastructure here, with hydrocracker retrofit schedules tied to benzene and aromatics limit compliance. The Namangan-Andijan corridor hosts polymer processing facilities serving regional packaging markets.
Jizzakh Region
The Jizzakh Petroleum JV complex represents the country's newest refining entrant with modern residue hydrocracking capability enabling higher-yield gasoline production. Technology transfer from Russian hydrocracking expertise supports Euro-5 blendstock manufacturing. This facility is compressing margin premiums previously captured by imported clean fuels through domestic low-sulfur output.
Surkhandarya Border Zone
Underdeveloped fuel station infrastructure along Afghanistan trade corridors offers first-mover positioning for retail network expansion. Diesel demand from cross-border freight and agricultural machinery exceeds local supply capacity. Seasonal consumption patterns differ from commercial demand profiles in this peri-urban and rural territory.
Samarkand-Bukhara Corridor
Tourism and transport logistics drive gasoline and diesel procurement across this historic trade route. Urban vehicle fleets in Samarkand face tightening emission standards enforcement similar to Tashkent's regulatory intensity. Distribution infrastructure relies on pipeline and rail networks moving refined products from Fergana Valley and Jizzakh processing centers.
Uzbekistan Oil and Gas Downstream Market Competitive Landscape
Global majors compete with regional champions across technology licensing and feedstock access dimensions, creating a tiered structure where scale advantages separate integrated state enterprises from specialized joint ventures. State-controlled incumbents leverage captive infrastructure and regulatory relationships, while newer entrants compete on conversion technology and product specification compliance. Three archetypes dominate: national oil companies with distribution monopolies, international joint ventures with technology transfer agreements, and Central Asian regional operators with cross-border supply relationships. Competitive moves concentrate on hydrocracker capacity expansion and strategic partnerships for catalyst procurement expertise.
Within the state-controlled tier, JSC Uzbekneftegaz anchors domestic fuel supply through integrated refining and distribution infrastructure, while Lukoil Uzbekistan occupies a position exemplifying Russian technology transfer partnerships. Jizzakh Petroleum JV represents the modern conversion capacity archetype, competing through residue hydrocracking deployment that enables Euro-5 gasoline yield expansion.
| Leading Market Players |
|---|
| Sanoat Energetika Guruhi LLC (SEG) |
| Petroliam Nasional Berhad |
| JSC Uzbekneftegaz |
| Lukoil Uzbekistan |
| Sasol Limited |
| PJSC Gazprom |
| Jizzakh Petroleum JV |
| China National Petroleum Corporation (CNPC) |
| TotalEnergies SE |
| Others |
Value Network & Pricing Analysis
Automotive fuel suppliers serving Tashkent's dense vehicle population anchor pricing power through long-term offtake contracts, compressing spot market liquidity and reinforcing contract-based procurement as the dominant pricing model across Uzbekistan's downstream sector.
Pricing Analysis
Crude import costs from Russian and Kazakh pipeline deliveries pass through directly to refinery gate pricing, with sulfur content and octane grade as the primary price differentiation drivers. Pricing pressure stems from seasonal oversupply of lower-cost Russian gasoline imports that erode domestic refinery margins. State-controlled buyers at Uzbekneftegaz exhibit lowest price sensitivity due to captive infrastructure access, while independent retail operators in Surkhandarya face acute margin compression.
Supply Chain Analysis
Pipeline and rail distribution networks channel refined products from Jizzakh and Fergana Valley processing centers to Tashkent and Samarkand consumption corridors. Supply concentration rests on Russian and Kazakh crude deliveries, with noble-metal hydrocracker catalysts and hydrogen plant equipment as critical imported inputs. Single-source vulnerability in catalyst procurement from Western suppliers creates supply chain risk. Distribution runs through state-controlled terminal infrastructure that limits third-party storage access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uzbekistan's downstream sector operates as a regulatory compounder where Euro-5 sulfur mandates below 10 parts per million are forcing capital-intensive hydrocracker retrofits that reshape competitive economics across refining and fuel distribution.
For Market Incumbents: To counter margin erosion from lower-cost Russian fuel imports, JSC Uzbekneftegaz should accelerate residue hydrocracking capacity additions at Fergana Valley facilities while securing long-term catalyst supply agreements with Russian technology partners to lock in conversion cost advantages.
For New Entrants and Emerging Players: Residue hydrocracking technology transfer agreements represent the most viable entry wedge, enabling new joint ventures to capture premium positioning in Euro-5 gasoline blendstock supply. The Surkhandarya border zone offers underdeveloped retail infrastructure with diesel demand from Afghanistan trade corridors exceeding local supply capacity.
For Investors and Strategic Acquirers: Chinese national oil companies are the most active acquirer in this space, seeking Central Asian refining assets with modern conversion capacity. Long-term viability hinges on feedstock security and technology access rather than commodity exposure. Watch hydrocracker retrofit completion rates at legacy Uzbekneftegaz facilities as the inflection signal for domestic supply competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Residue Hydrocracking Capacity Addition | Jizzakh Petroleum JV deployment enables Euro-5 gasoline yield expansion displacing imported clean fuels. |
| Catalyst Procurement Partnership | Technology transfer from Lukoil Uzbekistan secures noble-metal loading expertise for high-pressure units. |
| Retail Network Expansion | First-mover fuel station development in Surkhandarya captures Afghanistan-border trade corridor diesel demand. |
| Long-term Jet Fuel Offtake Contract | Tashkent International Airport hub growth provides volume visibility for aviation kerosene suppliers. |
| Petrochemical Integration Project | Fergana Valley polyethylene production serves captive textile and packaging industry feedstock demand. |
Research Methodology
Direct dialogue with refinery operations managers, State Inspection for Control in Use of Petroleum Products enforcement officers, automotive fuel procurement leads, and petrochemical plant engineers grounded qualitative findings, validated against customs trade data, Committee on Industrial Safety regulatory filings, Uzbekneftegaz infrastructure disclosures, and EIA Central Asia energy statistics. Bottom-up capacity assessments and top-down demand projections were triangulated to ensure consistency.
Segment-level outputs across service type, product type, end user, and technology dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from capacity utilization trends, regulatory compliance timelines, and import substitution progress. Hydrocracker retrofit schedules and Euro-5 enforcement consistency served as industry-specific forecast inputs.
The model holds under stable Russian crude pipeline supply and consistent regulatory enforcement; deviation in transit tariff volatility or geopolitical supply interruptions would shift refinery margin projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market