
 Energy Storage Battery for Microgrid Market | 2026-2036
Energy Storage Battery for Microgrid Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Storage Battery for Microgrid Market Analysis
UL 9540A fire-safety certification for battery energy storage systems is collapsing the supplier field to firms with capital-intensive testing infrastructure. Samsung SDI leverages its integrated cell-to-system manufacturing to secure utility-scale microgrid tenders across Southeast Asia. BYD anchors its position through captive lithium supply and vertical cell production, while LG Energy Solution competes on high-nickel chemistry platforms optimized for tropical climate cycling.
Energy storage batteries for microgrids are electrochemical systems designed for cyclic charge-discharge operation at 20-80% depth of discharge, with thermal management sustaining performance across -20°C to 50°C ambient conditions for islanded or weak-grid installations. Their primary purpose is buffering intermittent renewable generation against load variability in locations without reliable central grid access. Lithium-ion configurations dominate current procurement due to declining cell costs and established recycling pathways, while flow battery systems occupy niche applications requiring daily multi-hour discharge cycles. Among end users, remote communities represent the fastest-growing addressable segment as governments replace diesel mini-grids with solar-battery hybrids.
The US EPA enforces stationary source air quality standards that accelerate diesel displacement in remote generation, while India's CEA mandates technical standards for distributed storage interconnection that filter non-compliant suppliers. The EU's F-Gas Regulation constrains fluorinated greenhouse gas use in battery thermal management systems, pushing manufacturers toward water-glycol cooling architectures. Stakeholders must monitor how evolving national content requirements in major microgrid procurement markets reshape supplier eligibility and technology selection criteria.
Market Dynamics
Standalone storage investment tax credits and islanded electrification programs are concentrating procurement authority in government tender offices across Southeast Asia and Africa, collapsing supplier qualification to firms with capital-intensive testing infrastructure and captive lithium supply.
Growth Catalysts
- US Inflation Reduction Act:The standalone storage investment tax credit accelerates utility-scale microgrid deployment by de-risking capital-intensive battery installations in weak-grid regions.
- Indonesia's archipelago electrification programs:State-owned utility tenders prioritize lithium-ion systems with established recycling pathways for diesel displacement across 17,000+ islands.
- Flow battery chemistry advancement:Vanadium redox systems capture niche applications requiring daily multi-hour discharge cycles beyond lithium-ion cycling limits.
Market Restraints
- UL 9540A certification costs:Fire-safety testing infrastructure requirements exceed capital thresholds for mid-tier suppliers, consolidating procurement access to vertically integrated cell manufacturers.
- Lithium carbonate price volatility:Cathode material input swings compress margin visibility for project developers bidding fixed-price rural microgrid tenders.
- Weak-grid interconnection standards:India's CEA technical mandates for distributed storage filter non-compliant suppliers from state-level renewable energy tenders.
Strategic Opportunities
- Pacific Islands diesel displacement:Government mini-grid replacement programs create first-mover advantage for solar-battery hybrid integrators with tropical climate cycling expertise.
- Water-glycol thermal management:The EU's F-Gas Regulation constrains fluorinated greenhouse gas use, pushing manufacturers toward alternative cooling architectures with patentable system designs.
- Cell-to-system manufacturing convergence:Integrated production from electrode coating to containerized deployment compresses lead times for archipelago logistics constraints.
Industry Challenges
- Electrochemical engineering talent scarcity:Battery system integration specialists with tropical climate degradation modeling experience command premium compensation in Southeast Asian hiring markets.
- Recycling pathway certification delays:Extended audit timelines for closed-loop material recovery compliance compress project financing windows for rural electrification tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Storage Battery for Microgrid Market |
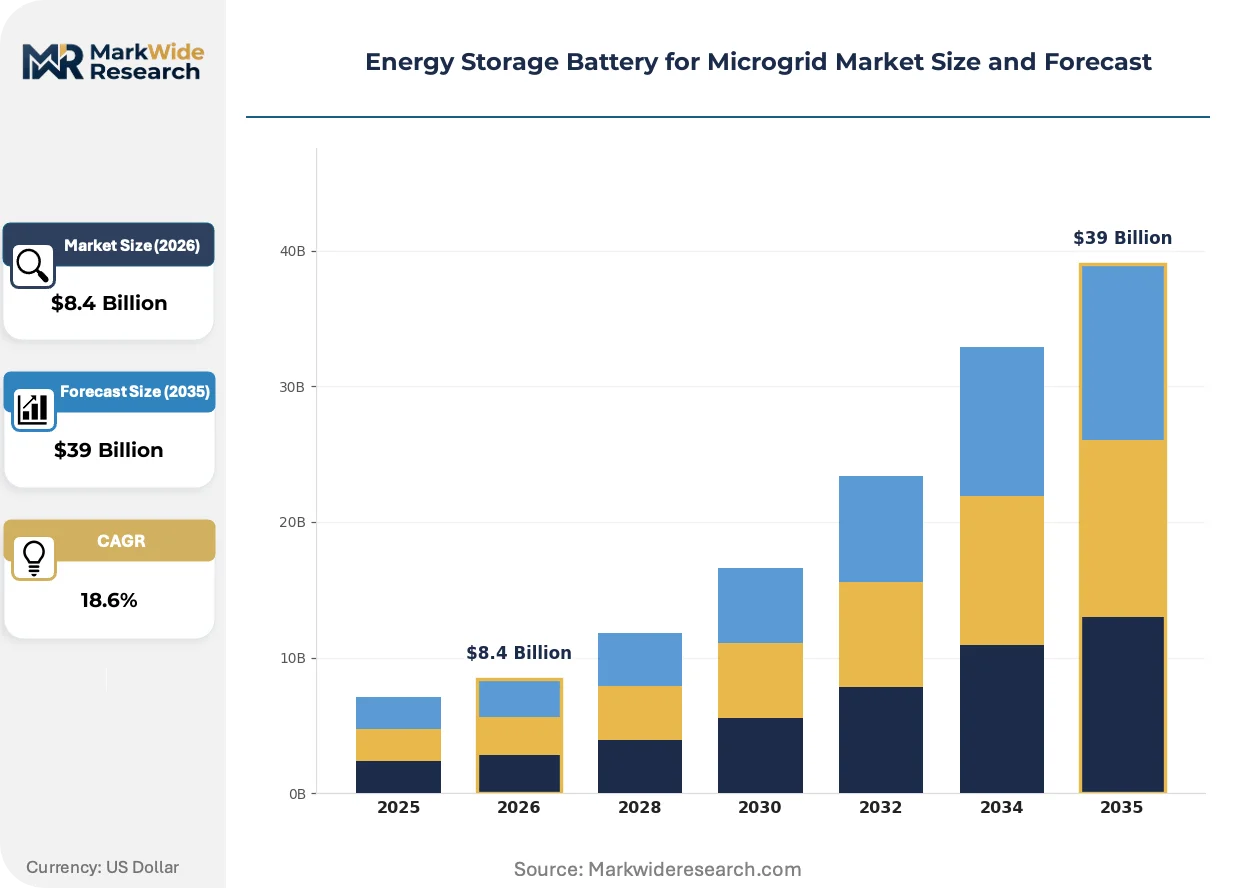
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
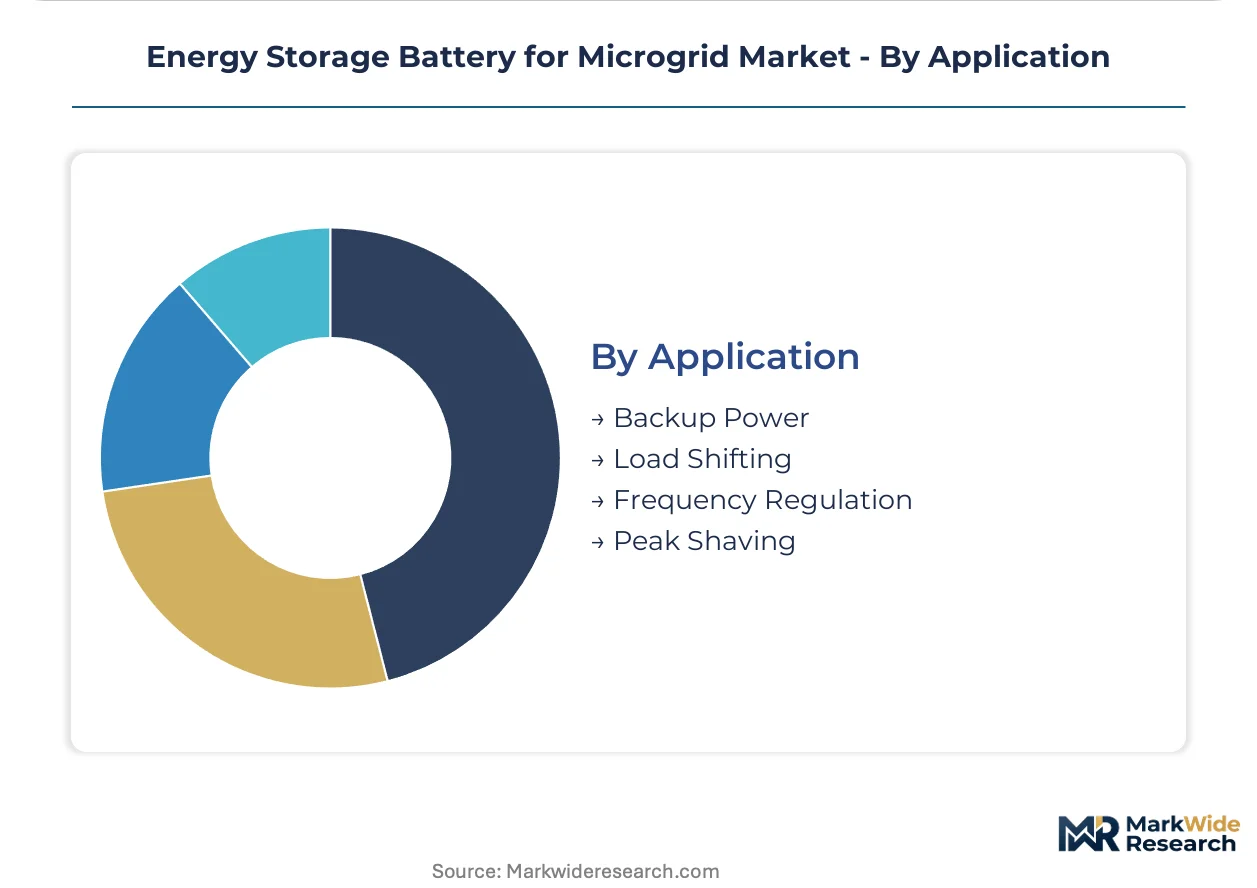
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel-cadmium, Flow Battery Technology: Smart Grid, Renewable Integration, Energy Management, Demand Response End User: Utility Providers, Industrial Facilities, Commercial Buildings, Remote Communities Application: Backup Power, Load Shifting, Frequency Regulation, Peak Shaving |
| Companies Covered | Samsung SDI, Panasonic, Tesla, Toshiba, General Electric, BYD, LG Energy Solution, SolarEast BESS, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Storage Battery for Microgrid Market Emerging Trajectories
Technology convergence between electrochemical storage and power electronics is compressing system integration timelines while regulatory pressure on thermal management fluids reconfigures supplier R&D priorities across tropical climate installations.
High-nickel NMC cathode formulations are supplanting LFP chemistry in Southeast Asian procurement specifications. Islanded microgrid operators in Indonesia and the Philippines prioritize energy density for containerized shipping constraints. This chemistry shift is compressing supplier qualification to firms with integrated cell production and tropical degradation testing protocols.
The EU's F-Gas Regulation constrains fluorinated greenhouse gas use in battery thermal management systems. Manufacturers face forced migration toward water-glycol cooling architectures with redesigned heat exchanger footprints. Southeast Asian integrators with existing tropical climate deployment experience are adapting system designs fastest to maintain tender eligibility.
Buyers in India's rural microgrid sector now require outcome-based performance guarantees with liquidated damages clauses tied to cycle life degradation curves. Traditional equipment supply contracts with warranty-only coverage are losing share to integrated service agreements bundling maintenance and cell replacement. This contractual evolution is most visible in Ministry of New and Renewable Energy tenders for village-level solar-battery hybrids.
Energy Storage Battery for Microgrid Market Segmentation
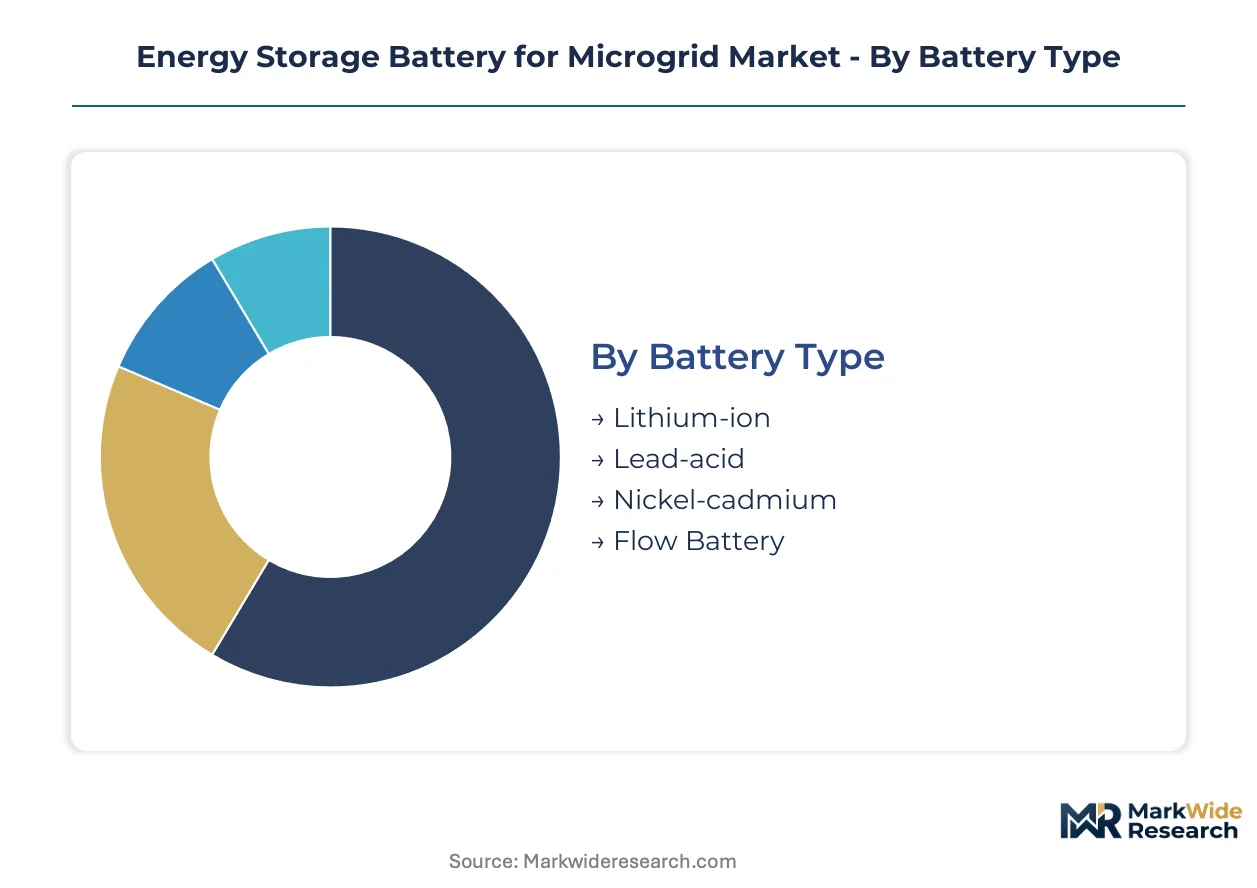
Segmentation in the Energy Storage Battery for Microgrid Market reveals how chemistry selection, control system architecture, and deployment context reshape procurement specifications. Each dimension exposes distinct margin structures and certification barriers that filter supplier participation.
Battery Type:
Lithium-ion faces substitution pressure from flow battery systems in applications requiring extended discharge duration beyond conventional cycling limits.
- Lithium-ion:NMC and LFP cathode formulations dominate containerized deployments with 4-8 hour discharge profiles. Procurement concentrates in Indonesia's archipelago programs where energy density constraints favor high-nickel chemistry for shipping logistics.
- Flow Battery:Vanadium redox systems enable daily multi-hour cycling without capacity degradation. Demand clusters in Pacific Islands diesel displacement projects where 10-15 year asset life outweighs higher capital cost.
- Lead-acid:Mature recycling infrastructure supports limited procurement in budget-constrained rural electrification tenders with short design horizons.
- Nickel-cadmium:Extreme temperature tolerance sustains niche demand in desert-edge microgrids where thermal management infrastructure is unavailable.
Lithium-ion anchors the volume base while flow battery configurations gain share at the steepest rate in long-duration procurement specifications.
Technology:
Control system sophistication separates cost tiers, with premium architectures commanding price multiples for predictive degradation management.
- Smart Grid:Bidirectional communication protocols enable real-time dispatch optimization across distributed assets. Deployment concentrates in India's CEA-mandated rural microgrid tenders requiring grid-forming inverter integration.
- Renewable Integration:Maximum power point tracking and ramp rate control buffer solar variability. Procurement accelerates in Southeast Asian solar-battery hybrid mini-grids replacing diesel generation.
- Energy Management:Predictive algorithms optimize charge-discharge scheduling against time-of-use tariffs. Demand clusters in commercial building microgrids with structured utility rate exposure.
- Demand Response:Aggregated load curtailment contracts create revenue stacking opportunities. Adoption spreads in US weak-grid regions leveraging standalone storage investment tax credit eligibility.
Renewable Integration carries the heaviest procurement volume while Smart Grid architectures expand most quickly as interconnection standards tighten.
End User:
Customer type determines contract structure, with government tenders imposing outcome-based performance guarantees absent in private procurement.
- Remote Communities:Islanded electrification programs in the Pacific Islands and Indonesia's outer islands drive solar-battery hybrid deployment with diesel displacement mandates.
- Utility Providers:State-owned tenders in India and Southeast Asia specify technical standards filtering non-compliant suppliers from renewable energy auctions.
- Industrial Facilities:Mining and processing operations in weak-grid regions procure containerized systems for power quality assurance.
- Commercial Buildings:Behind-the-meter installations target demand charge reduction through peak shaving algorithms.
Remote Communities anchor procurement volume while Utility Providers capture the steepest expansion trajectory as government electrification programs scale.
Application:
Use case specificity dictates depth of discharge requirements and thermal management design, with frequency regulation imposing the most severe cycling stress.
- Backup Power:Standby systems maintain critical load during grid outage with shallow cycling profiles. Deployment spreads in commercial and industrial microgrids with reliability premiums.
- Load Shifting:Time-of-use arbitrage requires daily deep cycling with degradation modeling for warranty pricing. Procurement concentrates in markets with structured time-varying tariffs.
- Frequency Regulation:Fast-response ancillary services impose high C-rate cycling stress. Adoption remains limited to grid-connected microgrids with market access.
- Peak Shaving:Demand charge reduction drives behind-the-meter commercial deployment with predictable dispatch patterns.
Backup Power sustains the broadest installed base while Load Shifting applications climb fastest as tariff structures evolve toward time-varying pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Java-Bali electricity transmission backbone underwrites Indonesia's archipelago electrification mandate, while India's Green Energy Corridors program channels rural microgrid investment through interstate transmission networks. Containerized battery logistics from Port of Singapore and Port of Rotterdam enable modular deployment to islanded communities across Southeast Asia and the Pacific.
Indonesia
PLN's 35,000 MW electrification program targets diesel displacement across 17,000 islands with lithium-ion containerized systems. The Ministry of Energy and Mineral Resources mandates local content requirements for battery storage tenders. Manufacturing clusters in Batam and Bintan Islands assemble imported cells into climate-hardened enclosures for tropical maritime logistics.
India
Ministry of New and Renewable Energy village-level solar-battery hybrid tenders specify CEA technical standards for distributed storage interconnection. The Green Energy Corridors program channels interstate transmission investment into weak-grid regions. Industrial zones in Gujarat and Tamil Nadu host system integrators qualifying for domestic content-linked PLI scheme incentives.
United States
The Inflation Reduction Act's standalone storage investment tax credit de-risks capital-intensive battery installations in weak-grid regions spanning Alaska and Puerto Rico. EPA stationary source air quality standards accelerate diesel generator displacement in remote communities. Project developers in Texas and California leverage the credit for utility-scale microgrid deployments with grid-forming inverter integration.
Philippines
NEA's missionary electrification program prioritizes solar-battery hybrids for unserved island barangays beyond the main transmission grid. The Department of Energy's Renewable Energy Act mandates competitive bidding for mini-grid concessions. Deployment concentrates in the Visayas archipelago where maritime logistics constraints favor high-energy-density nickel-manganese-cobalt configurations.
Germany
The EU Green Deal industrial policy channels battery manufacturing investment through European Investment Bank project finance. The F-Gas Regulation constrains fluorinated greenhouse gas use in thermal management systems, forcing water-glycol cooling redesigns. Industrial clusters in Baden-Württemberg and Bavaria develop containerized storage systems for export to tropical climate installations.
Energy Storage Battery for Microgrid Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and captive supply chains. The supplier field consolidates around vertically integrated cell manufacturers with capital-intensive UL 9540A fire-safety testing capabilities. Three archetypes dominate: integrated electronics conglomerates with in-house cell production, dedicated battery specialists with tropical climate testing protocols, and diversified industrial conglomerates leveraging power electronics heritage. Competitive moves center on backward integration into lithium supply and patentable thermal management architectures.
Within the integrated electronics tier, Samsung SDI and LG Energy Solution exemplify archetypes combining cell manufacturing with system integration capabilities. Panasonic anchors the specialist position through established tropical deployment experience. These three firms represent the qualification threshold for government tender offices in Indonesia and India where capital-intensive testing infrastructure filters mid-tier competitors from procurement access.
| Leading Market Players |
|---|
| Samsung SDI |
| Panasonic |
| Tesla |
| Toshiba |
| General Electric |
| BYD |
| LG Energy Solution |
| SolarEast BESS |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Water-glycol thermal management architectures replacing fluorinated cooling fluids simultaneously relocate manufacturing clusters toward EU-compliant assembly hubs and compress margin structures for legacy system integrators. This substitution dynamic concentrates pricing power with firms possessing redesigned heat exchanger patents while forcing mid-tier competitors toward commodity hardware margins.
Pricing Analysis
Certification level (UL 9540A fire-safety grade) creates the primary spread between premium and standard tiers. Project-based pricing dominates rural electrification tenders, with differentiation anchored in tropical climate testing protocols and captive lithium supply. Cost compression in standard-tier containerized systems intensifies as Chinese cell manufacturers expand direct bidding into Indonesian archipelago programs. Government tender offices exhibit lowest price sensitivity, while commercial behind-the-meter buyers prioritize demand charge reduction over capital cost minimization.
Supply Chain Analysis
Port congestion at Singapore and Rotterdam constrains containerized battery delivery timelines for Pacific Islands deployment. Cell production concentrates in China, South Korea, and Japan, with cathode active material sourcing from Indonesia and Chile. The supply chain rests on lithium carbonate spot market exposure and specialized thermal management component procurement. Single-source vulnerability in high-nickel cathode precursors poses structural risk. Distribution runs through state-owned utility tender offices and EPC contractor integration partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical engineering talent capable of tropical degradation modeling commands premium compensation across Southeast Asian hiring markets, creating acquisition premiums for firms with established specialist teams. This capability scarcity rewards early investment in climate-hardened testing infrastructure.
For Market Incumbents: Secure backward integration into lithium supply and UL 9540A certification infrastructure to defend against emerging Chinese cell manufacturers bidding directly into Indonesian state tenders. Expand Batam and Bintan Island assembly capacity to satisfy local content mandates. Prioritize patent filings for water-glycol cooling architectures ahead of EU F-Gas Regulation enforcement. For New Entrants and Emerging Players: Lead with flow battery systems targeting Pacific Islands diesel displacement programs requiring 10-15 year asset life guarantees. Focus on vanadium redox chemistry for daily multi-hour cycling applications beyond lithium-ion technical limits. Partner with established EPC contractors for archipelago logistics expertise rather than building direct distribution. For Investors and Strategic Acquirers: The EU Green Deal industrial policy and US IRA standalone storage credit reshape the acquisition landscape toward firms with dual-jurisdiction certification capabilities. Long-term viability favors vertically integrated cell-to-system manufacturers with tropical climate deployment track records. Monitor CEA technical standard revisions in India as inflection indicators for supplier qualification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Supply | Captive cathode material sourcing insulates margin visibility against carbonate price volatility. |
| UL 9540A Certification Investment | Fire-safety testing infrastructure filters mid-tier competitors from government tender access. |
| Water-Glycol Thermal Management Patenting | EU F-Gas Regulation compliance creates defendable IP positions in cooling system design. |
| Cell-to-System Manufacturing Convergence | Integrated production compresses lead times for Indonesia's 17,000-island logistics constraints. |
| Tropical Climate Testing Protocol Development | Degradation modeling expertise commands premium positioning in Southeast Asian procurement. |
Methodological Framework
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up installation tracking across battery chemistry types and top-down macroeconomic scenario analysis were triangulated to ensure consistency.
Sensitivity analysis tested forecast robustness across lithium price volatility scenarios and regulatory implementation timelines. Segmentation dimensions modeled include battery chemistry, control system architecture, end-user category, and application type across the analysis window. CAGRs were derived from installed capacity buildout trajectories, with specific inputs for archipelago electrification program commitments and standalone storage incentive phase-out schedules.
Underlying assumptions cover technology cost decline curves and policy continuity, with deviation risk concentrated in raw material supply disruptions and interconnection standard revisions. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Grid-Scale Stationary Battery Storage Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Water Electrolysis Machine Market