
 Battery Energy Storage System Fire Protection Market | 2026-2036
Battery Energy Storage System Fire Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Energy Storage System Fire Protection Market Insights
Software-defined fire detection analytics is realigning how protection contracts are structured across battery energy storage installations. Johnson Controls International PLC leverages its building-automation heritage to integrate fire detection with facility energy management. Honeywell International Inc. sustains competitive positioning through captive sensor manufacturing and UL-certified suppression chemistry. Siemens AG anchors European utility-scale deployments with IEC-compliant integrated safety architectures.
Battery energy storage system fire protection encompasses active suppression, passive containment, and predictive thermal management engineered to arrest lithium-ion thermal runaway events before cascading failure propagates across cell arrays; systems typically deploy aerosol, clean agent, or water mist discharge calibrated to 4-10 minute suppression windows while maintaining electrical isolation. Fire suppression systems dominate current procurement volumes as utilities retrofit existing installations, yet thermal management solutions represent the fastest-expanding margin pool as OEMs embed predictive cooling into original equipment. Fixed installation configurations retain the largest revenue share, though modular installation formats are gaining traction in distributed commercial and industrial microgrid deployments.
NFPA Standards and UL Standards in the United States, alongside IEC Standards across European and Asian markets, mandate increasingly granular thermal runaway propagation testing that elevates barrier-to-entry for uncertified suppliers. Local Regulations in jurisdictions such as Australia and South Korea are adding site-specific emergency response planning requirements that extend project timelines but deepen incumbent relationships. Stakeholders must monitor divergence between evolving national codes and harmonized international frameworks when configuring multi-region product portfolios.
Market Dynamics
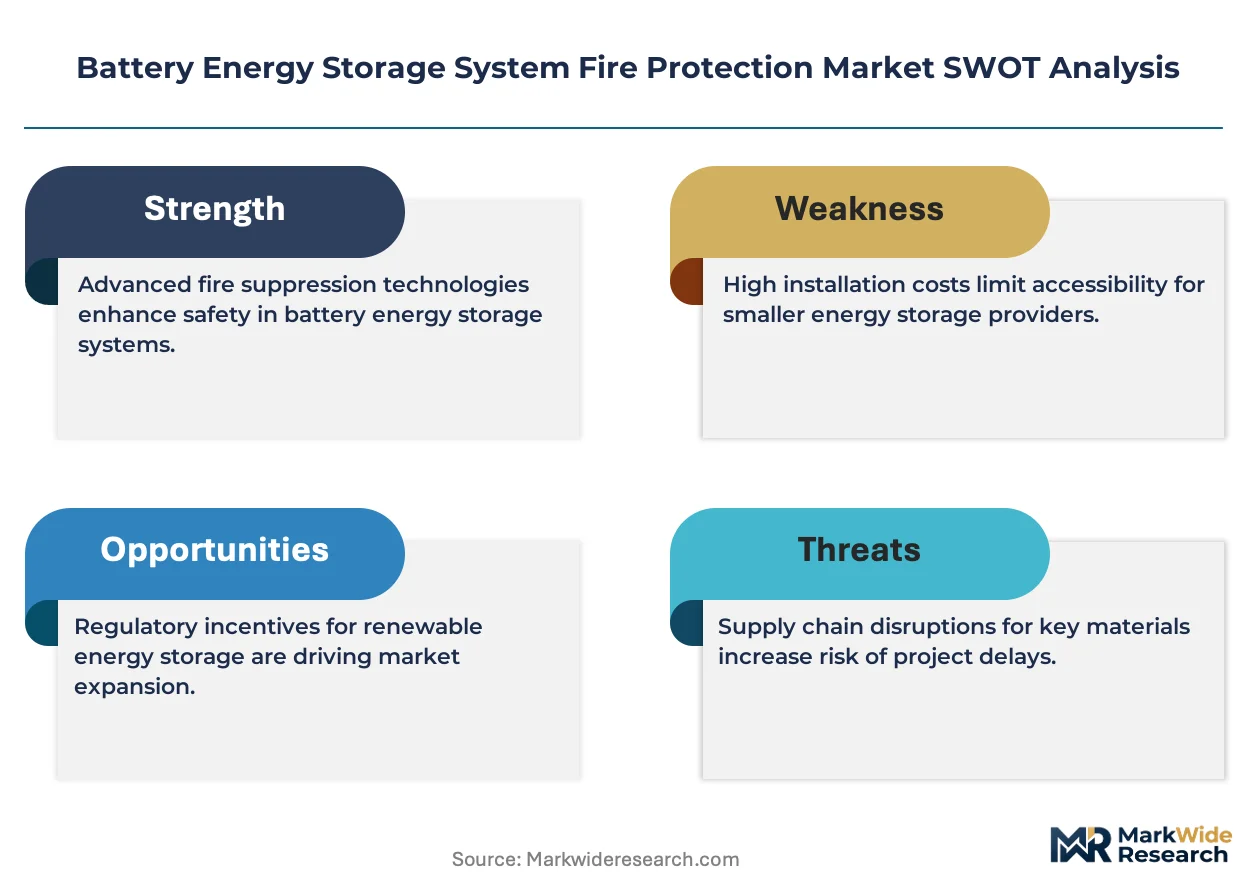
Thermal runaway propagation testing mandates are compressing supplier qualification timelines while simultaneously fragmenting procurement across specialized detection, suppression, and containment subsystems. NFPA 855 and evolving IEC standards now require full-scale cell-to-cell failure demonstration before system certification, forcing engineering teams to front-load validation spend.
Growth Catalysts
- Utility-scale solar-plus-storage deployments:California and Texas grid operators are mandating standalone battery installations, each requiring site-specific fire engineering studies that expand professional services attach rates.
- NFPA 855 adoption:US jurisdictions are embedding this standard into building codes, creating compliance-driven replacement cycles for pre-2020 installations lacking thermal barrier documentation.
- Aerosol suppression chemistry:Potassium-based condensed aerosol systems are gaining specification preference over clean agents due to reduced cleanup burden and electrical conductivity preservation.
Market Restraints
- Lithium carbonate price volatility:Input cost swings for battery cell production are delaying storage project financial closes, pushing fire protection procurement into contingency budgets.
- Chinese supply concentration:CATL and BYD captive fire protection integration limits third-party system penetration in the world's largest manufacturing base.
- Clean agent regulatory phase-out:F-Gas Regulation restrictions on fluorinated gases are forcing chemistry reformulation and re-certification timelines.
Strategic Opportunities
- Distributed commercial microgrids:Modular installation formats for C&I behind-the-meter storage remain underpenetrated relative to utility-scale deployments.
- Predictive thermal management convergence:Integration of battery management system data with fire detection algorithms enables pre-thermal-runaway intervention.
- Australian emergency response planning mandates:State-level requirements for site-specific fire brigade liaison protocols create recurring inspection revenue streams.
Industry Challenges
- Thermal barrier engineering specialization:Cell-to-cell propagation containment requires materials science expertise scarce in traditional fire protection contractor networks.
- Multi-standard certification complexity:Simultaneous UL, IEC, and local fire marshal approvals extend product launch timelines.
- Legacy HVAC integration:Retrofitting detection systems into existing climate control architectures without triggering false discharge remains technically demanding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Energy Storage System Fire Protection Market |
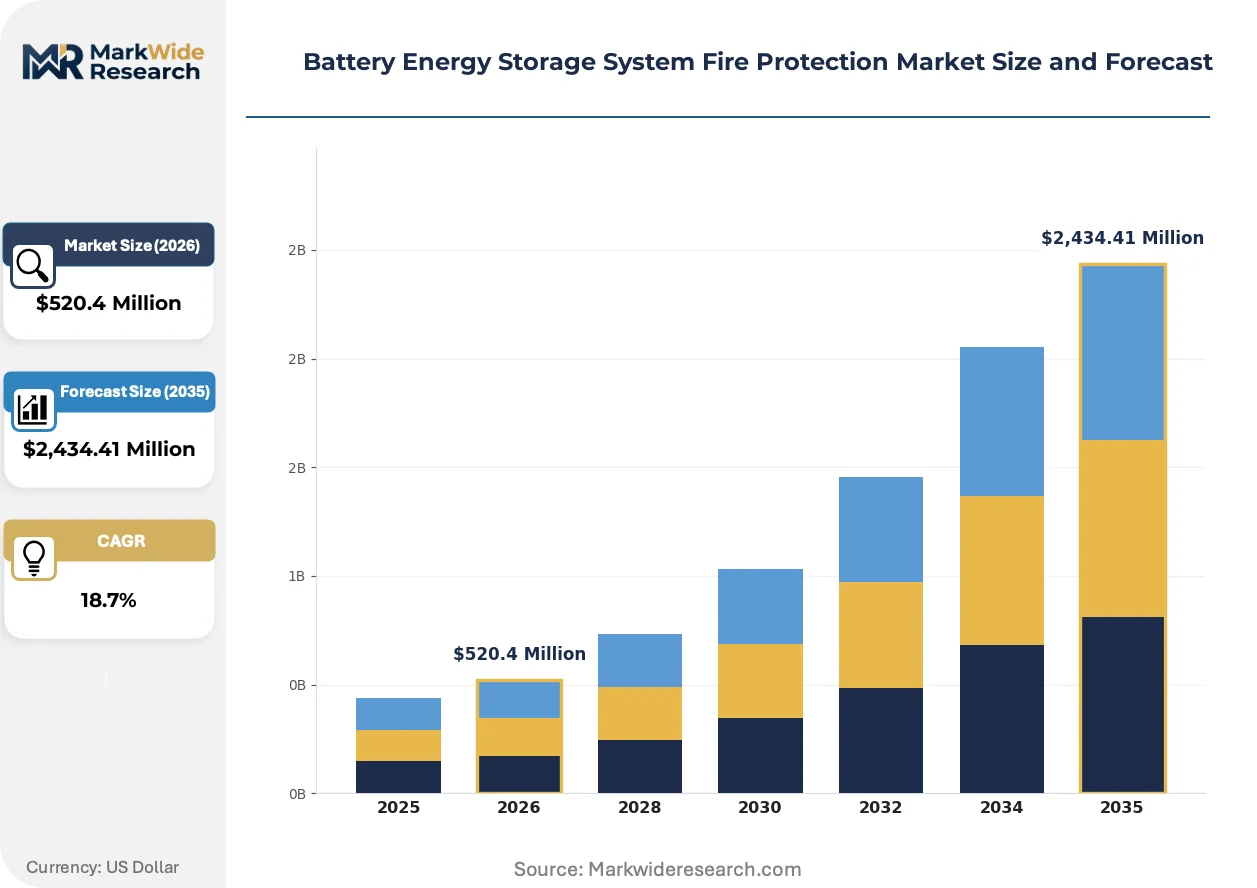
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $2,434.41 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Suppression Systems, Fire Detection Systems, Fire Barriers, Thermal Management Solutions Installation Type: Fixed Installation, Mobile Installation, Modular Installation, Integrated Systems End User: Utilities, Commercial Buildings, Residential Users, Industrial Facilities Compliance Standard: NFPA Standards, UL Standards, IEC Standards, Local Regulations |
| Companies Covered | Carrier, Clariant, Johnson Controls International PLC, Lanxess, ICL Group, Honeywell International Inc., Minimax GmbH & Co. KG, Solvay, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Energy Storage System Fire Protection Market Trends and Innovations
Detection-to-suppression latency compression is redefining system architecture as predictive analytics migrate from building automation into battery-specific safety loops. Engineers now specify integrated platforms where thermal sensor arrays trigger staged responses before cell venting occurs.
Multi-sensor fusion detection is decentralizing fire protection system topology across large-format battery installations. Arrays of hydrogen, temperature, and pressure sensors now feed edge-computing nodes that localize decision-making without central panel dependency. Utility-scale developers in Texas and California are specifying this architecture to reduce single-point-of-failure risk. The shift is compressing traditional panel-manufacturer margins while elevating sensor and software component suppliers.
EU battery safety directives are tightening propagation testing granularity beyond current IEC thresholds. The framework now requires documented containment performance across three consecutive cell failures rather than single-cell demonstration. European utility-scale developers are responding by specifying passive barrier systems with thicker ceramic fiber layers. German and French certification bodies are expanding testing capacity to address backlog.
Buyer specifications are fragmenting between risk-transfer and performance-guarantee contracting models. Large independent power developers now demand multi-year thermal runaway containment warranties backed by captive insurance pools. This displaces traditional equipment-purchase contracts with limited liability terms. The pattern is most visible in US independent power producer procurement, where project finance covenants now mandate extended coverage periods.
Battery Energy Storage System Fire Protection Market Segmentation
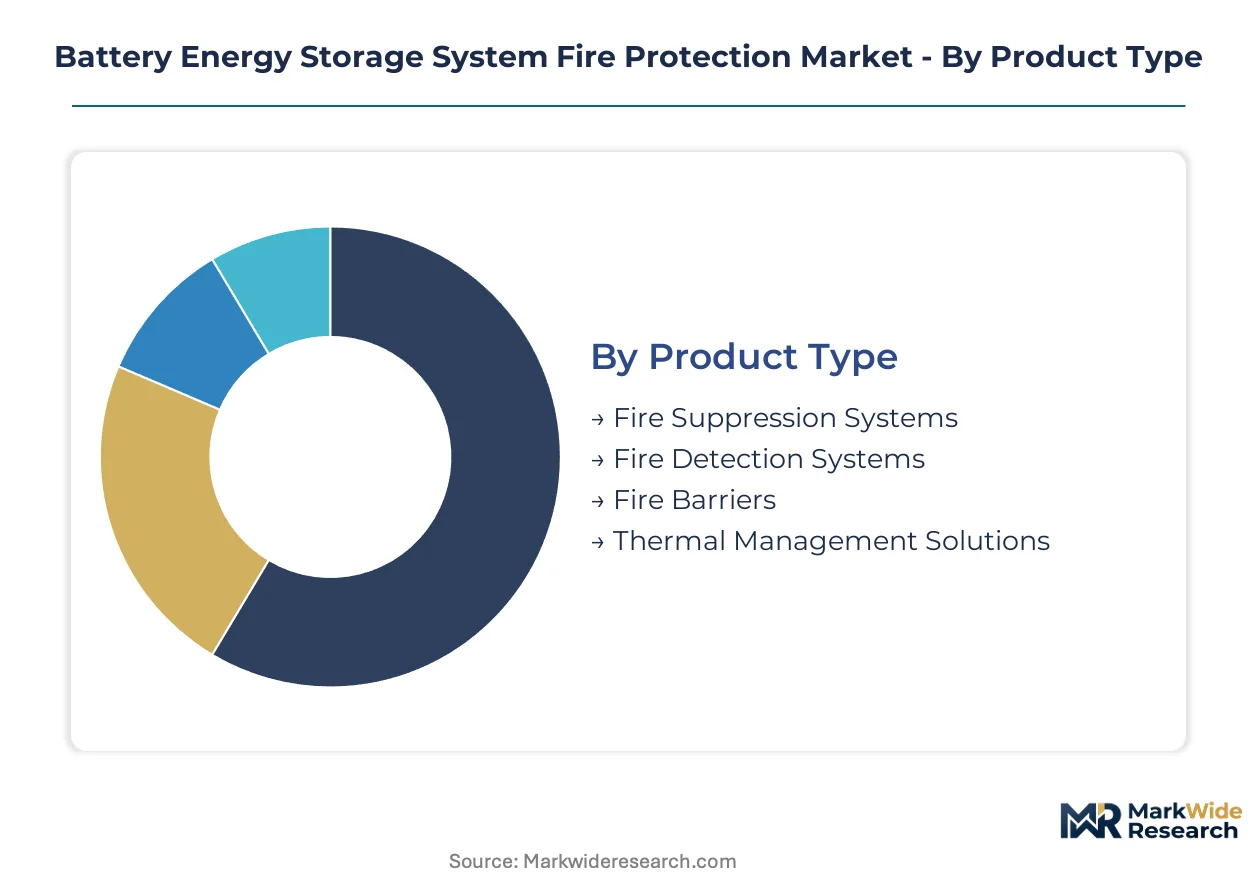
Fire protection procurement patterns diverge sharply across battery energy storage configurations, with suppression chemistry choices and installation formats determining project economics and regulatory compliance pathways. Segmentation reveals where engineering margins concentrate and which technology bundles command specification preference.
Product Type:
Supply concentration in aerosol chemistry and sensor manufacturing favors integrated system vendors over component specialists, compressing standalone equipment margins while elevating platform-level contracts.
- Fire Suppression Systems:Deploy aerosol, clean agent, or water mist discharge calibrated to 4-10 minute suppression windows while preserving electrical isolation. Utilities in California and Texas specify these for retrofitting pre-2020 installations lacking NFPA 855 thermal barrier documentation, driving replacement cycle volume.
- Fire Detection Systems:Multi-sensor fusion architectures decentralize topology across large-format installations, with hydrogen, temperature, and pressure sensors feeding edge-computing nodes. This architecture reduces single-point-of-failure risk for utility-scale developers.
- Fire Barriers:Passive containment systems with ceramic fiber layers meet EU propagation testing mandates requiring three consecutive cell failure documentation.
- Thermal Management Solutions:Predictive cooling integration with battery management systems enables pre-thermal-runaway intervention, climbing the fastest as OEMs embed fire safety into original equipment.
Today's leader: Fire Suppression Systems. Tomorrow's challenger: Thermal Management Solutions.
Installation Type:
Cost tier stratification separates capital-intensive fixed infrastructure from flexible modular formats suited to distributed deployment economics.
- Fixed Installation:Permanent infrastructure dominates current revenue share as utilities harden existing battery enclosures with retrofit suppression and detection arrays. These configurations anchor utility-scale solar-plus-storage deployments requiring site-specific fire engineering studies.
- Modular Installation:Containerized and skid-mounted formats accelerate deployment timelines for commercial and industrial microgrid projects. Distributed energy developers in behind-the-meter segments specify these for rapid relocation and capacity scaling.
- Mobile Installation:Transportable suppression units serve temporary construction-phase protection and emergency response staging at large battery facilities.
- Integrated Systems:Factory-embedded fire protection within battery enclosures captures specification preference from CATL and BYD gigafactory output, limiting third-party penetration.
Fixed Installation commands present procurement volume. Modular Installation gains specification share fastest in commercial microgrid expansion.
End User:
Application-driven requirements fragment between grid-scale risk-transfer contracting and behind-the-meter operational integration needs.
- Utilities:Independent power developers mandate multi-year thermal runaway containment warranties backed by captive insurance pools, displacing traditional equipment-purchase contracts. Project finance covenants in US independent power producer procurement now mandate extended coverage periods.
- Commercial Buildings:Behind-the-meter storage in retail, data center, and manufacturing facilities drives demand for compact detection-to-suppression latency compression. Building automation integration requirements favor vendors with heritage in facility energy management.
- Industrial Facilities:Heavy manufacturing and process industries specify fire protection for onsite backup power and peak shaving installations.
- Residential Users:Home battery systems represent emerging specification territory as local jurisdictions begin mandating detection and suppression for garage-mounted installations.
Utilities dominate contract value. Commercial Buildings represent the steepest expansion trajectory in unit deployment.
Compliance Standard:
Customer type stratification separates multinational OEMs requiring harmonized certification from regional integrators navigating jurisdiction-specific approval pathways.
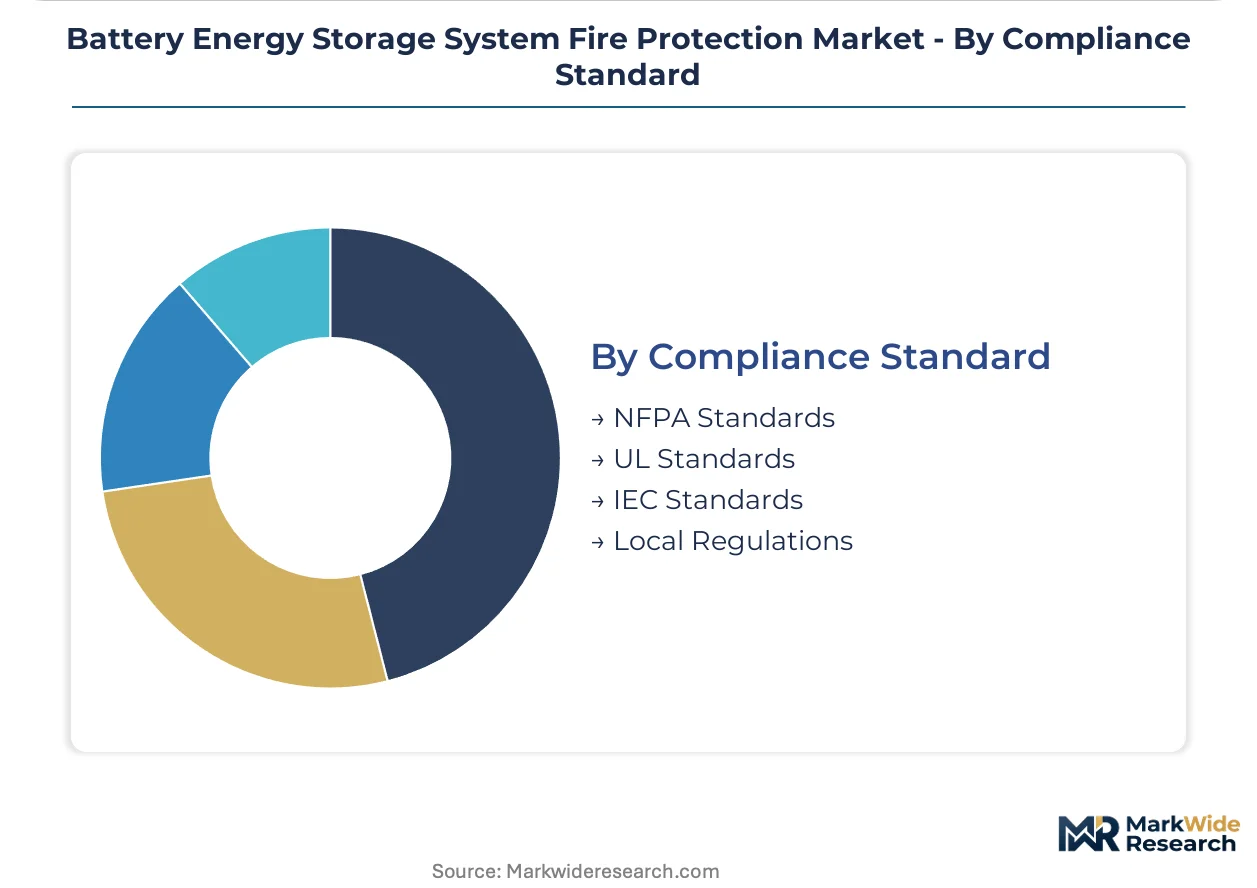
- NFPA Standards:NFPA 855 mandates in US jurisdictions create compliance-driven replacement cycles and elevate professional services attach rates for site-specific fire engineering studies. California and Texas grid operators embed these requirements into standalone battery installation approvals.
- IEC Standards:European and Asian market access requires IEC-compliant integrated safety architectures, with evolving EU battery safety directives tightening propagation testing granularity beyond current thresholds.
- UL Standards:US product safety certification underpins insurance and project finance requirements for battery storage fire protection equipment.
- Local Regulations:Australia and South Korea impose site-specific emergency response planning requirements that extend project timelines but deepen incumbent contractor relationships.
NFPA Standards anchor North American procurement. IEC Standards expand testing capacity fastest as European certification bodies address backlog.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas anchor North American procurement through utility-scale solar-plus-storage mandates, while China's gigafactory concentration and Germany's IEC certification backlog reveal divergent regional maturation patterns across fire protection integration timelines.
United States
California and Texas grid operators mandate standalone battery installations with site-specific fire engineering studies that expand professional services attach rates. NFPA 855 adoption across US jurisdictions creates compliance-driven replacement cycles for pre-2020 installations lacking thermal barrier documentation. Utility-scale developers in the ERCOT and CAISO territories specify aerosol suppression systems with reduced cleanup burden.
China
CATL and BYD's massive gigafactory expansions drive localized fire protection integration that limits third-party system penetration in the world's largest manufacturing base. The country's national battery safety regulator enforces propagation testing standards aligned with evolving international frameworks. Manufacturing clusters in Fujian and Shenzhen provinces embed factory-integrated fire protection within battery enclosures at the production stage.
Germany
European utility-scale deployments anchor on IEC-compliant integrated safety architectures with tightening propagation testing granularity. The F-Gas Regulation restricts fluorinated gas chemistries, forcing suppression system reformulation and re-certification timelines. Certification bodies in Berlin and Munich expand testing capacity to address backlog from EU battery safety directive implementation.
Australia
State-level emergency response planning mandates create recurring inspection revenue streams and extend project timelines while deepening incumbent contractor relationships. The country's national energy regulator imposes site-specific fire brigade liaison protocols for battery storage installations. Deployment clusters in New South Wales and Victoria specify modular installation formats for distributed commercial microgrid projects.
South Korea
Industrial facility backup power and peak shaving installations drive fire protection specification for heavy manufacturing onsite storage systems. The MFDS and national fire safety authorities coordinate battery-specific emergency response planning requirements. Manufacturing corridors around Seoul and Busan concentrate demand for fixed installation configurations in utility-scale hardening projects.
Battery Energy Storage System Fire Protection Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding platform-level contracts while component specialists face compressed standalone equipment margins. The structure concentrates around three strategic archetypes: building-automation heritage players leveraging facility energy management integration, captive sensor manufacturers with UL-certified suppression chemistry, and European engineering houses anchoring IEC-compliant safety architectures. Competitive moves center on backward integration into sensor manufacturing and geographic expansion through certification body partnerships to compress multi-standard approval timelines.
Among diversified industrial conglomerates, Johnson Controls International PLC, Honeywell International Inc., and Siemens AG exemplify contrasting strategic positioning archetypes. Johnson Controls leverages building-automation heritage to integrate fire detection with facility energy management systems. Honeywell sustains competitive positioning through captive sensor manufacturing capabilities. Siemens anchors European utility-scale deployments with integrated safety architectures compliant with IEC standards. These three represent the dominant tier structuring procurement patterns across North American and European utility-scale installations.
| Leading Market Players |
|---|
| Carrier |
| Clariant |
| Johnson Controls International PLC |
| Lanxess |
| ICL Group |
| Honeywell International Inc. |
| Minimax GmbH & Co. KG |
| Solvay |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Potassium-based aerosol precursor chemicals flow from Chinese specialty chemical manufacturers through three pricing tiers before reaching utility-scale installers in California and Texas. NFPA 855 compliance documentation costs separate premium-certified system integrators from commodity suppression equipment traders.
Pricing Analysis
Capacity additions in China's Fujian and Shenzhen manufacturing clusters are reshaping price floors for condensed aerosol suppression systems. Project-based contracting dominates procurement, with price differentiation hinging on UL 9540A certification tier and multi-year thermal runaway containment warranty terms. Pricing pressure stems from CATL and BYD's captive fire protection integration, compressing margins for third-party equipment vendors. Commercial and industrial microgrid developers exhibit highest price sensitivity, while US independent power producers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's battery storage procurement guidelines are reshaping sourcing patterns for European and North American system integrators. Manufacturing concentrates in China, South Korea, and Germany, with sensor arrays and suppression chemistry drawing from Taiwanese semiconductor foundries and Belgian fluorochemical specialists. Single-source vulnerability runs through Chinese lithium carbonate processing. Distribution runs through engineering-procurement-construction contractors with direct utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between China's integrated manufacturing cost base and Western jurisdictions' certification-premium pricing. Regulatory divergence between NFPA 855 and evolving EU battery safety directives creates margin capture opportunities for multi-standard suppliers.
For Market Incumbents: Acquire thermal barrier materials science capabilities to address cell-to-cell propagation engineering specialization scarcity. Johnson Controls and Honeywell should harden sensor manufacturing captive supply against Chinese supply concentration. Certification body partnerships in Berlin and Munich compress multi-standard approval timelines. Threat: Modular installation formats from distributed microgrid specialists erode fixed-installation revenue share. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer lowest-friction entry for aerosol chemistry specialists lacking incumbent EPC relationships. White-space targets include Australian emergency response planning inspection services and South Korean industrial facility peak-shaving installations. Penetrable segment: Behind-the-meter commercial building automation integration where building-heritage players lack battery-specific detection algorithms. For Investors and Strategic Acquirers: Consolidation pressure builds where thermal runaway propagation testing mandates fragment procurement across detection, suppression, and containment subsystems. Long-term viability favors platform-level contracts with captive insurance backing over standalone equipment margins. Acquisition target archetype: Edge-computing sensor fusion specialists with utility-scale deployment references. Signal to watch: Independent power producer procurement shifting from equipment purchase to performance-guarantee contracting models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Honeywell's captive production of hydrogen detection arrays secures supply chain control against Taiwanese foundry concentration. |
| Multi-Standard Certification Partnership | Siemens anchors European utility-scale deployments through Berlin and Munich testing body relationships compressing IEC approval timelines. |
| Predictive Thermal Management Platform Launch | Integration of battery management system data with fire detection algorithms enables pre-thermal-runaway intervention for OEM embedding. |
| Emergency Response Planning Service Expansion | Australian state-level fire brigade liaison mandates create recurring inspection revenue deepening incumbent contractor relationships. |
| Modular Installation Format Development | Containerized suppression systems capture commercial microgrid specification preference from distributed energy developers in Texas and California. |
Research Methodology
Bottom-up utility-scale and commercial-industrial deployment modeling reconciled against top-down suppression chemistry production tracking forms the analytical core. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fire protection system integrators combined with secondary validation from NFPA technical committee proceedings, UL certification databases, IEC standard development records, and FERC interconnection queue filings. Triangulation across stakeholder inputs and regulatory documentation ensures segment-level precision.
Historical trendline analysis of solar-plus-storage procurement patterns and thermal runaway incident reporting established baseline penetration rates across the projection horizon. Segmentation dimensions modeled include product type, installation format, end-user application, and compliance standard cluster. CAGRs derive from weighted capacity addition forecasts and technology substitution curves. Industry-specific inputs incorporate battery cell production expansion timelines and evolving propagation testing granularity requirements.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry would alter the outlook by displacing lithium-ion thermal runaway risk profiles. Forecasts reflect assumptions regarding NFPA 855 jurisdictional adoption velocity and F-Gas Regulation enforcement stringency. Supply chain disruption from lithium carbonate price volatility or Chinese manufacturing policy shifts could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Battery Energy Storage Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Solar Storage System Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Power Bank Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
Hydrogen Storage Cylinders Market