
 Battery Energy Storage Market | 2026-2036
Battery Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Energy Storage Market Analysis
Multi-source procurement for battery cells is consolidating as developers seek supply security amid raw material volatility. CATL leverages its integrated cathode-to-pack manufacturing to anchor cost positions across utility-scale projects. Tesla Energy competes through in-house cell production and software-defined power electronics. BYD Energy Storage sustains vertical control from lithium extraction to containerized systems, dominating integrated delivery models.
Battery energy storage systems electrochemically store electrical energy in modular cell assemblies, typically operating at voltages from 400V to 1500V DC before inversion, to enable time-shifted dispatch and grid services. These systems buffer intermittency from renewable generation and provide synthetic inertia to stabilize frequency deviations. Li-ion chemistry occupies the majority of installed capacity due to energy density advantages and manufacturing scale, though flow batteries are extending duration economics for multi-hour applications. Grid Stabilization and Frequency Regulation applications concentrate revenue pools where ancillary service markets compensate rapid response capability, while Peak Shaving segments grow fastest among commercial and industrial offtakers managing demand charges.
FERC Order 2222 in the United States enables distributed storage aggregation into wholesale markets, while the EU Green Deal and F-Gas Regulation shape battery manufacturing emissions standards and thermal management requirements across Europe. China's MIIT and GB standards mandate cell safety testing protocols that constrain market access for uncertified suppliers. Stakeholders must monitor evolving capacity market rules and carbon border adjustments that will determine competitive positioning in regional procurement cycles.
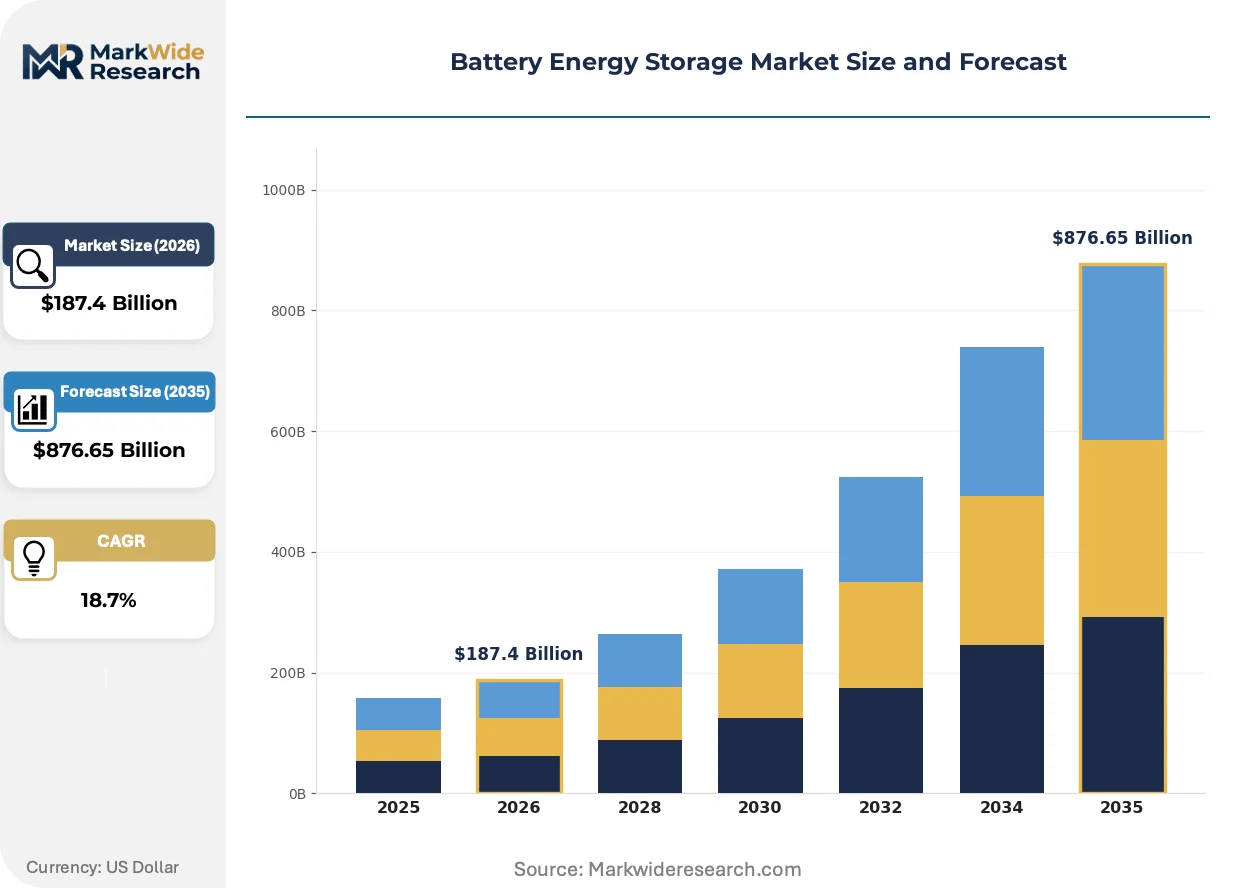
Market Dynamics
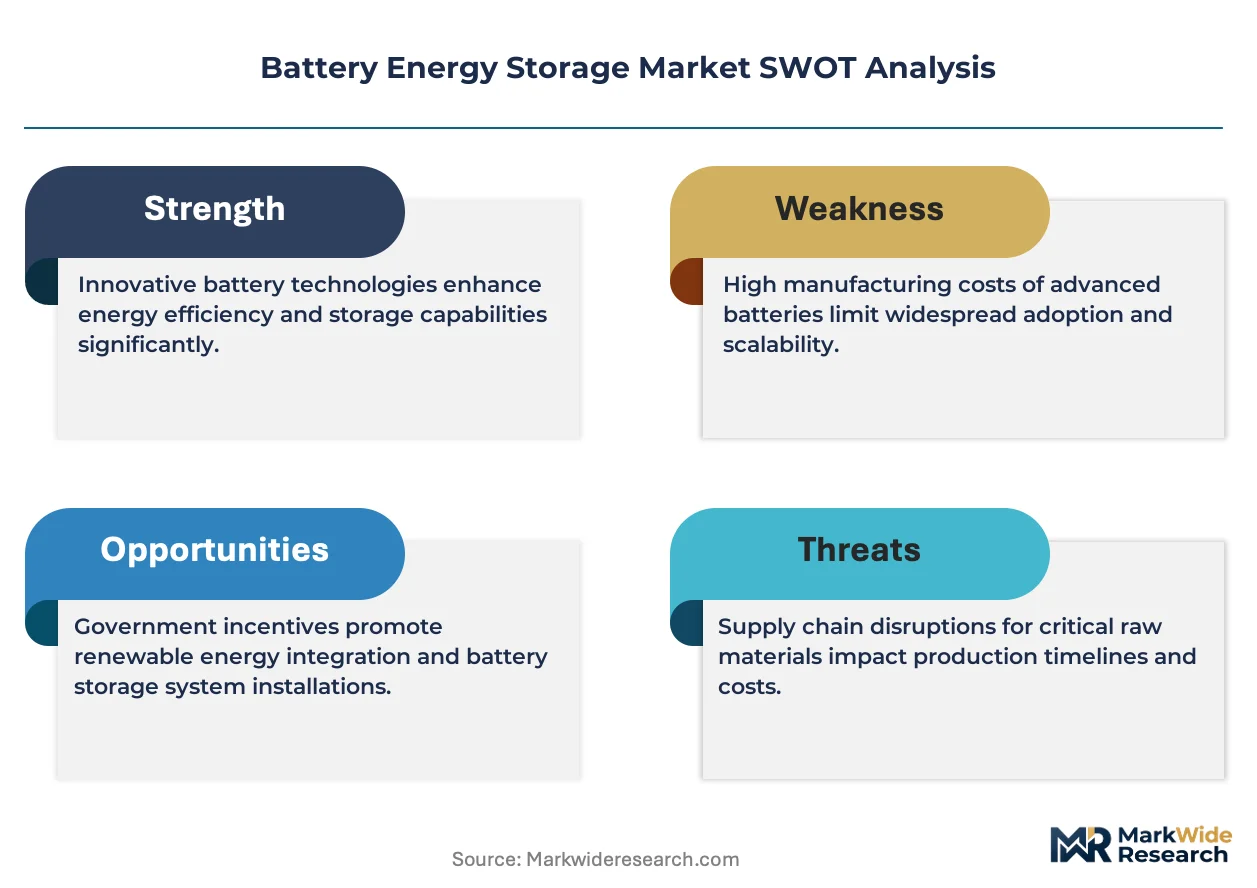
Lithium iron phosphate chemistry shifts are compressing supply chain exposure to cobalt and nickel price volatility while redirecting capital toward integrated cathode manufacturing.
Growth Catalysts
- IRA Production Credits:The United States Inflation Reduction Act's manufacturing tax credits are pulling cell and pack assembly capacity toward domestic facilities, accelerating project development timelines.
- Grid Modernization Mandates:China's MIIT battery safety standards are forcing technology upgrades that expand addressable market for certified system integrators.
- Solar-Plus-Storage Procurement:Utility-scale developers in Germany are bundling photovoltaic and battery assets into single tender submissions, creating integrated revenue streams.
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings constrain project financing certainty for independent power producers without long-term offtake contracts.
- Cathode Concentration:Supply risk concentrates in integrated Chinese manufacturers controlling lithium conversion and precursor chemical production.
- Duration Economics Ceiling:Lithium-ion chemistry faces fundamental cost barriers beyond four-hour discharge durations, limiting multi-day storage applications.
Strategic Opportunities
- India Grid-Scale Deployment:The country's renewable purchase obligations and PLI scheme for advanced chemistry cells create first-mover positioning for containerized system suppliers.
- FERC Order 2222 Aggregation:Distributed storage virtual power plants unlock wholesale market revenue for commercial and industrial behind-the-meter installations.
- Flow Battery Convergence:Vanadium redox technology pairing with lithium-ion in hybrid configurations extends project duration without full chemistry substitution.
Industry Challenges
- Battery Management System Integration:Cell-to-pack architectures demand software competency that legacy inverter manufacturers struggle to build organically.
- UL 9540A Certification Timelines:Thermal runaway propagation testing delays product launches by 12-18 months, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Energy Storage Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $876.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Li-ion, Lead Acid, Flow Batteries, Sodium-Sulfur End User: Utilities, Renewable Energy, Commercial, Residential Installation: Onsite, Offsite, Mobile, Centralized Application: Grid Stabilization, Peak Shaving, Backup Power, Frequency Regulation |
| Companies Covered | Sungrow, Siemens Battery Storage, CATL, Pylontech, EVE Energy, BYD Energy Storage, LG Energy Solution, Huawei Digital Power, Tesla Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Energy Storage Market Emerging Trajectories
Active materials innovation and software-defined architectures are compressing system cost curves while expanding revenue stack complexity for asset operators.
Solid-state electrolyte development is electrifying next-generation cell designs by replacing flammable liquid electrolytes with ceramic or polymer alternatives. Automotive suppliers are transferring pilot-line capacity toward stationary storage validation. This transition is electrifying safety standards and enabling denser pack configurations for urban substation installations.
The EU F-Gas Regulation is phasing down fluorinated greenhouse gases used in battery thermal management systems, forcing refrigerant transitions toward CO2 or propane-based cooling. European system integrators are redesigning container HVAC architectures to maintain fire suppression compatibility. Grid-scale projects in Germany and the Netherlands face compressed commissioning schedules to lock in grandfathered equipment certifications.
Merchant revenue stacking is displacing single-service contracting as independent power producers seek to capture multiple value streams from single assets. Developers are unbundling energy arbitrage, frequency regulation, and capacity payments into optimized dispatch algorithms. This behavior is most visible in Texas ERCOT and California CAISO markets where nodal pricing creates locational value differentiation.
Battery Energy Storage Market Segmentation
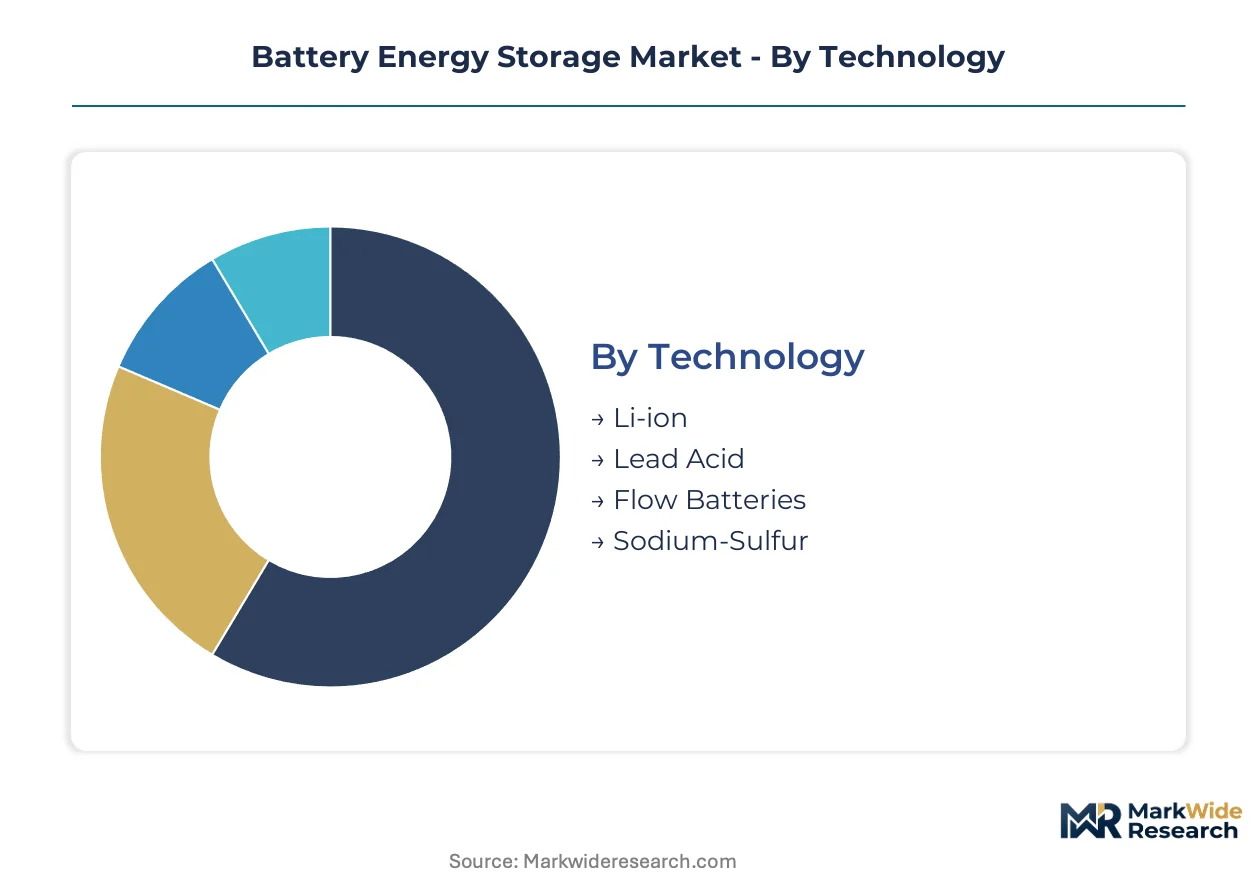
Technology choices in battery energy storage dictate project economics, supply chain exposure, and revenue stack complexity. Segmentation reveals where capital concentrates and which configurations unlock merchant market participation.
Technology:
Supply concentration in cathode precursor manufacturing favors chemistries with domestic conversion pathways.
- Li-ion:Lithium iron phosphate and nickel manganese cobalt variants dominate utility-scale procurement due to energy density above 150 Wh/kg and manufacturing scale. Demand clusters in China, the United States, and Germany where IRA production credits and MIIT safety standards redirect supply chain investments toward certified cell suppliers.
- Flow Batteries:Vanadium redox systems decouple power and energy ratings through external electrolyte tanks, enabling 8-12 hour discharge without lithium-ion cost penalties. Installations concentrate in Germany and Australia where multi-day storage procurement targets favor duration-optimized chemistries.
- Lead Acid:Mature recycling infrastructure and low capital cost sustain niche deployment in backup power applications with shallow discharge requirements.
- Sodium-Sulfur:High operating temperature and molten electrolyte chemistry suit grid-scale installations in Japan where METI demonstration programs validate long-duration performance.
Li-ion absorbs the bulk of installed capacity; flow batteries are expanding most quickly.
End User:
Customer type determines contracting structure and exposure to merchant price volatility.
- Utilities:Vertically integrated grid operators procure containerized systems through 10-20 year capacity contracts, prioritizing UL 9540A certification and synthetic inertia capability for frequency response markets.
- Renewable Energy:Solar and wind developers bundle storage to firm output profiles and capture time-shifted energy arbitrage in nodal pricing markets like ERCOT and CAISO.
- Commercial:Behind-the-meter installations target demand charge reduction through peak shaving algorithms, with FERC Order 2222 aggregation enabling wholesale market participation.
- Residential:Home energy management systems pair rooftop solar with 5-15 kWh wall-mounted units, concentrated in California NEM 3.0 transition markets and German feed-in tariff expiration regions.
Utilities command the largest project pipelines; commercial installations are gaining share fastest.
Installation:
Physical deployment mode shapes permitting timelines and interconnection cost allocation.
- Onsite:Co-located with generation or load, these systems minimize transmission upgrade requirements and capture locational marginal pricing advantages at congested nodes.
- Offsite:Standalone merchant projects in Texas and California procure independent transmission service, requiring FERC interconnection queue navigation and nodal congestion analysis.
- Mobile:Containerized trailer-mounted units serve construction sites and emergency response, with deployments concentrated in disaster-prone regions requiring rapid grid restoration.
- Centralized:Utility-owned substation installations aggregate multiple revenue streams through software-defined dispatch, dominating frequency regulation procurement in PJM and CAISO markets.
Centralized installations anchor utility procurement; mobile configurations are climbing the fastest.
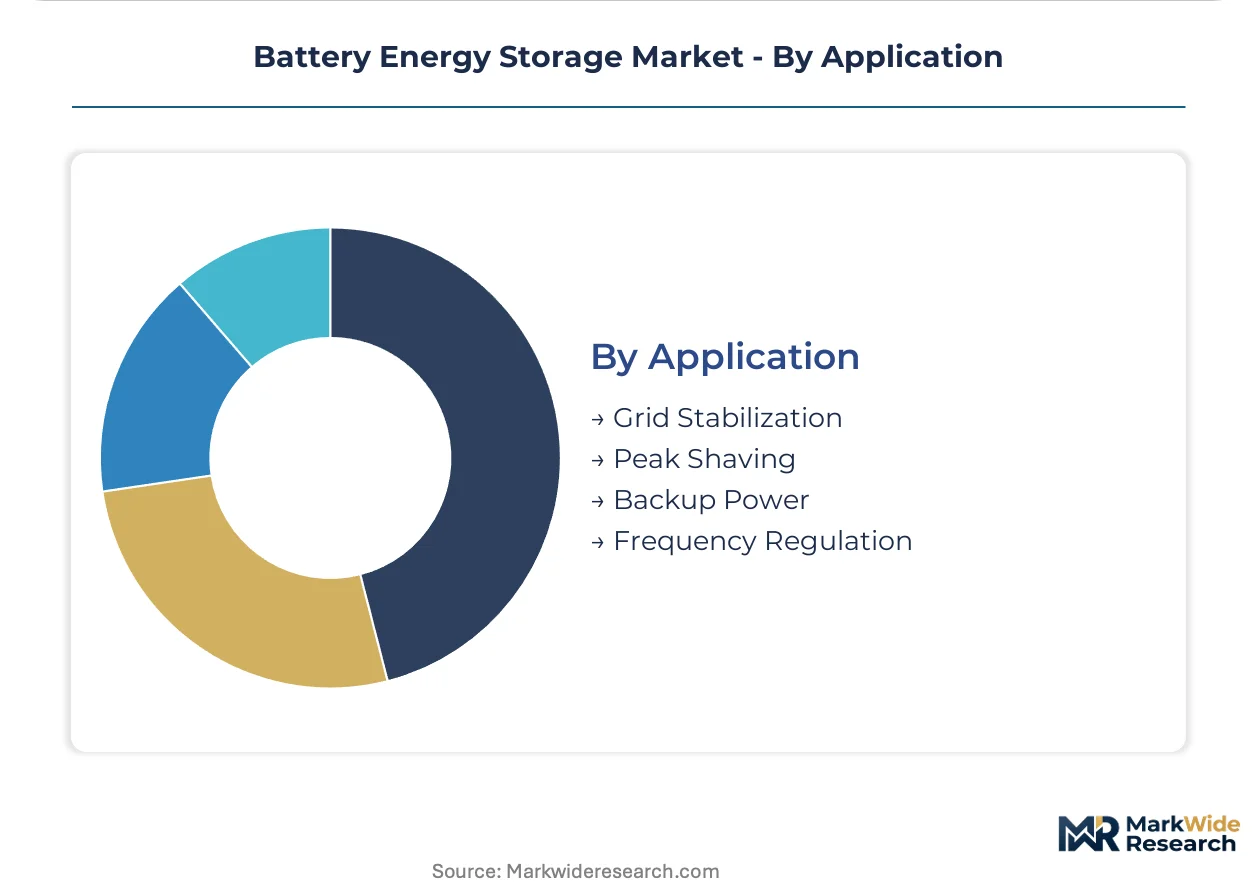
Application:
Revenue stack composition varies by service type and market design maturity.
- Grid Stabilization:Synthetic inertia and voltage support services compensate rapid response capability, with procurement concentrated in island grids and weak network areas in Australia and the United Kingdom.
- Peak Shaving:Time-shifted discharge during high-price periods captures energy arbitrage spreads, dominating commercial and industrial economics in demand-charge-heavy jurisdictions like California and New York.
- Backup Power:Uninterruptible supply for critical facilities sustains lead acid and lithium-ion deployment in healthcare and data center verticals.
- Frequency Regulation:Sub-second response to area control error signals generates capacity payments in organized markets, with fastest-growing procurement in ERCOT's new ancillary service products.
Peak shaving captures the largest revenue pool; frequency regulation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate conversion capacity in Qinghai and Sichuan provinces anchors China's dominance in cathode precursor supply, while IRA production credits redirect cell assembly investments toward domestic U.S. facilities. Utility-scale procurement concentrates in jurisdictions with mature ancillary service markets and renewable integration mandates.
United States
Texas ERCOT and California CAISO markets drive merchant storage deployment through nodal pricing and frequency regulation products. FERC Order 2222 enables distributed aggregation into wholesale markets, accelerating behind-the-meter commercial installations. Arizona and Nevada host gigawatt-scale solar-plus-storage clusters where developers exploit high solar irradiance and transmission congestion.
China
MIIT battery safety standards and GB certification protocols constrain market access while expanding procurement for certified system integrators. Xinjiang and Inner Mongolia wind bases pair with co-located storage to curtail grid integration costs. Yangtze River Delta manufacturing clusters concentrate cathode-to-pack integration capacity serving domestic and export markets.
Germany
EU Green Deal carbon border adjustments and F-Gas Regulation thermal management requirements reshape container HVAC specifications. North Rhine-Westphalia and Bavaria host utility-scale tenders bundling photovoltaic and battery assets into single procurement submissions. Industrial demand charges in Baden-Württemberg drive commercial peak shaving deployments.
India
Renewable purchase obligations and PLI scheme incentives for advanced chemistry cells attract containerized system suppliers to Gujarat and Tamil Nadu grid-scale tenders. CEA technical standards mandate frequency response capability for grid-connected assets. Karnataka and Andhra Pradesh solar parks integrate co-located storage to manage evening ramp constraints.
Australia
National Electricity Market ancillary service reforms compensate synthetic inertia and fast frequency response from grid-scale batteries. South Australia and Victoria weak network areas prioritize voltage support procurement. Queensland and New South Wales coal plant retirements accelerate replacement storage tenders with multi-hour duration requirements.
Battery Energy Storage Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated manufacturers scale cathode-to-pack operations to capture IRA production credits and MIIT-certified supply contracts. The vendor base stratifies into three tiers: vertically integrated cell producers controlling lithium conversion, system integrators sourcing cells from multiple suppliers, and software-defined power electronics specialists. Strategic archetypes include chemistry-agnostic integrators, captive cathode manufacturers, and dispatch optimization platforms. M&A activity concentrates on battery management system capabilities and regional project development pipelines.
Among Asia-Pacific-based integrated manufacturers, CATL and BYD Energy Storage exemplify cathode-to-container vertical control, while Tesla Energy represents the software-defined power electronics archetype with in-house cell production. These three anchors illustrate divergent paths to cost position and revenue stack capture in utility-scale procurement cycles.
| Leading Market Players |
|---|
| Sungrow |
| Siemens Battery Storage |
| CATL |
| Pylontech |
| EVE Energy |
| BYD Energy Storage |
| LG Energy Solution |
| Huawei Digital Power |
| Tesla Energy |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate conversion costs cascade from Qinghai and Sichuan extraction through cathode precursor manufacturing to containerized system assembly, with IRA production credits and MIIT certification tiers segmenting procurement pools into premium-certified and economy-uncertified bands.
Pricing Analysis
Warranty bundling separates premium-tier suppliers offering 15-20 year performance guarantees from economy players selling bare hardware without degradation coverage. Price differentiation rests on UL 9540A certification status and software-defined dispatch capability, with certified integrators commanding substantial premiums over uncertified pack assemblers. Pricing pressure stems from cathode material volatility compressing margins for non-integrated developers. Utility offtakers show lowest price sensitivity due to long-term capacity contracts, while commercial behind-the-meter buyers prioritize upfront capital minimization over lifecycle cost optimization.
Supply Chain Analysis
End-of-life battery flows through refurbishment and second-life stationary applications before final recycling, creating reverse-logistics revenue streams for integrators with disassembly capabilities. Cell production concentrates in China, South Korea, and Japan, with cathode precursor chemistry drawing from lithium conversion capacity anchored in domestic Chinese supply. Single-source vulnerability concentrates in integrated manufacturers controlling lithium extraction through pack assembly. Distribution runs through EPC contractors and direct utility procurement channels with multi-year offtake structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where UL 9540A and MIIT GB certification requirements erect barrier-to-entry moats favoring capital-rich incumbents with testing infrastructure and regulatory affairs capabilities.
For Market Incumbents: To counter emerging software-defined power electronics specialists, anchor market position through captive cathode manufacturing investments in IRA-eligible U.S. facilities and accelerate UL 9540A pre-certification for next-generation cell-to-pack architectures before competitors complete testing timelines.
For New Entrants and Emerging Players: The premium-to-economy price gap in commercial behind-the-meter installations offers accessible entry points for containerized system suppliers targeting FERC Order 2222 aggregation opportunities with hardware-agnostic battery management software and streamlined installation partnerships.
For Investors and Strategic Acquirers: FERC interconnection queue clearance velocity is the leading indicator that merchant storage deployment is accelerating; prioritize acquisition targets with cleared queue positions and software-defined dispatch platforms capable of revenue stacking across multiple ancillary service products.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Manufacturing Scale-Up | CATL and BYD leverage integrated cathode-to-container production to capture IRA production credits and MIIT certification advantages. |
| Software-Defined Dispatch Platform Development | Tesla Energy and Huawei Digital Power unbundle energy arbitrage, frequency regulation, and capacity payments through algorithmic optimization. |
| Long-Term Cathode Supply Agreement | System integrators without captive lithium conversion secure precursor chemical offtake to insulate project financing from carbonate volatility. |
| UL 9540A Pre-Certification Investment | Early thermal runaway propagation testing compresses product launch timelines and expands competitive windows in utility procurement cycles. |
| Hybrid Flow Battery Integration Partnership | Vanadium redox pairing with lithium-ion extends project duration economics without full chemistry substitution in multi-hour applications. |
Methodological Framework
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings, with secondary validation drawing from EIA project databases, FERC interconnection filings, IEA stationary storage outlooks, and MIIT certification registries; bottom-up project pipelines and top-down capacity forecasts were triangulated to anchor volume estimates.
Comparable historical deployment periods through the projection horizon established baseline growth trajectories, with the analytical framework modeling technology chemistry, end-user contracting structure, installation deployment mode, and application revenue stack as core segmentation dimensions; CAGRs were derived from installed capacity buildout curves and system cost compression rates, incorporating IRA credit eligibility and carbon border adjustment exposure as forecast sensitivity inputs.
Inputs from regulatory filing databases and project development trackers were available through the study window; gaps in merchant revenue realization data introduce uncertainty bands around dispatch optimization assumptions. Practitioners should monitor FERC Order 2222 implementation pace and lithium carbonate spot price volatility for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
South America Energy Storage Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Ultracapacitors Market
Energy Storage
Germany Energy Storage Systems Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Grid Scale Battery Storage Sales Market