
 Solar Storage Inverter Market | 2026-2036
Solar Storage Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Storage Inverter Market Insights
Residential battery attachment is collapsing as the dominant buyer archetype, while commercial and industrial microgrid operators gain procurement share. SolarEdge Technologies leverages its power optimizer architecture to sustain premium positioning in retrofit-heavy European markets. Sungrow Power Supply anchors its position through captive cell-to-inverter integration, dominating utility-scale tenders across Asia-Pacific.
A solar storage inverter converts direct current from photovoltaic arrays and battery banks into grid-synchronized alternating current, typically operating at 97-99% peak efficiency with switching frequencies between 2-20 kHz depending on topology. Its primary purpose is enabling bidirectional energy flow between generation, storage, and load while maintaining grid code compliance. Hybrid inverters lead product type revenue pools by capturing both solar conversion and battery management functions in single hardware stacks. Smart inverter deployments are accelerating fastest among technology categories as grid operators in Germany and Australia mandate dynamic volt-var response and ride-through capabilities.
The US Federal Energy Regulatory Commission and state-level public utility commissions shape interconnection queues and storage participation rules in wholesale markets. Europe's F-Gas Regulation and CE marking requirements under the EU Green Deal constrain coolant choices and electromagnetic compatibility thresholds for inverter imports. China's National Energy Administration and GB standards dictate efficiency benchmarks and grid connection protocols for domestic manufacturers. Stakeholders must monitor whether IEEE 1547-2018 interoperability mandates in the US and impending EU Battery Regulation due diligence rules fragment certification requirements across export markets.
Market Dynamics
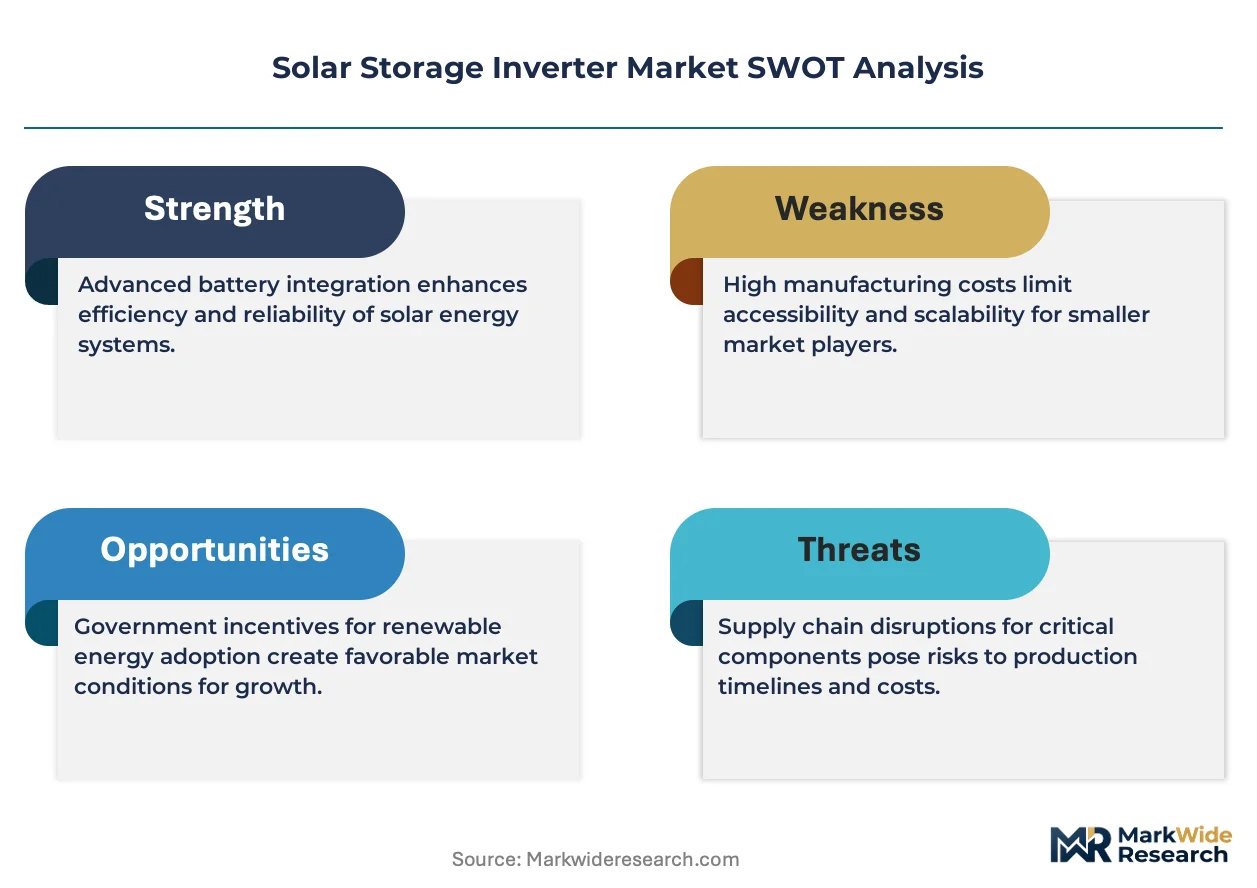
Utility-scale solar-plus-storage procurement in Texas and California is compressing delivery timelines and forcing inverter manufacturers to pre-certify hardware stacks before interconnection queue deadlines, squeezing engineering margins across the supply base.
Growth Catalysts
- US Investment Tax Credit extension:The federal incentive structure now explicitly covers standalone storage, redirecting capital toward hybrid inverter configurations that couple photovoltaic generation with battery management in single enclosures.
- Commercial microgrid operators:Data center and semiconductor fabrication facilities in Arizona and Nevada are procuring three-phase hybrid inverters to island from grid disturbances, creating a premium segment detached from residential attachment rates.
- Silicon carbide switching:Wide-bandgap semiconductor adoption is pushing peak efficiency thresholds toward 99% while reducing thermal management overhead, enabling higher power density in containerized utility deployments.
Market Restraints
- IGBT supply concentration:Power module fabrication for high-voltage inverters depends on a concentrated East Asian supplier base, exposing procurement timelines to foundry allocation cycles and geopolitical export controls.
- F-Gas Regulation coolant constraints:Europe's phasedown of hydrofluorocarbon refrigerants is forcing thermal design revisions for liquid-cooled inverters, extending certification timelines by 6-12 months for products targeting EU markets.
- Electrolytic capacitor lifespans:DC-link capacitors in string inverter architectures degrade asymmetrically under high-ripple current conditions, creating warranty exposure in hot-climate installations where replacement economics favor full system retirement.
Strategic Opportunities
- India CEA grid code alignment:Central Electricity Authority technical standards for distributed solar-plus-storage are stabilizing, opening tender opportunities for inverter suppliers willing to localize final assembly and establish service networks.
- Virtual power plant aggregation:Software-layer orchestration of residential battery fleets is creating recurring revenue streams for inverter OEMs that embed telemetry and dispatch-responsive firmware at the factory.
- Agricultural irrigation microgrids:California's Central Valley and Australia's Murray-Darling Basin are deploying solar-storage inverters to displace diesel pumping, representing an underpenetrated application with high utilization rates and predictable load profiles.
Industry Challenges
- IEEE 1547-2018 interoperability testing:Utility interconnection approval requires validated ride-through and volt-var response across multiple regional transmission operator specifications, fragmenting firmware development resources and extending time-to-revenue.
- Power electronics engineering scarcity:Magnetics design and EMI mitigation expertise concentrates among senior practitioners approaching retirement, constraining R&D throughput for emerging topologies like multilevel T-type inverters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Storage Inverter Market |
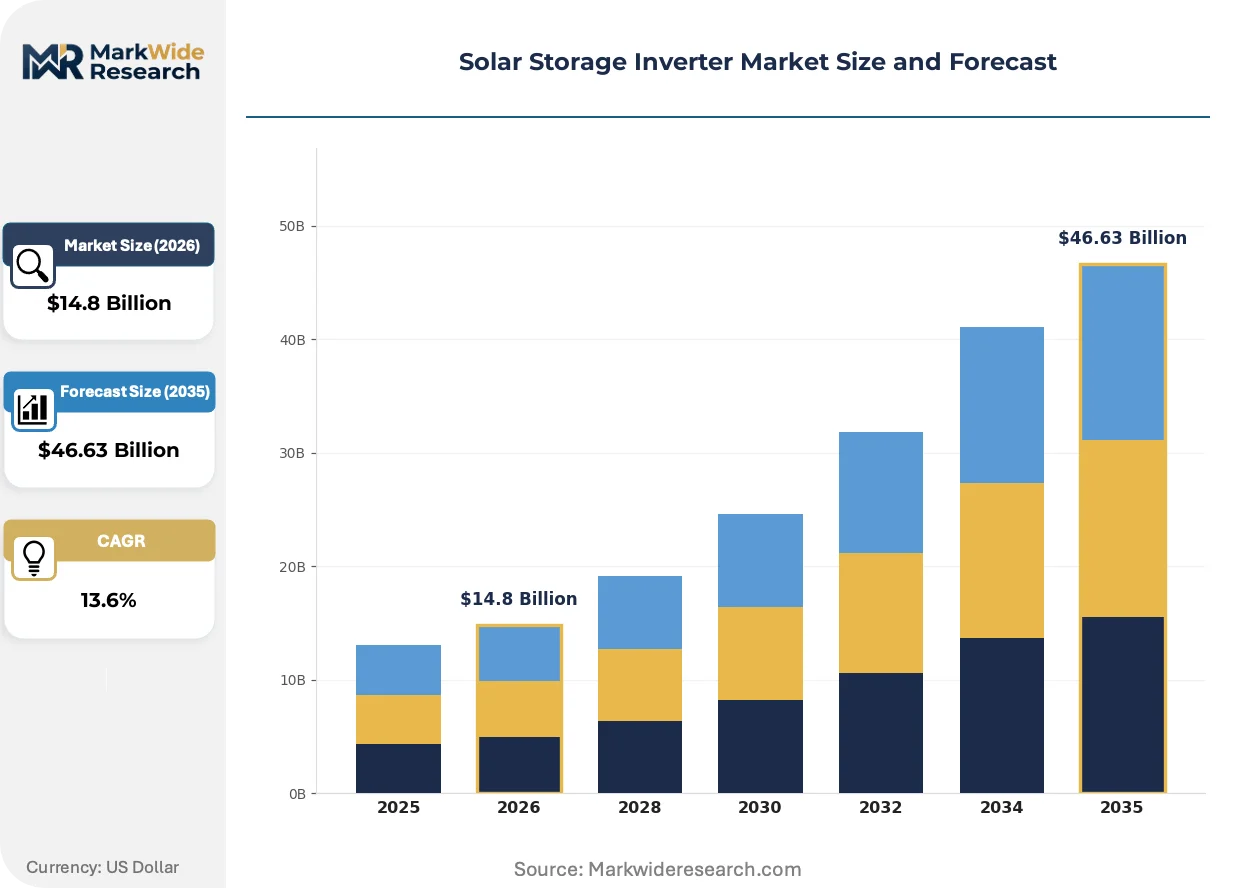
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Micro Inverters, Power Optimizers, Hybrid Inverters Technology: Grid-Tied, Off-Grid, Battery-Based, Smart Inverters End User: Residential, Commercial, Industrial, Utilities Installation Type: Indoor, Outdoor, Wall-Mounted, Ground-Mounted |
| Companies Covered | SolarEdge Technologies, Ginlong Technologies, Sungrow Power Supply, Tesla, SMA Solar Technology, FIMER, Enphase Energy, Power Electronics, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Storage Inverter Market Trends and Innovations
Hardware-software convergence is redefining competitive differentiation, as grid-forming capability and predictive maintenance algorithms displace raw efficiency metrics as primary procurement criteria in utility tenders.
Silicon carbide MOSFET deployment in three-level active neutral-point-clamped topologies is fragmenting the traditional string-versus-central inverter dichotomy. Mid-scale commercial projects in Germany and Australia are adopting modular power blocks that parallel at the medium-voltage level, compressing balance-of-system costs while complicating service training requirements for local integrators.
Europe's F-Gas Regulation and impending EU Battery Regulation due diligence rules are tightening material traceability and thermal fluid disclosure requirements for imports. Inverter manufacturers serving the bloc must reconfigure supply chains to document conflict mineral status and carbon intensity across cell-to-inverter integration partners, with enforcement beginning at the port-of-entry customs level.
Aggregators are consolidating residential battery fleets into wholesale market participation vehicles, unbundling hardware procurement from revenue optimization services. California's NEM 3.0 export compensation collapse has accelerated this shift, with homeowners prioritizing inverter compatibility with third-party virtual power plant platforms over manufacturer-branded energy management applications.
Solar Storage Inverter Market Segmentation
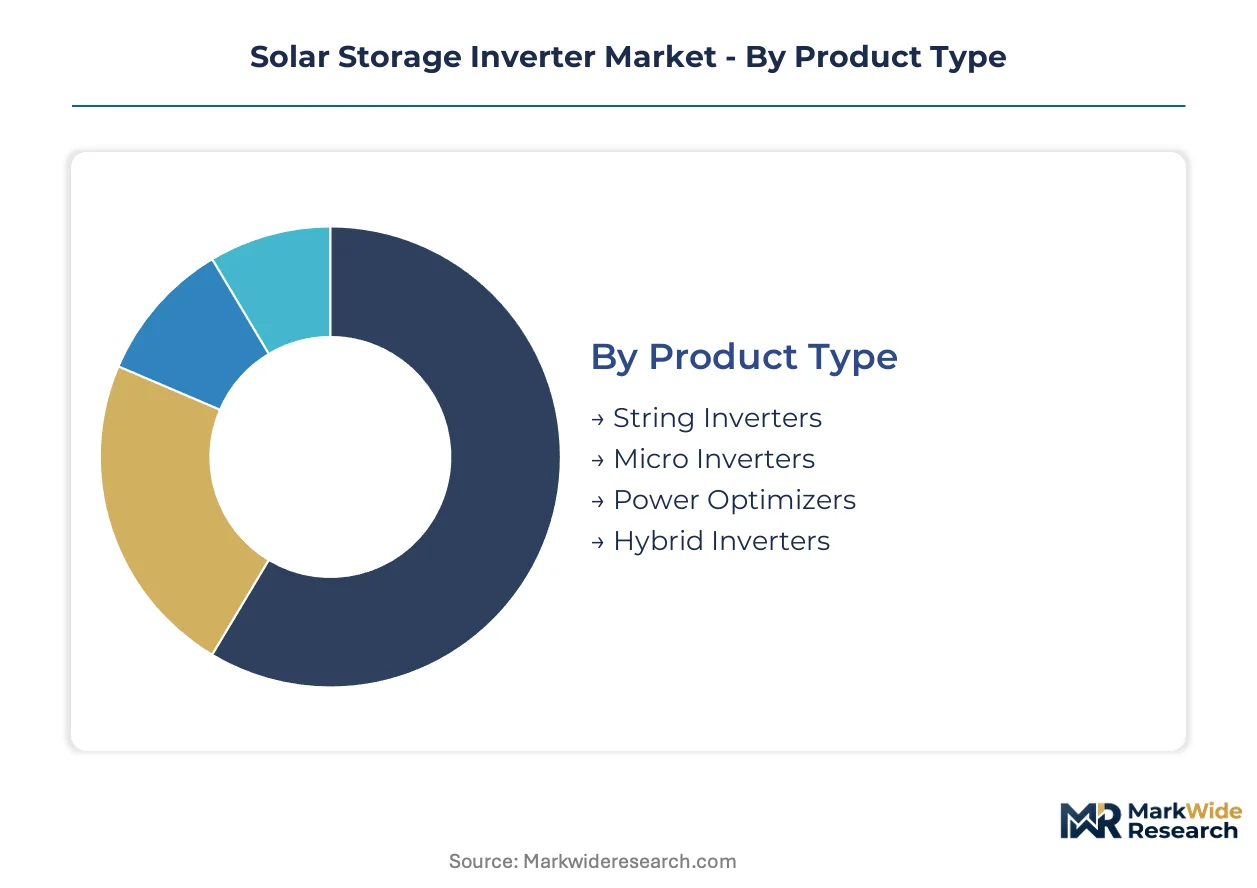
Segmentation in solar storage inverters reveals how hardware specifications, grid interconnection protocols, and installation constraints fragment procurement patterns across customer archetypes. Each dimension carries distinct certification burdens and margin structures that reshape competitive positioning.
Product Type:
Hybrid inverters face the most intense substitution pressure as standalone battery inverters and AC-coupled retrofits erode their historical advantage in new-build solar-plus-storage projects.
- Hybrid Inverters:Single-enclosure units combine photovoltaic DC/AC conversion with bidirectional battery management, typically rated 3-50 kW residential and 100 kW-5 MW utility-scale. Demand concentrates in Texas and California utility-scale tenders where compressed interconnection timelines favor pre-integrated hardware stacks.
- String Inverters:Centralized DC/AC conversion for serially connected module strings dominates commercial rooftops and utility ground-mounts through cost-optimized silicon IGBT topologies. Procurement from data center operators in Arizona and Nevada favors three-phase variants with ride-through capabilities for microgrid islanding.
- Micro Inverters:Module-level power electronics eliminate string mismatch losses and enable granular monitoring for residential retrofits with complex roof geometries.
- Power Optimizers:DC-to-DC converters at the module level pair with centralized string inverters to deliver panel-level optimization without full micro inverter cost premiums.
String inverters retain volume leadership across utility and commercial procurement channels; hybrid inverters hold the steepest expansion curve as storage attachment rates climb in new solar deployments.
Technology:
Cost tier differentiation separates basic grid-tied units from premium smart inverter categories that command firmware-enabled service revenue streams.
- Smart Inverters:Grid-supportive functionality including dynamic volt-var response, frequency-watt control, and remote telemetry integration. Germany and Australia mandate these capabilities for distributed resource interconnection, concentrating demand among utilities managing high renewable penetration.
- Grid-Tied Inverters:Synchronous operation with utility frequency and voltage without storage integration serves pure solar export economics in markets with favorable net metering.
- Battery-Based Inverters:Designed for DC-coupled or AC-coupled storage retrofit, these units prioritize charge/discharge efficiency and battery management system communication protocols.
- Off-Grid Inverters:Standalone operation with battery backup for sites beyond utility infrastructure serves agricultural pumping in California's Central Valley and remote mining operations.
Grid-tied technology dominates installed base economics; smart inverters are climbing the fastest as grid operators impose advanced inverter standards.
End User:
Customer type determines volume scale, with utilities procuring containerized megawatt-scale systems and residential buyers driving attachment rate volatility.
- Utilities:Centralized procurement of three-phase hybrid inverters for solar-plus-storage plants ranging 50-500 MWAC, with Texas ERCOT and California CAISO interconnection queues compressing delivery timelines.
- Industrial:Semiconductor fabrication and data center facilities in Arizona and Nevada procure island-capable microgrids with premium ride-through specifications detached from residential market cycles.
- Commercial:Distributed generation for retail, warehousing, and office facilities favors string inverter architectures with optional storage retrofit compatibility.
- Residential:Single-phase hybrid and string inverters face collapsing battery attachment rates in California following NEM 3.0 export compensation reforms.
Utility end users command procurement volume leadership; industrial microgrid operators hold the steepest expansion trajectory as reliability premiums detach from grid-tied economics.
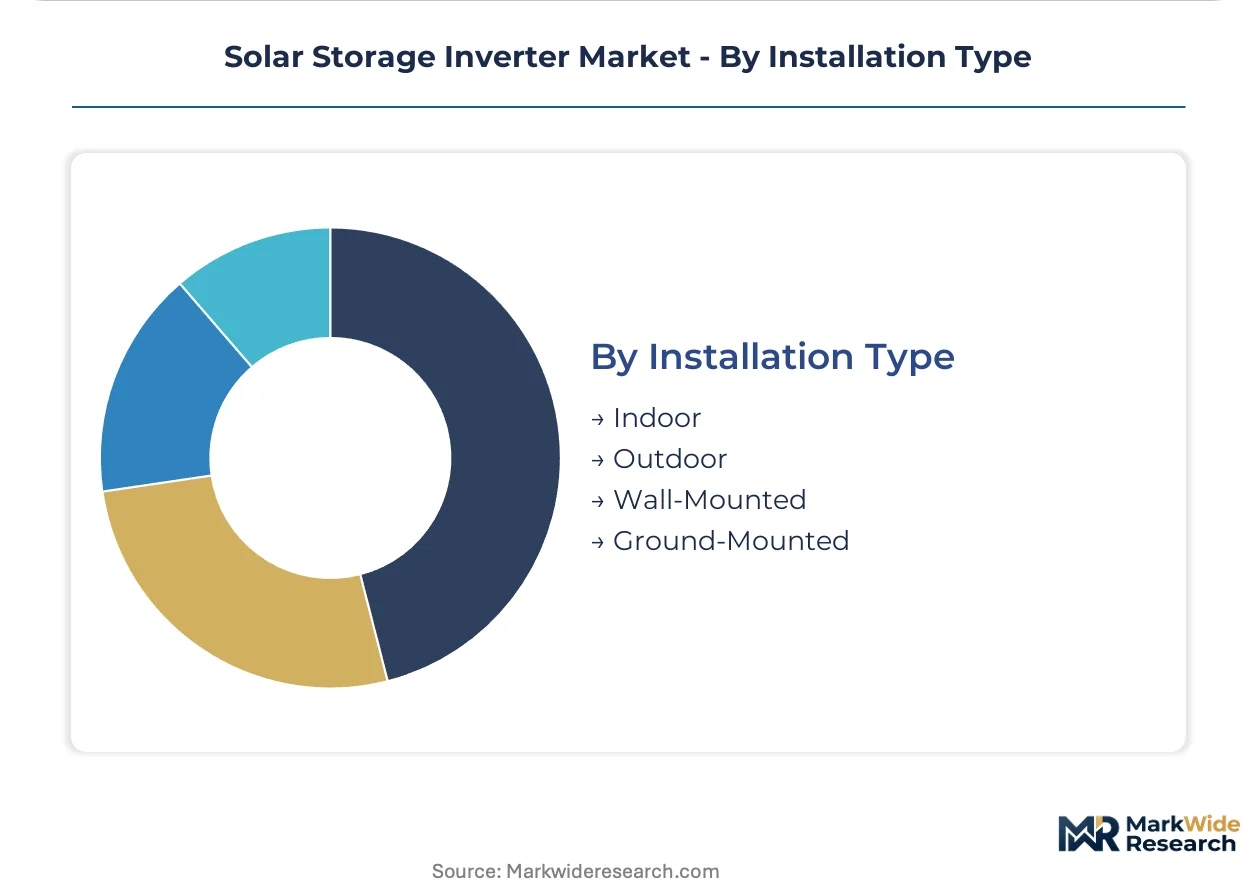
Installation Type:
Environmental exposure requirements fragment thermal management and enclosure IP rating specifications across deployment contexts.
- Outdoor:NEMA 3R or IP65-rated enclosures with passive or forced-air cooling dominate utility-scale ground-mount and commercial rooftop installations where ambient temperature swings stress electrolytic capacitor lifespans.
- Ground-Mounted:Pad-mounted or skid-mounted configurations for utility-scale deployments integrate transformer and switchgear functions at the medium-voltage interconnection point.
- Indoor:Climate-controlled environments in commercial basements or dedicated electrical rooms allow reduced enclosure ratings and extended component lifespans.
- Wall-Mounted:Residential garages and utility rooms favor compact single-phase units with simplified installation logistics and homeowner-accessible disconnects.
Outdoor installation retains volume leadership across utility and commercial deployment; ground-mounted configurations are gaining share fastest as utility-scale procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-California interconnection corridor anchors North American procurement velocity, while China's GB-certified manufacturing clusters feed Asia-Pacific utility-scale deployment. Distribution infrastructure across Germany's transmission network and Australia's NEM grid operators are mandating smart inverter interoperability standards that reshape import requirements.
United States
ERCOT interconnection queues in Texas and CAISO procurement in California are compressing delivery timelines for three-phase hybrid inverters. FERC Order 2222 enables distributed resource aggregation, redirecting capital toward storage-coupled systems. Arizona's data center corridor and Nevada's semiconductor fabrication zones are procuring island-capable microgrids with premium ride-through specifications.
China
Domestic manufacturers supply over half of global inverter capacity through Yangtze River Delta production clusters. The National Energy Administration's GB standards dictate efficiency benchmarks and grid connection protocols for export-bound hardware. Ningbo and Shenzhen industrial zones are scaling silicon carbide switching production for next-generation wide-bandgap topologies.
Germany
Transmission system operators mandate dynamic volt-var response and ride-through capabilities under VDE-AR-N 4105 grid codes. The F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing thermal design revisions for liquid-cooled inverter imports. Bavaria's industrial microgrid operators and North Rhine-Westphalia's commercial rooftop segment are driving smart inverter attachment rates.
Australia
The National Electricity Market's distributed resource integration rules require inverter-level telemetry and dispatch-responsive firmware. AEMO's frequency control ancillary services market is creating recurring revenue streams for aggregators orchestrating residential battery fleets. Queensland's agricultural irrigation zones and Victoria's commercial solar-plus-storage deployments represent underpenetrated high-utilization applications.
India
Central Electricity Authority technical standards for distributed solar-plus-storage are stabilizing procurement frameworks for tender participation. The PLI scheme incentivizes domestic cell-to-inverter integration, attracting suppliers willing to localize final assembly. Gujarat's industrial parks and Karnataka's commercial rooftop markets are emerging as service network anchor points for multinational OEMs.
Solar Storage Inverter Market Competitive Landscape
Listed leaders compete with private specialists across capital access and engineering agility dimensions, producing a tiered structure where scale advantages concentrate among vertically integrated Asian manufacturers. The vendor base fragments across three strategic archetypes: power electronics conglomerates with captive semiconductor sourcing, pure-play inverter specialists with software-layer differentiation, and energy storage integrators with bundled hardware-software offerings. Competitive moves center on silicon carbide supply chain partnerships and pre-certification engineering for compressed interconnection timelines.
Within the power electronics conglomerate tier, Huawei Technologies and Sungrow Power Supply exemplify scale-driven positioning through upstream control over switching component supply. SolarEdge Technologies occupies a specialist position leveraging power optimizer architecture for retrofit-heavy European markets. Among pure-play inverter fabricators, SMA Solar Technology and Ginlong Technologies represent contrasting geographic anchoring strategies, with the former serving German-engineered premium segments and the latter targeting cost-optimized volume deployment across Asia-Pacific utility tenders.
| Leading Market Players |
|---|
| SolarEdge Technologies |
| Ginlong Technologies |
| Sungrow Power Supply |
| Tesla |
| SMA Solar Technology |
| FIMER |
| Enphase Energy |
| Power Electronics |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
Containerized megawatt-scale deployments in Texas and California compress manufacturing scale curves, concentrating price-setting power among vertically integrated Asian producers while forcing smaller fabricators toward niche retrofit segments or full exit.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-enabled smart inverters with grid-forming firmware from silicon IGBT string variants and basic grid-tied units without storage integration. Price differentiation hinges on certification grade—UL 1741 SA versus basic IEEE 1547 compliance—and captive cell-to-inverter integration that eliminates battery management system licensing fees. Pricing pressure stems from compressed interconnection timelines in ERCOT and CAISO queues that force pre-certification engineering costs onto suppliers. Residential buyers in California exhibit highest price sensitivity following NEM 3.0 export compensation collapse, while data center operators in Arizona prioritize ride-through specifications over unit economics.
Supply Chain Analysis
China and Taiwan anchor power semiconductor fabrication, with Yangtze River Delta clusters producing over half of global inverter capacity and Hsinchu Science Park supplying silicon carbide wafers for next-generation switching topologies. Raw material dependencies center on high-purity silicon, rare-earth magnetics for inductor cores, and electrolytic capacitors for DC-link stabilization. Single-source vulnerability concentrates in IGBT module supply from East Asian foundries, exposing procurement timelines to export control allocation cycles. Distribution runs through EPC contractors and utility procurement desks for utility-scale volumes, with commercial integrators and residential installers handling downstream fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as virtual power plant aggregation unbundles hardware procurement from software-layer revenue optimization, rewarding inverter OEMs with embedded telemetry and dispatch-responsive firmware.
For Market Incumbents: Secure silicon carbide supply agreements through long-term offtake arrangements with Taiwanese wafer producers, insulating margins from foundry allocation volatility. Defend utility-scale market share by pre-certifying hardware stacks for compressed ERCOT and CAISO interconnection timelines before queue deadlines eliminate late entrants. Prioritize firmware development resources for IEEE 1547-2018 interoperability across multiple regional transmission operator specifications to prevent fragmentation drag on time-to-revenue. For New Entrants and Emerging Players: Virtual power plant software orchestration represents the most penetrable service-layer gap, as California's NEM 3.0 reforms accelerate homeowner prioritization of third-party aggregation compatibility over manufacturer-branded energy management applications. Target agricultural irrigation microgrids in California's Central Valley and Australia's Murray-Darling Basin, where diesel displacement economics and predictable load profiles reduce customer acquisition costs. Pursue white-label firmware licensing to established EPC contractors lacking in-house power electronics engineering expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inverter OEMs with embedded telemetry and virtual power plant platform compatibility, as hardware-software bundling creates subscription-like cash flow profiles detached from cyclical solar installation volumes. Acquisition targets should demonstrate captive semiconductor sourcing or backward integration into power module fabrication, with valuation premia accruing to GB-certified manufacturers serving China's domestic utility-scale tender pipeline. Watch for inflection in India's PLI scheme localization requirements, which will separate suppliers with established final assembly and service networks from import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Long-term offtake with Taiwanese wafer producers insulates margins from foundry allocation cycles. |
| Pre-Certification Engineering Investment | Early UL 1741 SA validation compresses time-to-revenue in ERCOT and CAISO interconnection queues. |
| Virtual Power Plant Platform Integration | Firmware embedding for AEMO frequency control services captures recurring revenue from residential battery fleets. |
| India Final Assembly Localization | CEA grid code alignment and PLI scheme compliance open tender participation in Gujarat industrial parks. |
| Agricultural Microgrid Service Network | Central Valley and Murray-Darling Basin deployment expertise builds defensible position in diesel displacement applications. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary interview cycles, with secondary validation drawing from EIA generation data, IEA renewable technology reports, FERC interconnection filings, and project development databases. Bottom-up unit economics modeling triangulated against top-down capacity deployment forecasts across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with analytical framework segmentation by product type, technology tier, end-user scale, installation environment, and regional regulatory cluster. CAGRs derived from deployment trajectory analysis incorporating interconnection queue velocity, policy incentive duration, and technology substitution curves.
Underlying assumptions cover ITC extension continuity, silicon carbide cost-down trajectories, and IEEE 1547-2018 interoperability harmonization, with deviation risk concentrated in F-Gas Regulation enforcement timing and IGBT supply chain disruption scenarios. Recalibration cycles align with material shifts in interconnection queue processing rates and storage participation rulemakings in wholesale markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
Supercapacitor Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Energy Storage Software Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Battery Storage Inverter Market