
 Hybrid Solar Wind Energy Storage Market | 2026-2036
Hybrid Solar Wind Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Solar Wind Energy Storage Market Analysis
Multi-sourcing of battery cells and power electronics is hardening as the dominant procurement pattern among hybrid system integrators. General Electric leverages its turbine-to-inverter manufacturing footprint to sustain cost advantages across utility-scale deployments. Siemens competes through its grid-forming inverter technology, while Sungrow anchors its position with vertically stacked DC-coupled storage architectures for solar-wind hybrids.
Hybrid solar wind energy storage combines photovoltaic arrays and wind turbines with electrochemical or mechanical storage to dispatch firm renewable power against intermittency. Systems typically integrate lithium-ion battery racks with hybrid inverters managing bidirectional DC-AC conversion at 1,500 V DC bus voltages for utility-scale efficiency. Grid-tied configurations dominate current deployments, though off-grid systems serving remote industrial sites represent the fastest-expanding application segment. Lithium-ion technology leads installed capacity, while flow batteries capture emerging interest for multi-day duration requirements in wind-heavy resource zones.
The EU Green Deal and F-Gas Regulation impose embodied-carbon disclosure requirements on storage equipment imported into Europe, reshaping supplier qualification criteria. India's CEA mandates frequency-response standards for hybrid renewable plants above 50 MW, directly influencing inverter and battery control-system specifications. Australia's CER and AEMO jointly regulate grid-connection protocols for co-located assets, creating compliance complexity that favors vendors with established local certification track records. Stakeholders must monitor evolving duration requirements in procurement tenders and assess which storage chemistries align with emerging multi-hour dispatch obligations.
Market Dynamics
Utility-scale microgrid developers in island nations are expanding procurement of co-located solar-wind-battery assets, compressing project timelines and forcing inverter manufacturers to certify products for multi-source hybrid control architectures.
Growth Catalysts
- EU F-Gas Regulation:Embodied-carbon disclosure requirements on storage equipment imported into Europe are reshaping supplier qualification criteria toward low-carbon battery chemistries.
- Remote mining operations:Australia's grid instability and off-grid industrial demand accelerate adoption of DC-coupled solar-wind-battery systems for 24/7 power supply.
- Frequency-response mandates:India's CEA technical standards for hybrid plants above 50 MW are pulling advanced inverter and battery control-system specifications into mainstream procurement.
Market Restraints
- Lithium price volatility:Battery cell input costs swing with lithium carbonate spot markets, squeezing project IRRs for long-duration hybrid storage tenders.
- Power electronics concentration:IGBT and SiC module supply concentrates among East Asian foundries, creating single-source vulnerability for 1,500 V hybrid inverter production.
- Interconnection queues:Grid connection approval timelines in Australia stretch 18-36 months under AEMO and CER joint protocols, freezing capital deployment.
Strategic Opportunities
- Flow battery convergence:Vanadium redox technology paired with wind-heavy resource profiles captures emerging interest for multi-day duration obligations in remote grids.
- Distribution network deferral:Australia's NEM regions face transmission constraints that favor distributed hybrid assets as non-wires alternatives to pole-and-wire upgrades.
- Green hydrogen coupling:Electrolyzer integration with curtailed renewable output creates new offtake pathways for hybrid developers in islanded power systems.
Industry Challenges
- Grid-forming control expertise:Scarce power systems engineers capable of tuning virtual synchronous machine parameters for multi-inverter hybrid plants delay commissioning.
- Multi-certification burden:Vendors must navigate parallel IEC 62485, UL 9540, and AS/NZS 5139 testing tracks to serve Australia, Europe, and North American demand simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Solar Wind Energy Storage Market |
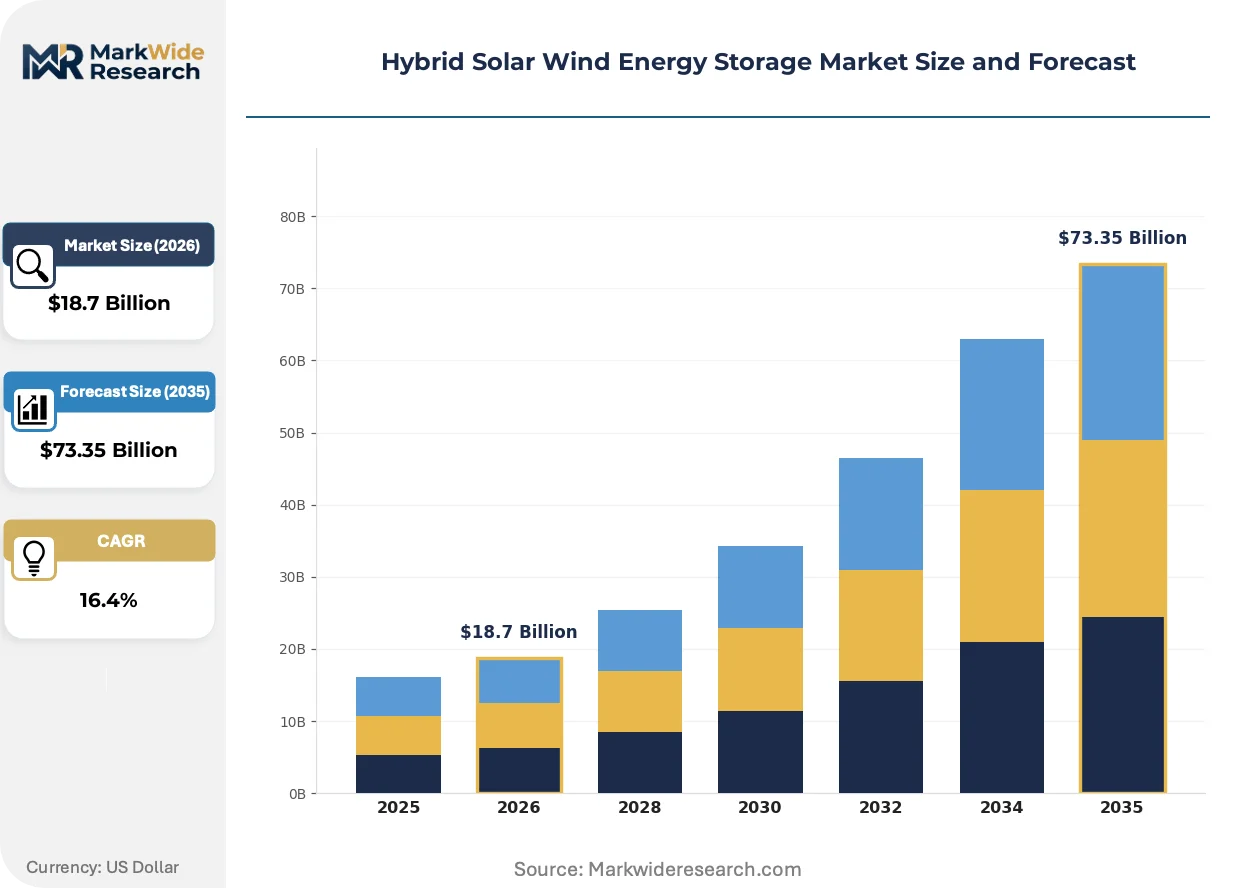
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Grid-Tied, Off-Grid, Battery Storage, Hybrid Inverter Energy Source: Solar Power, Wind Power, Biogas, Hydro Power Storage Technology: Lithium-Ion, Flow Batteries, Pumped Hydro, Compressed Air Application: Residential, Commercial, Industrial, Utility |
| Companies Covered | Delta Electronics, Sungrow, General Electric, EVLO Energy Storage, Hero Future Energies, Siemens, Hitachi, SolarEast BESS, NextEra Energy Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Solar Wind Energy Storage Market Emerging Trajectories
Hybrid system architecture is absorbing innovations from adjacent power electronics sectors, compressing the gap between solar inverter and wind converter control philosophies. Three developments are restructuring competitive positioning.
Silicon carbide (SiC) power modules are absorbing switching losses in 1,500 V DC bus hybrid inverters, enabling higher power density per megawatt. Remote mining operators in Western Australia are specifying SiC-based systems for containerized deployments where cooling infrastructure is constrained. This semiconductor transition is absorbing cost premiums from earlier silicon IGBT generations while extending inverter lifespans in high-temperature environments.
Australia's CER and AEMO jointly regulate grid-connection protocols for co-located assets, creating compliance complexity that favors vendors with established local certification track records. The regulatory burden is compressing vendor selection pools to those with pre-qualified inverter-battery control platforms. Off-grid hybrid developers serving Pilbara mining sites are responding by locking multi-year service contracts with certified integrators.
Buyers are unbundling engineering-procurement-construction contracts into separate equipment supply and integration service agreements. Mining operators and utility-scale developers are displacing turnkey contractors with direct battery cell and inverter procurement plus third-party integration. This disintermediation is most visible in Australia's remote industrial microgrid segment, where end-users seek supply chain transparency and avoid margin stacking.
Hybrid Solar Wind Energy Storage Market Segmentation
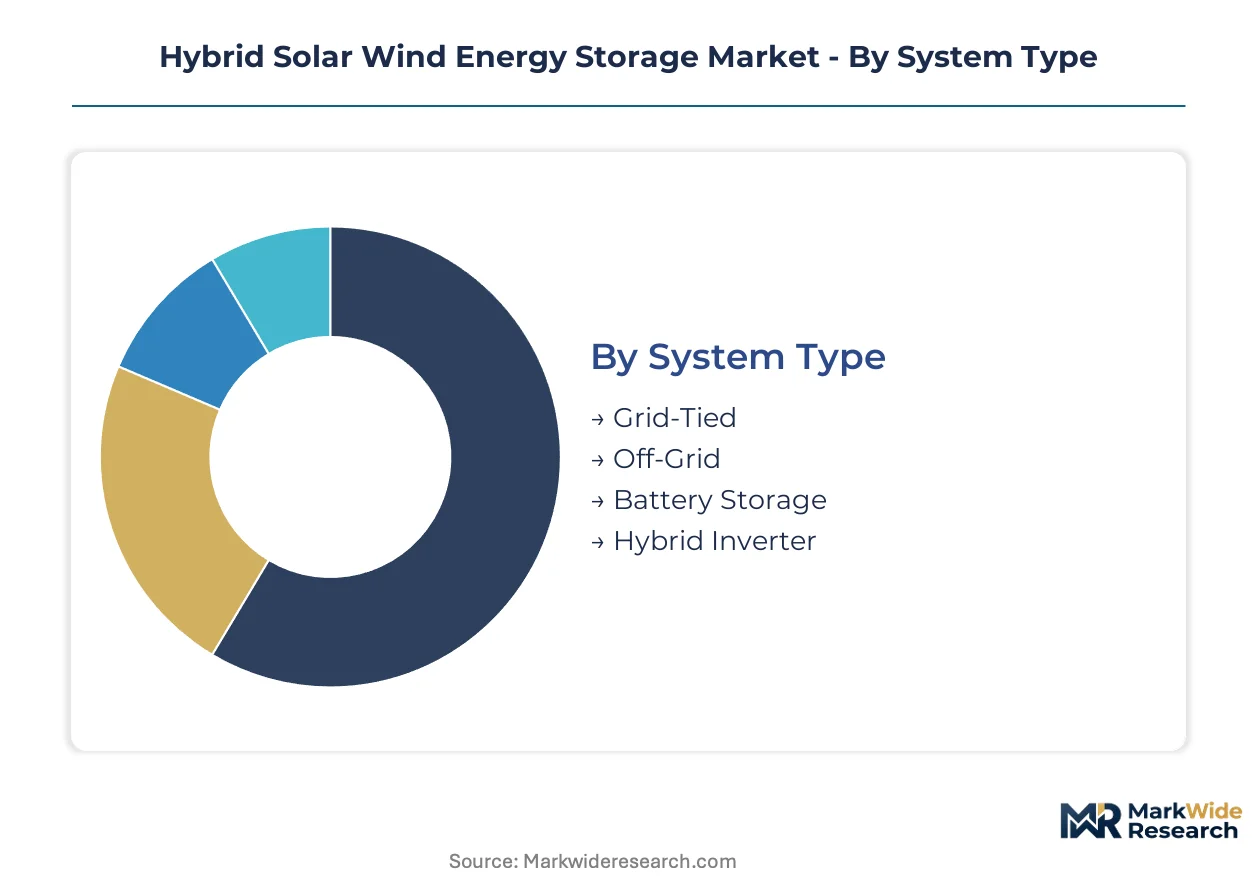
Hybrid solar wind energy storage systems fragment across four structural dimensions that determine integration complexity and procurement economics. System type and storage technology choices lock in capital intensity, while energy source mix and application scale dictate control architecture and regulatory exposure.
System Type:
Grid-tied configurations dominate utility procurement, while off-grid systems embed deeper control autonomy for remote industrial sites.
- Grid-Tied:Synchronous connection to distribution networks at 1,500 V DC bus voltage with bidirectional power flow managed by hybrid inverters. Australia's NEM regions concentrate demand where AEMO interconnection protocols mandate grid-forming inverter capabilities for frequency stability.
- Off-Grid:Autonomous microgrids serving mining camps and island communities with diesel displacement as primary economic driver. Western Australia's Pilbara region anchors procurement volume for 24/7 industrial power supply.
- Battery Storage:Rack-mounted electrochemical systems providing dispatchable capacity and ancillary services.
- Hybrid Inverter:Power electronics managing multi-source DC-AC conversion with integrated maximum power point tracking.
Grid-Tied leads volumes today; Off-Grid is gaining share fastest.
Energy Source:
Cost tier separates mature photovoltaic and wind technologies from emerging biogas and small-hydro hybrids.
- Solar Power:Photovoltaic arrays with silicon wafer or thin-film modules delivering predictable daytime generation. India's CEA frequency-response mandates for plants above 50 MW pull advanced inverter specifications into solar-wind hybrid tenders.
- Wind Power:Horizontal-axis turbines with variable-speed generators and full-scale converters. Coastal and high-altitude zones in Australia and India concentrate procurement where wind resource profiles complement solar diurnal patterns.
- Biogas:Anaerobic digestion systems providing dispatchable renewable baseload.
- Hydro Power:Run-of-river or small-reservoir installations with pumped storage coupling.
Solar Power leads volumes today; Wind Power is climbing the fastest.
Storage Technology:
Duration requirements and cycle life differentiate chemistries for intraday versus multi-day dispatch obligations.
- Lithium-Ion:NMC and LFP cell chemistries packaged in containerized racks with battery management systems. Australia's remote mining sector specifies lithium-ion for 4-6 hour duration requirements where energy density and modularity outweigh capital cost sensitivity.
- Flow Batteries:Vanadium redox systems with separated power and energy scaling for 8-100 hour duration. Wind-heavy resource profiles in islanded grids drive emerging interest where multi-day storage offsets diesel backup.
- Pumped Hydro:Gravitational potential storage with upper and lower reservoir configurations.
- Compressed Air:Subsurface cavern or aboveground vessel storage with thermal management.
Lithium-Ion leads volumes today; Flow Batteries is expanding most quickly.
Application:
Customer type determines procurement scale, contract structure, and service integration depth.
- Industrial:Mining operations and manufacturing facilities with 24/7 baseload requirements and diesel displacement economics. Western Australia's iron ore and lithium extraction corridors anchor off-grid hybrid procurement with direct equipment purchasing displacing turnkey EPC contracts.
- Utility:Transmission-connected assets bidding into wholesale markets and providing network services. India's state distribution companies and Australia's gentailers dominate tender volume with 50 MW-plus plant specifications.
- Residential:Behind-the-meter systems with rooftop solar and small wind coupling.
- Commercial:C&I facilities with peak shaving and backup power requirements.
Utility leads volumes today; Industrial is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Pilbara mining corridor anchors procurement volume for off-grid hybrid systems, with Western Australia's grid instability and remote industrial demand compressing project timelines for DC-coupled solar-wind-battery assets.
Australia
Remote mining operations in Western Australia and Queensland's renewable energy zones drive demand for 24/7 industrial power supply. The CER and AEMO jointly regulate grid-connection protocols for co-located assets, creating compliance complexity that favors vendors with established local certification track records. Pilbara iron ore and lithium extraction corridors anchor off-grid hybrid procurement with direct equipment purchasing displacing turnkey EPC contracts.
India
State distribution companies and gentailers dominate tender volume for 50 MW-plus hybrid plants with frequency-response obligations. The CEA mandates technical standards for hybrid renewable plants above 50 MW, directly influencing inverter and battery control-system specifications. Coastal Tamil Nadu and Gujarat concentrate wind-solar complementary resource development where state utilities accelerate procurement.
Germany
Utility-scale microgrid developers expand procurement of co-located solar-wind-battery assets under tightening carbon-accounting frameworks. The EU Green Deal and F-Gas Regulation impose embodied-carbon disclosure requirements on storage equipment, reshaping supplier qualification criteria toward low-carbon battery chemistries. Northern German coastal zones and Bavarian industrial clusters anchor deployment of grid-forming hybrid inverters for frequency stability services.
United States
NextEra Energy Resources and utility-scale developers concentrate procurement in Texas ERCOT markets and California ISO territories facing intermittency challenges. FERC Order 2222 and state-level storage mandates pull advanced inverter specifications into mainstream procurement for hybrid renewable plants. ERCOT's frequency instability events and California's wildfire-driven PSPS protocols accelerate adoption of grid-forming hybrid architectures.
China
State-owned power generators and grid companies dominate procurement of utility-scale hybrid systems in Inner Mongolia and Xinjiang wind-solar resource bases. MIIT industrial policy and GB standards for energy storage systems shape domestic supplier qualification criteria and export competitiveness. The Yangtze River Delta and Pearl River Delta manufacturing clusters anchor production of 1,500 V hybrid inverters and lithium-ion battery racks for global deployment.
Hybrid Solar Wind Energy Storage Market Vendor Landscape
Global majors compete with regional champions across power electronics manufacturing and system integration capabilities, producing a tiered structure where turbine-to-inverter conglomerates, dedicated storage specialists, and emerging Asian integrators each occupy distinct competitive positions. Strategic archetypes include full-spectrum industrial conglomerates with captive component manufacturing, pure-play battery system integrators with software-defined control platforms, and regional EPC firms with local certification expertise. Dominant competitive moves center on backward integration into semiconductor supply chains and multi-certification investments to serve parallel IEC, UL, and AS/NZS testing tracks simultaneously.
Within the industrial conglomerate tier, General Electric and Siemens exemplify turbine-to-inverter manufacturing footprints that sustain cost advantages across utility-scale deployments. Sungrow anchors the specialist integrator position with vertically stacked DC-coupled storage architectures purpose-built for solar-wind hybrid applications. These three companies represent contrasting approaches to control-system architecture: hardware-integrated turbine-inverter platforms, grid-forming inverter technology leadership, and purpose-built hybrid DC-coupled designs respectively.
| Leading Market Players |
|---|
| Delta Electronics |
| Sungrow |
| General Electric |
| EVLO Energy Storage |
| Hero Future Energies |
| Siemens |
| Hitachi |
| SolarEast BESS |
| NextEra Energy Resources |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed power producers in China's Inner Mongolia and Xinjiang wind-solar bases anchor upstream manufacturing scale, compressing component costs while concentrating pricing power among state-owned turbine and inverter producers. This ownership structure feeds into procurement patterns where Australian mining operators and Indian utilities face asymmetric bargaining positions against integrated suppliers.
Pricing Analysis
Input-cost pass-through from lithium carbonate spot markets and silicon carbide module premiums shapes project economics across utility-scale tenders. Three-tier pricing structure across premium, standard, and economy levels separates grid-forming inverter platforms with AS/NZS 5139 certification from basic IEC 62485-compliant alternatives and uncertified economy imports. Pricing pressure stems from battery cell cost volatility squeezing IRRs for long-duration hybrid storage projects. Industrial mining buyers in Western Australia exhibit highest price sensitivity due to diesel displacement economics, while European utility procurement under EU Green Deal carbon-accounting rules shows lowest sensitivity.
Supply Chain Analysis
IGBT and silicon carbide power module supply rests on East Asian semiconductor foundries in China, South Korea, and Japan, creating concentrated dependency for 1,500 V hybrid inverter production. Lithium-ion cell supply draws from Chinese LFP and NMC manufacturing clusters, while vanadium electrolyte for flow batteries sources from South African and Chinese mining operations. Single-source vulnerability in SiC wafer fabrication poses structural risk given Australia's 18-36 month AEMO interconnection queues freezing capital deployment timelines. Distribution runs through direct equipment supply agreements displacing turnkey EPC contracts, particularly in Australia's Pilbara mining corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement shifts toward grid-forming inverter specifications and multi-certification compliance favor vendors with pre-qualified control platforms over price-competitive challengers.
For Market Incumbents: Hedge lithium price exposure through long-term offtake contracts with Chinese cell producers and captive supply of silicon carbide modules via backward integration into semiconductor packaging. GE and Siemens must defend against pure-play integrators like Sungrow by accelerating AS/NZS 5139 and UL 9540 certification investments to match Australian and North American procurement requirements.
For New Entrants and Emerging Players: India's CEA frequency-response mandates for hybrid plants above 50 MW opens a window for specialist inverter control firms with virtual synchronous machine expertise to penetrate state distribution company tenders. Target Western Australia's off-grid mining microgrid segment where direct equipment purchasing displaces turnkey contractors, and lead with containerized DC-coupled architectures purpose-built for 24/7 industrial power supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional EPC firms with established Australian CER and AEMO certification track records that lack captive component manufacturing. Over a five-to-ten year horizon, acquisition targets with pre-qualified inverter-battery control platforms and multi-year service contracts with Pilbara mining operators offer defensive cash flow visibility. Watch flow battery deployment announcements in islanded grids as the signal indicating multi-day duration storage is crossing from pilot to mainstream procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | AS/NZS 5139 pre-qualification unlocks Australian NEM procurement under AEMO protocols. |
| Backward Integration into SiC Modules | In-house semiconductor packaging reduces dependency on East Asian foundry concentration. |
| Flow Battery Technology Licensing | Vanadium redox partnerships address multi-day duration obligations in wind-heavy island grids. |
| Direct Equipment Supply Agreements | Unbundled procurement contracts displace turnkey EPC margin stacking in Australian mining. |
| Green Hydrogen Coupling Development | Electrolyzer integration with curtailed renewable output creates new offtake pathways. |
Methodological Framework
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators across Australia's CER, India's CEA, and Germany's network regulator environments grounded qualitative findings. Secondary validation drew from FERC Order 2222 implementation filings, IEA hybrid renewable deployment databases, AEMO interconnection queue reports, and customs trade data on inverter and battery cell imports. Bottom-up project pipeline analysis triangulated against top-down market sizing from regulatory mandate trajectories.
Bottom-up modeling aggregated individual project capacities across utility-scale and industrial microgrid segments, while top-down analysis tracked regulatory procurement mandates from EU Green Deal carbon-accounting rules, India's CEA technical standards, and Australia's NEM transmission constraints. Segmentation dimensions spanned system type, energy source mix, storage technology chemistry, and application scale across the projection horizon. CAGRs derived from capacity-weighted average of disclosed tender volumes and announced manufacturing expansions, with sensitivity testing around lithium price volatility and SiC module supply availability.
Revisions become necessary when lithium carbonate spot markets sustain extended volatility bands, when AEMO interconnection protocols shift duration requirements, or when EU F-Gas Regulation tightens embodied-carbon disclosure thresholds beyond current supplier qualification criteria. A small set of named triggers—flow battery cost curves, grid-forming inverter standardization, and sovereign manufacturing subsidies—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Energy Storage Software Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
ASEAN Energy Storage Devices Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Europe Battery Energy Storage System Market
Energy Storage
Battery Energy Storage Market
Energy Storage
South America Energy Storage Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Solar Storage System Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
North America NMC Battery Energy Storage System (BESS) Market