
 Australia Energy Storage Systems (ESS) Market | 2026-2036
Australia Energy Storage Systems (ESS) Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Energy Storage Systems (ESS) Market Outlook
Utility-scale buyers is rotating toward front-of-the-meter deployments as distributed commercial uptake moderates. Tesla Inc. dominates grid-scale battery supply through its Megapack manufacturing presence and software-integrated power electronics. Fluence anchors the utility segment with its proprietary operating system and project development footprint across Australian renewable energy zones. LG Energy Solution Ltd competes on cell chemistry diversity, supplying both lithium-ion racks and emerging solid-state prototypes to local integrators.
Energy Storage Systems encompass electrochemical and mechanical devices that capture electrical energy for timed discharge, with lithium-ion battery packs typically operating at 85-95% round-trip efficiency and 10-20 year design lifespans under controlled thermal management. These systems buffer intermittency from solar and wind generation while providing frequency regulation and peak-shaving services to Australian grid operators. Lithium-Ion technology leads installed capacity due to declining cell costs and mature recycling pathways, while Flow Batteries occupies a structural niche in long-duration applications where daily cycling exceeds eight hours. Utility Scale deployment concentrates the largest capital flows, though Residential segment growth accelerates as virtual power plant aggregations monetize behind-the-meter flexibility.
The Australian Energy Market Operator enforces connection standards that mandate grid-forming inverter capabilities for new storage above 5 MW, directly shaping procurement specifications. CEC accreditation and AS/NZS 3000 wiring rules govern installation compliance, while the Clean Energy Finance Corporation's concessional debt programs influence project finance structures. Stakeholders must monitor the evolution of capacity mechanism designs and state-based renewable storage targets that will determine revenue stacking opportunities for new assets.
Market Dynamics
Utility-scale grid operators in New South Wales and Victoria are accelerating procurement timelines as transmission congestion and renewable energy zone commitments force dispatchable capacity into the construction pipeline ahead of scheduled completion dates.
Growth Catalysts
- Renewable Energy Zone mandates:State governments in New South Wales and Victoria have legislated storage procurement targets tied to zone development, creating guaranteed offtake for utility-scale battery projects.
- Frequency Control Ancillary Services reform:The National Electricity Market's redesigned FCAS markets reward fast frequency response, favoring lithium-ion batteries over slower mechanical inertia providers.
- Virtual Power Plant aggregation:Retailers and network operators are enrolling residential battery systems into coordinated dispatch pools, monetizing behind-the-meter flexibility through wholesale market participation.
Market Restraints
- Lithium carbonate price volatility:Cell chemistry costs remain exposed to upstream mining concentration in South American salares and Australian hard-rock spodumene operations.
- Grid connection queue congestion:Australian Energy Market Operator technical studies and network augmentation timelines stretch project energization dates by 18-36 months beyond original schedules.
- Flow battery cost premiums:Vanadium redox systems carry capital expenditure multiples of 2.5-3.5x versus lithium-ion equivalents, limiting uptake despite superior cycle life for 8+ hour duration applications.
Strategic Opportunities
- Queensland renewable storage procurement:The state's Clean Energy Hub program and CopperString transmission project create new demand centers outside the saturated NSW-Victoria corridor.
- Grid-forming inverter certification:Early movers achieving AS/NZS 4777.2 compliance for synthetic inertia capabilities can capture premium connection agreements with AEMO.
- Second-life battery integration:Automotive cell retirement streams from South Korean and Japanese manufacturers offer feedstock for stationary storage repackaging at reduced cost positions.
Industry Challenges
- Power systems engineering talent scarcity:Specialized expertise in grid-forming inverter control algorithms and battery management system integration commands salary premiums that compress project development margins.
- Thermal runaway containment compliance:Clean Energy Council accreditation requirements for fire suppression and gas venting systems add non-standard engineering scope to every installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Energy Storage Systems (ESS) Market |
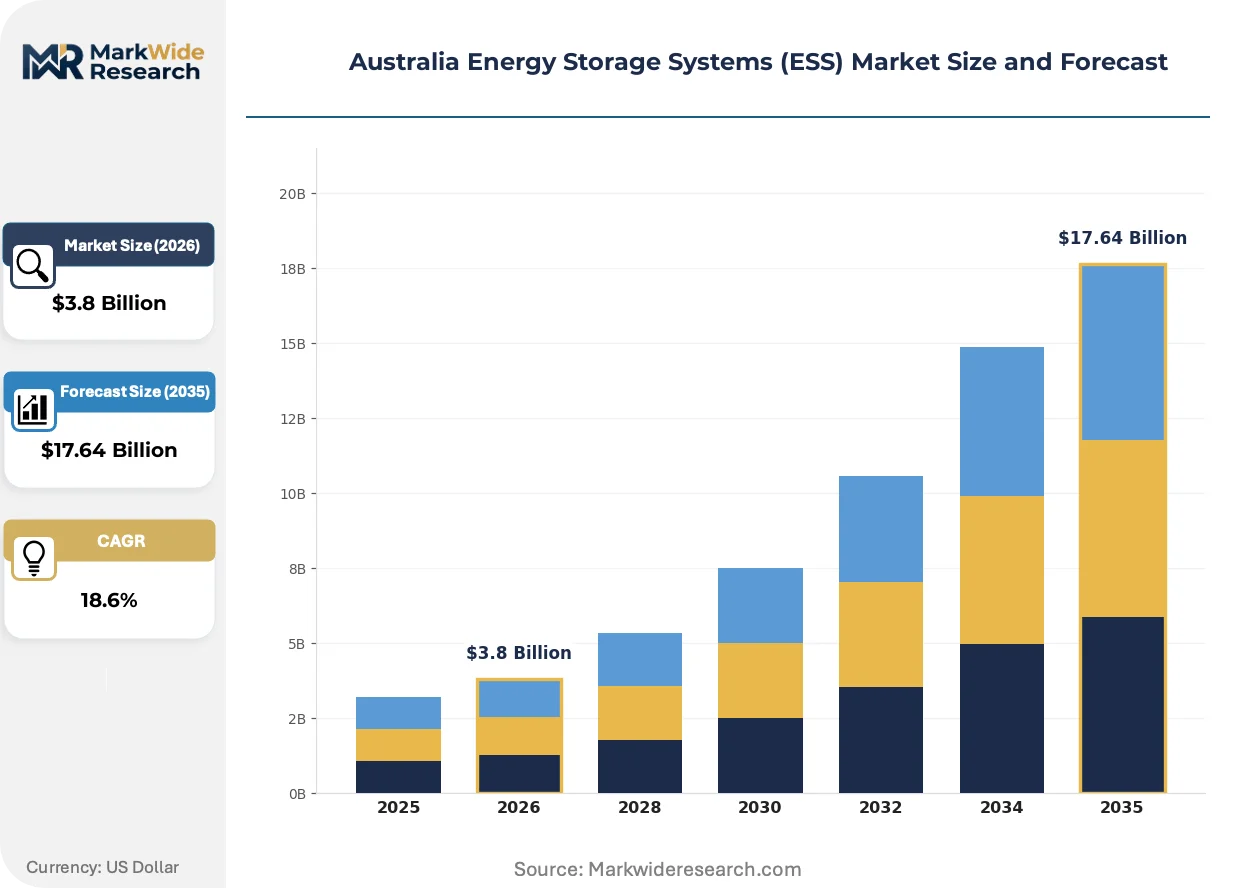
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-Ion, Lead Acid, Flow Batteries, Sodium-Sulfur Application: Residential, Commercial, Industrial, Utility Scale End User: Homeowners, Businesses, ESCOs, Utilities Service Type: Installation, Maintenance, Financing, Consulting |
| Companies Covered | Century Yuasa Batteries Pty Ltd, Pacific Green Technologies Group, Tesla Inc., RWE Renewables Australia, Enphase Energy Inc, LG Energy Solution Ltd, EVO Power Pty Ltd, Energy Vault, Fluence, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Energy Storage Systems (ESS) Market Strategic Shifts
Technology trajectories in the Australian ESS sector center on duration differentiation, software-defined grid services, and procurement model restructuring as asset owners seek revenue stack optimization beyond energy arbitrage.
Lithium iron phosphate chemistry is decomposing the historical cost-duration tradeoff that favored nickel-manganese-cobalt formulations for high-power applications. Utility developers in Victoria's Western Renewables Link zone are specifying LFP racks for 2-4 hour systems previously reserved for NMC alternatives. This shift is compressing supplier margins on legacy nickel-cobalt supply chains while expanding addressable market volume for iron-phosphate cell manufacturers.
The National Electricity Market reform agenda is mandating grid-forming inverter capabilities for all new storage above 5 MW, with AEMO enforcing synthetic inertia and black-start functionality through updated connection standards. This regulatory pressure is forcing hardware retrofits on partially completed projects and redirecting procurement specifications toward vertically integrated power electronics suppliers capable of firmware customization. Grid-scale developers in New South Wales are absorbing 8-12% capital cost premiums to secure compliant equipment.
Aggregators are unbundling residential battery hardware from energy retail contracts, allowing standalone equipment purchases with subsequent enrollment in virtual power plant programs. This channel restructuring displaces the bundled solar-plus-storage model that dominated 2020-2023 installations. South Australian households are exhibiting the fastest uptake of this unbundled procurement pattern, driven by state-specific VPP tariff structures and retailer competition for flexible capacity.
Australia Energy Storage Systems (ESS) Market Segmentation
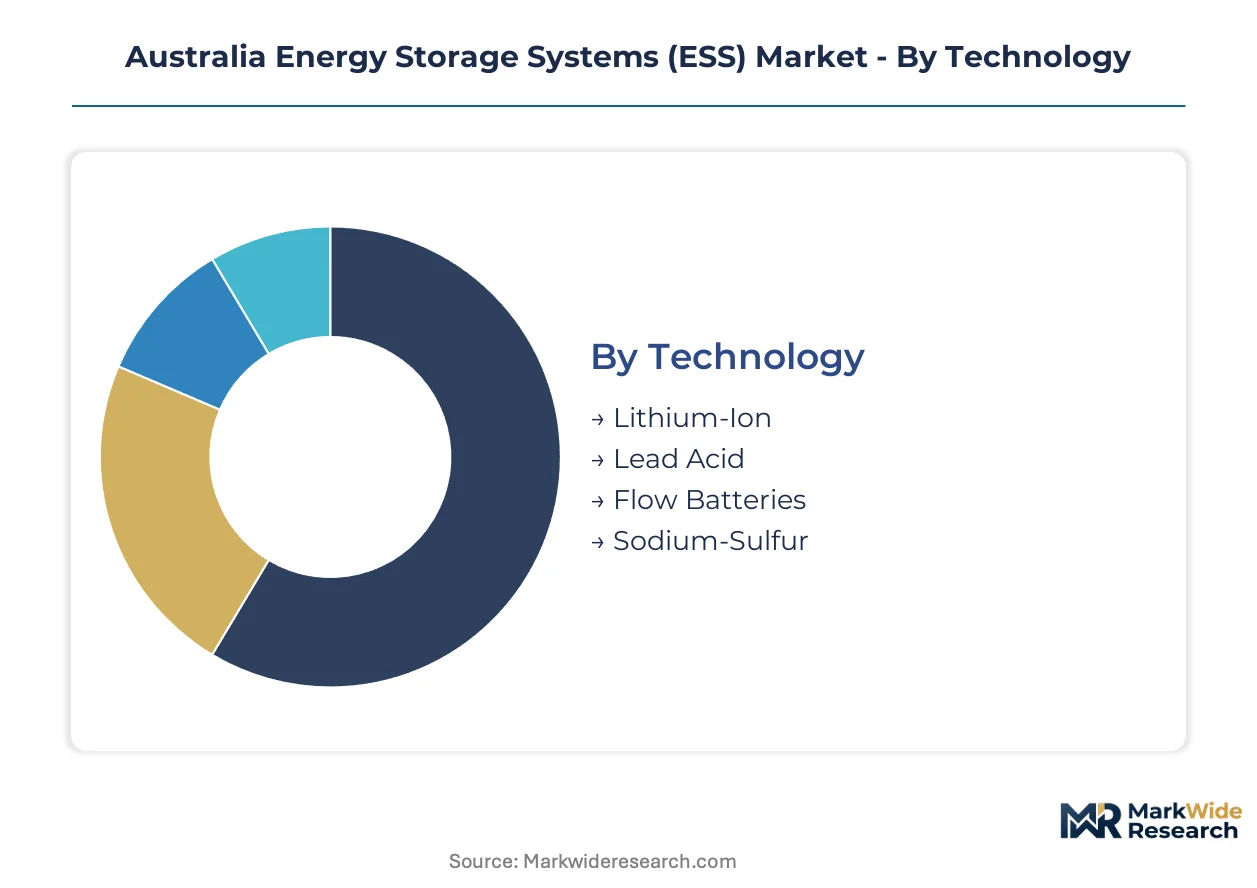
Technology choice dictates capital intensity and revenue stacking potential for Australian ESS developers. Application scale determines regulatory pathway and procurement complexity across the National Electricity Market.
Technology:
Margin pools concentrate in cell chemistry selection, where thermal management requirements and cycle life specifications drive engineering cost differentials.
- Lithium-Ion:Lithium iron phosphate and nickel-manganese-cobalt formulations dominate utility-scale procurement through 85-95% round-trip efficiency and mature recycling infrastructure. New South Wales renewable energy zone developers specify these racks for 2-4 hour duration requirements where frequency control ancillary services revenue justifies capital outlay.
- Flow Batteries:Vanadium redox systems occupy long-duration niches exceeding eight hours of daily cycling, commanding capital expenditure multiples of 2.5-3.5x versus lithium-ion equivalents despite superior cycle life economics for multi-day storage applications.
- Lead Acid:Mature flooded and valve-regulated designs serve backup power applications in remote industrial sites where procurement simplicity outweighs energy density constraints.
- Sodium-Sulfur:High-temperature ceramic electrolyte systems from Japanese manufacturers target grid-scale bulk energy shifting with 6-8 hour discharge profiles and minimal degradation over 15-year operational horizons.
Lithium-Ion holds installed capacity. Flow Batteries is rotating up the share rankings as duration requirements extend beyond four-hour standards.
Application:
Customer procurement authority varies dramatically across deployment scales, with utility-scale buyers consolidating vendor relationships while residential channels fragment through retailer competition.
- Utility Scale:Front-of-the-meter installations above 5 MW absorb the majority of capital deployment under AEMO grid-forming inverter mandates. Victorian and New South Wales network operators accelerate procurement timelines as transmission congestion forces dispatchable capacity into construction pipelines ahead of scheduled completion dates.
- Residential:Behind-the-meter battery systems enroll in virtual power plant aggregations that monetize flexibility through wholesale market participation. South Australian households exhibit fastest uptake of unbundled hardware procurement patterns driven by state-specific VPP tariff structures.
- Commercial:C&I installations target peak demand charge reduction and backup resilience for manufacturing and data center operations across Melbourne and Sydney metropolitan zones.
- Industrial:Heavy load facilities integrate megawatt-scale systems for process continuity and grid services revenue stacking at mining and smelting operations in Queensland's Clean Energy Hub corridor.
Utility Scale commands capital flows. Residential is expanding most quickly as virtual power plant aggregation models mature.
End User:
Financing sophistication separates customer tiers, with utilities accessing concessional debt through Clean Energy Finance Corporation programs while homeowners navigate retail channel complexity.
- Utilities:AEMO-regulated network operators and gentailers procure grid-scale assets under renewable energy zone mandates with guaranteed offtake mechanisms.
- ESCOs:Energy service companies structure power purchase agreements and performance contracts that transfer technology risk from commercial hosts to specialized financiers.
- Businesses:Commercial enterprises purchase or lease systems through solar retailers seeking to attach storage margins to panel installations.
- Homeowners:Individual consumers select hardware through virtual power plant aggregators or bundled solar-plus-storage offerings from electricity retailers.
Utilities anchor procurement volume. ESCOs are climbing the fastest as third-party ownership models penetrate commercial segments.
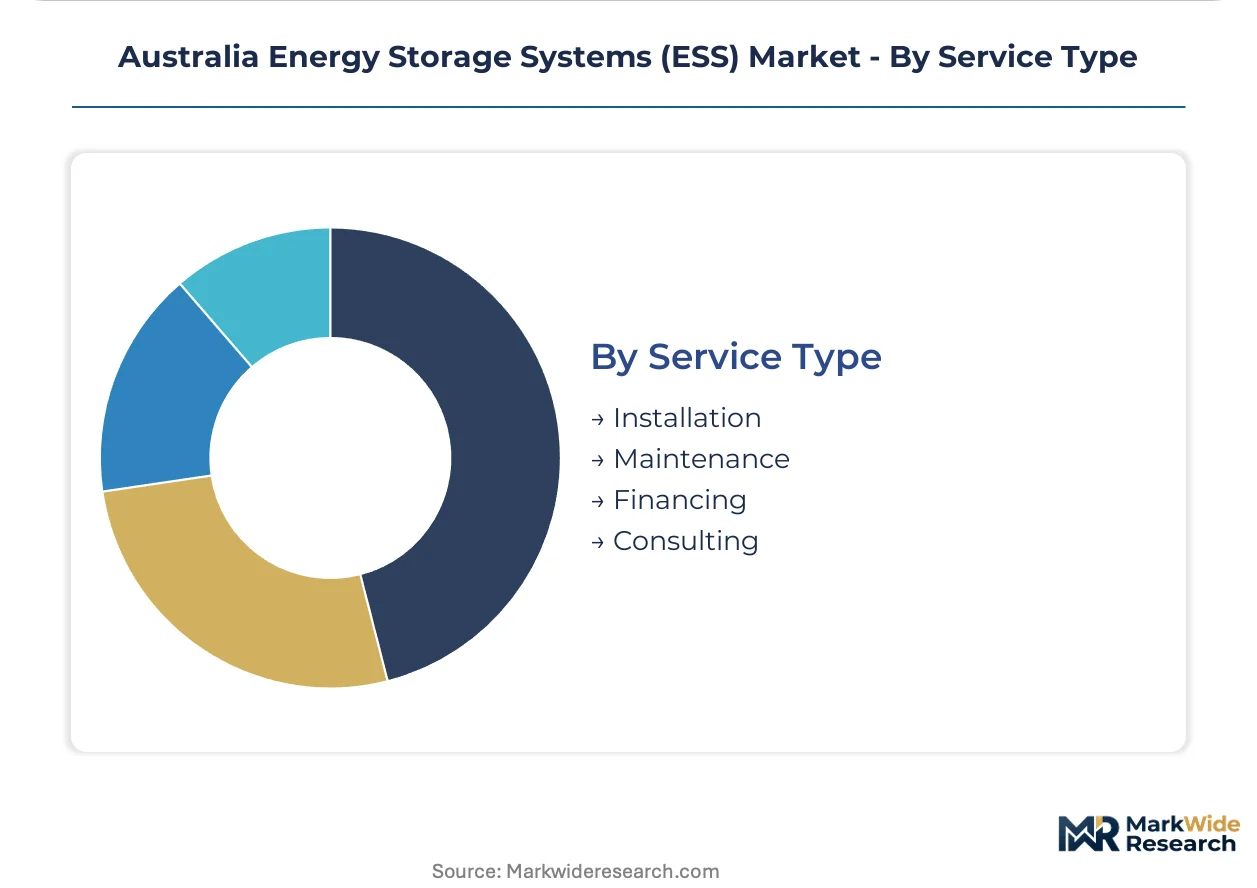
Service Type:
Value capture shifts downstream as hardware commoditization compresses equipment margins and recurring service revenue attracts specialized providers.
- Installation:CEC-accredited contractors execute electrical integration under AS/NZS 3000 wiring rules with thermal runaway containment compliance adding non-standard engineering scope.
- Maintenance:Battery management system monitoring and cell replacement services generate recurring revenue streams tied to performance guarantees.
- Financing:Green bond issuance and CEFC concessional debt programs structure project finance for utility-scale developers seeking to optimize weighted average cost of capital.
- Consulting:Grid connection feasibility studies and revenue stack optimization advisory command premium fees as project development timelines stretch 18-36 months beyond original schedules.
Installation captures upfront value. Financing is gaining share fastest as capital structures complexify for utility-scale pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale buyers concentrate procurement authority in state-level network operators and gentailers, with renewable energy zone mandates driving capital deployment toward dispatchable capacity in transmission-constrained corridors.
New South Wales
Renewable energy zone commitments and transmission congestion accelerate procurement timelines for front-of-the-meter battery installations. The state's Energy Corporation structures guaranteed offtake mechanisms under the Electricity Infrastructure Investment Act. Developers concentrate activity in the Central-West Orana zone where grid-forming inverter compliance commands capital cost premiums.
Victoria
Western Renewables Link zone specifications favor lithium iron phosphate chemistry for 2-4 hour duration requirements previously reserved for nickel-manganese-cobalt alternatives. AEMO connection standards mandate synthetic inertia capabilities for storage above 5 MW. Project pipelines cluster around Ballarat and Bendigo as network augmentation timelines stretch energization schedules.
Queensland
Clean Energy Hub program allocations and CopperString transmission development create demand centers outside the saturated NSW-Victoria corridor. The state government directs storage procurement toward mining and smelting load centers in the north. Industrial integrators target Gladstone and Townsville for megawatt-scale process continuity systems.
South Australia
Virtual power plant tariff structures drive fastest uptake of unbundled residential battery procurement patterns. State-specific aggregation models monetize behind-the-meter flexibility through wholesale market participation. Adelaide metropolitan households enroll coordinated dispatch pools at rates exceeding other mainland states.
Western Australia
Isolated grid architecture and mining sector load profiles sustain demand for long-duration storage beyond National Electricity Market boundaries. The state's Wholesale Electricity Market operates separate procurement frameworks from eastern jurisdictions. Remote industrial sites in the Pilbara integrate vanadium redox systems for multi-day storage applications.
Australia Energy Storage Systems (ESS) Market Competitive Environment
Player mix skews toward vertically integrated cell manufacturers and specialized power electronics suppliers, with tiered concentration separating utility-scale integrators from residential channel aggregators. Tier-one vendors combine manufacturing presence with software-integrated control systems, while tier-two specialists compete on installation velocity and financing structure innovation. Dominant competitive moves center on grid-forming inverter certification achievement and virtual power plant platform development.
Within the integrated manufacturing tier, Tesla Inc. and LG Energy Solution Ltd occupy positions spanning cell production through system integration, while Fluence exemplifies the pure-play utility-scale developer archetype with proprietary operating system deployment across Australian renewable energy zones. Century Yuasa Batteries Pty Ltd anchors the established local supplier segment with flooded and valve-regulated designs serving backup power applications in remote industrial sites.
| Leading Market Players |
|---|
| Century Yuasa Batteries Pty Ltd |
| Pacific Green Technologies Group |
| Tesla Inc. |
| RWE Renewables Australia |
| Enphase Energy Inc |
| LG Energy Solution Ltd |
| EVO Power Pty Ltd |
| Energy Vault |
| Fluence |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-thirty-six-month grid connection queues compress developer working capital cycles and amplify procurement negotiation leverage for vertically integrated cell manufacturers. This lead-time band concentrates pricing power with lithium iron phosphate suppliers capable of delivering certified racks within contracted windows.
Pricing Analysis
The lithium iron phosphate-to-nickel-manganese-cobalt pricing gap narrows as Victorian renewable energy zone developers specify LFP chemistry for 2-4 hour systems previously reserved for NMC alternatives. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation driven by AS/NZS 4777.2 certification tier and volume scale commitments. Cost compression in residential battery hardware intensifies as unbundled procurement displaces bundled solar-plus-storage models. Commercial and industrial segments exhibit highest price sensitivity due to peak demand charge reduction payback calculations, while utility-scale buyers prioritize grid-forming inverter compliance over unit cost.
Supply Chain Analysis
Hard-rock spodumene concentrate transit from Western Australian mines to Chinese chemical conversion facilities constitutes a critical chokepoint for lithium carbonate feedstock security. Cell manufacturing concentrates in China, South Korea, and Japan, with Australian project developers drawing from South Korean and Japanese automotive cell retirement streams for second-life battery integration. Single-source vulnerability in vanadium electrolyte supply constrains flow battery deployment scaling. Distribution runs through CEC-accredited EPC contractors executing installation under Clean Energy Council thermal runaway containment protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Financing and maintenance service layers expand faster than hardware deployment as virtual power plant aggregation models monetize recurring dispatch revenue streams.
For Market Incumbents: Compound software-integrated power electronics capabilities through firmware customization investments that secure AEMO grid-forming inverter certification ahead of connection standard enforcement. Defend margin position by capturing captive lithium carbonate supply through offtake agreements with Western Australian spodumene producers, neutralizing upstream price volatility exposure from South American salares concentration. For New Entrants and Emerging Players: AS/NZS 4777.2 fast-track certification for synthetic inertia capabilities unlocks premium connection agreements with New South Wales and Victorian network operators facing renewable energy zone completion deadlines. Target Queensland's Clean Energy Hub corridor where CopperString transmission development creates demand centers outside the saturated NSW-Victoria procurement pipeline. Pursue power purchase agreement structuring expertise as third-party ownership models penetrate commercial and industrial segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized battery management system engineering capabilities and existing CEC accreditation infrastructure. Five-to-ten-year viability hinges on revenue stack diversification beyond energy arbitrage into frequency control ancillary services and virtual power plant aggregation. Monitor AEMO capacity mechanism design evolution as the inflection signal determining long-term asset cash flow predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Certification | AEMO compliance mandates synthetic inertia capabilities for storage above 5 MW, commanding capital cost premiums. |
| Virtual Power Plant Platform Development | South Australian VPP tariff structures monetize behind-the-meter flexibility through wholesale market participation pools. |
| Second-Life Battery Integration | Automotive cell retirement streams from South Korean and Japanese manufacturers reduce stationary storage feedstock costs. |
| CEC Accreditation Investment | Clean Energy Council fire suppression and gas venting standards add non-standard engineering scope to every installation. |
| Queensland Corridor Expansion | Clean Energy Hub allocations and CopperString transmission create demand centers outside saturated NSW-Victoria markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of AEMO connection application databases, Clean Energy Council accreditation registries, and CEFC project finance disclosures. Utility planning officers, IPP project developers, EPC contractors, and grid operators provided structured input on procurement timelines and technical specification evolution. Bottom-up project pipeline aggregation triangulates against top-down National Electricity Market capacity forecasts.
Segmentation dimensions modeled span technology chemistry, application scale, end-user financing sophistication, and service type attachment across the projection horizon. CAGRs derive from capacity deployment trajectories within renewable energy zone mandates and frequency control ancillary services market redesign impacts. Vanadium redox system cost curves and lithium iron phosphate manufacturing scale-up rates inform duration-specific penetration assumptions.
Underlying assumptions cover state-based storage procurement target achievement, AEMO connection queue processing velocity, and lithium carbonate price band stability, with deviation risk concentrated in grid augmentation timeline slippage and flow battery capital expenditure premium persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Natural Gas Storage Market
Energy Storage
Cryogenic Vaporizer Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Solar Energy Storage Market
Energy Storage
Off-Grid Energy Storage Systems Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Asia-Pacific Energy Storage Systems Market