
 Lead Acid Battery for Energy Storage Market | 2026-2036
Lead Acid Battery for Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Acid Battery for Energy Storage Market Intelligence
The expansion of utility-scale projects and data centers for backup power is realigning the end-user landscape for lead acid batteries. EnerSys leverages its established industrial base to serve these high-reliability segments. In Asia, companies like Exide Industries and Amara Raja Energy & Mobility Limited compete on regional manufacturing scale and distribution networks. GS Yuasa Corporation differentiates through its focus on specialized applications requiring long service life.
A lead acid battery for energy storage is an electrochemical device that converts chemical energy into electrical energy using lead-peroxide and sponge lead electrodes immersed in a sulfuric acid electrolyte. Its primary commercial function is to provide reliable backup power and support grid stability in stationary applications. While backup power for telecom systems remains a mature application, renewable integration represents the fastest-growing segment. Within product types, Valve Regulated Lead Acid (VRLA) batteries, including Absorbent Glass Mat (AGM) variants, dominate new installations due to their maintenance-free characteristics.
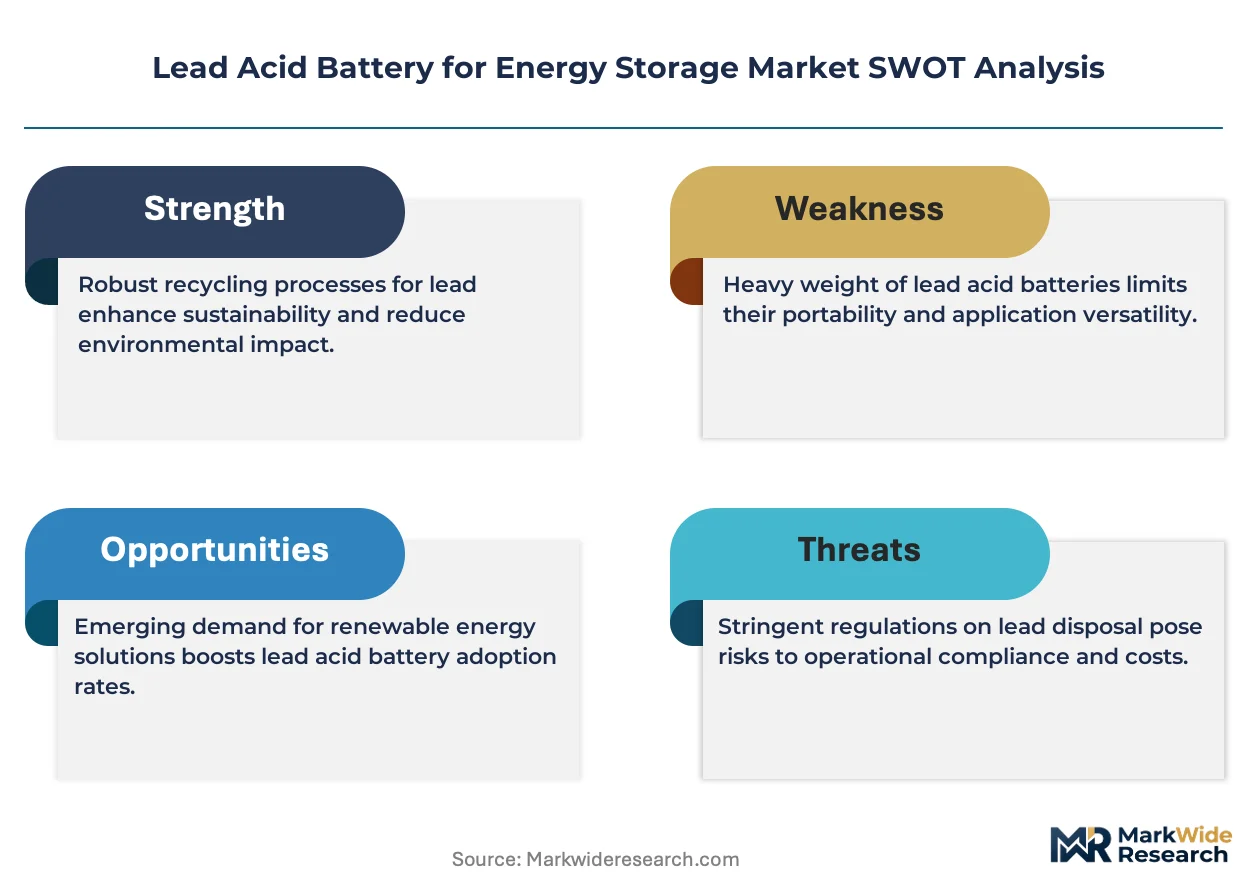
Global regulations, including the EU's REACH framework and rules from the US EPA, govern the handling of lead and sulfuric acid, mandating strict recycling and disposal protocols. In China, the Ministry of Ecology and Environment (MEE) enforces similar standards to mitigate environmental impact from battery production and end-of-life management. The key decision for manufacturers is how to invest in performance enhancements, such as improved cycle life and energy density, to maintain competitiveness against alternative storage chemistries.
Market Dynamics
The central tension shaping the market is the bifurcation of demand between mature, cost-sensitive backup power applications and high-growth, performance-driven grid stabilization roles. This dynamic forces manufacturers to balance investment in incremental product improvements against the need for radical innovation to defend share against alternative chemistries.
Growth Catalysts
- Renewable Energy Mandates:Policies such as the EU Green Deal and national renewable portfolio standards create sustained demand for energy storage to stabilize grids, with lead acid batteries offering a proven, cost-effective solution for short-duration applications.
- Infrastructure Expansion in India:Rapid grid expansion and the integration of intermittent renewable sources in India necessitate large-scale deployment of energy storage systems, where domestic manufacturing of lead acid batteries provides a secure supply chain.
- Data Center and Telecom Growth:The global build-out of data centers and 5G telecom infrastructure drives requirements for highly reliable uninterruptible power supply (UPS) systems, a core application for VRLA batteries.
Market Restraints
- Technical Performance Gaps:Lead acid batteries exhibit lower energy density, shorter cycle life, and slower charging rates compared to lithium-ion alternatives, constraining their use in applications requiring frequent, deep discharge cycles.
- Environmental and Safety Regulations:Strict regulations governing lead and sulfuric acid, such as the EU's REACH framework and rules from the US EPA, increase compliance costs for manufacturing, transport, and end-of-life recycling.
- Substitution from Lithium-Ion:Falling costs and performance improvements in lithium-ion batteries create significant substitution pressure, particularly in new grid-scale and commercial energy storage projects where total cost of ownership is a key factor.
Strategic Opportunities
- Hybrid Energy Storage Systems:Pairing lead acid batteries with other storage technologies like lithium-ion or supercapacitors in hybrid systems allows for optimized performance and cost, creating new use cases in microgrids and industrial facilities.
- Advanced Lead-Carbon Formulations:Development of lead-carbon electrodes enhances charge acceptance and cycle life, making advanced lead acid batteries more competitive for partial state-of-charge applications like grid frequency regulation and renewable smoothing.
- Cost-Effective Rural Electrification:In developing economies across Africa and Southeast Asia, the low upfront cost and established recycling infrastructure of lead acid batteries present an opportunity to support off-grid and mini-grid solar projects.
Industry Challenges
- Raw Material Price Volatility:The market is exposed to fluctuations in the price of lead, a primary input material, which can compress manufacturer margins and create uncertainty in project cost bidding.
- High Capital Costs for Recycling:Establishing and operating closed-loop recycling facilities that meet stringent environmental standards, such as those enforced by China's MEE, requires significant capital investment, creating barriers to entry.
- System Integration Complexity:Ensuring seamless interoperability between lead acid battery systems and diverse third-party energy management systems (EMS) remains a challenge due to a lack of universal communication protocols and standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Acid Battery for Energy Storage Market |
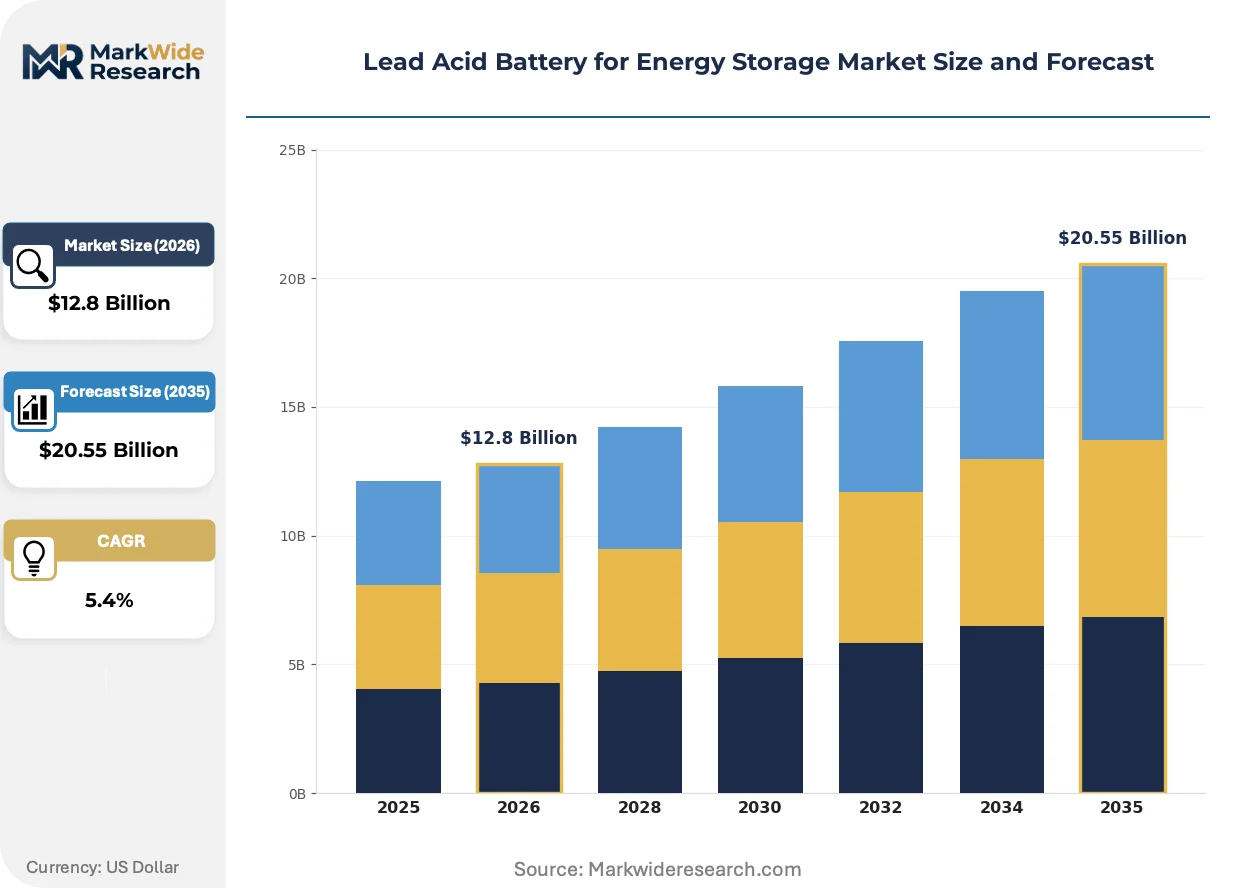
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate, Tubular, Valve Regulated, Gel, Absorbent Glass Mat Technology: Flooded, Sealed, Recombinant, Maintenance-Free, Enhanced Flooded Application: Renewable Integration, Backup Power, Grid Stabilization, UPS Systems, Telecom Systems End User: Data Centers, Telecommunication Operators, Utility Companies, Industrial Facilities, Commercial Buildings |
| Companies Covered | Exide Industries, EnerSys, Amara Raja Energy & Mobility Limited, Camel Group, C&D Technologies, CLARIOS, GS Yuasa Corporation, CHILWEE GROUP, East Penn Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Acid Battery for Energy Storage Market Strategic Shifts & Innovations
Performance expectations are reshaping the competitive landscape. Manufacturers are focused on enhancing cycle life and energy efficiency to defend the technology's position in stationary storage, balancing the inherent cost advantages of lead chemistry with the technical demands of modern grid and backup power applications.
Advanced lead-carbon composites are being added to negative plates to reduce sulfation and improve charge acceptance. Utility operators and microgrid developers are adopting these enhanced batteries for applications requiring frequent cycling, such as frequency regulation. This material science improvement is converging with sophisticated battery management systems to extend operational life and better compete against lithium-ion in high-duty-cycle roles.
China's "dual carbon" goals are accelerating the deployment of large-scale energy storage to support its massive renewable energy build-out. The policy creates strong domestic demand and provides incentives for technologies that can be produced at scale, including advanced VRLA batteries. The stationary grid storage segment in China is most affected, with local manufacturers optimizing designs to meet MIIT performance standards for grid-connected assets.
A preference for service-based models is altering procurement in the data center and telecom sectors. Instead of outright purchasing batteries, customers are increasingly seeking agreements that guarantee power availability and include lifecycle management, shifting risk to the supplier. This trend is most prominent in North America and Europe, where large enterprises favor operational expenditure (OpEx) models for critical backup infrastructure.
Lead Acid Battery for Energy Storage Market Segmentation
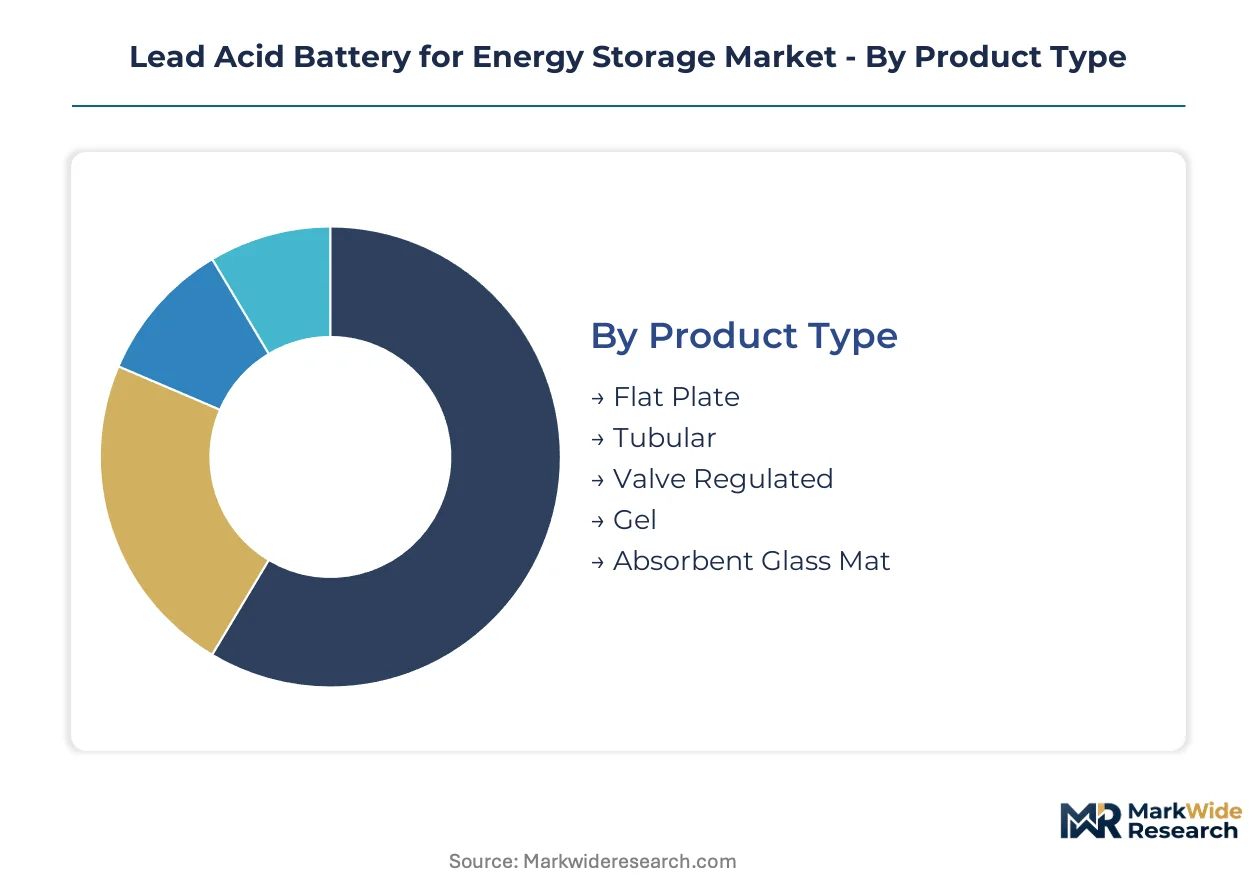
The segmentation analysis of the lead acid battery for energy storage market provides a granular understanding of product characteristics, technological distinctions, functional applications, and end-user adoption patterns. This detailed breakdown helps identify specific demand pockets and the competitive dynamics within each sub-market, informing strategic investment decisions.
Product Type:
The product type segmentation highlights the balance between standardized, widely adopted designs and specialized configurations tailored for specific performance needs.
- Flat Plate:These batteries utilize flat lead plates for electrodes, a traditional and cost-effective design primarily found in automotive and basic backup power systems. Demand for flat plate designs remains consistent in mature, cost-sensitive backup power applications.
- Tubular:Tubular plate batteries feature lead spines encased in a porous material, offering enhanced cycle life and deeper discharge capabilities compared to flat plate designs. Utility companies often deploy tubular batteries in remote grid infrastructure projects.
- Valve Regulated:VRLA batteries are sealed units that recombine gases internally, eliminating the need for water replenishment and reducing maintenance. New installations in data centers and telecom systems increasingly favor VRLA due to their maintenance-free characteristics.
- Gel:Gel batteries use a silica-based gel electrolyte, providing improved resistance to vibration, extreme temperatures, and deep discharge cycles. Off-grid solar projects in developing economies utilize gel batteries for their robust performance.
- Absorbent Glass Mat:AGM batteries employ a fiberglass mat to absorb the electrolyte, allowing for faster charging and superior performance in high-rate discharge applications. Data centers and uninterruptible power supply (UPS) systems commonly specify AGM variants for their reliability.
Most installed capacity flows through Valve Regulated batteries. Expansion is steepest in Absorbent Glass Mat variants.
Technology:
Technology differentiation often reflects varying cost structures and operational demands across the market.
- Flooded:These batteries feature liquid electrolyte and require regular maintenance, including water replenishment, making them suitable for applications with accessible service. Industrial facilities often use flooded batteries for their long service life and robustness.
- Sealed:Sealed lead acid batteries are designed to be maintenance-free, with an internal gas recombination system that prevents electrolyte loss. Telecommunication operators prefer sealed batteries for remote and distributed network infrastructure.
- Recombinant:Recombinant technology allows for the internal recombination of hydrogen and oxygen gases generated during charging, minimizing water loss and extending battery life. Grid stabilization projects in India increasingly adopt recombinant batteries.
- Maintenance-Free:These technologies, including VRLA and AGM, eliminate the need for routine electrolyte checks and water additions, reducing operational costs and making them ideal for remote or difficult-to-access installations. Data centers prioritize maintenance-free solutions for critical backup power.
- Enhanced Flooded:Enhanced flooded batteries incorporate design improvements to offer better cycle life and charge acceptance compared to standard flooded types, bridging the performance gap towards VRLA. Renewable energy projects often utilize enhanced flooded batteries for cost-effective storage.
Maintenance-Free technologies currently command the largest share of new deployments. Enhanced Flooded batteries are climbing the fastest.
Application:
The application segments delineate the diverse operational contexts where lead acid batteries provide essential energy storage solutions.
- Renewable Integration:This application involves storing excess energy generated from intermittent renewable sources like solar and wind to ensure a stable and continuous power supply to the grid. India's rapid renewable energy expansion drives significant demand for this segment.
- Backup Power:Lead acid batteries provide reliable, short-duration power during grid outages or fluctuations, ensuring continuity for critical systems. Data centers and telecom networks extensively deploy backup power systems.
- Grid Stabilization:These applications focus on maintaining grid frequency and voltage stability, absorbing power fluctuations, and providing ancillary services to utility operators. Utility companies globally use lead acid batteries for frequency regulation.
- UPS Systems:Uninterruptible Power Supply (UPS) systems use batteries to provide immediate, seamless power to sensitive electronic equipment during power interruptions. Commercial buildings and hospitals rely on UPS systems for critical operations.
- Telecom Systems:Batteries provide backup power for cell towers, data switches, and other telecommunication infrastructure, ensuring uninterrupted communication services. 5G network expansion drives sustained demand in this sector.
Backup Power applications currently represent the largest volume segment. Renewable Integration is experiencing the most rapid expansion.
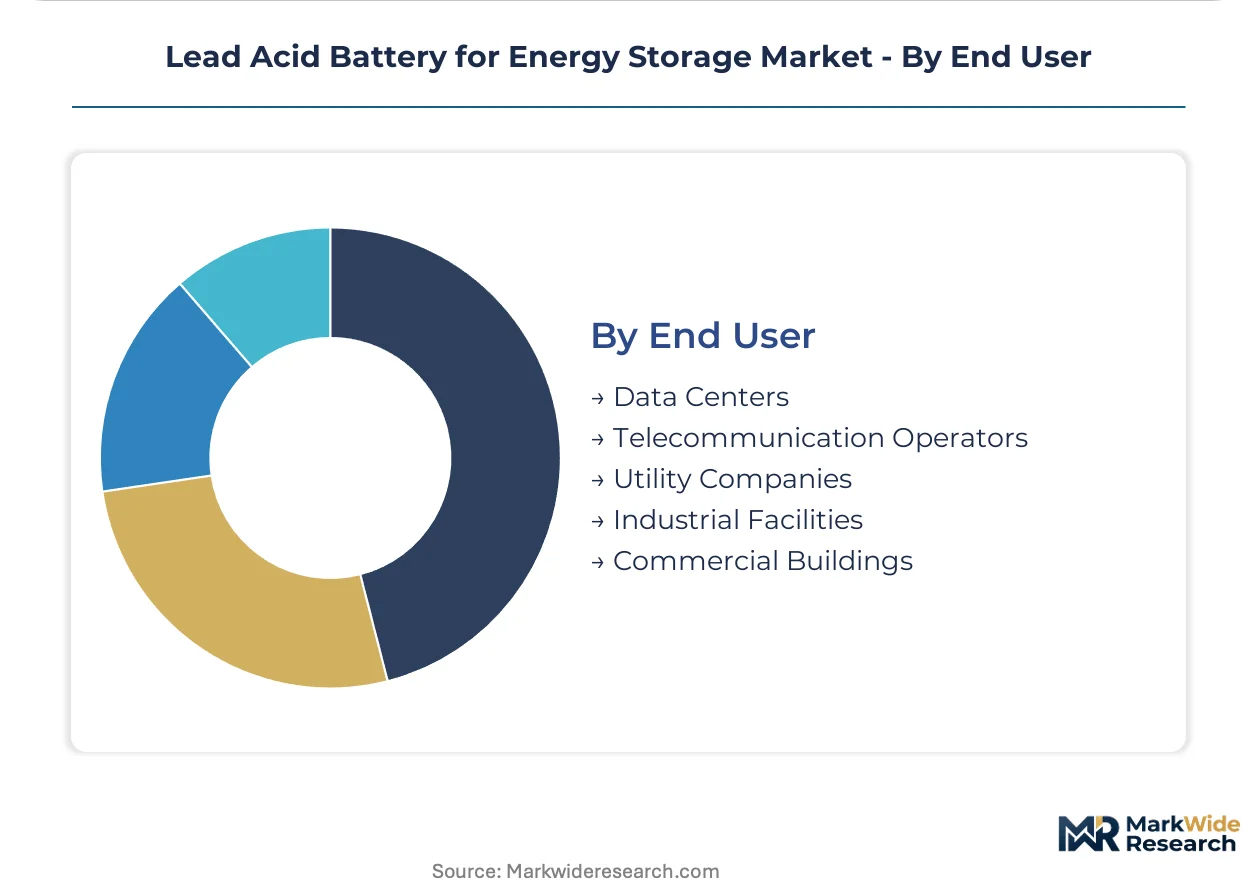
End User:
End user categories reflect distinct procurement patterns and operational scale requirements for energy storage systems.
- Data Centers:These facilities require highly reliable, large-scale backup power to protect critical servers and data. EnerSys serves data centers with high-reliability VRLA battery solutions.
- Telecommunication Operators:Telecom companies deploy batteries for backup power at base stations, central offices, and network nodes to ensure continuous service. Procurement is shifting towards service-based models in North America.
- Utility Companies:Utilities utilize lead acid batteries for grid stabilization, renewable energy integration, and peak shaving applications at substations and power plants. China's "dual carbon" goals drive utility demand for large-scale storage.
- Industrial Facilities:Manufacturing plants, warehouses, and other industrial sites use batteries for material handling equipment, emergency lighting, and critical process backup. These facilities often prioritize robust, long-lasting solutions.
- Commercial Buildings:Offices, retail establishments, and other commercial properties employ batteries for emergency power, UPS systems, and increasingly for demand charge management. Building managers seek cost-effective and reliable backup.
Utility Companies drive significant demand for large-scale deployments. Data Centers exhibit substantial growth in backup power requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory differences across major economies are influencing where lead acid battery production concentrates, creating a dynamic of cost-of-compliance arbitrage. Regions with less stringent environmental controls or robust domestic demand often attract manufacturing investment, impacting global supply chain configurations. This divergence in regulatory frameworks shapes investment decisions for new capacity and influences the competitive landscape for energy storage solutions.
United States
Data centers and grid stabilization projects drive significant demand for lead acid batteries across the United States. The US EPA regulations mandate strict protocols for lead recycling and disposal, influencing manufacturing practices. Major data center hubs in Silicon Valley and Northern Virginia continue to expand, requiring reliable backup power solutions.
China
China's ambitious renewable energy build-out and grid modernization initiatives create substantial demand for stationary energy storage. The Ministry of Ecology and Environment (MEE) enforces stringent environmental standards for battery production and end-of-life management. Industrial clusters in the Yangtze River Delta actively optimize VRLA battery designs to meet MIIT performance standards for grid-connected assets.
India
Rapid infrastructure expansion and the integration of intermittent renewable sources in India necessitate large-scale deployment of energy storage systems. India's Production Linked Incentive (PLI) scheme supports domestic manufacturing of advanced energy storage technologies. Manufacturing centers in Maharashtra and Gujarat are expanding their capacity to serve the nation's growing energy storage needs.
Germany
Germany's commitment to the EU Green Deal and its robust industrial base generate steady demand for reliable backup power and grid stabilization. The EU's REACH framework imposes strict regulations on chemicals like lead and sulfuric acid, increasing compliance costs for manufacturers. Industrial facilities in Bavaria and North Rhine-Westphalia deploy lead acid batteries for critical process backup and uninterruptible power supply systems.
Japan
Japan's focus on specialized applications requiring long service life and high reliability drives demand for advanced lead acid battery solutions. The Ministry of Economy, Trade and Industry (METI) supports the development of innovative energy storage technologies. Research and development clusters in the Kansai and Chubu regions focus on enhancing battery performance for grid frequency regulation and industrial applications.
Lead Acid Battery for Energy Storage Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The market exhibits global players with established industrial bases, alongside regional manufacturers competing on scale and distribution networks. Strategic archetypes include high-reliability industrial suppliers, regional volume leaders, and application-focused innovators. Competitive moves involve significant capacity expansion and the formation of strategic partnerships to address diverse application needs.
At the scale-driven end, EnerSys, with its established industrial base, exemplifies global reach in high-reliability segments like data centers. India-based Exide Industries and Amara Raja Energy & Mobility Limited occupy positions as regional powerhouses, leveraging extensive manufacturing scale and distribution networks. GS Yuasa Corporation represents a specialist archetype, differentiating through its focus on niche applications requiring long service life and specific performance characteristics.
| Leading Market Players |
|---|
| Exide Industries |
| EnerSys |
| Amara Raja Energy & Mobility Limited |
| Camel Group |
| C&D Technologies |
| CLARIOS |
| GS Yuasa Corporation |
| CHILWEE GROUP |
| East Penn Manufacturing Company |
| Others |
Cost & Logistics Intelligence
Data centers' demand for high-reliability VRLA batteries is forcing manufacturers to invest in performance enhancements, impacting pricing structures across the market. This dynamic requires supply chains to adapt to evolving technical specifications and procurement models.
Pricing Analysis
Distributor margins for VRLA batteries vary significantly based on volume and specific application requirements in the energy storage market. Pricing stratifies across premium, standard, and economy tiers, primarily differentiated by factors such as enhanced cycle life, energy density, and after-sales service bundles. Raw material price volatility, especially for lead, creates consistent pricing pressure for manufacturers. Utility companies and data centers, prioritizing reliability, exhibit lower price sensitivity compared to cost-conscious buyers in rural electrification projects.
Supply Chain Analysis
Direct-to-OEM channels handle large-scale utility and data center procurement for energy storage solutions. Supply concentrates heavily in China, India, and the United States, given their manufacturing capabilities and domestic demand. The market relies on stable sourcing of lead and sulfuric acid as primary inputs. Commodity price volatility for lead presents a significant structural risk across the entire supply chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lead acid battery market is a late-cycle quality story, driven by utility demand for enhanced cycle life and grid stability. This shift towards premium specifications redefines competitive advantage.
For Market Incumbents:Extend R&D investment into advanced lead-carbon formulations to counter lithium-ion substitution pressure. Secure long-term supply agreements for lead to mitigate raw material price volatility. Expand manufacturing capacity in India to serve rapid renewable integration demand. Invest in sophisticated Battery Management Systems to improve cycle life and energy efficiency.
For New Entrants and Emerging Players:Rural electrification projects in Southeast Asia represent an underserved buyer archetype for cost-effective storage solutions. Focus on off-grid solar and mini-grid applications with robust gel battery variants. Leverage established local recycling infrastructure for sustainable operations. Offer service-based models for simplified procurement and operational expenditure.
For Investors and Strategic Acquirers:Asymmetric upside sits with advanced lead-carbon technology providers addressing grid stabilization. The long-term viability of lead acid in stationary storage depends on performance enhancements and cost competitiveness against alternatives. Target regional specialists with strong R&D in materials science and established recycling capabilities. The signal to watch is the adoption rate of hybrid energy storage systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Lead-Carbon R&D | Improves cycle life and charge acceptance for grid applications. |
| Capacity Expansion in India | Capitalizes on rapid renewable integration and infrastructure growth across India. |
| Hybrid System Integration | Optimizes performance and cost by pairing lead acid with other storage technologies. |
| Service-Based Model Adoption | Addresses operational expenditure preferences in data center and telecom sectors, shifting risk to supplier. |
| Closed-Loop Recycling Investment | Ensures compliance with environmental regulations and secures raw material supply, reducing price volatility. |
Research Approach
Direct dialogue with utility planning officers, data center architects, and battery R&D directors informed primary insights. This primary research combined with secondary validation from regulatory filings and industry reports. Bottom-up and top-down triangulation ensured data consistency. Data sources included US EPA guidelines, EU REACH framework documents, and China's MEE standards.
The quantitative model produced detailed volume and value forecasts across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected technological adoption. Key forecast inputs included renewable energy deployment targets and data center expansion.
Inputs from public disclosures and government energy reports were available through the study window; gaps in real-time raw material pricing introduce uncertainty bands. Forecasts reflect documented assumptions regarding technological advancements and regulatory shifts. Decision-makers should treat outputs as directional.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Supercapacitor Market
Energy Storage
Solar Storage System Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market