
 Endoscopy Procedures Estimates Market | 2026-2036
Endoscopy Procedures Estimates Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopy Procedures Estimates Market Intelligence
Ambulatory surgical centers is bifurcating demand from traditional hospital settings as payors and patients favor same-day discharge economics. Olympus Corporation leverages its integrated imaging platform to dominate the upper GI endoscopy segment. Medtronic anchors its position through extensive service networks that lock in hospital system loyalty. Boston Scientific differentiates via therapeutic device innovation that extends procedure capabilities beyond pure diagnosis.
Endoscopy procedures estimates encompass the quantified volume and value of minimally invasive diagnostic and therapeutic interventions performed using flexible or rigid optical instruments inserted through natural body openings or small incisions, typically involving video imaging systems with resolution standards exceeding 1080p and specialized channels for biopsy or instrument delivery. The primary commercial purpose is to enable early disease detection, reduce surgical trauma, and lower per-procedure healthcare costs compared to open surgical alternatives. Colonoscopy procedures sustain the largest revenue pool due to established screening protocols for colorectal cancer detection across mature healthcare systems. Capsule endoscopy represents the fastest-expanding technology segment as patient preference for non-invasive examination methods reshapes demand patterns. Robotic endoscopy occupies concentrated investment focus from manufacturers seeking premium pricing through enhanced precision and reduced operator variability.
FDA 510(k) premarket notification requirements and the EU MDR conformity assessment framework shape device approval timelines and clinical evidence standards for market access across North America and Europe. Japan's PMDA and China's NMPA impose additional localization testing that fragments regulatory strategy for multinational manufacturers. ISO 13485 quality management certification remains the baseline operational requirement for supply chain participation worldwide. Stakeholders must monitor reimbursement code consolidation trends and ambulatory center accreditation standards that determine site-of-service economics.
Market Dynamics
Outpatient migration from inpatient hospital settings to ambulatory surgical centers is compressing site-of-service economics and forcing manufacturers to reconfigure device specifications, service models, and pricing architectures for lower-acuity environments.
Growth Catalysts
- EU MDR conformity assessment:Stricter clinical evidence requirements for reusable endoscope reprocessing are accelerating replacement cycles and driving demand for single-use alternatives.
- Colorectal cancer screening mandates:Population-based programs in Germany, Japan, and the United States are institutionalizing procedure volumes through reimbursement guarantees.
- Capsule endoscopy platforms:Patient preference for non-invasive examination methods is expanding addressable populations beyond traditional colonoscopy-intolerant cohorts.
Market Restraints
- Supply concentration in Japanese imaging sensors:Dependence on specialized CMOS and CCD components from concentrated manufacturing clusters creates vulnerability to disruption.
- FDA 510(k) clinical data requirements:Expanded predicate device comparisons and human factors testing are extending premarket notification timelines.
- Reprocessing liability exposure:Hospital-acquired infection litigation risks associated with inadequate high-level disinfection are elevating insurance and compliance costs.
Strategic Opportunities
- Underpenetrated screening in India:Low colorectal cancer screening rates relative to disease burden present expansion potential for mobile endoscopy units.
- Robotic-assisted therapeutic integration:Convergence of flexible endoscopy platforms with haptic feedback and autonomous navigation is opening premium procedural categories.
- Japan's PMDA fast-track pathway:Sakigake designation for breakthrough devices offers accelerated approval for AI-augmented diagnostic systems.
Industry Challenges
- Gastroenterologist training pipeline:Procedural volume requirements for competency certification are constraining workforce expansion relative to screening demand.
- ISO 13485 audit complexity:Multi-site quality management system certification for distributed manufacturing networks is consuming compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopy Procedures Estimates Market |
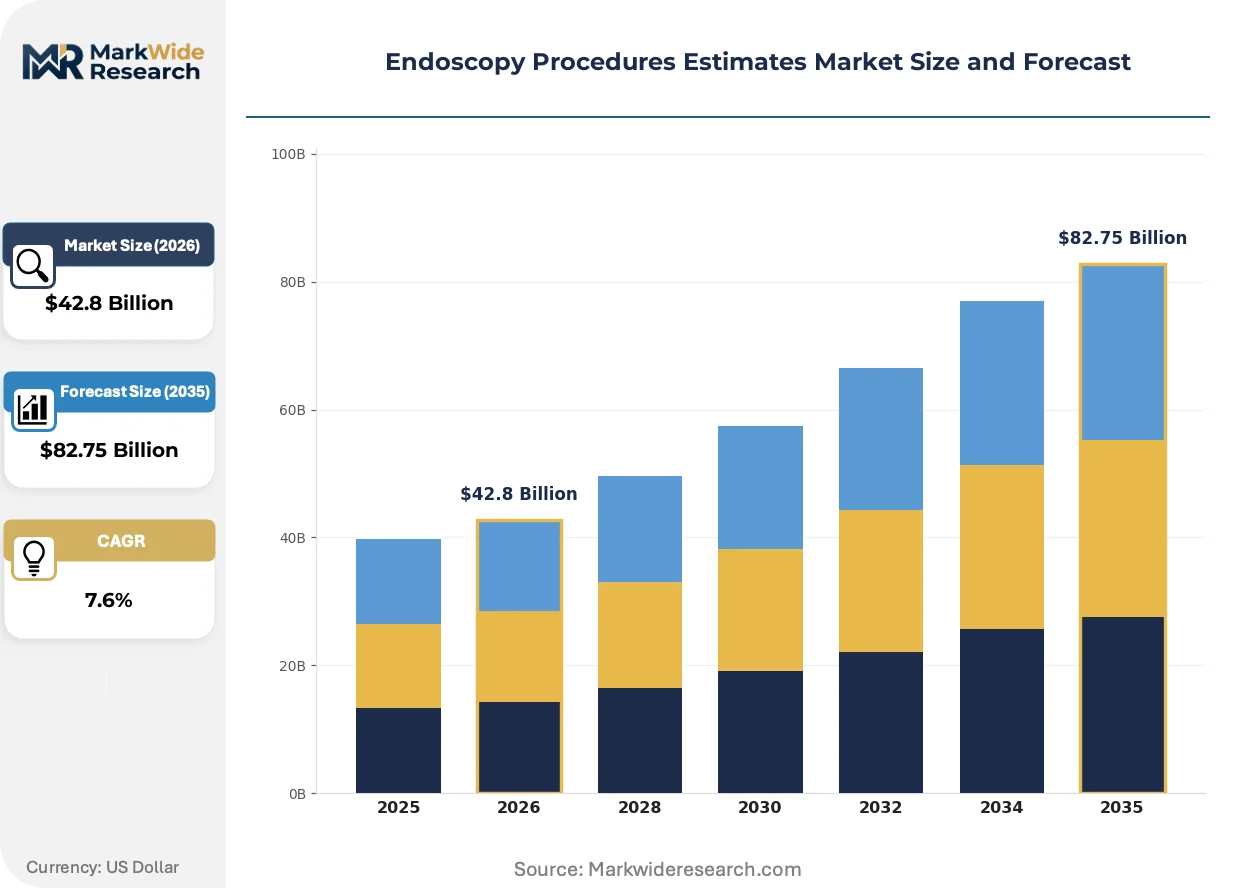
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $82.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Upper GI Endoscopy, Colonoscopy, Endoscopic Ultrasound, Bronchoscopy End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Practices Technology: Video Endoscopy Systems, Capsule Endoscopy, Flexible Endoscopy, Robotic Endoscopy Application: Diagnostic, Therapeutic, Screening, Monitoring |
| Companies Covered | Olympus Corporation, Medtronic, Boston Scientific, Stryker Corporation, Karl Storz, Fujifilm Holdings Corporation, Apollo Hospitals Enterprise Ltd, Johnson & Johnson, Ramsay Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopy Procedures Estimates Market Strategic Shifts & Innovations
Artificial intelligence integration and disposable device architectures are simultaneously elevating diagnostic precision and eliminating cross-contamination risks, restructuring competitive advantage around software-enabled workflows rather than hardware durability alone.
Single-use flexible endoscopes are fragmenting the traditional reusable device market by eliminating reprocessing infrastructure requirements. Ambulatory surgical centers are adopting these platforms fastest due to capital constraint and space limitations. The technology is fragmenting purchasing decisions away from capital equipment committees toward per-procedure supply contracts.
EU MDR Article 120 transition deadlines are forcing manufacturers to resubmit technical documentation for legacy devices under stricter biocompatibility and clinical performance standards. Small-to-mid cap suppliers lacking notified body relationships face market exit. The regulation is compressing competitive field concentration in upper GI and colonoscopy segments.
Hospital procurement departments are unbundling service contracts from device purchases, separating preventive maintenance from capital acquisition. Health systems in the United States are negotiating direct-to-manufacturer agreements that bypass traditional distributor markups. This restructuring is most visible in integrated delivery networks consolidating purchasing across multiple states.
Endoscopy Procedures Estimates Market Segmentation
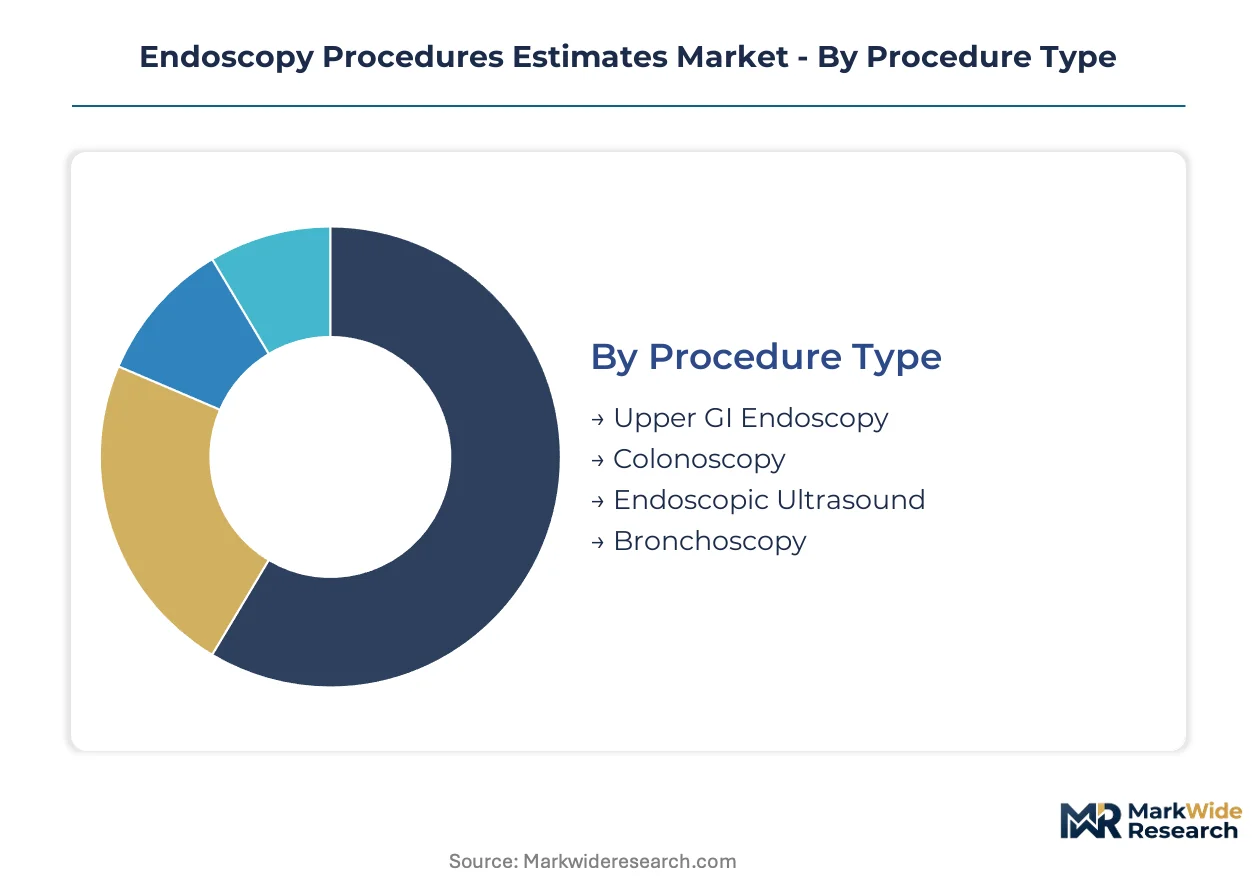
Endoscopy procedure segmentation reveals how site-of-service economics and technology substitution pressures reshape competitive priorities across diagnostic and therapeutic interventions. Manufacturers must align portfolio investments with diverging reimbursement profiles and capital intensity requirements.
Procedure Type:
Colonoscopy faces the strongest substitution pressure from capsule-based alternatives, while upper GI procedures retain structural demand from direct visualization requirements.
- Upper GI Endoscopy:Direct esophageal and gastric visualization with biopsy capability sustains irreplaceable demand for Barrett's esophagus surveillance and ulcer assessment. Hospital gastroenterology departments in the United States and Germany concentrate procedural volume where reimbursement codes reward tissue acquisition.
- Colonoscopy:Optical colonoscopy with polypectomy channel dominates colorectal cancer screening protocols through established reimbursement guarantees. Ambulatory surgical centers in Japan and the United States are capturing migration volume as payors favor same-day discharge economics over inpatient settings.
- Endoscopic Ultrasound:EUS combines endoscopic access with ultrasonographic imaging for pancreaticobiliary and mediastinal assessment.
- Bronchoscopy:Flexible bronchoscopy with lavage and biopsy capability serves pulmonary nodule evaluation and lung cancer staging.
Colonoscopy anchors the volume base while capsule platforms gain share at the steepest rate in screening-intolerant populations.
End User:
Capital equipment requirements and reprocessing infrastructure create sharp cost-tier differentiation across care settings.
- Hospitals:Inpatient facilities maintain high-complexity therapeutic procedure dominance through integrated surgical support and emergency backup capacity. Academic medical centers in Germany and Japan concentrate advanced endoscopic resection and submucosal dissection volume.
- Ambulatory Surgical Centers:Freestanding ASCs prioritize single-use device economics to eliminate reprocessing capital and compliance overhead. United States payor migration policies accelerate site-of-service shift for low-acuity screening procedures.
- Clinics:Office-based settings concentrate diagnostic upper GI procedures with shallow sedation protocols.
- Specialty Practices:Gastroenterology-dedicated practices bundle screening colonoscopy with pathology and anesthesia services.
Hospitals retain the therapeutic complexity margin while ambulatory surgical centers expand screening volume most aggressively.
Technology:
Disposable architectures are displacing reusable device incumbents fastest where reprocessing liability and capital constraints intersect.
- Video Endoscopy Systems:Integrated 1080p+ imaging platforms with processor-light source combinations anchor hospital capital budgets. Olympus and Pentax installed bases in Japan and the United States create switching-cost barriers for replacement purchases.
- Capsule Endoscopy:Ingestible camera platforms eliminate sedation requirements and expand screening access to colonoscopy-contraindicated patients. Small bowel capsule demand concentrates in celiac disease and obscure GI bleeding evaluation.
- Flexible Endoscopy:Conventional reusable flexible scopes face replacement pressure from single-use alternatives in ASC settings.
- Robotic Endoscopy:Haptic-enabled platforms target premium therapeutic categories with precision positioning requirements.
Video endoscopy systems anchor the installed base while capsule platforms climb the fastest in patient-preferred screening segments.
Application:
Reimbursement code consolidation is compressing diagnostic margins while therapeutic applications command premium procedural payments.
- Diagnostic:Visual inspection with biopsy sampling generates baseline procedure volumes through screening mandates. United States Medicare reimbursement for diagnostic colonoscopy faces downward pressure from code bundling initiatives.
- Therapeutic:Polypectomy, hemostasis, and stricture dilation command enhanced reimbursement through device-intensive intervention. Japanese endoscopic submucosal dissection techniques are expanding Western therapeutic adoption.
- Screening:Asymptomatic population surveillance drives volume through colorectal cancer prevention programs.
- Monitoring:Disease surveillance intervals for inflammatory bowel disease and Barrett's esophagus create recurring procedure demand.
Screening applications anchor population-scale volume while therapeutic interventions capture the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese imaging sensor clusters and German precision manufacturing dominate upstream component supply for endoscopy systems. Device assembly concentrates in manufacturing corridors near regulatory hubs where FDA, EU MDR, and PMDA compliance infrastructure resides. Procedure demand spreads across aging populations in North America, Western Europe, and East Asia.
United States
Medicare reimbursement expansion for colorectal cancer screening drives ambulatory surgical center volume migration. FDA 510(k) premarket notification pathways shape device commercialization timelines for manufacturers seeking market access. Minneapolis and Boston corridor health systems consolidate purchasing through integrated delivery networks that negotiate direct manufacturer agreements.
Germany
Population-based colorectal cancer screening mandates institutionalize procedure volumes through statutory health insurance guarantees. EU MDR conformity assessment requirements accelerate replacement cycles for reusable endoscope portfolios. Baden-Württemberg and Bavaria manufacturing clusters concentrate precision optical component fabrication for video endoscopy platforms.
Japan
Aging demographics and universal health coverage sustain the highest per-capita endoscopy procedure rates globally. PMDA Sakigake fast-track designation offers accelerated approval pathways for AI-augmented diagnostic systems. Tokyo and Osaka metropolitan areas concentrate advanced endoscopic submucosal dissection expertise and therapeutic procedure volume.
India
Low colorectal cancer screening penetration relative to disease burden creates expansion potential for mobile endoscopy units and telemedicine-enabled screening networks. CDSCO medical device regulations impose localization testing requirements that fragment multinational regulatory strategy. Maharashtra and Karnataka urban corridors concentrate private hospital capacity where Apollo Hospitals Enterprise Ltd anchors diagnostic service delivery.
United Kingdom
NHS bowel cancer screening programme targets drive colonoscopy waiting list management and capacity expansion priorities. MHRA post-Brexit regulatory autonomy diverges from EU MDR timelines for device market access. London and Manchester academic medical centers concentrate advanced therapeutic endoscopy training and complex procedure referral networks.
Endoscopy Procedures Estimates Market Key Industry Players
Concentration sits with integrated imaging platform providers that combine processor-light source systems with disposable device architectures. The vendor base separates into three tiers: full-stack platform owners, therapeutic device specialists, and regional service network operators. Consolidation pressure intensifies as health systems unbundle service contracts from capital purchases and negotiate direct procurement agreements. Strategic moves center on single-use portfolio expansion and AI-enabled diagnostic software integration.
Within the integrated platform tier, Olympus Corporation and Fujifilm Holdings Corporation anchor Japanese-origin imaging system supply. Medtronic and Boston Scientific occupy the therapeutic innovation vector with device-intensive intervention portfolios. Karl Storz represents German precision manufacturing archetype in rigid endoscopy segments. Stryker Corporation and Johnson & Johnson sit within diversified medical technology conglomerates where endoscopy serves as one vertical among orthopedic and surgical device portfolios.
| Leading Market Players |
|---|
| Olympus Corporation |
| Medtronic |
| Boston Scientific |
| Stryker Corporation |
| Karl Storz |
| Fujifilm Holdings Corporation |
| Apollo Hospitals Enterprise Ltd |
| Johnson & Johnson |
| Ramsay Health Care |
| Others |
Cost & Logistics Intelligence
Japanese CMOS sensor fabrication scale and German precision optical component clusters anchor production economics, concentrating upstream supply among a handful of specialized manufacturers whose capacity utilization rates directly determine price floors for downstream device assembly.
Pricing Analysis
Volume-discount tiering structures separate integrated platform purchases with multi-year service commitments from per-procedure single-use supply contracts. Price differentiation rests on ISO 13485 certification grade and installed-base switching costs rather than raw component quality. Pricing pressure stems from ambulatory surgical centers negotiating direct-to-manufacturer agreements that bypass traditional distributor markups. Hospital procurement committees demonstrate lowest price sensitivity due to capital budget insulation, while freestanding ASCs drive hardest bargain on per-unit economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate Japanese imaging sensor procurement, whereas European manufacturers maintain strategic stockpiles of specialized optical glass and precision-machined metal components to buffer against regulatory inspection delays. Geographic supply concentration centers on Japan for CMOS/CCD sensors, Germany for rigid endoscope optics, and China for disposable polymer extrusion. Raw material dependencies include rare-earth elements for lens coatings, medical-grade polymers for single-use sheaths, and high-purity quartz for light transmission. Single-source vulnerability in specialized sensor fabrication creates systemic exposure. Distribution runs through regional authorized dealers with service engineering capabilities, though integrated delivery networks increasingly demand direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endoscopy procedures estimates represent an early-cycle expansion story, with single-use device substitution and AI-augmented diagnostic platforms accelerating penetration beyond traditional screening-intolerant cohorts.
For Market Incumbents: Secure installed-base loyalty through backward integration into reprocessing service networks that lock in hospital system contracts. Expand single-use portfolio breadth to capture ambulatory surgical center volume migration before disposable specialists establish foothold. Prioritize EU MDR notified body relationships to accelerate legacy device recertification timelines as regulatory consolidation compresses competitive field.
For New Entrants and Emerging Players: Service-layer gaps in AI-powered polyp detection software and remote procedural supervision present white-space opportunities where Olympus and Fujifilm under-invest. Target India's mobile endoscopy screening networks as most penetrable geography given low colorectal cancer screening rates and Apollo Hospitals' expansion appetite. Pursue software-as-diagnostic-companion go-to-market angle that circumvents capital equipment committee purchasing friction.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among single-use device specialists with per-procedure supply contracts rather than capital equipment vendors with lumpy replacement cycles. Long-term viability favors manufacturers with dual reusable-disposable portfolios that capture both hospital and ASC site-of-service economics. Watch FDA 510(k) clearance velocity for AI-augmented systems as inflection indicator for diagnostic software valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Portfolio Expansion | Eliminates reprocessing liability exposure while capturing ASC volume migration away from hospital settings. |
| AI Diagnostic Software Development | PMDA Sakigake fast-track pathway in Japan accelerates approval for polyp detection algorithms. |
| Direct-to-Health-System Contracting | Bypasses distributor markups as integrated delivery networks consolidate purchasing across state boundaries. |
| EU MDR Notified Body Certification | Technical documentation resubmission under stricter biocompatibility standards determines market access survival. |
| Mobile Screening Unit Deployment | Telemedicine-enabled networks address India's underpenetrated rural colorectal cancer detection gap. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gastroenterologists, hospital purchasing committee members, biomedical engineering directors, ambulatory surgical center administrators, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA approval registries, CMS Medicare reimbursement code updates, and hospital procurement transaction records. Bottom-up procedure volume estimates triangulated against top-down device shipment data across the analysis window.
The projection horizon spans from base-year market sizing through terminal-year estimates without interim annual disclosure. Segmentation dimensions modeled include procedure type, site-of-service setting, technology architecture, and application purpose. CAGRs were derived from logistic growth curve fitting anchored to screening mandate penetration curves and device replacement cycle dynamics. Forecast inputs incorporated EU MDR transition deadline impacts on legacy device retirement and single-use substitution elasticity parameters.
Underlying assumptions cover reimbursement code stability, regulatory approval pathway continuity, and screening program enrollment trajectories, with deviation risk concentrated in FDA clinical data requirement expansion and supply disruption in Japanese sensor clusters. Revision becomes warranted when ambulatory surgical center accreditation standards or payor site-of-service policies cross threshold shifts that alter volume migration velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Global Endoscopes Market
Endoscopy
US Colonic Stents Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Endoscopy Device Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Endoscopic Ultrasound (EUS) Market
Endoscopy
Video Laryngoscope Market
Endoscopy
Sigmoidoscope Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Japan Endoscopy Devices Market