
 Hysteroscopic Endometrial Resection Procedures Market | 2026-2036
Hysteroscopic Endometrial Resection Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Hysteroscopic Endometrial Resection Procedures Market Foresight
Equipment leasing and pay-per-procedure financing is rewriting capital deployment across ambulatory surgical centers. KARL STORZ GmbH & Co. KG leverages its vertically integrated manufacturing in Tuttlingen to control resectoscope quality and cost. Richard Wolf GmbH anchors its competitive position through specialized electrode portfolios for bipolar resection. Stryker competes by extending integrated fluid management systems that reduce per-procedure complexity.
Hysteroscopic endometrial resection denotes the transcervical removal or destruction of endometrial tissue using electrosurgical, laser, or mechanical instruments under direct hysteroscopic visualization, typically employing 26-28 French resectoscopes with continuous-flow fluid distension systems to maintain uterine cavity clarity. The procedure serves as a minimally invasive alternative to hysterectomy for benign menstrual disorders, preserving uterine anatomy and fertility potential in selected patients. Bipolar systems lead procedural volume due to reduced fluid absorption risks and compatibility with saline distension media, while laser resection commands premium positioning in fertility-preserving applications where tissue thermal spread must be minimized. Outpatient clinics represent the fastest-growing end-user channel as same-day discharge protocols and office-based hysteroscopy expand access beyond traditional hospital settings.
FDA 510(k) clearance requirements govern device commercialization in the United States, while the EU Medical Device Regulation mandates notified body certification and post-market surveillance for resectoscope systems sold in Europe. The EPA regulates disposal pathways for resection byproducts containing biological material, influencing facility operational protocols. Stakeholders must monitor evolving reimbursement codes for office-based hysteroscopic procedures across Medicare and commercial payers to align capital investment with site-of-care migration trends.
Market Dynamics
Outpatient migration is compressing capital deployment cycles as ambulatory surgical centers displace inpatient hysterectomy volumes through same-day resection protocols. This site-of-care shift forces manufacturers to recalibrate device footprints, fluid management integration, and disposable economics for lower-acuity settings.
Growth Catalysts
- Saline-compatible bipolar electrosurgery:Reduced hyponatremia risk expands procedural candidacy to outpatient clinics previously restricted to hospital settings.
- Germany's Tuttlingen cluster:Concentrated endoscope manufacturing infrastructure compresses lead times for resectoscope component sourcing across European distribution networks.
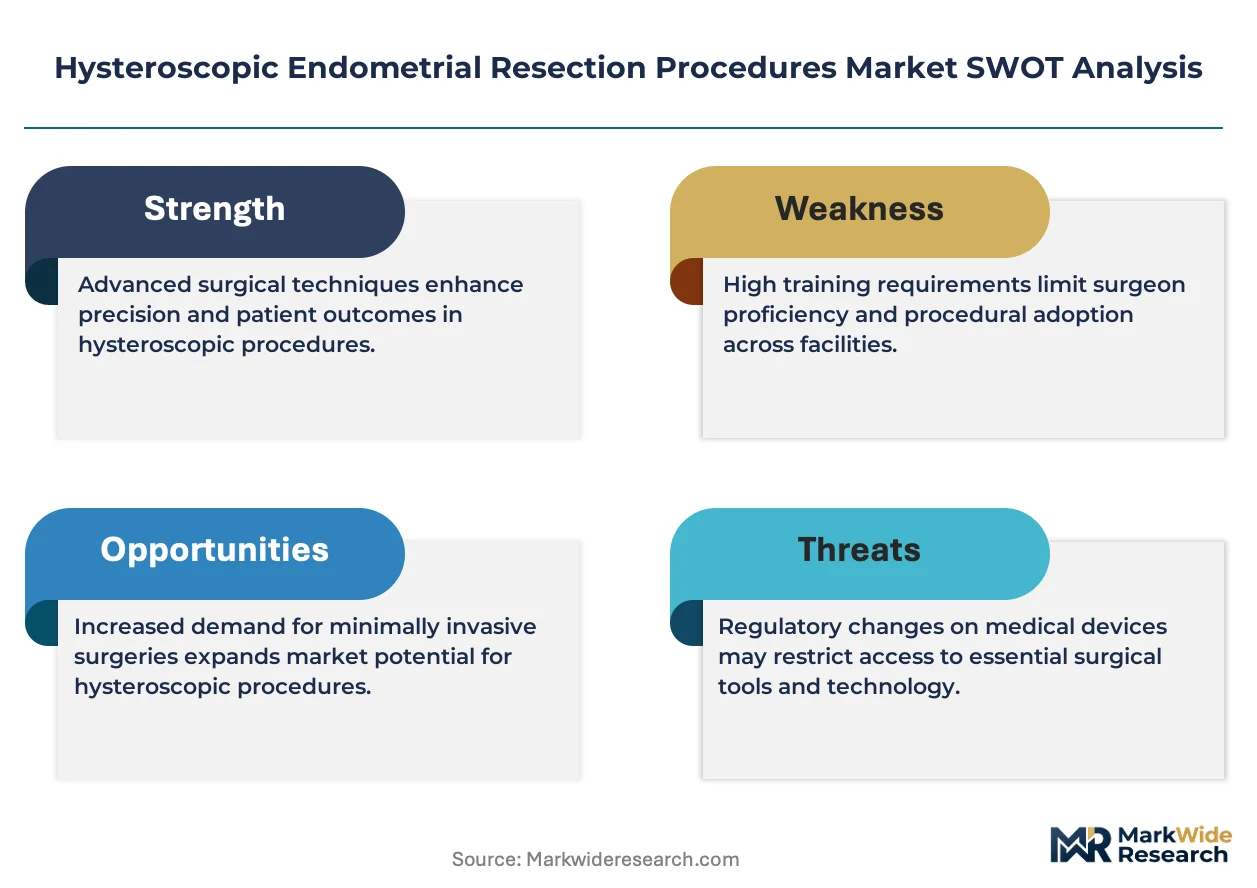
- EU Medical Device Regulation post-market surveillance:Mandatory clinical follow-up data elevates evidence standards, favoring incumbent systems with established safety databases.
Market Restraints
- Single-use electrode cost volatility:Precious metal pricing in bipolar electrode tips creates margin pressure for high-volume outpatient operators.
- Tuttlingen supply concentration:German endoscope component dominance exposes procurement timelines to regional logistics disruptions.
- Fluid absorption physiology:Uterine perforation risk during resection mandates standby anesthesia capacity, limiting full office-based conversion.
Strategic Opportunities
- India's tier-2 city expansion:Underpenetrated gynecological service infrastructure creates first-mover positioning for compact bipolar systems.
- Disposable sheaths with integrated electrodes:Elimination of reprocessing protocols aligns with ASC infection control priorities.
- Japan's aging demographic fertility preservation:Laser resection demand for myoma resection in nulliparous patients commands premium positioning.
Industry Challenges
- Hysteroscopist training pipeline:Subspecialty fellowship scarcity constrains procedural capacity expansion in underserved markets.
- FDA 510(k) predicate device dependency:Substantial equivalence pathways for novel electrode geometries encounter reviewer variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hysteroscopic Endometrial Resection Procedures Market |
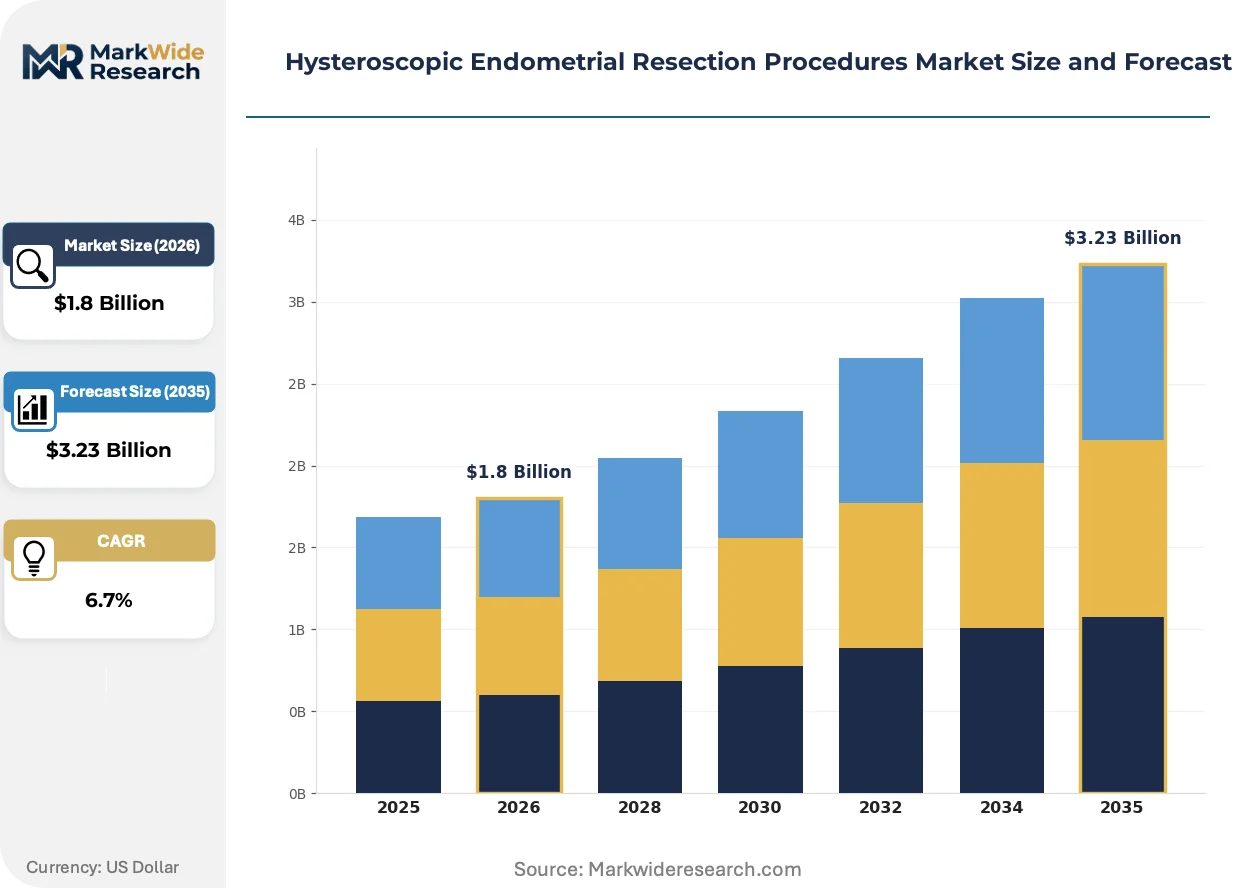
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resectoscopes, Electrodes, Bipolar Systems, Fluid Management Systems Technique: Laser Resection, Cold Resection, Hormonal Treatment, Thermal Ablation End User: Hospitals, Outpatient Clinics, Specialty Fertility Centers, Academic Institutions Application: Menstrual Disorders, Submucosal Fibroids, Endometrial Hyperplasia, Uterine Polyp Removal |
| Companies Covered | WISAP Medical Technology, Richard Wolf GmbH, KARL STORZ GmbH & Co. KG, Stryker, Olympus Corporation, Hologic, Medtronic, Ethicon LLC, Maxer Endoscopy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hysteroscopic Endometrial Resection Procedures Market Shifts & Advancements
Electrosurgical platform architecture is converging with fluid management automation, collapsing the traditional separation between energy delivery and cavity distension control. This integration is redefining competitive differentiation beyond standalone resectoscope specifications.
Bipolar resection with integrated impedance sensing is hybridizing tissue recognition algorithms with real-time power modulation. Ambulatory surgical centers in North America are adopting these systems at accelerated replacement cycles. The technology is hybridizing capital equipment and consumable revenue models into bundled per-procedure contracts.
EU MDR clinical evaluation requirements are extending notified body review timelines for resectoscope system renewals. Manufacturers with legacy CE certificates face compressed transition windows to generate post-market clinical follow-up data. Class III device reclassifications are forcing portfolio rationalization among smaller electrode suppliers.
Service unbundling is separating device maintenance from capital purchase agreements. Hospital procurement departments in Germany are negotiating standalone technical service contracts with third-party providers. This disintermediation is most visible in multi-site health systems seeking to consolidate vendor management overhead across regional resectoscope fleets.
Hysteroscopic Endometrial Resection Procedures Market Segmentation
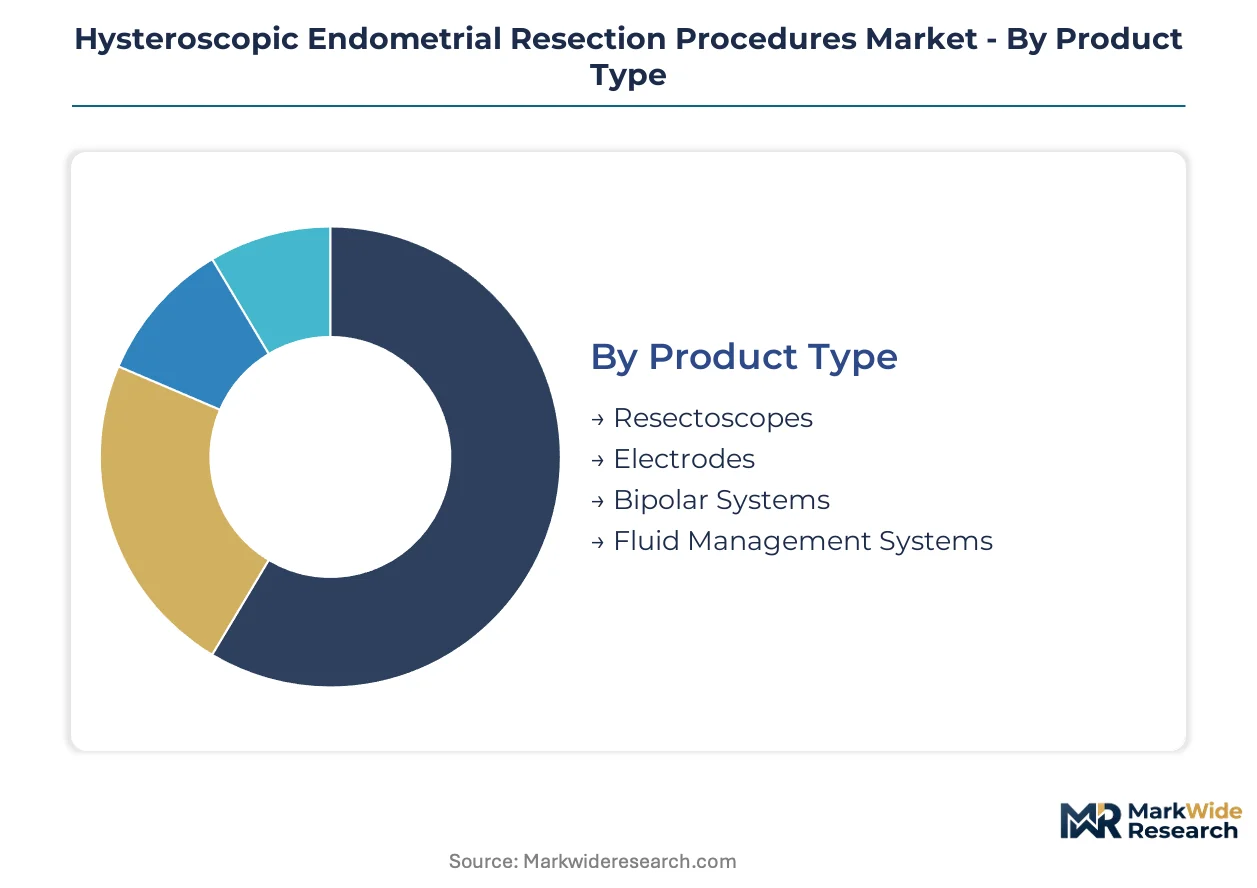
Device configuration and site-of-care economics fragment procurement patterns across hysteroscopic endometrial resection. Manufacturers calibrate portfolio depth against reimbursement velocity and capital deployment constraints in each channel.
Product Type:
The use-case spectrum spans diagnostic visualization through complete tissue resection, with system integration determining workflow efficiency and total cost of ownership.
- Bipolar Systems:Saline-compatible electrosurgical platforms with active electrode monitoring reduce hyponatremia risk and enable outpatient migration. German manufacturing clusters in Tuttlingen anchor supply for European hospital networks seeking same-day discharge protocols.
- Resectoscopes:26-28 French continuous-flow instruments with rigid optics provide the foundational visualization platform. Academic medical centers in the United States drive demand for 4K-compatible configurations compatible with integrated operating room infrastructure.
- Electrodes:Disposable loop, ball, and barrel electrodes with precious metal tips generate recurring revenue streams. Precious metal price volatility compresses margins for high-volume ambulatory surgical center operators.
- Fluid Management Systems:Automated pressure regulation and deficit monitoring devices reduce nursing labor intensity. These systems gain traction in outpatient clinics prioritizing reduced staffing models.
Established volume favors bipolar systems; emerging adoption favors fluid management systems.
Technique:
Cost tier differentiation separates capital-intensive laser platforms from disposable-heavy electrosurgical approaches, with reimbursement alignment determining site penetration.
- Laser Resection:Nd:YAG and diode laser systems deliver precise tissue vaporization with minimal thermal spread. Specialty fertility centers in Japan command premium positioning for myoma resection in nulliparous patients.
- Thermal Ablation:Global endometrial ablation devices deploy bipolar radiofrequency or heated fluid for non-resectoscopic tissue destruction. Outpatient clinics in North America favor these systems for reduced hysteroscopist training requirements.
- Cold Resection:Mechanical tissue removal without energy delivery eliminates thermal injury risk. This technique sees selective use in fertility-preserving cases where endometrial basalis layer integrity is paramount.
- Hormonal Treatment:Pre-operative GnRH agonist therapy reduces endometrial thickness and vascularity. Academic institutions employ this adjunct to reduce procedural complexity in complex pathology cases.
Capital deployment constraints favor thermal ablation; clinical precision requirements favor laser resection.
End User:
Customer type determines purchasing authority structure, with hospital procurement departments negotiating enterprise contracts against clinic-level disposable ordering.
- Outpatient Clinics:Office-based hysteroscopy suites with compact bipolar systems and local anesthesia protocols. These facilities in Germany and the United States are climbing the fastest as same-day discharge mandates expand.
- Hospitals:Inpatient and ambulatory surgical center settings with full anesthesia support and 24-hour observation capacity. North American health systems consolidate resectoscope fleets across multi-site networks.
- Specialty Fertility Centers:Reproductive endocrinology practices prioritizing uterine cavity preservation. These centers in Japan and select European markets command premium pricing for fertility-sparing techniques.
- Academic Institutions:Teaching hospitals with fellowship programs and research protocols. These sites drive early adoption of integrated impedance-sensing platforms and 4K visualization upgrades.
Procurement scale favors hospitals; margin expansion favors specialty fertility centers.
Application:
Pathology severity and malignancy risk stratify reimbursement intensity, with benign conditions enabling full outpatient conversion while hyperplasia cases retain hospital tethering.
- Menstrual Disorders:Abnormal uterine bleeding refractory to medical management represents the highest-volume indication. Outpatient clinics in North America capture the majority of these cases through endometrial ablation alternatives.
- Submucosal Fibroids:Type 0 and Type 1 myomas accessible through hysteroscopic approach. European gynecological services prioritize resection over hysterectomy for fertility preservation in younger patients.
- Uterine Polyp Removal:Diagnostic hysteroscopy with polypectomy for intermenstrual bleeding or infertility evaluation. Ambulatory surgical centers favor single-use polypectomy devices to eliminate reprocessing overhead.
- Endometrial Hyperplasia:Precancerous endometrial proliferation requiring histologic sampling and focal resection. Hospital-based settings retain these cases due to anesthesia standby requirements and malignancy exclusion protocols.
Volume concentration favors menstrual disorders; reimbursement intensity favors endometrial hyperplasia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's outpatient reimbursement reforms and the United States' site-of-care migration incentives are accelerating ambulatory adoption of hysteroscopic resection systems across developed markets.
United States
Medicare's expansion of same-day surgical facility payments drives outpatient clinic investment in compact bipolar systems. FDA 510(k) clearance pathways compress commercialization timelines for novel electrode geometries. Academic medical centers in Greater Boston anchor demand for 4K-integrated visualization platforms.
Germany
Statutory health insurance coverage for office-based hysteroscopy procedures incentivizes clinic-level capital deployment. EU MDR post-market surveillance requirements elevate evidence standards for resectoscope system renewals. The Tuttlingen manufacturing cluster concentrates endoscope component supply for European distribution networks.
Japan
Aging demographics and fertility preservation priorities command premium positioning for laser resection systems in nulliparous patients. PMDA regulatory reviews emphasize clinical follow-up data for energy-based surgical devices. The Kansai region's reproductive medicine centers drive adoption of myoma resection protocols.
India
Underpenetrated gynecological service infrastructure in tier-2 cities creates first-mover positioning for cost-optimized bipolar platforms. CDSCO medical device registration requirements shape import substitution strategies for domestic manufacturers. Maharashtra's hospital networks consolidate procurement across multi-site ambulatory surgical center expansions.
United Kingdom
NHS England's outpatient procedure targets redirect abnormal uterine bleeding cases from inpatient hysterectomy to hysteroscopic resection. MHRA conformity assessment timelines influence CE-marked device transition post-Brexit. London's teaching hospitals pilot integrated impedance-sensing platforms for fellowship training programs.
Hysteroscopic Endometrial Resection Procedures Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated endoscope manufacturers and diversified surgical platform conglomerates. German precision engineering clusters and American integrated health technology groups represent distinct strategic archetypes. Competitive moves concentrate on M&A for electrode technology access and strategic partnerships for fluid management integration.
Among German-based specialists, Richard Wolf GmbH and KARL STORZ GmbH & Co. KG occupy positions anchored in Tuttlingen's component manufacturing density, while Stryker exemplifies the diversified platform archetype extending surgical visualization into integrated operating room ecosystems.
| Leading Market Players |
|---|
| WISAP Medical Technology |
| Richard Wolf GmbH |
| KARL STORZ GmbH & Co. KG |
| Stryker |
| Olympus Corporation |
| Hologic |
| Medtronic |
| Ethicon LLC |
| Maxer Endoscopy |
| Others |
Supply & Pricing Matrix
Tuttlingen's concentrated endoscope manufacturing infrastructure anchors component supply for resectoscope systems, positioning German precision engineering clusters as the primary margin capture point across European and North American distribution networks. This upstream concentration translates into pricing power for bipolar electrode assemblies and continuous-flow instrument platforms, while downstream ambulatory surgical centers face compressed negotiation leverage on disposable consumables.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared bipolar systems and economy-tier configurations lacking saline-compatibility validation. Three-tier pricing structure across premium, standard, and economy levels reflects differential after-sales service bundling and electrode precious-metal content. Cost compression in the outpatient clinic channel is intensifying because high-volume operators negotiate per-procedure contracts that eliminate capital purchase premiums. Academic medical centers exhibit lowest price sensitivity due to integrated operating room infrastructure requirements, while tier-2 city hospitals in emerging markets drive hardest bargain on standalone device procurement.
Supply Chain Analysis
Extended payment terms from Tuttlingen-based manufacturers to European hospital networks illustrate how supplier financing facilities lubricate capital equipment deployment cycles. Component sourcing draws from Germany, the United States, and Japan for optical assemblies, electrosurgical generators, and impedance-sensing circuitry respectively. Single-source vulnerability concentrates in precious-metal electrode tip supply from South African mining operations. Distribution runs through specialized surgical device distributors with GPO contracting relationships rather than direct manufacturer-to-facility sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation across multi-site health systems in North America and Germany is shifting buyer power toward enterprise contracting, fragmenting pricing autonomy for individual clinic sites. This concentration forces manufacturers toward bundled service agreements and away from transactional device sales.
For Market Incumbents: Insulate margin pools by deepening backward integration into electrode precious-metal sourcing and expanding captive fluid management system production. Laser resection platforms from Japanese specialists threaten premium positioning in fertility-preserving segments. Certification investment in EU MDR post-market surveillance databases creates switching costs for hospital procurement committees evaluating system renewals. For New Entrants and Emerging Players: India's tier-2 city gynecological service infrastructure offers the most penetrable white-space for cost-optimized bipolar platforms with reduced feature sets. Compact disposable sheath configurations eliminate reprocessing infrastructure requirements that constrain clinic-level adoption. Direct distribution partnerships with Maharashtra's consolidating hospital networks bypass established distributor markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across disposable electrode manufacturing as precious-metal recycling technologies mature. Long-term viability favors acquisition targets with established notified body relationships under EU MDR rather than legacy CE certificate dependencies. Watch PMDA regulatory review timelines for laser resection systems as the signal for Japan fertility-preservation market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR transition compresses renewal windows for legacy resectoscope certificates. |
| Hospital System Partnership | Multi-site ASC networks in Germany consolidate procurement across regional fleets. |
| Software Companion Development | Integrated impedance-sensing algorithms differentiate bipolar platforms from commodity electrosurgery. |
| Reimbursement Strategy | Medicare same-day surgical facility payments accelerate outpatient clinic capital deployment. |
| FDA Submission | 510(k) predicate device pathways for novel electrode geometries encounter reviewer variability. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hysteroscopists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up triangulation across device shipment estimates and top-down reconciliation against procedure volume data anchored market sizing.
Forecast inputs incorporated bipolar system replacement cycles, outpatient migration velocity, and precious-metal price trajectory assumptions across the projection horizon. Segmentation modeling spanned product configuration, technique differentiation, end-user purchasing authority structure, and pathology severity stratification. CAGRs were derived from logistic adoption curves fitted to site-of-care shift parameters and regulatory clearance timeline distributions.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or statutory insurance reimbursement rates would shift the trajectory. Forecasts reflect documented assumptions about procedure volume migration and electrode cost structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Brazil Endoscopy Devices Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
China Arthroscopy Market
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Endoscopic Ultrasound (EUS) Market