
 US Colonic Stents Market | 2026-2036
US Colonic Stents Market Size, Share, and Industry Trends Forecast 2026-2036
US Colonic Stents Market Insights
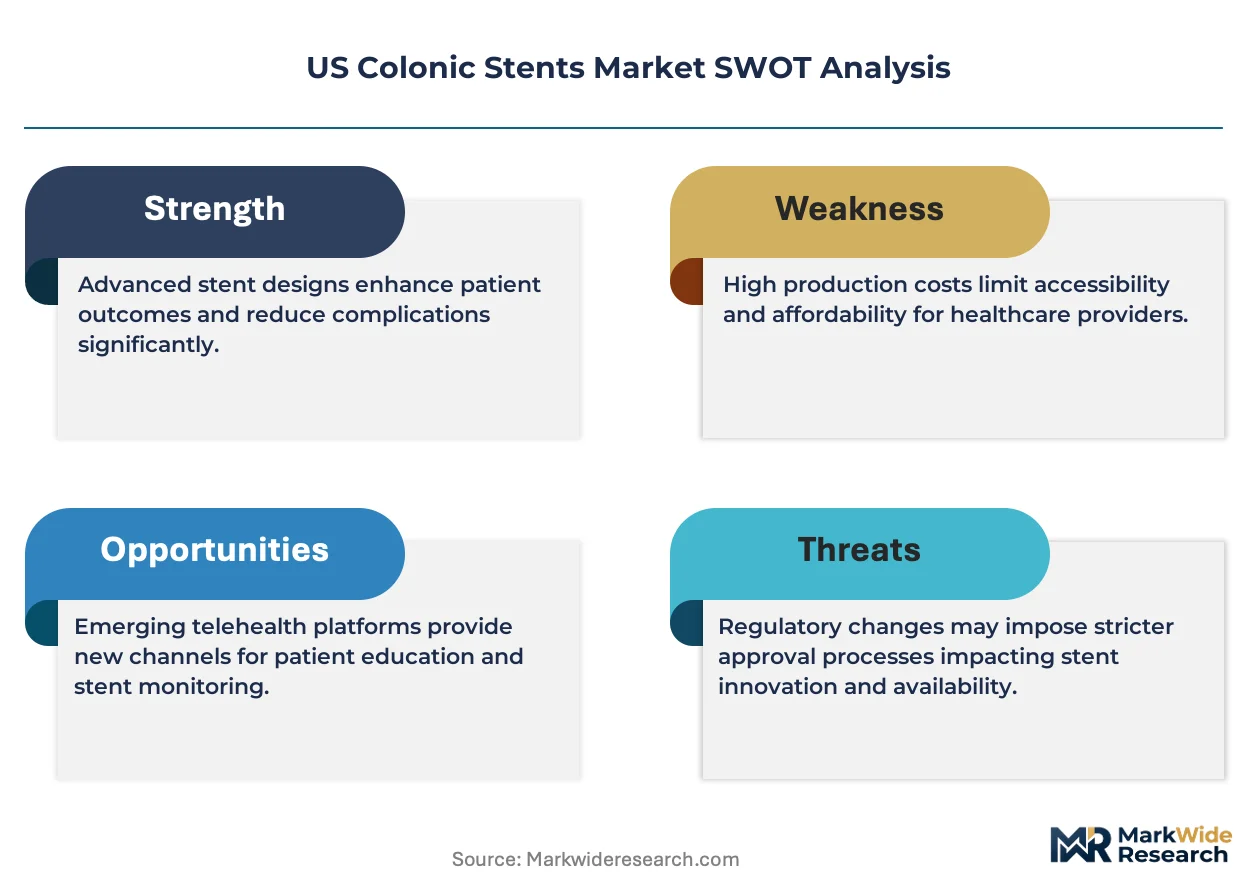
The FDA's updated 510(k) biocompatibility requirements for implantable devices is repositioning the cost-of-entry calculus for domestic manufacturers. Boston Scientific Corporation leverages its vertically integrated nitinol processing capabilities to sustain margin structures under tighter testing mandates. Cook Medical anchors its competitive stance through specialized physician training networks across academic medical centers. Medtronic competes by controlling direct-to-hospital distribution channels that bypass traditional distributor markups.
Colonic stents are tubular prostheses typically constructed from nitinol or stainless steel alloys, designed to maintain luminal patency in malignant colorectal obstructions through radial expansion forces ranging from 8 to 12 Newtons. Metal stents dominate hospital procurement budgets due to superior patency durations and reduced reintervention rates compared to plastic alternatives. Ambulatory Surgical Centers represent the fastest-growing end user segment as outpatient endoscopic stenting protocols expand reimbursement eligibility. Direct sales channels capture the largest margin pools by eliminating intermediary costs on high-value implant contracts.
FDA's Quality System Regulation and the Physician Payments Sunshine Act shape product development timelines and commercial transparency obligations for manufacturers operating in the US. The Centers for Medicare and Medicaid Services maintains reimbursement codes that directly determine procedure economics across hospital and outpatient settings. Stakeholders must monitor evolving CMS national coverage determinations for endoscopic interventions to anticipate volume shifts between inpatient and ambulatory settings.
Market Dynamics
Hospital procurement consolidation across Florida, Georgia, and Texas is compressing vendor margins while elevating volume commitments for colonic stent suppliers. This buyer-side concentration is reshaping contract structures toward multi-year sole-source agreements with embedded price step-downs.
Growth Catalysts
- CMS outpatient reimbursement expansion:Ambulatory Surgical Centers in the Southeast now capture expanded procedure codes for endoscopic stenting, diverting cases from inpatient settings.
- Nitinol alloy processing advances:Domestic wire-forming capabilities are reducing lead times for self-expanding metal stent frames, enabling just-in-time inventory models.
- Aging demographics in Sun Belt states:Florida's Medicare beneficiary growth is driving malignant obstruction case volumes faster than national averages.
Market Restraints
- FDA 510(k) biocompatibility testing escalation:Updated ISO 10993 cytotoxicity requirements are extending clearance timelines by 8-14 months for new nitinol formulations.
- Single-source nitinol feedstock dependency:Domestic stent manufacturers rely on two primary US wire suppliers, creating concentration risk for specialized nickel-titanium alloys.
- Plastic stent substitution in palliative care:Lower-acuity cases in community hospitals are shifting toward temporary polyethylene alternatives to reduce upfront implant costs.
Strategic Opportunities
- Texas ASC network penetration:Dallas-Fort Worth ambulatory centers are under-indexed for complex endoscopic interventions relative to patient density.
- IRA domestic manufacturing incentives:Tax credits for US-based medical device production are offsetting compliance cost inflation for FDA-regulated facilities.
- Remote physician training platforms:Virtual proctoring systems are collapsing geographic barriers to specialized stent placement technique dissemination.
Industry Challenges
- Interventional gastroenterology fellowship pipeline constraints:ACGME-accredited training slots for advanced endoscopy are not keeping pace with stent placement demand growth.
- Legacy hospital ERP integration:Implant tracking systems for FDA Unique Device Identification mandates are requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Colonic Stents Market |
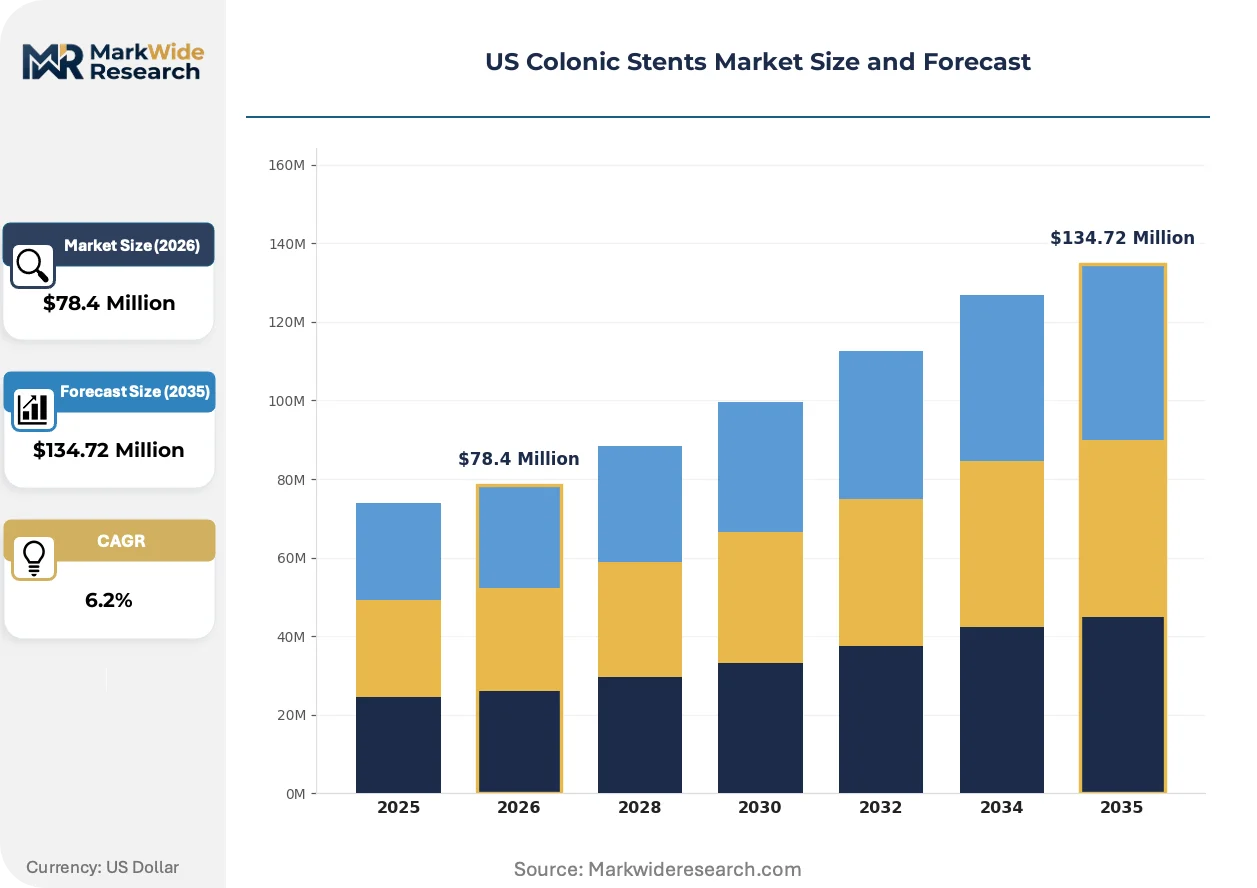
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $134.72 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Stents, Plastic Stents, Drug-Eluting Stents, Biliary Stents End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Centers Distribution Channel: Direct Sales, Online Sales, Distributors, Third-Party Vendors Material: Silicone, Polyurethane, Stainless Steel, Composite Materials |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Medtronic, CONMED Corporation, Merit Medical Systems, Olympus Corporation, Becton, Dickinson and Company, Hobbs Medical, Stryker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Colonic Stents Market Trends and Innovations
Stent design priorities are pivoting from mechanical patency alone toward integrated delivery system ergonomics and real-time procedural feedback. This shift is elevating R&D investment in catheter-based deployment mechanics.
Drug-eluting colonic stent platforms are rewriting the competitive landscape for malignant obstruction management. Academic medical centers in the Northeast are piloting paclitaxel-coated nitinol frameworks to extend patency duration beyond bare metal benchmarks. This technology is compressing the addressable market for repeat intervention procedures.
FDA's updated guidance on nitinol corrosion testing under ISO 10993-15 is accelerating qualification protocols for new alloy compositions. Manufacturers are responding by consolidating testing partnerships with specialized biocompatibility laboratories. The Southeast manufacturing corridor is absorbing the largest compliance cost increases.
Hospital supply chain directors are unbundling stent procurement from traditional distributor bundles. Direct manufacturer contracts are displacing GPO-mediated purchasing in high-volume academic centers. This behavioral shift is most pronounced in California and Illinois hospital systems with captive distribution infrastructure.
US Colonic Stents Market Segmentation
Colonic stent procurement patterns diverge sharply across clinical settings and supply chain configurations. Understanding these segment boundaries reveals where margin pools concentrate and which technology platforms command pricing power.
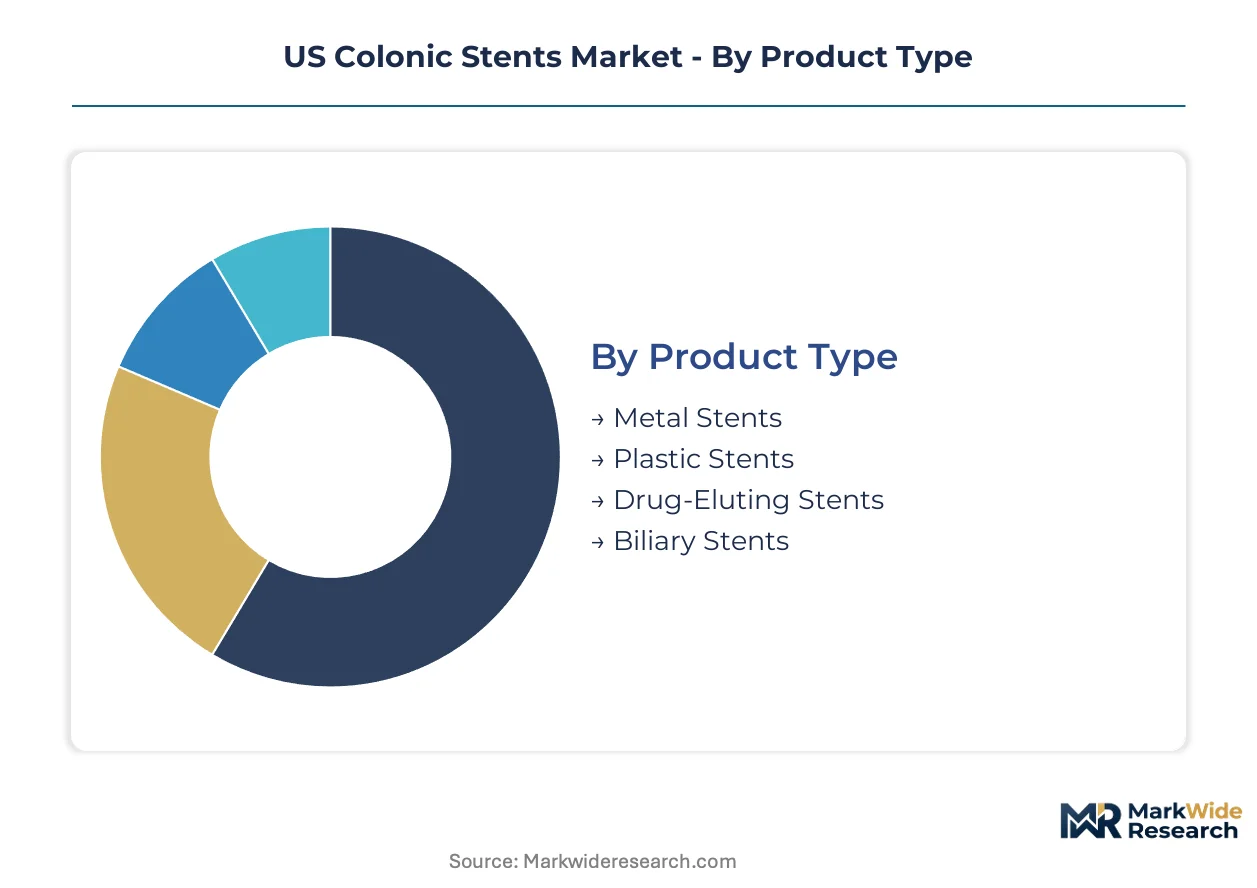
Product Type:
Metal stents capture premium unit economics while plastic alternatives anchor high-volume palliative protocols.
- Metal Stents:Self-expanding nitinol frameworks deliver radial expansion forces of 8-12 Newtons for malignant obstructions. Academic medical centers in Florida and Georgia prioritize these for superior patency duration and reduced reintervention rates.
- Plastic Stents:Polyethylene and polyurethane constructs serve temporary decompression needs. Community hospitals across Texas deploy these for lower-acuity cases where upfront implant cost compression outweighs longevity requirements.
- Drug-Eluting Stents:Paclitaxel-coated nitinol platforms are piloting at Northeast academic centers to extend patency beyond bare metal benchmarks.
- Biliary Stents:Cross-adapted designs address colonic applications with modified deployment mechanics and diameter specifications.
Mature deployment sits with Metal Stents. Newer deployment is concentrated in Drug-Eluting Stents.
End User:
Site-of-care economics reshape volume allocation between inpatient and ambulatory settings.
- Hospitals:Gastroenterology departments perform complex stenting with backup surgical capability. Southeast hospital networks in Florida and Georgia drive procedure concentration through aging Medicare beneficiary density.
- Ambulatory Surgical Centers:Outpatient endoscopic protocols expand under CMS reimbursement code revisions. Dallas-Fort Worth ASCs show under-penetration relative to patient density, creating expansion headroom.
- Clinics:Office-based settings handle stable patient follow-up and stent monitoring without procedural intervention.
- Specialty Centers:Dedicated cancer institutes coordinate stent placement within multimodal oncology pathways.
Procedure concentration tilts toward Hospitals for complex cases. ASCs are gaining share fastest as CMS eligibility broadens.
Distribution Channel:
Channel selection determines margin capture and contract structure flexibility.
- Direct Sales:Manufacturer-to-hospital contracts eliminate intermediary markups on high-value implant purchases. California and Illinois academic centers with captive distribution infrastructure lead this shift.
- Distributors:Traditional GPO-mediated purchasing persists in community hospital networks lacking procurement scale.
- Online Sales:Digital platforms serve smaller clinics and urgent replenishment scenarios with limited contract complexity.
- Third-Party Vendors:Specialized medical device resellers provide regional inventory positioning for just-in-time delivery.
Direct Sales commands the premium tier. Distributors retain volume leadership in consolidated Southeast hospital systems.
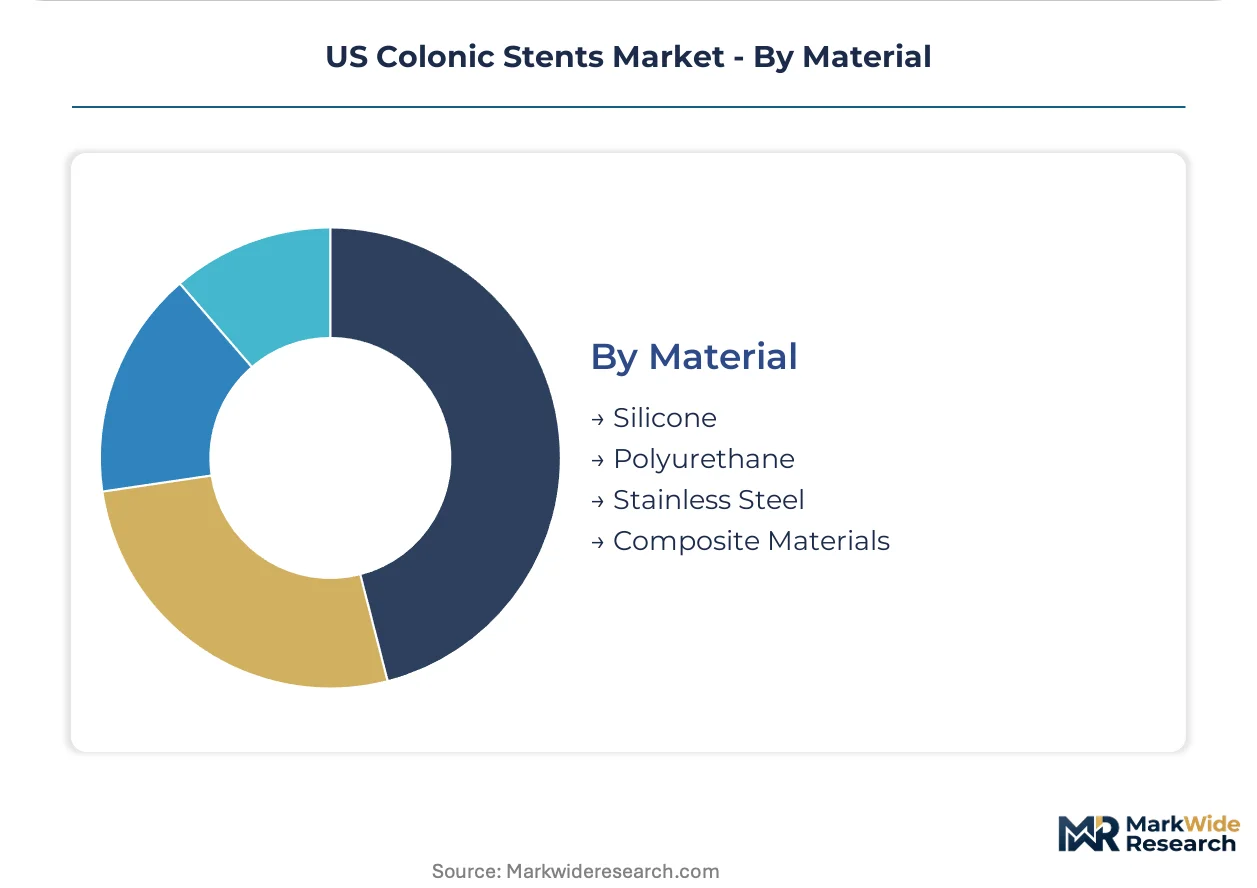
Material:
Material selection balances biocompatibility testing burden against mechanical performance specifications.
- Nitinol:Nickel-titanium alloys dominate self-expanding metal stent construction. FDA's updated ISO 10993-15 corrosion testing is extending qualification timelines for new compositions.
- Stainless Steel:Balloon-expandable platforms serve specific anatomical constraints where precise diameter control matters.
- Silicone:Soft, conformable layers reduce mucosal irritation in plastic stent designs for temporary placement.
- Polyurethane:Enhanced durability versus polyethylene extends functional life in intermediate-term palliative applications.
- Composite Materials:Multi-layer constructs combine structural and surface properties for specialized clinical scenarios.
Nitinol anchors metal stent supply chains. Polyurethane is climbing fastest in plastic stent substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for colonic stenting concentrates in states with aging Medicare populations and expanding hospital networks. Florida and Georgia anchor procedure volumes, while Texas and California present divergent reimbursement and procurement dynamics.
Southeast (Florida and Georgia)
Florida's Medicare beneficiary growth outpaces national averages, driving malignant colorectal obstruction cases through hospital-based gastroenterology departments. CMS maintains reimbursement codes that favor inpatient stenting protocols in this region. Atlanta and Miami hospital networks are consolidating procurement under multi-year sole-source agreements with embedded price step-downs.
Southwest (Texas)
Dallas-Fort Worth ambulatory surgical centers show under-penetration for complex endoscopic interventions relative to patient density. Texas ASC networks are capturing expanded CMS outpatient procedure codes, diverting cases from inpatient settings. Houston's Texas Medical Center anchors academic medical center stent placement volumes with backup surgical capability.
West Coast (California)
California academic medical centers with captive distribution infrastructure are unbundling stent procurement from traditional GPO bundles. FDA's updated 510(k) biocompatibility requirements are extending clearance timelines for manufacturers supplying West Coast hospitals. Los Angeles and San Francisco health systems are pioneering direct manufacturer contracts that bypass distributor markups.
Midwest (Illinois and Ohio)
Chicago hospital networks are consolidating vendor relationships under value-based procurement frameworks. The Physician Payments Sunshine Act shapes commercial transparency obligations for manufacturers operating across Illinois and Ohio. Cleveland Clinic and Northwestern Medicine anchor specialized physician training networks for advanced stent placement techniques.
Northeast (Massachusetts and New York)
Academic medical centers in Boston and New York are piloting drug-eluting colonic stent platforms with paclitaxel-coated nitinol frameworks. FDA's Quality System Regulation elevates compliance costs for manufacturers supplying Northeast hospitals. Memorial Sloan Kettering and Massachusetts General Hospital coordinate stent placement within multimodal oncology pathways.
US Colonic Stents Market Competitive Landscape
Domestic producers anchor the premium tier through vertically integrated nitinol processing and direct hospital distribution; European and Asian specialists hold alternative positions through specialized delivery systems and cost-optimized platforms. The vendor base concentrates around three strategic archetypes: integrated device manufacturers with captive alloy supply, specialized endoscopy platform companies, and diversified medical technology conglomerates. M&A activity targets ambulatory surgical center channel access, while capacity expansion focuses on Southeast manufacturing corridors to offset IRA domestic production incentives.
Within the integrated manufacturer tier, Boston Scientific Corporation and Cook Medical exemplify archetypes built on nitinol processing control and physician training network density. Medtronic occupies a position bridging direct-to-hospital distribution scale with diversified portfolio breadth. Merit Medical Systems and CONMED Corporation represent mid-scale specialists competing through focused endoscopy platform development.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Medtronic |
| CONMED Corporation |
| Merit Medical Systems |
| Olympus Corporation |
| Becton, Dickinson and Company |
| Hobbs Medical |
| Stryker |
| Others |
Pricing and Supply Chain Analysis
Family-owned nitinol wire specialists and private-equity-rolled-up distributors anchor upstream supply, translating concentrated feedstock control into tiered pricing discipline across hospital procurement tiers. Their ownership structures prioritize long-term contract stability over spot-market volatility, reinforcing price step-down mechanisms in multi-year sole-source agreements.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery schedules in just-in-time hospital inventory models. Three-tier pricing structure across premium, standard, and economy levels separates bare metal nitinol stents from drug-eluting platforms and temporary polyethylene alternatives. Price differentiation hinges on FDA 510(k) clearance tier and volume commitment scale. Cost compression in standard metal stents is intensifying because hospital procurement consolidation across Florida and Georgia extracts embedded price reductions.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume academic medical center demand, while distributor-mediated flows serve consolidated Southeast hospital networks lacking captive procurement infrastructure. Domestic nitinol wire supply draws from two primary US metallurgical processors in California and North Carolina. Raw material dependencies center on nickel-titanium alloy feedstock, specialized polymer resins for plastic stents, and paclitaxel coating agents for drug-eluting platforms. Single-source vulnerability in specialized nickel-titanium alloy supply creates concentration risk for domestic stent manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into nitinol wire processing represents the decisive upstream lever in this vertical-integration race, separating margin-sustainable incumbents from distributor-dependent challengers.
For Market Incumbents: Lock in multi-year sole-source agreements with embedded price step-downs across expanding Southeast hospital networks. Prioritize in-house production of specialized nickel-titanium alloys to offset FDA biocompatibility testing cost inflation and defend against plastic stent substitution in community hospital palliative care. For New Entrants and Emerging Players: Ambulatory surgical center networks in Dallas-Fort Worth present the most penetrable geography, given under-indexed complex endoscopic intervention density relative to patient population. Pursue virtual proctoring partnerships with academic medical centers to collapse geographic barriers to specialized stent placement technique certification. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale endoscopy platform specialists with FDA-cleared nitinol stent portfolios in the Southeast manufacturing corridor. Monitor CMS national coverage determination revisions for endoscopic interventions as the critical inflection signal for volume shifts between inpatient and ambulatory settings.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Biocompatibility testing under ISO 10993-15 extends clearance timelines for new nitinol formulations. |
| Hospital System Partnership | Direct manufacturer contracts at California academic centers bypass traditional GPO distributor markups. |
| Reimbursement Strategy | CMS outpatient procedure code expansion diverts stent placement volumes from inpatient to ASC settings. |
| Software Companion Development | Remote physician training platforms collapse geographic barriers to specialized placement technique dissemination. |
| CE Marking Pathway | European regulatory qualification creates export hedge against domestic FDA compliance cost inflation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with interventional gastroenterologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) clearance databases, CMS Medicare claims data, hospital procurement transaction records, and ACGME fellowship placement statistics provided validation layers. Bottom-up procedure volume modeling triangulated against top-down market value estimates.
Product-level granularity captured metal versus plastic versus drug-eluting stent platforms, while end-user segmentation distinguished hospital inpatient, ambulatory surgical center, and specialty cancer institute volumes. Geographic modeling parsed Medicare beneficiary density, hospital network consolidation patterns, and ASC penetration rates. CAGR derivation synthesized historical procedure growth, reimbursement elasticity estimates, and demographic projection inputs across the analysis window.
Caveats apply where FDA biocompatibility guidance revisions, CMS national coverage determinations, or nitinol feedstock supply disruptions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Endoscope Tracking Solutions Market