
 Endoscopic Ultrasound (EUS) Market | 2026-2036
Endoscopic Ultrasound (EUS) Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Ultrasound (EUS) Market Intelligence
Specialized component manufacturing for high-frequency probes in Japan and Germany is pivoting towards modular designs to serve a broader OEM base. Olympus Corporation leverages its dominance in traditional endoscopy to bundle integrated EUS systems. Boston Scientific Corporation competes through its portfolio of specialized needles and biopsy tools for EUS-guided interventions. FUJIFILM Holdings Corporation differentiates with advanced imaging software and processor technology.
Endoscopic ultrasound is a medical procedure combining a flexible endoscope with an ultrasound transducer operating at frequencies typically between 5 and 20 MHz. Its primary purpose is to provide high-resolution imaging of the gastrointestinal tract wall and adjacent organs. Linear EUS systems, essential for fine-needle aspiration, hold a larger market share than radial EUS probes used for staging. The diagnosis of pancreatic disorders and gastrointestinal tumors drives significant procedural volume in academic medical centers and specialized clinics.
Device approval pathways are governed by bodies like the US FDA, Europe's EMA under the Medical Device Regulation (MDR), and Japan's PMDA. These regulations mandate stringent clinical data for pre-market approval and post-market surveillance. Future system design will be shaped by the trade-off between incorporating advanced AI-driven analytics and maintaining cost-effectiveness for adoption in outpatient facilities.
Market Dynamics
The clinical pivot towards minimally invasive diagnostics is the central force shaping the market, enabled by device miniaturization and clearer regulatory pathways. This shift elevates EUS as a primary tool for evaluating complex gastrointestinal and pancreaticobiliary diseases, driving procedural volume.
Growth Catalysts
- Regulatory Pathways:Clearances for new mini-probes by agencies like the FDA and compliance frameworks such as the EU's MDR create defined routes for market entry, stimulating innovation in less invasive device technology.
- Pancreatic Cancer Diagnosis:The critical need for accurate staging and biopsy of pancreatic tumors positions EUS as an essential diagnostic tool, sustaining high procedural volumes in specialized oncology centers. li>Technological Miniaturization: Advances in transducer manufacturing enable smaller, higher-frequency probes, improving imaging resolution and access to narrow anatomical structures like the biliary and pancreatic ducts.
Market Restraints
- High Capital Cost:The substantial initial investment required for a complete EUS system, including the processor and specialized endoscopes, restricts adoption, particularly in smaller hospitals and outpatient clinics.
- Procedural Complexity:Performing EUS procedures requires extensive, specialized training beyond standard endoscopy, creating a skills bottleneck that limits the pool of qualified endosonographers globally.
- Reimbursement Variability:Inconsistent reimbursement policies for EUS-guided therapeutic procedures across different national healthcare systems can disincentivize hospitals from investing in the technology and associated training.
Strategic Opportunities
- AI-Assisted Diagnostics:Integrating artificial intelligence for real-time image analysis offers an opportunity to standardize lesion characterization, improve diagnostic accuracy, and reduce operator-dependent variability in EUS interpretation.
- Therapeutic EUS Expansion:There is significant white space for developing novel EUS-guided therapeutic applications beyond fine-needle aspiration, including targeted drug delivery, radiofrequency ablation, and portal pressure measurement.
- Adoption in Outpatient Settings:Developing lower-cost, more portable EUS systems could enable a procedural shift from inpatient hospital settings to more cost-effective ambulatory surgery centers, especially in the US market.
Industry Challenges
- Data Management and Integration:Integrating high-resolution EUS video and ultrasound data into existing hospital Picture Archiving and Communication Systems (PACS) and Electronic Health Records (EHR) presents significant technical and workflow challenges.
- Complex Device Reprocessing:The intricate design of EUS endoscopes, particularly the delicate ultrasound transducer at the tip, complicates sterilization and reprocessing, posing infection control risks and increasing operational costs.
- Skilled Technician Shortage:A scarcity of biomedical technicians trained to service and repair complex EUS systems can lead to prolonged equipment downtime, impacting procedural capacity in high-volume gastroenterology departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Ultrasound (EUS) Market |
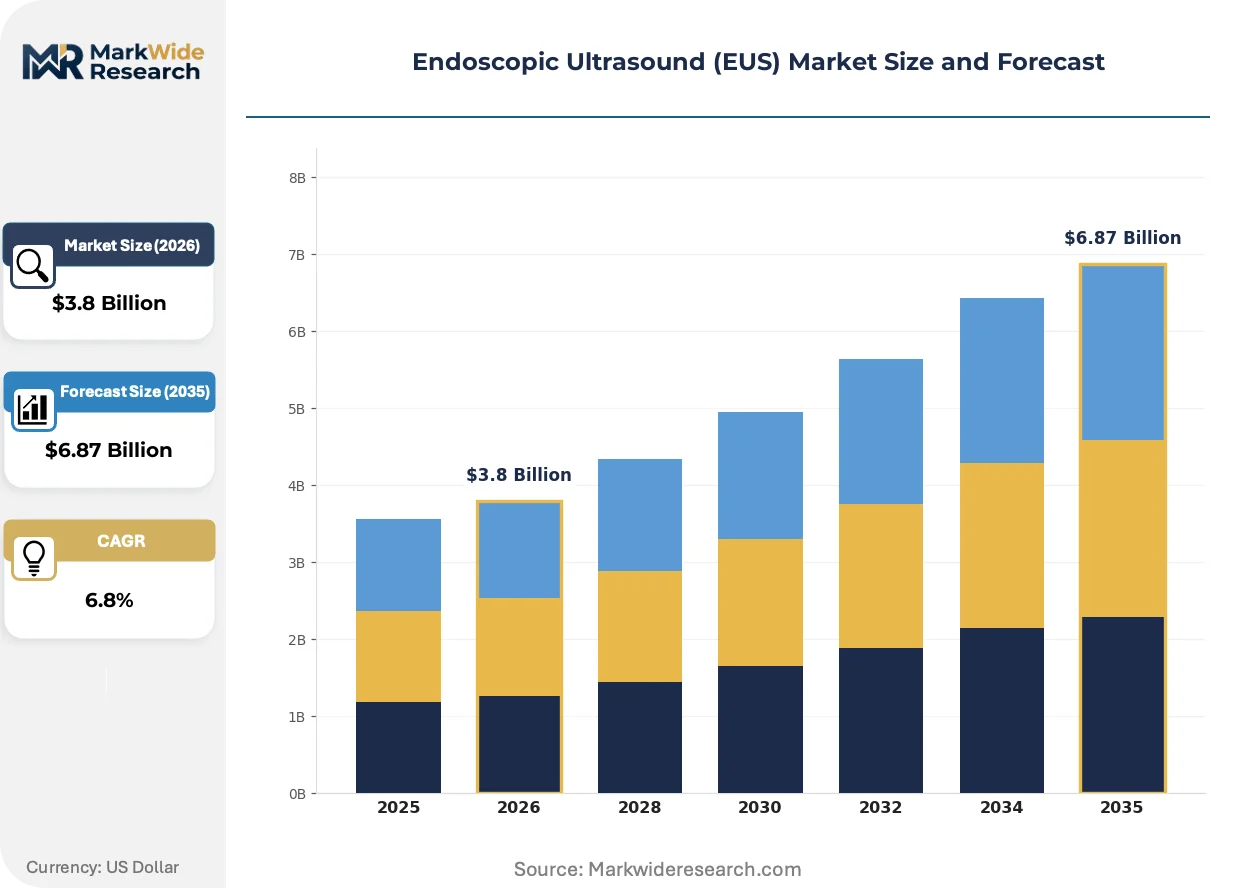
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial EUS, Linear EUS, Contrast-Enhanced EUS, Mini-Probe EUS, High-Frequency EUS Application: Pancreatic Disorders, Gastrointestinal Tumors, Biliary Diseases, Submucosal Lesions, Mediastinal Staging End User: Specialized Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Academic Medical Centers, Outpatient Facilities Deployment: Inpatient Hospitals, Outpatient Clinics, Mobile Units, Telemedicine Setup, Research Institutions |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Medtronic, FUJIFILM Holdings Corporation, Canon Medical Systems Corporation, CONMED Corporation, Steris, Cook Medical, SonoScape Medical Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Ultrasound (EUS) Market Strategic Shifts & Innovations
The convergence of advanced imaging, interventional capabilities, and data analytics transforms endoscopic ultrasound from a purely diagnostic modality. This evolution creates a platform for real-time, image-guided therapeutic interventions within the gastrointestinal tract and adjacent organs.
Contrast-enhanced harmonic EUS (CH-EUS) uses microbubble agents to visualize microvasculature in lesions. Academic medical centers adopt it for differential diagnosis of pancreatic masses. This enhanced visualization capability is rewriting the standards for characterizing solid pancreatic lesions, often reducing the need for immediate invasive biopsy.
Stricter requirements under the European Union's Medical Device Regulation (MDR) impact clinical evidence and post-market surveillance for high-risk devices. This results in longer development timelines and higher compliance costs for manufacturers. Smaller innovators are most affected, struggling to generate the extensive data required for CE marking.
Hospital purchasing is shifting from standalone devices to integrated system bundles that include processors, scopes, and consumables. This model disrupts the traditional practice of buying components from multiple vendors. The trend is most visible in large US hospital networks, where central procurement offices seek to standardize technology and streamline service contracts.
Endoscopic Ultrasound (EUS) Market Segmentation
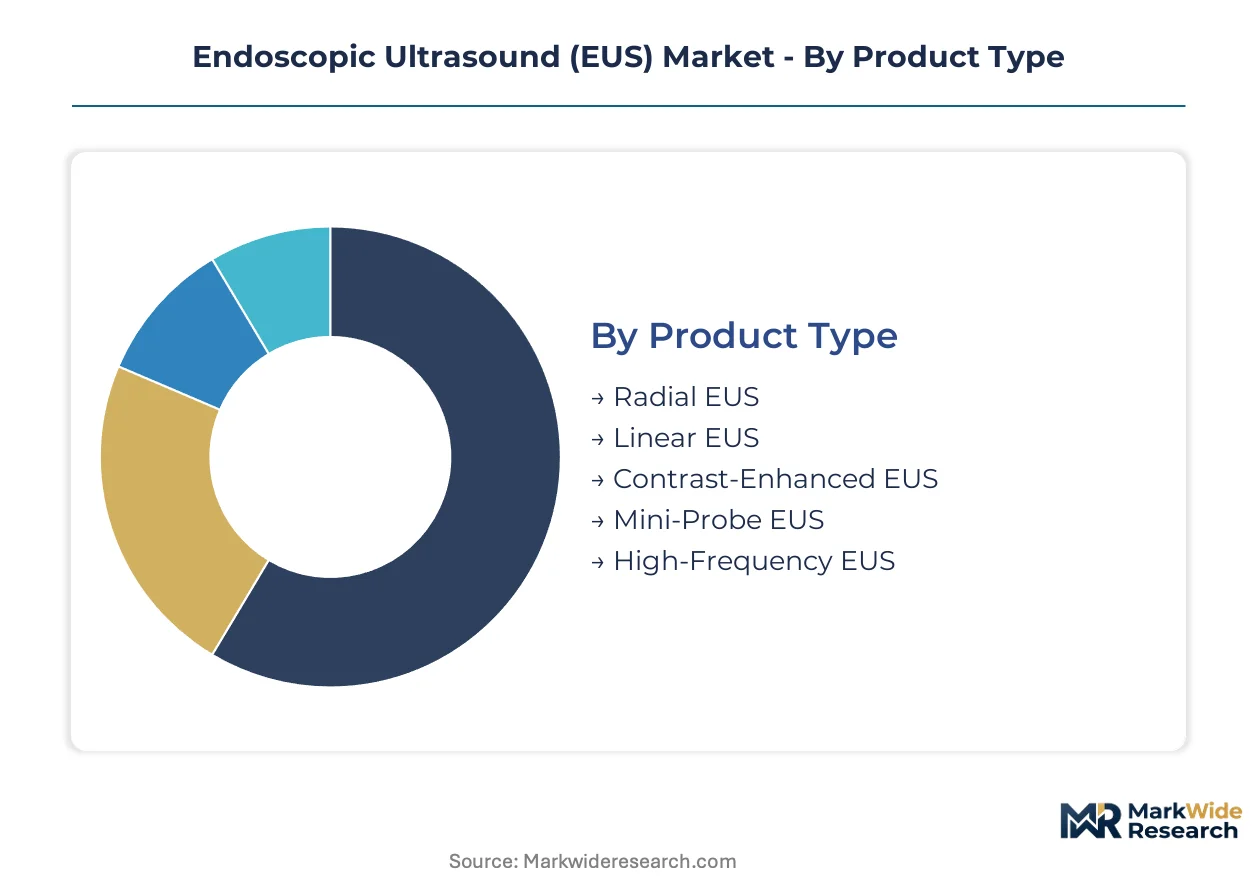
The Endoscopic Ultrasound market segmentation reflects the diverse technological advancements and clinical applications driving procedural adoption. These distinct categories delineate the specialized devices, target conditions, and healthcare settings integral to EUS delivery. Understanding these segments clarifies the varying demands and growth trajectories across the EUS landscape.
Product Type:
The product type segmentation highlights the customization versus standardization spectrum in EUS device design, addressing specific clinical needs from basic imaging to complex interventions.
- Linear EUS:These systems are crucial for fine-needle aspiration procedures, offering real-time guidance for biopsy collection. They hold a larger market share due to their utility in tissue sampling for diagnostic purposes.
- Mini-Probe EUS:Mini-probe devices facilitate less invasive procedures, particularly in narrow anatomical spaces like the biliary and pancreatic ducts. Regulatory clearances by agencies like the FDA support their expanding use in diagnostic evaluations.
- Radial EUS:Radial probes are primarily used for staging gastrointestinal tumors, providing a 360-degree cross-sectional view of the GI tract wall.
- Contrast-Enhanced EUS:This technology employs microbubble agents to enhance visualization of microvasculature, aiding in the differential diagnosis of pancreatic masses.
- High-Frequency EUS:High-frequency transducers offer superior resolution for superficial lesions, enabling detailed imaging of the gastrointestinal tract layers.
Leading the category by volume: Linear EUS. Growing fastest: Mini-Probe EUS.
Application:
This application segment delineates EUS utilization based on the criticality and complexity of the targeted disease states requiring high-resolution internal imaging.
- Pancreatic Disorders:EUS is a primary tool for the diagnostic evaluation and staging of pancreatic disorders, including pancreatitis and cystic lesions. Its high-resolution imaging capability is critical for accurate tumor characterization and biopsy.
- Gastrointestinal Tumors:EUS provides precise staging of gastrointestinal tumors by visualizing the depth of invasion and regional lymph node involvement. This application drives substantial procedural volume in specialized oncology centers globally.
- Biliary Diseases:EUS diagnoses various biliary diseases, including choledocholithiasis and strictures, offering detailed visualization of the bile ducts.
- Submucosal Lesions:This application focuses on characterizing and staging lesions originating from the submucosal layer of the gastrointestinal tract.
- Mediastinal Staging:EUS is employed for staging lung cancer and evaluating mediastinal lymph nodes, providing a less invasive alternative to surgical staging.
Pancreatic Disorders represent the largest segment in EUS applications. Gastrointestinal Tumors exhibit significant procedural growth.
End User:
The end-user classification reflects the varied infrastructure and specialized expertise required for EUS procedures across different healthcare providers.
- Academic Medical Centers:These institutions are central to EUS adoption, performing high volumes of complex diagnostic and therapeutic procedures. They often lead in research and training for advanced endosonography techniques.
- Specialized Clinics:Specialized clinics, particularly those focused on gastroenterology or oncology, offer targeted EUS services for specific disease states. These clinics manage a significant portion of diagnostic EUS cases.
- Diagnostic Centers:Diagnostic centers utilize EUS for accurate imaging and tissue sampling, often serving as referral hubs for less complex cases.
- Ambulatory Surgical Centers:ASCs are increasingly adopting EUS for outpatient procedures, driven by cost-effectiveness and patient convenience in the US market.
- Outpatient Facilities:These facilities provide accessible EUS services for routine diagnostic evaluations, supporting a shift from inpatient hospital settings.
Academic Medical Centers generate the highest EUS procedural volume. Outpatient Facilities are expanding their EUS service offerings.
Deployment:
Deployment models for EUS systems vary significantly, reflecting the diverse patient care settings and logistical requirements for delivering specialized endoscopic services.
- Inpatient Hospitals:Inpatient hospitals represent the traditional and largest deployment setting for EUS, handling both routine and complex procedures. They possess the comprehensive infrastructure and support staff for advanced interventions.
- Outpatient Clinics:The shift towards outpatient care is increasing EUS deployment in specialized clinics and ambulatory settings. These facilities focus on efficient, less complex diagnostic procedures.
- Mobile Units:Mobile EUS units provide diagnostic capabilities to underserved regions or smaller facilities, improving access to specialized imaging.
- Telemedicine Setup:Telemedicine integration supports remote consultation and image review for EUS, enhancing diagnostic collaboration across geographically dispersed experts.
- Research Institutions:Research institutions deploy EUS systems for clinical trials, device development, and advancing novel diagnostic and therapeutic applications.
Inpatient Hospitals remain the dominant deployment setting. Outpatient Clinics show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan, a hub for advanced medical device manufacturing, anchors significant demand for endoscopic ultrasound systems. Its sophisticated healthcare infrastructure supports early adoption of cutting-edge diagnostic technologies. This market expansion is further driven by a focus on precision medicine and an aging population requiring advanced diagnostic tools for chronic diseases.
Japan
Demand for EUS in Japan stems from high prevalence of gastrointestinal and pancreatic disorders, emphasizing early disease detection. The PMDA ensures rigorous regulatory oversight for new EUS device approvals. Tokyo's medical technology cluster drives innovation in high-frequency probes and integrated systems.
United States
The United States market sees robust demand for EUS due to its large patient population and advanced healthcare spending. The FDA provides clear pathways for new device clearances, especially for minimally invasive EUS technologies. Major academic medical centers in Boston lead EUS research and clinical application.
Germany
Germany's EUS market is propelled by a strong healthcare system and a high incidence of pancreatic and gastrointestinal cancers. European Medical Device Regulation (MDR) compliance shapes device development and market entry. Munich's biomedical sector contributes to specialized component manufacturing for EUS probes.
United Kingdom
The United Kingdom's EUS adoption increases, driven by NHS initiatives to improve cancer diagnosis and treatment pathways. The MHRA oversees EUS device safety and efficacy within the UK. London's specialized gastroenterology clinics expand EUS service offerings for complex cases.
China
China's EUS market expands rapidly, fueled by increasing healthcare expenditure and a rising burden of gastrointestinal diseases. The NMPA streamlines approval processes for advanced medical devices. Shanghai's burgeoning medical device industry invests in local production and R&D for EUS technologies.
Endoscopic Ultrasound (EUS) Market Key Industry Players
Global majors compete with regional champions across the spectrum of EUS device innovation and market reach. The market structure is moderately consolidated at the high-end, with several specialized players serving niche segments. Strategic archetypes include integrated system providers, specialized component manufacturers, and intervention tool developers. Dominant competitive moves involve strategic partnerships for technology co-development and portfolio diversification to capture broader clinical applications.
Integrated system providers, such as Olympus Corporation, exemplify companies offering comprehensive EUS platforms that bundle processors, scopes, and consumables. FUJIFILM Holdings Corporation represents another major player, differentiating with advanced imaging software and processor technology to enhance diagnostic capabilities. Boston Scientific Corporation occupies a distinct position, focusing on specialized needles and biopsy tools crucial for EUS-guided interventions, thereby complementing the broader imaging systems. These companies collectively drive innovation across the EUS ecosystem, from diagnostic visualization to therapeutic applications.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Medtronic |
| FUJIFILM Holdings Corporation |
| Canon Medical Systems Corporation |
| CONMED Corporation |
| Steris |
| Cook Medical |
| SonoScape Medical Corp. |
| Others |
Cost & Logistics Intelligence
The performance gap between integrated EUS systems and specialized mini-probes shapes both pricing strategies and component sourcing patterns. Pricing power concentrates with manufacturers offering comprehensive solutions, while component supply chains remain globalized for high-frequency transducers.
Pricing Analysis
Warranty and service bundling significantly influence the perceived value of EUS systems. Integrated system bundles often operate on a contract-based model, incorporating processors, scopes, and consumables. Advanced imaging software and specialized high-frequency probes drive premium pricing, reflecting their enhanced diagnostic capabilities. Cost compression in outpatient facilities is intensifying due to budget constraints, seeking lower-cost, portable EUS systems. Academic medical centers are less price-sensitive for cutting-edge technology, while outpatient facilities prioritize cost-effectiveness and operational efficiency.
Supply Chain Analysis
Reverse logistics for EUS systems, particularly for delicate endoscopes, involves complex reprocessing and refurbishment flows. Specialized component manufacturing for high-frequency probes concentrates in Japan and Germany. The market sources critical inputs like advanced imaging processors and high-frequency transducers from a limited vendor base. Single-source vulnerability for these specialized micro-components poses a structural risk for system integrators. Distribution primarily occurs through direct sales forces to academic medical centers and large hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EUS market is in a technology-transition phase, with contrast-enhanced harmonic EUS replacing traditional methods for complex lesion characterization.
For Market Incumbents: Anticipate the continued shift towards integrated system bundles by deepening vertical integration into specialized component manufacturing. Invest heavily in AI-driven analytics to standardize lesion characterization, countering operator-dependent variability. Focus R&D on next-generation mini-probes to mitigate threats from emerging specialized device developers. Navigate increasingly stringent regulatory frameworks like Europe's MDR through robust clinical data generation and post-market surveillance.
For New Entrants and Emerging Players: Specialized distributors offer new entrants a pathway to penetrate the EUS market by focusing on niche applications. Target the white space in therapeutic EUS, developing novel tools for targeted drug delivery or radiofrequency ablation. Pursue the underpenetrated outpatient facilities segment in the US market with lower-cost, portable EUS systems. A go-to-market angle emphasizing cost-effectiveness and simplified workflows will resonate with these new end-users.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap innovators given the demand for less invasive, AI-assisted diagnostic solutions. This market demonstrates strong long-term viability over the next decade, fueled by an aging population and rising chronic disease burden. Focus acquisition strategies on firms developing advanced imaging software or novel EUS-guided therapeutic devices. The signal to watch is the expansion of favorable reimbursement policies for therapeutic EUS procedures across major healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Integration for Diagnostics | Improves diagnostic accuracy and reduces operator variability in EUS interpretation. |
| Mini-Probe Device Development | Facilitates less invasive EUS procedures, expanding access to narrow anatomical spaces. |
| Therapeutic EUS Tool Expansion | Unlocks new revenue streams beyond diagnosis, including targeted drug delivery. |
| Outpatient System Localization | Enables cost-effective EUS adoption in ambulatory surgery centers, particularly in the US. |
| Regulatory Compliance Investment | Ensures market access and accelerates new device approvals under frameworks like the EU MDR. |
Research Approach
FDA filings, EMA submissions, and PMDA reports formed the secondary backbone for market sizing and trend identification. This was complemented by primary interviews with endosonographers, hospital purchasing committees, and R&D directors at device manufacturers. Data triangulation occurred through both bottom-up assessments of procedural volumes and top-down analyses of manufacturer revenues. This comprehensive approach ensured robust validation of market insights.
A bottom-up analytical framework projected market volume by procedural type and end-user facility. This was validated against top-down revenue estimates from major EUS system providers over the projection horizon. Segmentation dimensions included product type, application, end user, and deployment model. Compound annual growth rates incorporated historical trends, projected technological advancements, and the incidence of pancreatic disorders.
Several conditions sit outside the modeled scope, including specific regional reimbursement policy changes and unforeseen shifts in healthcare infrastructure development. Forecasts reflect assumptions regarding regulatory stability and consistent adoption rates for new EUS technologies. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Single Use Bronchoscopes Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Global Colonoscopes Market
Endoscopy
North America Endoscopy Devices Market