
 Video Laryngoscope Market | 2026-2036
Video Laryngoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Video Laryngoscope Market Intelligence
The ISO 13485 quality management standard is rotating market access towards manufacturers with documented design, production, and post-market surveillance controls. Medtronic leverages its extensive hospital distribution network to secure large-volume contracts for its diverse portfolio. KARL STORZ SE & Co. KG differentiates through its focus on high-definition surgical video laryngoscopes for complex airway procedures. Ambu A/S leads in the single-use disposable segment, which directly addresses hospital-acquired infection control concerns.
A video laryngoscope is a medical instrument used to obtain an indirect view of the vocal cords and glottis, facilitating safer tracheal intubation. These devices integrate a miniature camera, typically a CMOS sensor, at the blade's tip, transmitting live video to an attached or separate high-resolution digital display. The product category experiencing the most rapid expansion is disposable video laryngoscopes, driven by stringent hospital infection control protocols to minimize cross-contamination. While hospitals constitute the largest end-user segment, demand from prehospital settings for emergency intubation is expanding rapidly.
Regulatory frameworks like the US FDA's 510(k) pathway and the EU's Medical Device Regulation (MDR) dictate the extensive clinical evidence required for market entry. In parallel, Japan's Pharmaceuticals and Medical Devices Agency (PMDA) enforces strict post-market surveillance, influencing product life cycle management and recall procedures. Future procurement decisions for healthcare providers will balance the total cost of ownership for reusable systems against the clear infection control advantages of single-use devices.
Market Dynamics
The market's core tension lies between the push for single-use, disposable devices to mitigate hospital-acquired infections and the economic pressure on healthcare systems to manage the total cost of ownership associated with reusable video laryngoscope systems.
Growth Catalysts
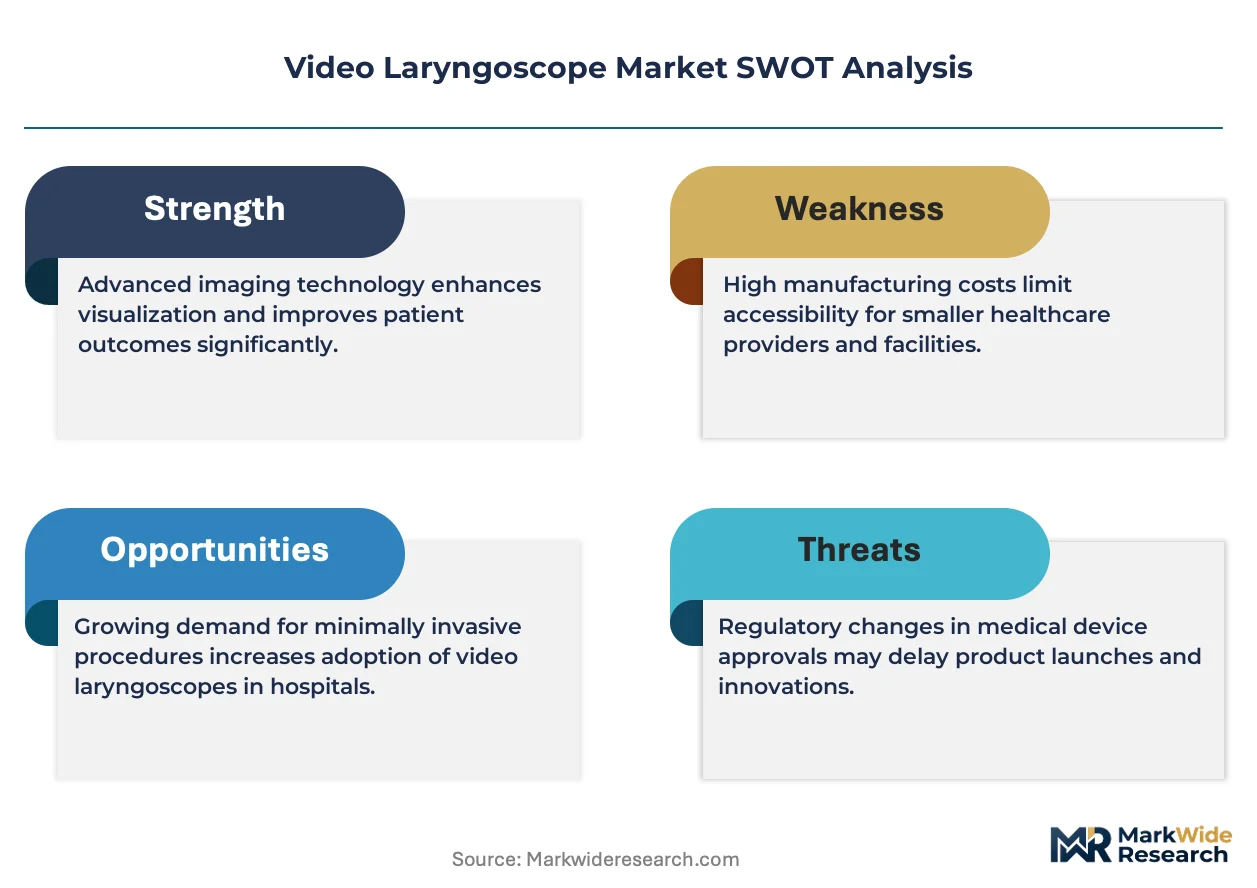
- Regulatory Harmonization:The European Union's Medical Device Regulation (MDR) is elevating clinical evidence requirements, favoring manufacturers with strong quality management systems and documented device performance.
- Prehospital Care Expansion:Uptake by ambulance services and emergency medical teams for out-of-hospital airway management is creating new demand outside traditional operating room environments.
- Sensor Technology Advancement:The miniaturization of high-resolution CMOS image sensors enables clearer visualization of the glottis, improving intubation success rates in patients with difficult airways.
Market Restraints
- High Initial Capital Cost:The significant upfront investment required for reusable video laryngoscope systems, including monitors and processing units, can be a barrier for smaller clinics or budget-constrained hospitals.
- Viable Low-Cost Alternatives:Traditional direct laryngoscopy remains a widely practiced and inexpensive technique, limiting video device penetration in resource-limited healthcare settings globally.
- Durability in Harsh Environments:Devices used in prehospital settings face challenges related to battery life, screen glare in bright sunlight, and resistance to damage from drops or extreme temperatures.
Strategic Opportunities
- Emerging Market Penetration:There is significant opportunity in developing healthcare systems like India and Brazil, where investment in emergency response infrastructure is increasing demand for advanced airway tools.
- AI-Assisted Guidance:Integrating artificial intelligence software to identify anatomical landmarks in real-time can lower the skill threshold for successful intubation, aiding less-experienced medical personnel.
- Veterinary Medicine Applications:Adapting video laryngoscope technology for specialized veterinary use, particularly for large animal and zoological medicine, represents an untapped adjacent market.
Industry Challenges
- Standardized User Training:A lack of uniform training protocols across different healthcare systems for paramedics and emergency staff can lead to inconsistent device proficiency and suboptimal patient outcomes.
- Complex Compliance Pathways:Navigating the distinct and rigorous post-market surveillance requirements mandated by regulatory bodies like Japan's PMDA presents a continuous compliance burden for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Laryngoscope Market |
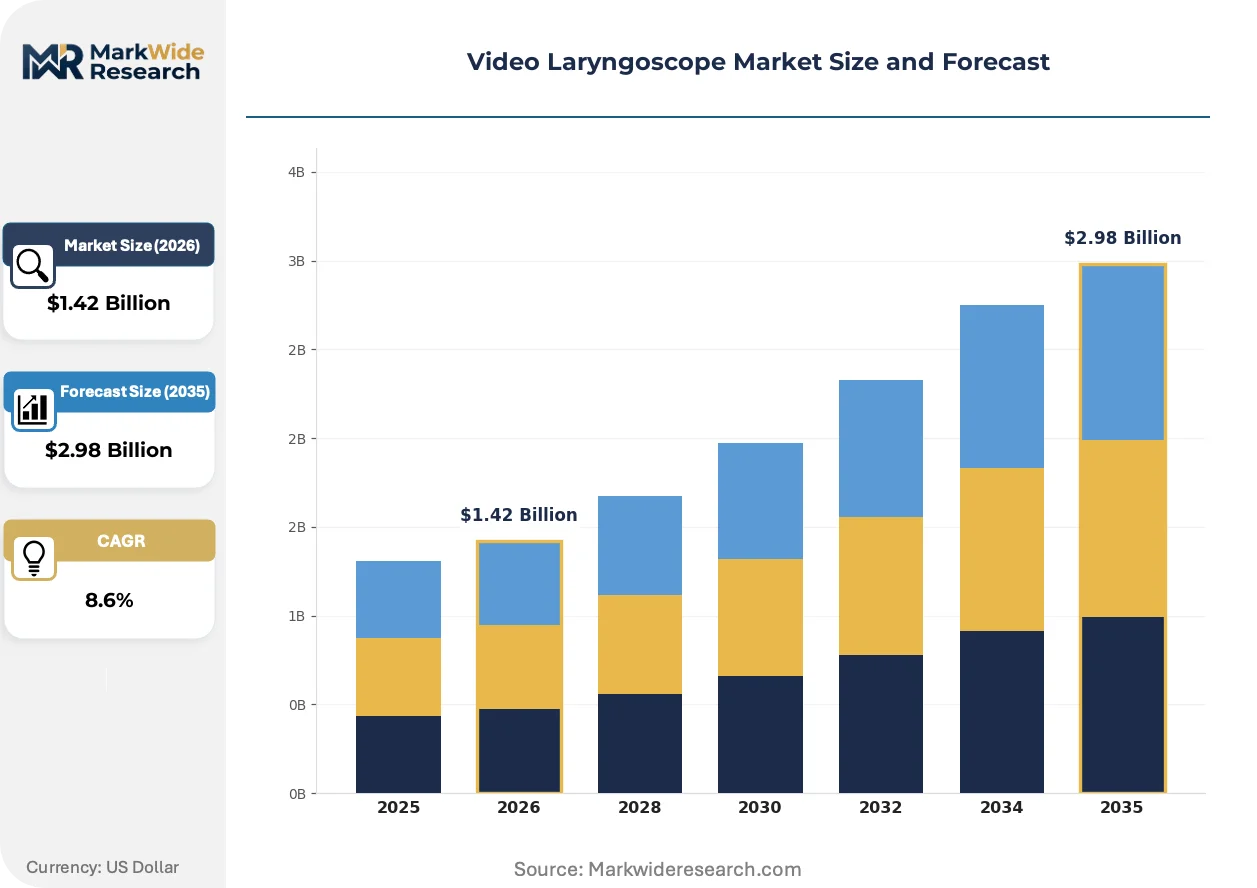
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Video Laryngoscopes, Portable Video Laryngoscopes, Disposable Video Laryngoscopes, Pediatric Video Laryngoscopes, Surgical Video Laryngoscopes Technology: CCD Camera, CMOS Sensor, Fiber Optic, Digital Display, Wireless Transmission Application: Emergency Intubation, Operating Room Procedures, Intensive Care Units, Prehospital Settings, Anesthesia Administration End User: Hospitals, Ambulatory Surgical Centers, Trauma Centers, Ambulance Services, Medical Training Facilities |
| Companies Covered | KARL STORZ SE & Co. KG, Nihon Kohden Corporation, Verathon Inc., Salter Labs, Teleflex Incorporated, Medtronic, Olympus Corporation, Prodol Meditec, Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Laryngoscope Market Strategic Shifts & Innovations
Device design and hospital workflow standards are being fundamentally altered by the dual pressures of infection control mandates and the integration of digital visualization technologies. This evolution prioritizes procedural safety and evidence-based equipment selection over traditional purchasing habits.
Channeled video laryngoscope blades integrate a guide path for the endotracheal tube. Emergency departments and paramedic services are adopting these designs to improve first-pass intubation success rates. This integrated functionality is displacing the conventional technique requiring a separate malleable stylet, streamlining the critical airway management workflow.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence. This regulation forces manufacturers to generate more extensive clinical data and maintain robust post-market surveillance systems. The impact is most significant for companies selling into EU member states like Germany, which must align product documentation with elevated ISO 13485 standards.
Hospital value analysis committees increasingly scrutinize the total cost of ownership for reusable systems against per-procedure costs of disposables. This shift challenges the upfront capital sales model for display monitors and reusable blades. The trend is most prominent in large US hospital networks, where procurement favors bundled contracts for single-use components.
Video Laryngoscope Market Segmentation
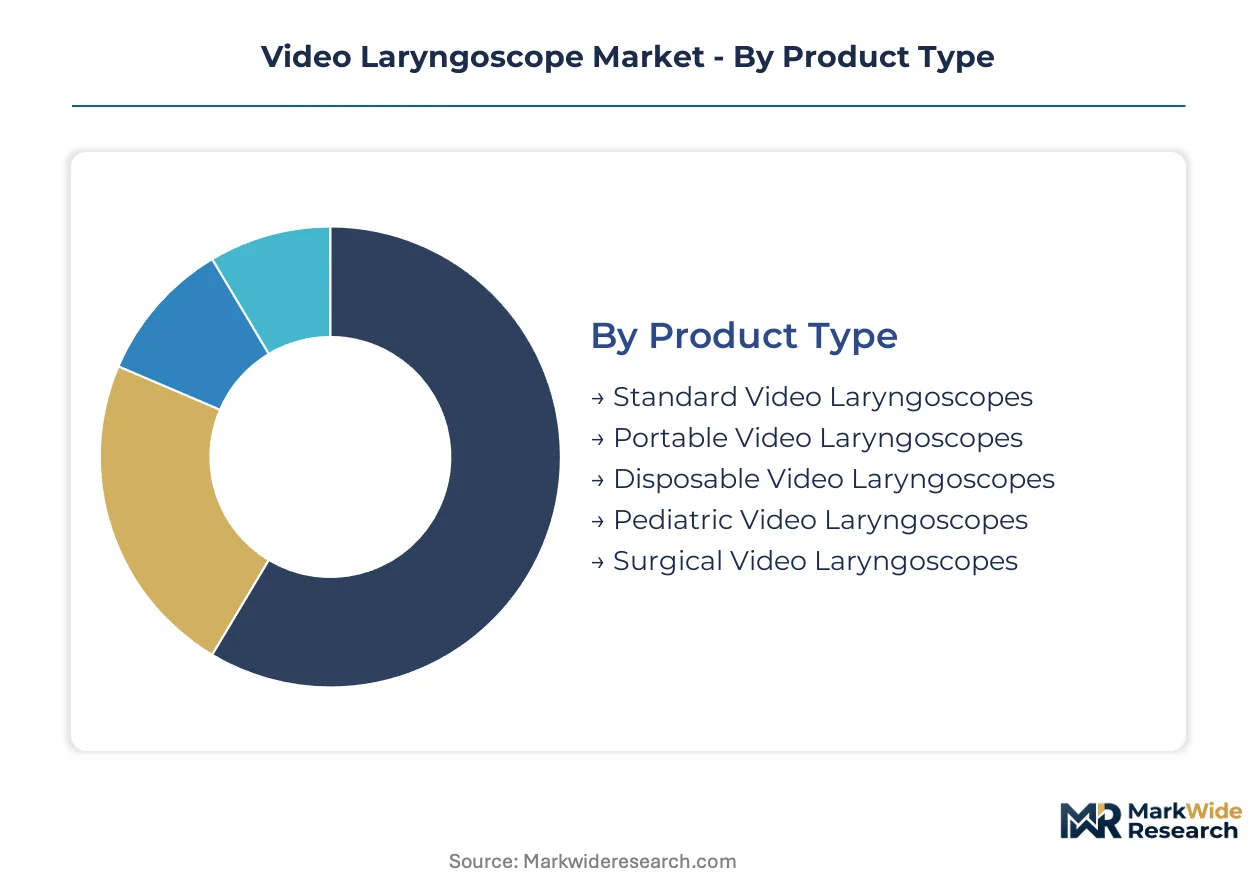
Understanding the distinct segments within the video laryngoscope market allows manufacturers to tailor product development and market entry strategies effectively. This segmentation highlights the diverse needs of healthcare providers, from emergency medical services to specialized hospital departments, influencing procurement decisions and technological priorities.
Product Type:
The distribution channels for video laryngoscopes vary significantly by product type, with some flowing through large medical distributors and others requiring specialized sales teams for clinical integration.
- Disposable Video Laryngoscopes:These single-use devices feature an integrated camera and blade, designed for one-time patient contact to prevent cross-contamination. Demand for these disposables is accelerating in hospitals across Germany and the United States due to stringent infection control protocols and the rising incidence of hospital-acquired infections.
- Surgical Video Laryngoscopes:Engineered for complex airway management, these high-definition devices offer superior visualization for intricate surgical procedures. KARL STORZ SE & Co. KG focuses on this segment, catering to specialized operating room environments where precision is paramount.
- Standard Video Laryngoscopes:These reusable systems typically consist of a durable handle, interchangeable blades, and a separate monitor for visualization.
- Portable Video Laryngoscopes:Designed for mobility, these compact units are crucial for prehospital and emergency medical services, often featuring integrated screens.
- Pediatric Video Laryngoscopes:Specifically scaled for smaller anatomy, these devices are essential for safe intubation in infants and children.
Standard Video Laryngoscopes dominate the installed base. Disposable Video Laryngoscopes are where expansion concentrates.
Technology:
The choice of underlying technology often dictates the device's application, with specific sensor types optimized for clarity in demanding clinical scenarios or for cost-effectiveness.
- CMOS Sensor:Complementary Metal-Oxide-Semiconductor sensors enable miniaturization and high-resolution image capture, crucial for clear visualization of the glottis. Advanced CMOS technology improves intubation success rates in patients with difficult airways, particularly in emergency departments.
- Digital Display:These high-resolution screens receive live video feeds from the laryngoscope's camera, providing a clear and magnified view for the clinician. The quality of digital displays directly impacts procedural safety and training effectiveness in medical training facilities.
- CCD Camera:Charge-Coupled Device cameras offer reliable image quality and are often found in established video laryngoscope systems.
- Wireless Transmission:This technology allows for cable-free video transfer to a monitor, enhancing mobility and reducing clutter in busy clinical settings.
- Fiber Optic:Fiber optic technology provides illumination and image transmission, particularly in older or more specialized laryngoscope designs.
CMOS Sensor technology is critical for advanced visualization. Wireless Transmission is gaining share fastest.
Application:
The specific clinical application of video laryngoscopes influences design requirements, from ruggedness for prehospital use to precision for operating room procedures.
- Prehospital Settings:Video laryngoscopes used by ambulance services and emergency medical teams require robust design, extended battery life, and clear visibility in varying light conditions. Uptake in these settings, including in countries with advanced emergency response like Germany, is creating new demand outside traditional hospital environments.
- Emergency Intubation:These applications demand rapid deployment and high first-pass success rates, often in critically ill patients where airway management is time-sensitive. AI-assisted guidance could further lower the skill threshold for successful intubation in emergency scenarios.
- Operating Room Procedures:Surgical teams utilize video laryngoscopes for routine intubation and complex airway management during anesthesia administration.
- Intensive Care Units:ICU staff rely on video laryngoscopes for managing patient airways, especially for prolonged ventilation or difficult intubations at the bedside.
- Anesthesia Administration:Anesthesiologists use these devices to ensure precise and safe tracheal intubation before surgical procedures.
Operating Room Procedures represent a foundational application. Prehospital Settings are expanding most quickly.
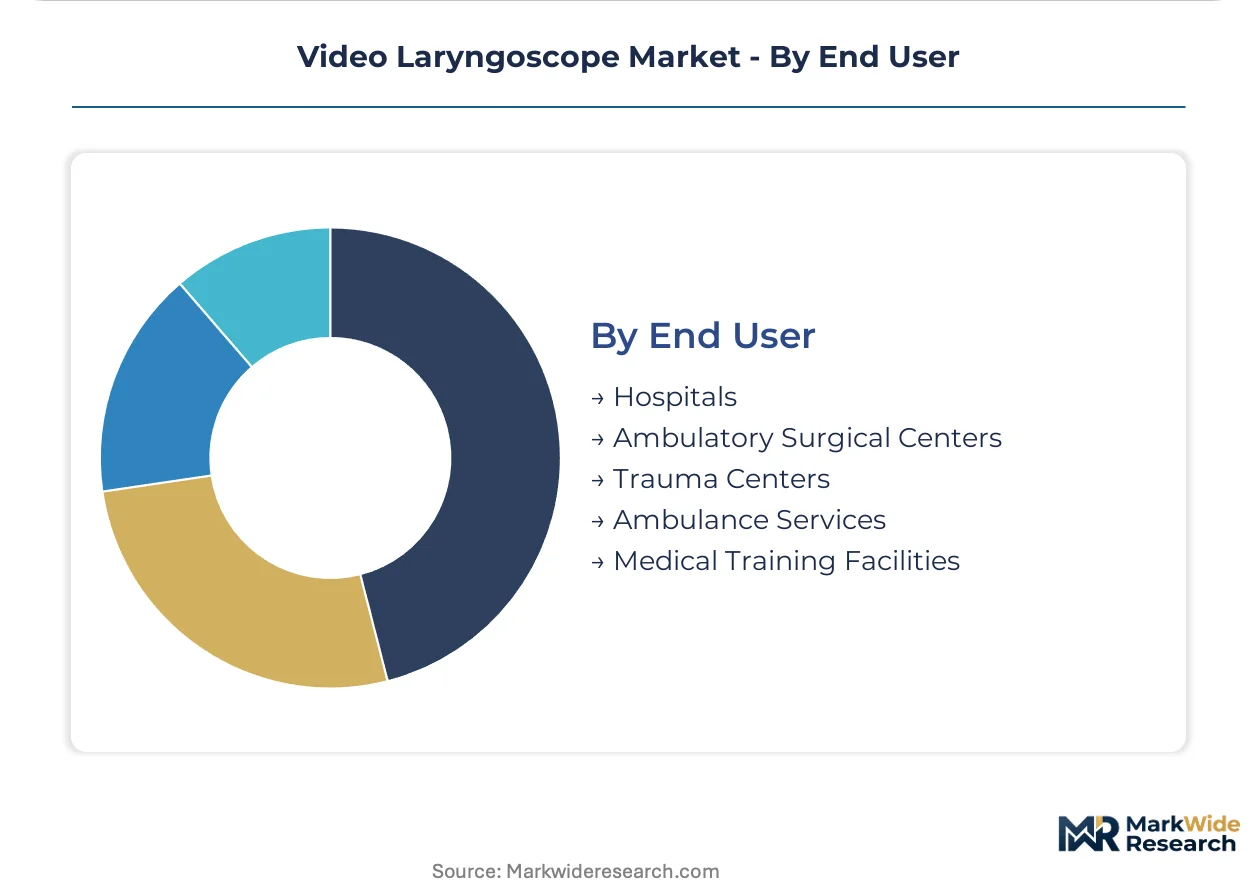
End User:
Different end-user segments exhibit distinct purchasing patterns and requirements, influencing manufacturers' sales and marketing strategies.
- Hospitals:As the largest end-user segment, hospitals procure a wide range of video laryngoscopes for various departments, driven by infection control and patient safety mandates. Large US hospital networks increasingly favor bundled contracts for single-use components.
- Ambulance Services:These services require portable, durable video laryngoscopes for out-of-hospital airway management, prioritizing ease of use and reliability in emergency situations. Uptake by ambulance services is expanding device requirements beyond traditional operating rooms.
- Trauma Centers:These specialized facilities demand robust and highly effective video laryngoscopes for critical and often challenging intubations in trauma patients.
- Medical Training Facilities:Institutions use video laryngoscopes for educating medical students and residents on advanced airway management techniques.
- Ambulatory Surgical Centers:ASCs utilize video laryngoscopes for elective procedures requiring intubation, balancing cost-effectiveness with patient safety.
Hospitals represent the most mature end-user segment. Ambulance Services demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetype concentration for video laryngoscopes centers on high-income healthcare systems prioritizing patient safety and rapidly expanding emergency medical services. Investment in advanced medical infrastructure influences procurement decisions across different geographies. Regulatory frameworks significantly shape market access and product development.
United States
Stringent infection control protocols and the presence of large hospital networks drive demand for disposable video laryngoscopes. The US FDA's 510(k) pathway dictates market entry and product clearances for medical devices. Boston's robust medical device cluster continues to innovate in digital visualization technologies for airway management.
Germany
Germany's advanced healthcare infrastructure and emphasis on rapid emergency response fuel the uptake of video laryngoscopes in prehospital settings. The European Union's Medical Device Regulation (MDR) elevates clinical evidence requirements, impacting product design. Bavarian medical technology firms focus on high-definition surgical devices for complex procedures.
Japan
An aging population and a strong emphasis on patient safety in surgical and emergency care contribute to steady demand for advanced visualization tools. Japan's PMDA enforces strict post-market surveillance, influencing product lifecycle management and recall procedures. Tokyo's medical equipment manufacturers integrate advanced CMOS sensors for superior imaging.
India
Increasing investment in emergency response infrastructure and expanding healthcare access in urban centers create new demand for portable video laryngoscopes. The BIS standards guide local manufacturing and import requirements for medical devices. Bengaluru's medical device startups adapt cost-effective solutions for diverse clinical environments.
Brazil
Growing public and private healthcare investment expands the installed base for video laryngoscopes, particularly in critical care and emergency departments. ANVISA dictates medical device registration and clinical trial requirements for market approval. São Paulo's healthcare technology sector sees rising procurement for single-use devices to enhance infection control.
Video Laryngoscope Market Key Industry Players
Player mix skews toward established medical technology conglomerates alongside specialized innovators in the video laryngoscope market. The market exhibits a tiered structure, with large diversified players competing against focused single-use device manufacturers. Strategic archetypes include global healthcare solution providers, niche high-definition surgical instrument specialists, and disposable medical product leaders. Portfolio diversification and strategic partnerships are dominant competitive moves.
Within the established diversified medical device segment, Medtronic leverages its extensive hospital distribution network for broad market reach. KARL STORZ SE & Co. KG, a German company, exemplifies specialized surgical visualization providers with its focus on high-definition systems for complex airway procedures. Ambu A/S, a Danish firm, occupies a leading position among single-use disposable innovators, directly addressing hospital-acquired infection concerns.
| Leading Market Players |
|---|
| KARL STORZ SE & Co. KG |
| Nihon Kohden Corporation |
| Verathon Inc. |
| Salter Labs |
| Teleflex Incorporated |
| Medtronic |
| Olympus Corporation |
| Prodol Meditec |
| Ambu A/S |
| Others |
Cost & Logistics Intelligence
Six-month lead times for high-definition CMOS sensors directly influence video laryngoscope manufacturing cycles and pricing stability. This supply constraint grants significant pricing power to component suppliers and impacts final product costs for hospitals.
Pricing Analysis
Cost-plus contracts, often indexed to raw material prices for medical-grade plastics and specialized optical components, govern much of the video laryngoscope market. Pricing stratifies across premium, standard, and economy tiers based on visualization quality (e.g., HD vs. standard definition) and after-sales service bundles. Pricing softness reflects intense competition in the disposable segment as manufacturers vie for large hospital network contracts. Hospitals, particularly large US networks, demonstrate high price sensitivity for disposables, while specialized surgical centers prioritize advanced features over cost.
Supply Chain Analysis
China and South Korea anchor the supply of miniature CMOS image sensors and specialized optical lenses critical for video laryngoscopes. The production of medical-grade plastics for disposable blades draws from diverse global sources. Single-source vulnerability for advanced sensor components presents a significant structural risk for manufacturers. Distribution runs through a dual model, with large medical distributors handling broad portfolios and specialized sales teams managing complex surgical systems directly with hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep clinical integration expertise, particularly in AI-assisted guidance for difficult airways, remains a scarce capability in the video laryngoscope market. This gap creates strategic opportunities for targeted investment and partnership.
For Market Incumbents: Consolidate market share in established hospital networks by offering bundled contracts that combine reusable systems with disposable blades. This defends against emerging low-cost alternatives and strengthens relationships with large procurement groups. Invest in ISO 13485 certification and post-market surveillance capabilities to navigate tightening EU MDR requirements. Deepen vertical integration into specialized sensor manufacturing to secure critical component supply.
For New Entrants and Emerging Players: Anchor in the rapidly expanding prehospital and emergency medical services segment with portable, durable video laryngoscopes. Focus on AI-assisted guidance features to lower the skill threshold for less experienced medical personnel. India and Brazil represent highly penetrable geographies due to increasing emergency response infrastructure investments. A direct-to-EMS sales model, emphasizing ease of use and battery life, offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a patient safety and efficiency play because advanced airway management tools reduce intubation complications. Seek out specialized innovators with strong intellectual property in AI-assisted visualization or novel disposable blade designs. Acquisition targets should be mid-cap firms with established regulatory pathways in the EU or US. The signal to watch is widespread adoption of AI-guided intubation protocols in major hospital systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Assisted Glottis Recognition Software | Enhances first-pass intubation success rates for emergency medical teams globally. |
| Expand Single-Use Disposable Blade Manufacturing | Directly addresses hospital-acquired infection concerns, particularly in US and German hospitals. |
| Secure ISO 13485 & EU MDR Compliance | Ensures market access and strengthens competitive positioning for European Union member states. |
| Partner with Prehospital Service Providers | Drives uptake of portable video laryngoscopes in out-of-hospital airway management settings. |
| Invest in Advanced CMOS Sensor Miniaturization | Improves visualization clarity for difficult airways, enhancing procedural safety in operating rooms. |
Research Approach
Desk research of regulatory filings, medical journals, and industry reports preceded structured interviews with hospital purchasing committees, clinicians, and biomedical engineers. This approach combined primary insights with secondary validation from GPO contracts and national health statistics. Bottom-up data aggregation from key end-user segments was triangulated with top-down market sizing for accuracy. This comprehensive data collection ensures robust market understanding.
Variance decomposition isolates the impact of key drivers, restraints, and opportunities on market growth across the analysis window. The framework models segmentation by product type, technology, application, and end-user, alongside regional adoption patterns. Compound annual growth rates derive from historical trends and projected technological advancements. Hospital procurement cycles for capital equipment serve as a critical forecast input.
Material uncertainties — rapid shifts in healthcare policy or unforeseen supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions based on current market dynamics and regulatory stability. Recalibration cycles align with material shifts in infection control mandates or technology breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Device Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Bronchoscopy Market
Endoscopy
United States Endoscopy Devices Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
Duodenoscope Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
South Korea Endoscopy Devices Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Endoscopic Submucosal Dissection Market