
 Endoscope Optics Objective Lenses Market | 2026-2036
Endoscope Optics Objective Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Optics Objective Lenses Market Insights
Aftermarket service revenue is reshaping profitability across the endoscope optics value chain, pulling margin pools away from bare component sales toward refurbishment contracts and field calibration programs. Olympus Corporation leverages its installed base of surgical visualization platforms to sustain recurring service income across Asia-Pacific hospital networks. Karl Storz GmbH & Co. KG anchors its competitive position through backward integration into proprietary glass formulations at its Tuttlingen headquarters. Fujifilm Holdings Corporation differentiates by controlling distribution of replacement lens modules for its expanding endoscopy system footprint.
Endoscope optics objective lenses are precision-molded glass or sapphire optical assemblies with numerical apertures typically ranging from 0.1 to 0.3, engineered to relay illuminated images from body cavities to camera sensors with minimal chromatic aberration. These components enable real-time visualization during laparoscopic, arthroscopic, and gastrointestinal procedures where physical access constraints preclude direct observation. Fiber optic lenses dominate current hospital procurement budgets due to proven reliability in sterilization cycles, while digital imaging technology is capturing the fastest expansion as 4K and 3D visualization protocols displace legacy analog stacks in minimally invasive surgery suites. Achromatic lens configurations command premium positioning in neurosurgical and ophthalmic applications where color fidelity directly impacts procedural outcomes.
FDA 510(k) premarket notification requirements govern lens assembly clearances in the United States, while the EU MDR and CE marking framework impose clinical evidence thresholds that smaller optical houses struggle to satisfy. Japan's PMDA maintains distinct biocompatibility testing protocols for reusable lens surfaces that contact mucosal tissue, creating additional compliance layers for exporters. Stakeholders must monitor how divergent sterilization validation standards across these three jurisdictions fragment product platform strategies and force region-specific SKU proliferation.
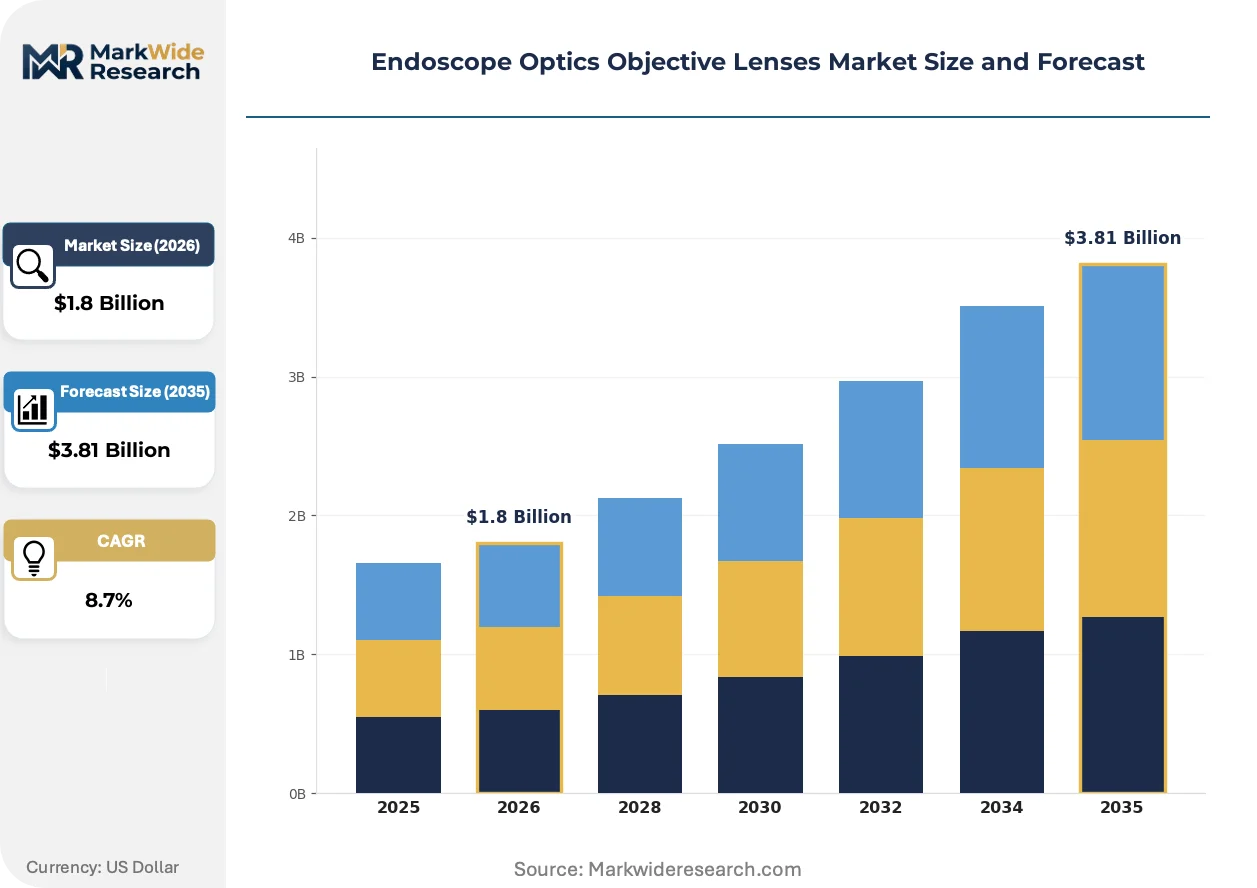
Market Dynamics
Backward integration into proprietary glass formulations at Tuttlingen and Baden-Württemberg is consolidating supply-side control, while tertiary hospital procurement of 4K optical stacks is compressing replacement cycles across minimally invasive surgery suites.
Growth Catalysts
- EU MDR biocompatibility mandates:Tightened clinical evidence thresholds for reusable lens surfaces are accelerating hospital replacement of legacy analog stacks with validated digital assemblies.
- Fiber optic sterilization reliability:Proven durability in autoclave cycles sustains procurement budgets for traditional optical pathways in high-throughput surgical environments.
- Germany's precision optics cluster:Concentrated specialized tooling and mold-making capabilities in Baden-Württemberg reduce lead times for complex achromatic lens configurations.
Market Restraints
- Sapphire substrate cost volatility:Raw material price swings for synthetic sapphire boules constrain margin stability in premium neurosurgical lens segments.
- FDA 510(k) pathway friction:Extended premarket notification timelines for new lens assemblies delay revenue recognition for smaller optical houses lacking regulatory infrastructure.
- Digital imaging substitution pressure:Solid-state sensor miniaturization threatens fiber optic relay architectures in gastrointestinal endoscopy applications.
Strategic Opportunities
- Japan's PMDA mucosal contact protocols:Distinct biocompatibility testing requirements for reusable lens surfaces create service revenue potential for compliance-certified refurbishment providers.
- Field calibration program expansion:Unbundled after-sales service contracts are capturing margin pools previously absorbed by bare component sales in Asia-Pacific hospital networks.
- 3D visualization protocol adoption:Stereoscopic imaging standards in laparoscopic suites are opening specification windows for dual-path objective lens architectures.
Industry Challenges
- Chromatography skill scarcity:Specialized coating technicians for anti-reflective dielectric stacks command premium wages, constraining production scaling at mid-cap manufacturers.
- ISO 13485 certification timelines:Medical device quality management system audits extend product launch schedules by eight to fourteen months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Optics Objective Lenses Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Lenses, Camera Lenses, Achromatic Lenses, Monochromatic Lenses Technology: Digital Imaging, Optical Coating, High-Definition, Zoom Technology Application: Minimally Invasive Surgery, Diagnostic Procedures, Therapeutic Applications, Veterinary Use End User: Hospitals, Clinics, Research Labs, Diagnostic Centers |
| Companies Covered | Olympus Corporation, Karl Storz GmbH & Co. KG, Fujifilm Holdings Corporation, Stryker Corporation, Excelitas Technologies, Sumita Optical Glass, Precision Optics Corporation, SCHÖLLY, Jenoptik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Optics Objective Lenses Market Trends and Innovations
Digital imaging technology is hybridizing with legacy optical architectures, compressing the distinction between analog relay systems and sensor-integrated endpoints across surgical visualization platforms.
Gradient-index (GRIN) rod lenses are hybridizing with conventional spherical assemblies to reduce optical stack length in rigid endoscopes without sacrificing numerical aperture performance. Tertiary hospital minimally invasive surgery suites are specifying these configurations for bariatric and orthopedic procedures where instrument diameter constraints are severe. The convergence is hybridizing procurement criteria, forcing suppliers to validate combined GRIN-conventional assemblies as unified subsystems rather than discrete components.
EU MDR's tightened biocompatibility requirements are extending development timelines for manufacturers seeking CE marking on reusable lens surfaces contacting mucosal tissue. Smaller optical houses without dedicated regulatory affairs departments are outsourcing clinical evidence compilation to specialized consultancies, increasing fixed cost structures. German and French surgical device clusters are most affected, with several Tuttlingen-area manufacturers delaying product launches pending notified body review queue clearance.
After-sales service unbundling is fragmenting traditional equipment procurement relationships in Asia-Pacific hospital networks. Olympus Corporation and Fujifilm Holdings are separating field calibration, refurbishment, and replacement lens module distribution into distinct contractual vehicles. Japan's metropolitan tertiary centers and South Korea's university hospitals are pioneering this model, compressing capital equipment decision cycles while elongating total customer lifetime value capture through recurring service revenue streams.
Endoscope Optics Objective Lenses Market Segmentation
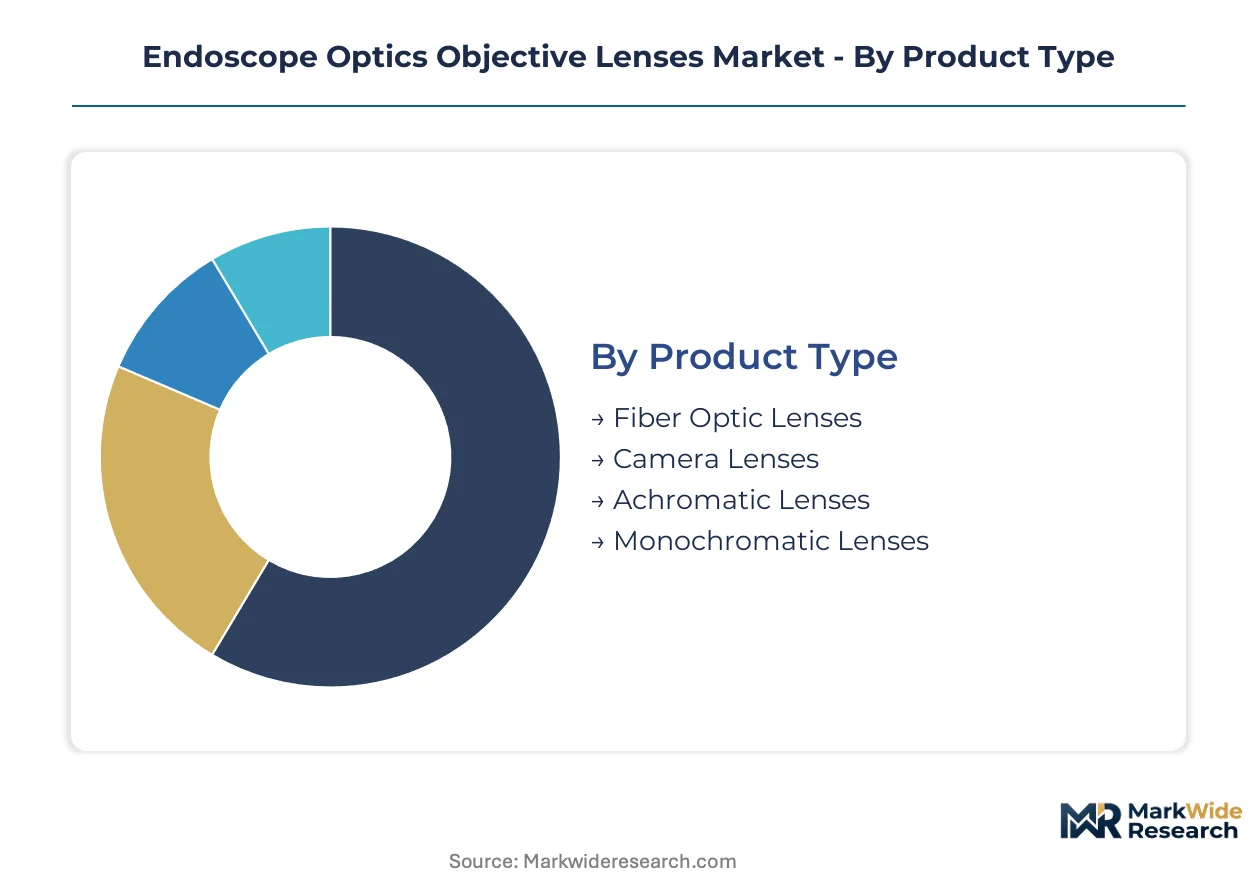
Endoscope optics objective lenses segment across multiple dimensions that determine procurement patterns and margin structures. Product type and technology classifications drive hospital capital allocation decisions, while application and end-user categories shape aftermarket service revenue potential across surgical visualization platforms.
Product Type:
Mature fiber optic assemblies dominate current installed bases, while emerging digital lens configurations capture specification windows in new minimally invasive surgery suite builds.
- Fiber Optic Lenses:Glass or sapphire relay assemblies transmit illuminated images through coherent fiber bundles with proven autoclave durability. Tertiary hospitals in Germany's Baden-Württemberg surgical device cluster specify these for high-throughput laparoscopic environments where sterilization reliability outweighs resolution advantages. Fiber optic sterilization reliability sustains procurement budgets despite digital substitution pressure.
- Camera Lenses:Precision-molded optical stacks integrate directly with CMOS sensors at the distal or proximal end of endoscope shafts. Demand concentrates in Japan's metropolitan tertiary centers adopting 4K and 3D visualization protocols that displace legacy analog relay architectures. Solid-state sensor miniaturization accelerates specification shifts in gastrointestinal endoscopy applications.
- Achromatic Lenses:Multi-element configurations correct chromatic aberration across visible wavelengths for color-critical procedures.
- Monochromatic Lenses:Single-wavelength optimized assemblies serve cost-sensitive diagnostic applications with reduced optical complexity.
Fiber optic lenses handle the majority of throughput; camera lenses are expanding most quickly on share as digital imaging protocols displace analog stacks.
Technology:
Cost tier stratification separates premium digital imaging stacks from standard high-definition configurations and economy optical coating alternatives.
- Digital Imaging:Sensor-integrated lens architectures capture 4K and 3D surgical visualization with direct digital output eliminating analog relay stages. EU MDR biocompatibility mandates for reusable lens surfaces contacting mucosal tissue accelerate hospital replacement of legacy analog systems with validated digital assemblies. Digital imaging technology is climbing the fastest as minimally invasive surgery suites specify native digital capture.
- Optical Coating:Anti-reflective dielectric stacks and hydrophobic surface treatments enhance light transmission and reduce fogging in body cavity environments. Specialized coating technicians command premium wages, constraining production scaling at mid-cap manufacturers serving high-volume diagnostic center procurement.
- High-Definition:1080p-class optical relay systems maintain installed base relevance in budget-constrained clinic settings.
- Zoom Technology:Variable focal length configurations enable magnification adjustment without instrument exchange during therapeutic procedures.
High-definition configurations retain volume leadership in replacement cycles; digital imaging is gaining share fastest as greenfield surgical suites specify native sensor integration.
Application:
Customer type differentiation separates capital-intensive hospital procurement from research lab specification patterns and diagnostic center volume purchasing.
- Minimally Invasive Surgery:Laparoscopic, arthroscopic, and endoscopic procedures requiring real-time visualization through small-diameter access ports. Tertiary hospital minimally invasive surgery suites in South Korea's university hospitals are expanding procurement of 4K optical stacks with unbundled after-sales service contracts. Gradient-index rod lenses hybridizing with conventional spherical assemblies reduce optical stack length for bariatric and orthopedic applications with severe instrument diameter constraints.
- Diagnostic Procedures:Screening and surveillance endoscopy for gastrointestinal, respiratory, and urological pathologies. FDA 510(k) premarket notification requirements govern lens assembly clearances for diagnostic platforms in the United States, extending development timelines for smaller optical houses lacking regulatory infrastructure.
- Therapeutic Applications:Interventional procedures combining visualization with instrument delivery channels for tissue resection or delivery.
- Veterinary Use:Companion animal and livestock endoscopy with reduced regulatory burden and shorter product lifecycles.
Minimally invasive surgery commands the dominant share of premium lens procurement; diagnostic procedures show the steepest expansion trajectory as population screening protocols expand.
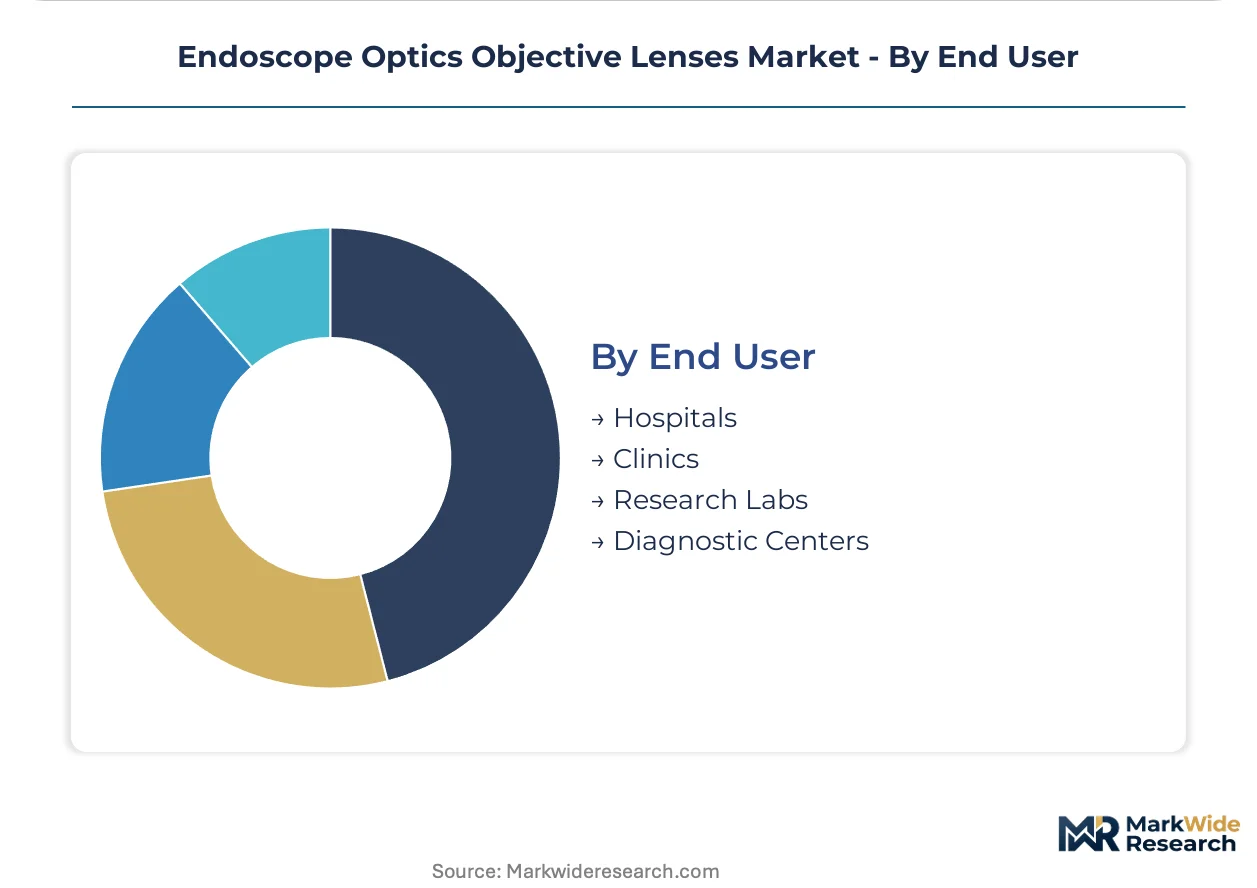
End User:
Geographic concentration within Germany's precision optics cluster shapes supply availability across end-user tiers, with Tuttlingen-area manufacturers prioritizing hospital and research lab fulfillment.
- Hospitals:Tertiary and secondary acute care facilities with centralized sterilization departments and capital equipment procurement committees. Japan's PMDA maintains distinct biocompatibility testing protocols for reusable lens surfaces that contact mucosal tissue, creating additional compliance layers for exporters serving hospital networks. Aftermarket service revenue is reshaping profitability as field calibration programs and refurbishment contracts pull margin pools away from bare component sales.
- Clinics:Ambulatory surgical centers and specialty practices with limited sterilization infrastructure and higher instrument turnover.
- Research Labs:Academic medical centers and device development facilities requiring custom optical configurations for preclinical validation.
- Diagnostic Centers:High-volume endoscopy screening facilities with standardized procedure protocols and price-sensitive procurement.
Hospitals absorb the majority of premium achromatic and digital imaging volume; diagnostic centers are scaling fastest as decentralized screening networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German tertiary hospitals absorb premium achromatic configurations with minimal price sensitivity, while diagnostic centers in India and Southeast Asia prioritize fiber optic reliability at aggressive cost points.
Germany
Tertiary hospitals in Baden-Württemberg specify 4K optical stacks with unbundled service contracts. EU MDR biocompatibility mandates for reusable lens surfaces accelerate replacement of legacy analog systems. Karl Storz and SCHÖLLY anchor precision optics production in Tuttlingen, consolidating specialized tooling capabilities.
United States
Minimally invasive surgery suites drive procurement of high-definition fiber optic assemblies with proven autoclave durability. FDA 510(k) premarket notification requirements extend development timelines for smaller optical houses lacking regulatory infrastructure. Boston and Cleveland medical device clusters concentrate refurbishment service providers.
Japan
Metropolitan tertiary centers specify native digital imaging protocols with sensor-integrated lens architectures. PMDA maintains distinct biocompatibility testing standards for reusable lens surfaces contacting mucosal tissue. Tokyo and Osaka hospital networks pioneer after-sales service unbundling for field calibration programs.
China
Domestic diagnostic centers scale procurement of cost-optimized monochromatic lenses for high-volume gastrointestinal screening. NMPA medical device registration pathways impose clinical evidence thresholds that favor established manufacturers. Yangtze River Delta surgical device clusters expand captive mold-making capacity for achromatic configurations.
South Korea
University hospitals specify dual-path objective lens architectures for stereoscopic visualization in laparoscopic suites. MFDS maintains harmonized biocompatibility standards with EU MDR frameworks, streamlining import clearance. Seoul Capital Area concentrates demand for gradient-index rod lens hybridizations in bariatric applications.
Endoscope Optics Objective Lenses Market Competitive Landscape
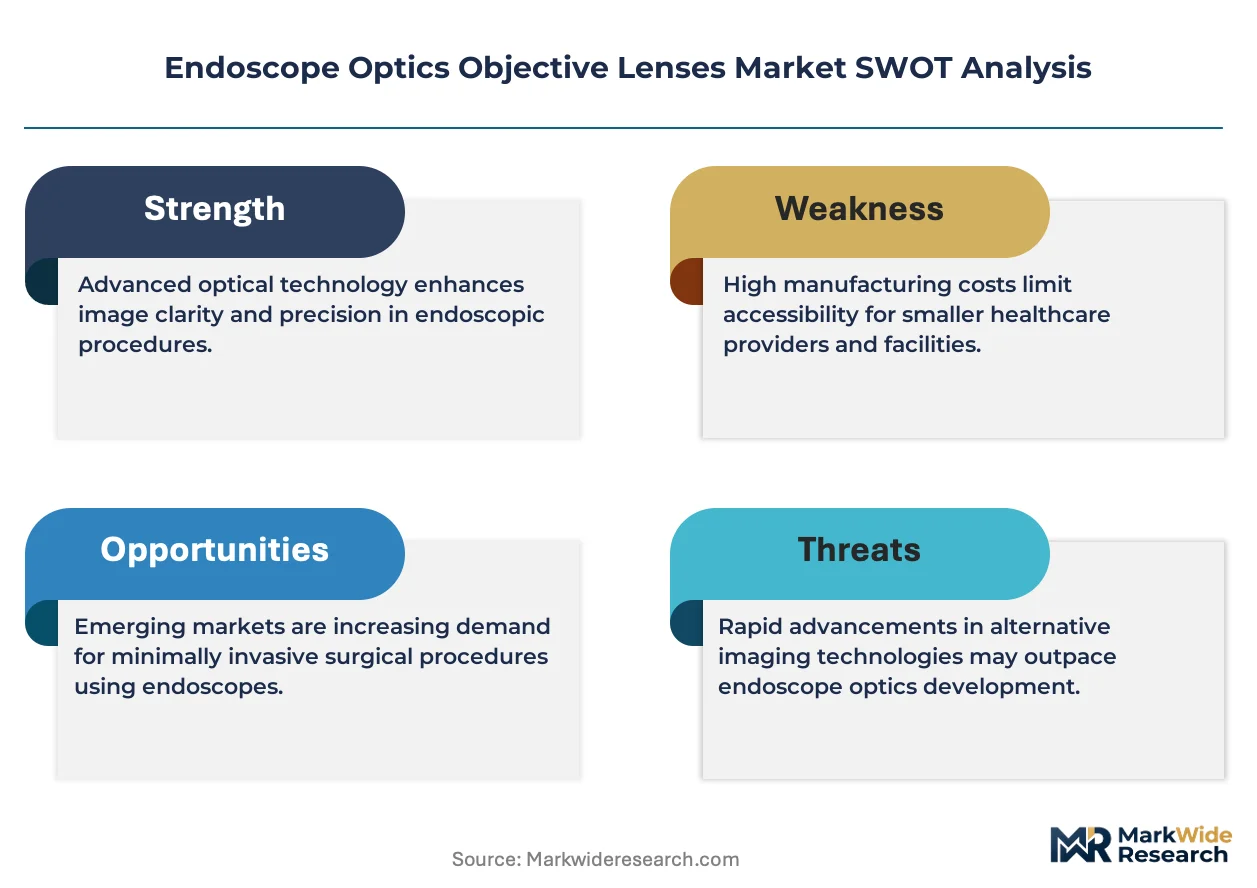
Capability concentration sits with German precision optics specialists; scale advantage sits with diversified medical device conglomerates. The market structures around three tiers: backward-integrated glass formulators, sensor-integrated platform vendors, and specialized coating houses. Dominant competitive moves include unbundled after-sales service contracts and proprietary distribution control over replacement lens modules.
Among Japan-based diversified manufacturers, Olympus Corporation and Fujifilm Holdings Corporation occupy positions exemplifying platform-scale leverage through installed base service monetization. Karl Storz GmbH & Co. KG represents the backward-integrated archetype with captive glass formulation capabilities. These three anchors illustrate how geographic clustering and vertical control shape competitive positioning across premium and mid-market segments.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz GmbH & Co. KG |
| Fujifilm Holdings Corporation |
| Stryker Corporation |
| Excelitas Technologies |
| Sumita Optical Glass |
| Precision Optics Corporation |
| SCHÖLLY |
| Jenoptik |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg's concentrated precision optics tooling capabilities tether margin pools to German manufacturers with captive mold-making capacity, while downstream hospital procurement committees in tertiary centers extract value through unbundled service contracts rather than bare component transactions.
Pricing Analysis
After-sales service revenue tiers—field calibration programs, refurbishment contracts, and extended replacement module distribution—now drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium achromatic configurations, standard high-definition optical stacks, and economy fiber optic assemblies stratifies procurement budgets by application criticality. Cost compression in economy monochromatic segments intensifies as Chinese diagnostic centers scale volume purchasing. Research labs and veterinary clinics exhibit highest price sensitivity; neurosurgical suites in German tertiary hospitals show minimal elasticity for color-critical lens configurations.
Supply Chain Analysis
Tariff exposure between Germany and China for synthetic sapphire boules constrains margin stability in premium neurosurgical lens segments. Manufacturing gravity centers on Germany, Japan, and China, with specialized glass formulation and mold-making capabilities concentrated in Tuttlingen and the Yangtze River Delta. Raw material dependencies include synthetic sapphire substrates, proprietary optical glass formulations, and anti-reflective dielectric coating chemicals. Single-source vulnerability sits with specialized coating technicians for achromatic configurations. Distribution runs through direct hospital system contracts in developed markets and GPO-aggregated procurement in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Endoscope optics objective lenses sit at a platform-economics inflection where sensor-integrated digital architectures are displacing analog relay systems, forcing interoperability investments that favor installed-base incumbents over component specialists.
For Market Incumbents: Harden defensive moats by deepening backward integration into proprietary glass formulations at Tuttlingen-area facilities and securing ISO 13485 certification ahead of EU MDR clinical evidence thresholds. Digital imaging substitution threatens fiber optic relay architectures; channel control over replacement lens module distribution preserves margin capture. For New Entrants and Emerging Players: Build out regulatory infrastructure targeting Japan's PMDA mucosal contact protocols, where distinct biocompatibility testing requirements create service revenue white space for compliance-certified refurbishment providers. Veterinary diagnostic centers and ambulatory surgical clinics in Southeast Asia represent the most penetrable procurement tiers with reduced sterilization validation burdens. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated precision optics specialists with captive mold-making capacity and established notified body relationships across the analysis window. Watch for inflection when tertiary hospital procurement committees mandate native digital capture protocols in greenfield minimally invasive surgery suite builds.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Clinical evidence thresholds for reusable lens surfaces accelerate validated digital assembly adoption in German surgical clusters. |
| Hospital System Partnership | Unbundled after-sales service contracts with Tokyo and Osaka metropolitan centers elongate customer lifetime value capture. |
| Backward Integration into Glass Formulation | Captive supply of proprietary optical materials at Tuttlingen headquarters reduces lead times for complex achromatic configurations. |
| Software Companion Development | Field calibration program digitization supports recurring revenue streams across Asia-Pacific hospital networks. |
| Reimbursement Strategy | Alignment with CMS Medicare coverage for 4K visualization protocols shapes capital equipment procurement cycles in US tertiary centers. |
Research Methodology
Desk research of FDA 510(k) premarket notification filings, EU MDR notified body review databases, and hospital procurement contract registries preceded structured interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee members, and aftermarket service heads. Secondary validation drew from PMDA biocompatibility testing protocols, customs trade data for optical glass imports, and SEC filings of diversified medical device conglomerates. Bottom-up demand modeling triangulated against top-down market sizing across product type and technology segments.
Assumptions held fixed include regulatory clearance timelines for new lens assemblies and sterilization validation standards across jurisdictions; variables included digital imaging protocol adoption rates and unbundled service contract penetration. The analytical framework segmented by product type, technology, application, and end user, with CAGRs derived from procedure volume growth in minimally invasive surgery and diagnostic screening expansion. Forecast inputs incorporated gradient-index rod lens hybridization adoption in bariatric applications and 3D visualization protocol specification in laparoscopic suites.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sensor-integrated platform vendors or regulatory acceleration by FDA would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Endoscopy Device Market
Endoscopy
Global Disposable Endoscope Market