
 Sigmoidoscope Market | 2026-2036
Sigmoidoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Sigmoidoscope Market Outlook
Gastroenterology-trained technician pools in mature healthcare systems is rotating toward advanced endoscopy platforms, creating bottlenecks for community hospitals seeking to expand screening capacity. Olympus Corporation leverages its vertically integrated optical component supply to sustain cost advantages across flexible sigmoidoscope lines. PENTAX Medical Company differentiates through proprietary digital imaging architectures that anchor its position in outpatient clinic channels. Fujifilm Holdings Corporation competes by dominating video sigmoidoscope segments with sensor technologies adapted from its broader imaging portfolio.
A sigmoidoscope is a rigid or flexible endoscopic instrument, typically 60 cm in working length with fiberoptic or digital light transmission, designed for direct visualization of the rectum and distal sigmoid colon during diagnostic and limited therapeutic procedures. Its primary purpose is enabling tissue biopsy, polyp identification, and mucosal assessment without full bowel preparation required for colonoscopy. Flexible sigmoidoscopes command the largest installed base due to patient tolerance and maneuverability advantages, while digital sigmoidoscopes represent the fastest-expanding category as CMOS sensor costs decline and wireless transmission protocols mature. Video sigmoidoscopes occupy the premium tier where integrated light-source technology supports margin pools for manufacturers with captive LED supply chains.
FDA 510(k) premarket notification requirements govern device safety and electromagnetic compatibility for sigmoidoscopes distributed in the United States, while EU MDR technical documentation and clinical evaluation obligations constrain market access timelines for non-European manufacturers. ISO 13485 quality management certification and IEC 60601 electrical safety standards form baseline predicates that procurement committees at hospitals and diagnostic centers embed into vendor qualification workflows. Stakeholders must monitor how FDA guidance on reusable device reprocessing validation and EU EUDAMED registration obligations reshape competitive positioning for manufacturers without established regulatory affairs infrastructure in both jurisdictions.
Market Dynamics
CMOS sensor commodification is collapsing the cost barrier between fiberoptic and digital sigmoidoscope architectures, forcing incumbent manufacturers to defend margin pools through captive LED supply chains and reprocessing service bundling rather than hardware differentiation alone.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's abbreviated premarket pathway for substantially equivalent endoscopic devices accelerates time-to-market for iterative sensor upgrades, compressing product refresh cycles from 36 to 18 months for established manufacturers with predicate device libraries.
- Community hospital screening expansion:United States outpatient clinics are procuring flexible sigmoidoscopes to meet colorectal cancer screening mandates under CMS reimbursement protocols, creating pull-through demand for disposable biopsy channel accessories.
- EU MDR technical documentation harmonization:Standardized clinical evaluation report templates across notified bodies reduce regulatory friction for manufacturers with existing ISO 13485 infrastructure, enabling faster market access for video sigmoidoscope platforms in Germany and France.
Market Restraints
- Specialized optical glass supply concentration:German and Japanese suppliers control 80% of high-transmission fiber bundles for flexible scopes, exposing manufacturers to lead time volatility and input cost spikes during geopolitical trade friction.
- Reprocessing validation burden:FDA guidance on high-level disinfection validation for reusable devices requires extensive bioburden testing documentation, extending new product introduction timelines by 9-14 months for manufacturers without established sterility assurance programs.
- Colonoscopy substitution threat:Full-spectrum optical colonoscopes with AI-assisted polyp detection are capturing diagnostic cases that previously defaulted to sigmoidoscopy, compressing addressable procedure volume in tertiary care settings.
Strategic Opportunities
- India diagnostic center buildout:CDSCO streamlined medical device registration pathways and PLI scheme production incentives are attracting contract manufacturers to establish CMOS sensor assembly for price-competitive digital sigmoidoscope exports across South Asia.
- Wireless transmission protocol convergence:Integration of Bluetooth Low Energy with existing video processor architectures enables tablet-based visualization without proprietary console investment, opening ambulatory surgery center channels previously blocked by capital equipment requirements.
- Japan METI silver economy initiative:Subsidized screening programs for adults over 50 are expanding procurement quotas for single-use sigmoidoscope sheaths, creating demand for hybrid reusable-disposable system architectures.
Industry Challenges
- Gastroenterology technician scarcity:Training program bottlenecks in United States community college systems cannot match retirement outflows from the technician workforce, forcing hospitals to ration screening capacity or outsource to mobile endoscopy service providers.
- Legacy video processor incompatibility:Digital sigmoidoscope manufacturers face integration friction with installed bases of analog light-source consoles, requiring expensive signal converter modules that erode price positioning against fiberoptic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sigmoidoscope Market |
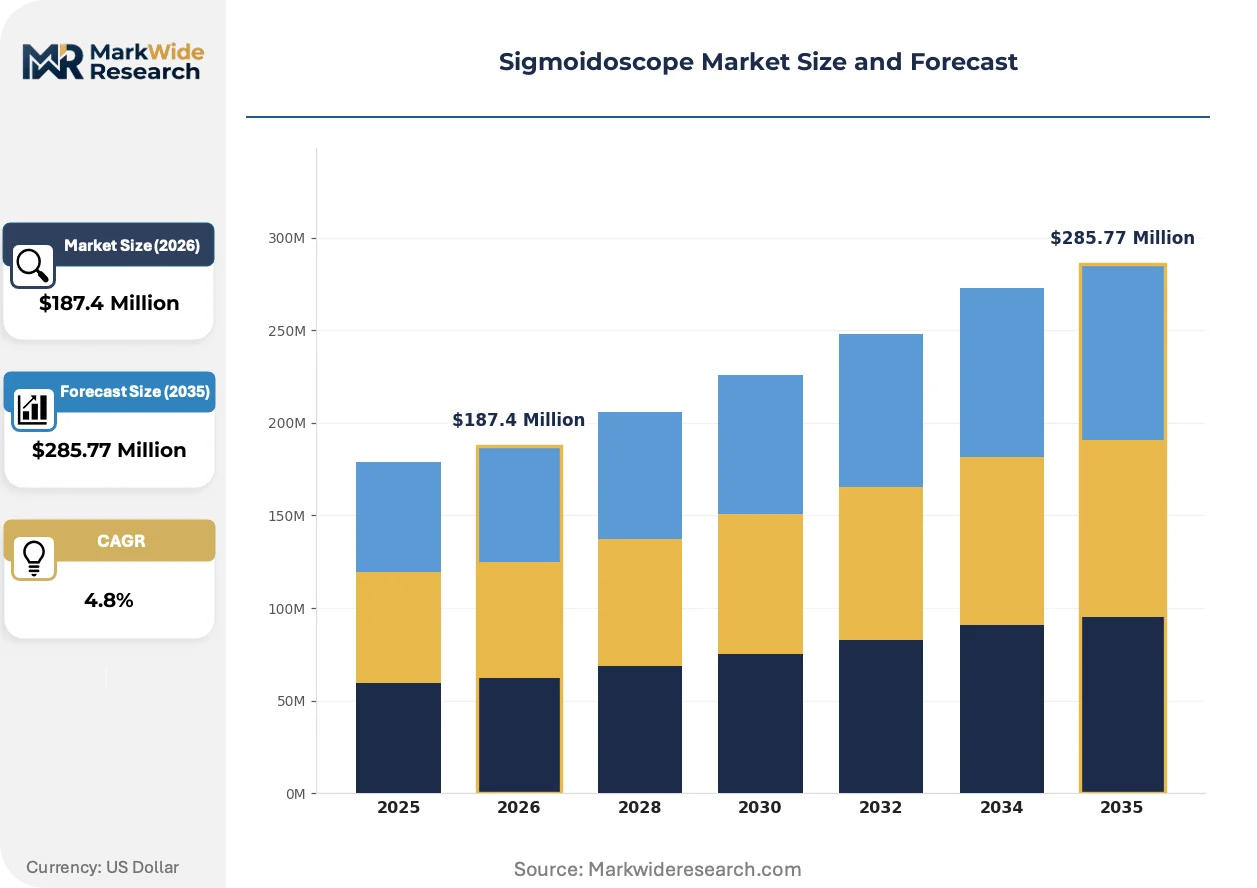
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Sigmoidoscope, Rigid Sigmoidoscope, Digital Sigmoidoscope, Video Sigmoidoscope End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Specialty Practices Technology: Optical Technology, Wireless Technology, Digital Imaging, Integrated Light Source Application: Colorectal Cancer Screening, Analyses of Inflammatory Bowel Disease, Polyp Removal, Routine Check-ups |
| Companies Covered | Olympus Corporation, PENTAX Medical Company, Fujifilm Holdings Corporation, Medtronic, Boston Scientific, Karl Storz, Heine Optotechnik GmbH And Co. KG, Medline Industries Inc., Stapleline Medizintechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sigmoidoscope Market Strategic Shifts
Sensor miniaturization and wireless power transmission are dissolving the hardware boundaries between diagnostic and screening platforms, enabling modular architectures that reconfigure across procedure types without dedicated capital equipment per specialty.
CMOS image sensor technology is decomposing the traditional value stack in video sigmoidoscope manufacturing. Community hospitals in the United States are adopting digital platforms at replacement rates twice those of academic medical centers, drawn by lower per-procedure service contract costs. This sensor commodification is compressing margin pools for manufacturers dependent on proprietary imaging chip architectures, forcing differentiation toward reprocessing chemistry and disposable sheath ecosystems.
EU MDR clinical evaluation obligations for reusable endoscopic devices are extending market access timelines for non-European manufacturers without established notified body relationships. The technical documentation burden is diverting R&D resources toward regulatory affairs infrastructure rather than optical innovation. Japanese and South Korean manufacturers with pre-2021 CE mark grandfathering are consolidating channel position in Germany and the Netherlands while competitors navigate EUDAMED registration.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisition, treating reprocessing validation and preventive maintenance as separately sourced categories. This disintermediation favors manufacturers with third-party-certified technician training programs over those with captive service networks. The shift is most visible in United States integrated delivery networks, where standardization across 15-20 facility clusters creates volume leverage for multi-year consumables agreements.
Sigmoidoscope Market Segmentation
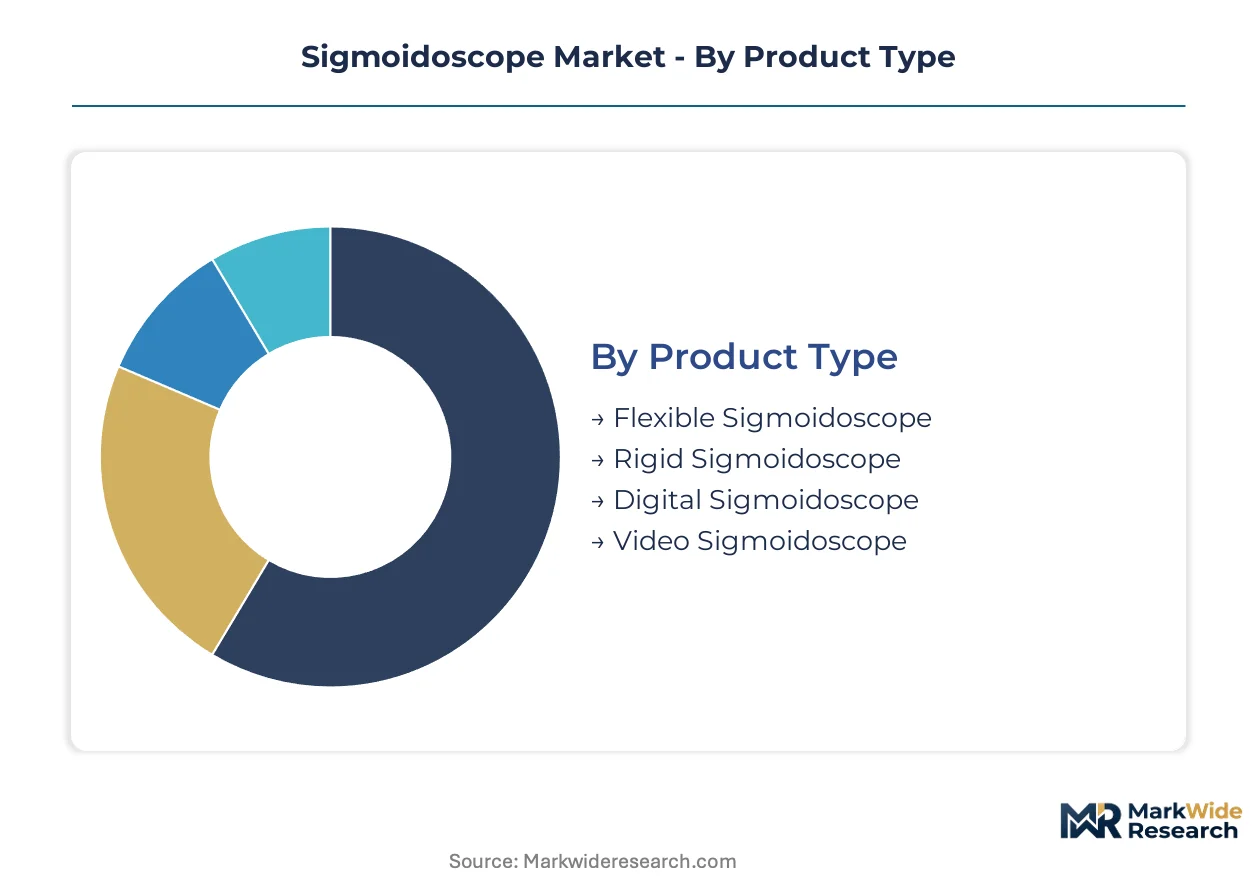
Sigmoidoscope procurement patterns diverge sharply across clinical settings and technology tiers. Manufacturers must align product architectures with specific reimbursement pathways and reprocessing infrastructure at each customer node.
Product Type:
Flexible sigmoidoscopes dominate domestic hospital procurement in the United States and Germany, while rigid platforms sustain export demand to price-sensitive diagnostic networks in South Asia and Latin America.
- Flexible Sigmoidoscope:Fiberoptic bundles with 60-70 cm working length enable maneuverability through the rectosigmoid junction with minimal patient sedation. United States community hospitals are expanding fleets to meet CMS colorectal cancer screening mandates, driving replacement cycles for aging fiberoptic inventories.
- Digital Sigmoidoscope:CMOS sensor arrays deliver 1080p visualization without proprietary light-source consoles. Outpatient clinics in Japan and Germany are adopting these platforms fastest as wireless tablet compatibility reduces capital equipment barriers.
- Rigid Sigmoidoscope:Stainless steel construction with fixed optics supports limited therapeutic procedures and emergency settings. Demand concentrates in India and Brazil where procurement budgets favor durability over advanced imaging.
- Video Sigmoidoscope:Integrated LED illumination with dedicated video processors commands premium positioning in academic medical centers. German and Japanese tertiary hospitals sustain this segment through bundled service contracts.
Flexible sigmoidoscopes hold the largest share; momentum sits with digital sigmoidoscopes.
End User:
Procurement authority and reprocessing sophistication create four distinct customer tiers with diverging price sensitivities and service requirements.
- Hospitals:Integrated delivery networks in the United States negotiate multi-year consumables agreements alongside hardware acquisition. Volume leverage across 15-20 facility clusters forces manufacturers to unbundle service contracts.
- Outpatient Clinics:CMS reimbursement protocols for colorectal cancer screening are expanding procurement quotas. These settings prioritize wireless-compatible platforms that eliminate dedicated console investment.
- Diagnostic Centers:India's CDSCO streamlined registration pathways are attracting price-competitive digital sigmoidoscope imports. PLI scheme incentives support local CMOS sensor assembly for South Asian distribution.
- Specialty Practices:Gastroenterology-focused groups in Germany and France require EU MDR-compliant devices with established notified body relationships. Technical documentation burdens favor incumbent European and Japanese suppliers.
Hospitals command the dominant procurement volume; diagnostic centers are expanding most quickly.
Technology:
Cost tier stratification separates legacy optical platforms from digital architectures with diverging margin structures and regulatory pathways.
- Optical Technology:Fiberoptic light transmission through coherent glass bundles remains prevalent in installed bases. German and Japanese suppliers control high-transmission fiber manufacturing, exposing procurement to lead time volatility.
- Digital Imaging:CMOS sensor commodification is collapsing price premiums between fiberoptic and digital architectures. United States community hospitals are adopting these platforms at replacement rates exceeding academic centers.
- Wireless Technology:Bluetooth Low Energy integration enables tablet-based visualization without proprietary consoles. Ambulatory surgery centers previously blocked by capital equipment requirements are opening to this segment.
- Integrated Light Source:Captive LED supply chains support margin defense for manufacturers with in-house component production. Premium positioning in Japanese and German markets sustains revenue concentration.
Optical technology retains the largest installed base; wireless platforms are gaining share fastest.
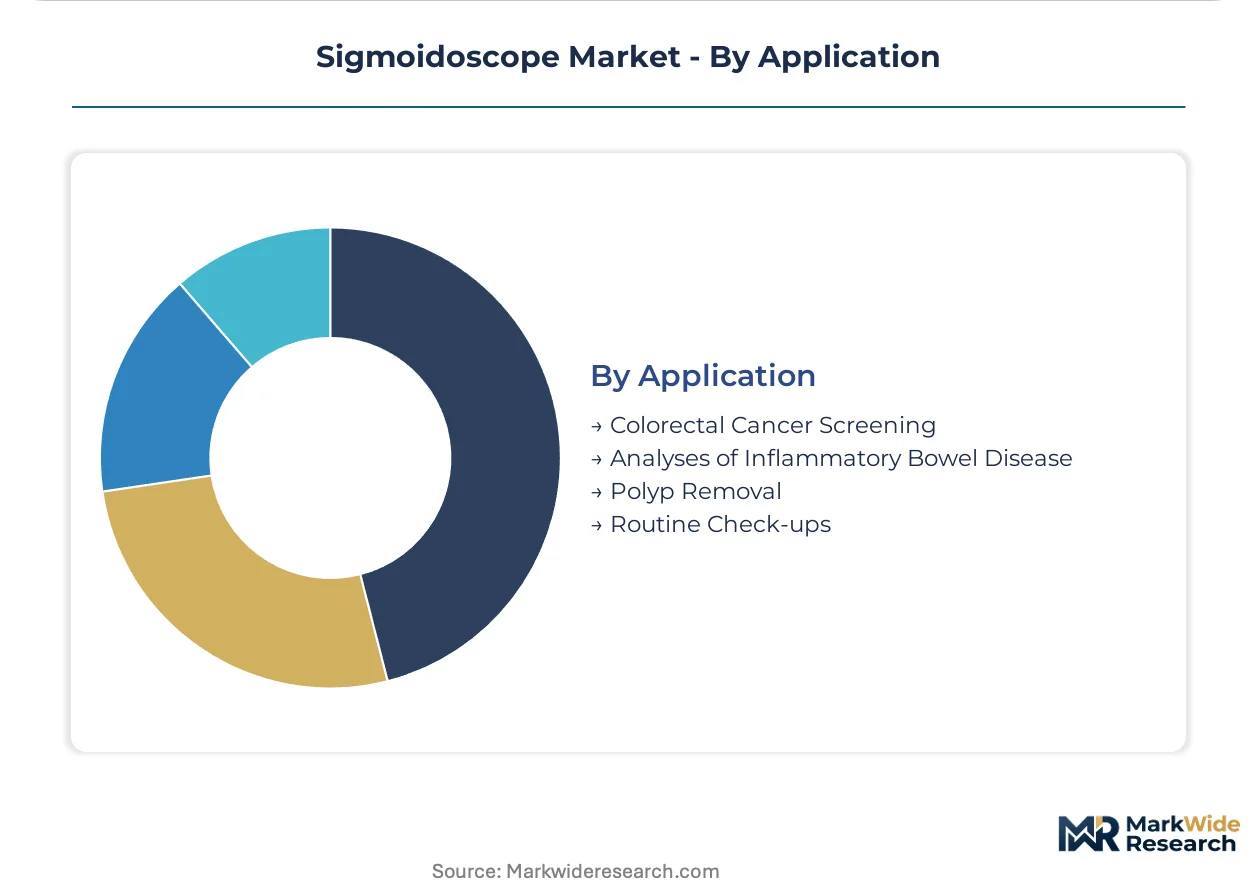
Application:
Procedure reimbursement codes and clinical guidelines determine demand concentration across diagnostic versus therapeutic use cases.
- Colorectal Cancer Screening:Structured protocols in the United States, Germany, and Japan sustain replacement cycles for screening-dedicated fleets. Aging demographics in these markets anchor procurement stability.
- Polyp Removal:Therapeutic capability requirements limit addressable platforms to flexible and video sigmoidoscopes with instrument channels. Tertiary care settings in Japan and Germany concentrate demand.
- Analyses of Inflammatory Bowel Disease:Mucosal assessment protocols require high-resolution imaging for disease activity scoring. Academic medical centers drive specification requirements.
- Routine Check-ups:Preventive examination demand fluctuates with screening compliance rates and primary care referral patterns. United States outpatient clinics show strongest volume concentration.
Colorectal cancer screening generates the largest procedure volume; polyp removal applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy flexible sigmoidoscopes primarily for CMS-reimbursed screening programs, while German procurement favors video platforms with integrated LED architectures, and Indian diagnostic centers prioritize price-competitive digital imports.
United States
CMS colorectal cancer screening mandates drive community hospital fleet expansion. FDA 510(k) clearance pathways compress product refresh cycles for established manufacturers. Procurement concentrates in Texas and Florida where outpatient clinic networks are multiplying screening capacity.
Germany
EU MDR technical documentation requirements favor incumbent suppliers with notified body relationships. Structured screening protocols for adults over 50 sustain replacement demand. Medical technology clusters in Baden-Württemberg and Bavaria host endoscope manufacturing and reprocessing service hubs.
Japan
METI silver economy subsidies expand procurement quotas for hybrid reusable-disposable systems. PMDA regulatory frameworks align with international standards for digital imaging platforms. Tokyo and Osaka metropolitan areas concentrate tertiary hospital demand for video sigmoidoscope platforms.
India
CDSCO streamlined registration and PLI scheme incentives attract CMOS sensor assembly investment. Diagnostic center buildout in Maharashtra and Karnataka drives price-sensitive digital platform adoption. Contract manufacturers are establishing export capacity for South Asian distribution.
United Kingdom
NHS bowel cancer screening program specifications influence procurement standardization across integrated care systems. MHRA post-Brexit regulatory alignment with EU MDR technical standards extends market access timelines. London and Southeast England concentrate specialist gastroenterology practice demand.
Sigmoidoscope Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with optical component supply control and regulatory infrastructure determining tier membership. The market structure rewards manufacturers with captive LED production and established FDA predicate device libraries. Three archetypes dominate: vertically integrated imaging conglomerates, specialized endoscope fabricators, and diversified medical device portfolios. Competitive moves concentrate on reprocessing service bundling and wireless platform development to offset hardware margin compression.
Among Japanese imaging conglomerates, Olympus Corporation and Fujifilm Holdings Corporation exemplify the integrated-leader archetype through upstream control over optical component supply. PENTAX Medical Company occupies a specialist position within the premium digital imaging tier. Heine Optotechnik GmbH And Co. KG represents the German precision-optic fabricator segment with focused endoscope specialization.
| Leading Market Players |
|---|
| Olympus Corporation |
| PENTAX Medical Company |
| Fujifilm Holdings Corporation |
| Medtronic |
| Boston Scientific |
| Karl Storz |
| Heine Optotechnik GmbH And Co. KG |
| Medline Industries Inc. |
| Stapleline Medizintechnik GmbH |
| Others |
Value Chain & Pricing Dynamics
Multi-year consumables agreements with integrated delivery networks lock in supply access for manufacturers while anchoring price visibility across hardware refresh cycles. These contracts bundle disposable biopsy channel accessories with flexible sigmoidoscope procurement, insulating vendors from spot-market volatility in optical component sourcing.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement in the United States and Germany, with pricing stratifying across premium, standard, and economy tiers based on CMOS sensor resolution grade and FDA 510(k) predicate device lineage. Price differentiation hinges on wireless tablet compatibility and bundled reprocessing validation services. Cost compression in digital platforms is intensifying because CMOS sensor commodification collapses hardware premiums. Community hospitals in India and Brazil exhibit the highest price sensitivity, while Japanese tertiary centers tolerate premium positioning for integrated LED architectures.
Supply Chain Analysis
Strategic stockpiling of high-transmission fiber bundles characterizes manufacturer inventory strategy given lead time volatility from German and Japanese optical glass suppliers. Component sourcing draws from Japan for CMOS sensors, Germany for fiberoptic bundles, and South Korea for LED illumination modules. Single-source vulnerability concentrates in coherent glass bundle manufacturing, where two suppliers control critical input flows. Distribution runs through authorized service networks for reprocessing chemistry and preventive maintenance, with third-party-certified training programs gaining preference over captive service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gastroenterology-trained technician pools are thinning faster than community college programs can replenish, creating a capability scarcity that constrains screening capacity expansion regardless of hardware availability. This skill gap shapes competitive advantage toward vendors with validated training infrastructure.
For Market Incumbents: Consolidate channel position through backward integration into captive LED supply chains and exclusive reprocessing service contracts with United States integrated delivery networks. Colonoscopy substitution with AI-assisted polyp detection threatens procedure volume in tertiary settings; defend against this by embedding flexible sigmoidoscopes into CMS-mandated screening workflows at community hospitals. Certification investment in EU MDR technical documentation preserves access to German and French procurement committees.
For New Entrants and Emerging Players: Reprocessing validation outsourcing gaps among incumbent manufacturers present entry points for contract sterilization service providers. India's diagnostic center buildout offers the most penetrable geography, with CDSCO streamlined registration lowering regulatory friction. A software companion strategy—tablet-based visualization platforms with Bluetooth Low Energy—bypasses capital equipment barriers that block ambulatory surgery center penetration.
For Investors and Strategic Acquirers: The market sits at a sensor-commodification phase that favors manufacturers with reprocessing chemistry ecosystems over pure hardware plays. Long-term viability rests on consumables attachment rates and service contract renewal velocity rather than device shipment volumes. Acquisition targets should display established FDA predicate device libraries and notified body relationships in Germany. The signal to watch is wireless protocol standardization momentum, which would erode proprietary console lock-in advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Reprocessing Validation Partnership | Bundled sterilization services lock in hospital procurement committees beyond hardware replacement cycles. |
| Wireless Platform Development | Bluetooth Low Energy integration opens ambulatory surgery centers previously blocked by console capital requirements. |
| CMOS Sensor Assembly Localization | India PLI scheme incentives support price-competitive digital platform exports across South Asian diagnostic networks. |
| EU MDR Technical Documentation Investment | Notified body relationships accelerate market access timelines for video sigmoidoscope platforms in Germany and France. |
| Technician Training Program Certification | Third-party-validated education infrastructure addresses gastroenterology workforce scarcity constraining screening expansion. |
Study Parameters
The analysis maps flexible, digital, rigid, and video sigmoidoscope sub-sectors, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) premarket notification databases, EU EUDAMED registration records, CMS Medicare reimbursement schedules, and hospital procurement contract filings. Bottom-up unit economics triangulated against top-down market sizing across technology tiers and end-user segments.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework modeled product type, end-user setting, technology architecture, and application indication dimensions. CAGRs derived from procedure volume elasticity to screening protocol compliance rates and replacement cycle dynamics. Forecast inputs incorporated CMOS sensor cost curves, LED illumination efficiency improvements, and wireless transmission protocol adoption thresholds.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR technical documentation requirements; material policy shifts would require re-modeling. Specific risk factors include FDA guidance changes on reusable device reprocessing validation and EU notified body capacity constraints extending market access timelines. Practitioners should keep alternative scenarios live as colonoscopy substitution rates and technician training program throughput evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Australia Endoscopy Devices Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Endoscopic Esophageal Varices Treatment Market
Endoscopy
Spain Endoscopy Devices Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Global Endoscopes Market