
 China Endoscopy Devices Market | 2026-2036
China Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Endoscopy Devices Market Outlook
Recurring maintenance and software upgrade contracts is shifting revenue models from capital equipment sales to lifetime value relationships. Olympus Corporation leverages its nationwide service infrastructure to sustain high-margin attachment rates on flexible endoscope fleets. Mindray Bio-Medical Electronics anchors its position through domestic manufacturing cost structures and rapid NMPA registration turnaround. KARL STORZ SE & Co. KG differentiates via rigid endoscope specialization for orthopedic and ENT surgical suites in tier-one cities.
Endoscopy devices comprise opto-electronic instrument systems integrating lens assemblies, illumination fibers, and image sensors for minimally invasive diagnostic and therapeutic visualization within hollow organs and body cavities. High-definition CMOS sensors and narrow-band imaging filters enable real-time mucosal tissue differentiation during gastrointestinal screening procedures. Flexible endoscopes dominate hospital procurement budgets due to gastroenterology procedure volume concentration, while capsule endoscopes represent the fastest-expanding category driven by patient preference for non-sedated colorectal examination alternatives. Video endoscopy technology captures the largest installed base, though 3D endoscopy systems command premium positioning in laparoscopic surgical centers.
NMPA medical device registration pathways and GB standards for electrical safety and biocompatibility shape product development timelines and market access requirements for domestic and imported manufacturers. China's dual carbon goals and green manufacturing directives are influencing sterilization process regulations and single-use device environmental compliance frameworks. Stakeholders must monitor NMPA policy revisions on innovative device fast-track approvals and provincial centralized procurement dynamics to calibrate portfolio and pricing decisions.
Market Dynamics
Single-use endoscope economics are compressing capital equipment replacement cycles across Guangdong and Jiangsu tertiary hospitals while NMPA innovation fast-tracks accelerate domestic substitution timelines.
Growth Catalysts
- NMPA Innovation Pathways:Fast-track registration for breakthrough devices shortens time-to-market for domestic manufacturers targeting infection-sensitive departments.
- Guangdong Procedure Volumes:Tertiary hospital clusters in this province generate concentrated demand for high-definition gastroenterology suites.
- CMOS Sensor Migration:Solid-state imaging technology eliminates fiber optic maintenance burdens while enabling 4K resolution at reduced unit economics.
Market Restraints
- Optical Glass Supply Concentration:German and Japanese lens assembly suppliers control critical illumination fiber inputs, creating import dependency exposure.
- GB Electrical Safety Compliance:Biocompatibility testing protocols under national standards extend validation timelines for novel materials.
- Capital Equipment Budget Compression:Provincial centralized procurement mechanisms squeeze premium pricing flexibility for imported video endoscopy platforms.
Strategic Opportunities
- Western Province Penetration:Sichuan and Shaanxi tertiary hospitals remain undersupplied with 3D visualization platforms relative to eastern coastal density.
- Dual Carbon Manufacturing Incentives:MEE environmental compliance credits favor domestic producers adopting low-carbon sterilization process technologies.
- AI-Assisted Polyp Detection:Machine vision integration with narrow-band imaging creates premium service tier differentiation in urban screening centers.
Industry Challenges
- Endoscope Reprocessing Technician Shortage:Qualified sterile processing staff scarcity in tier-two cities limits flexible scope fleet utilization rates.
- Legacy Video Processor Integration:Proprietary connector formats across manufacturer ecosystems obstruct multi-brand surgical suite standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Endoscopy Devices Market |
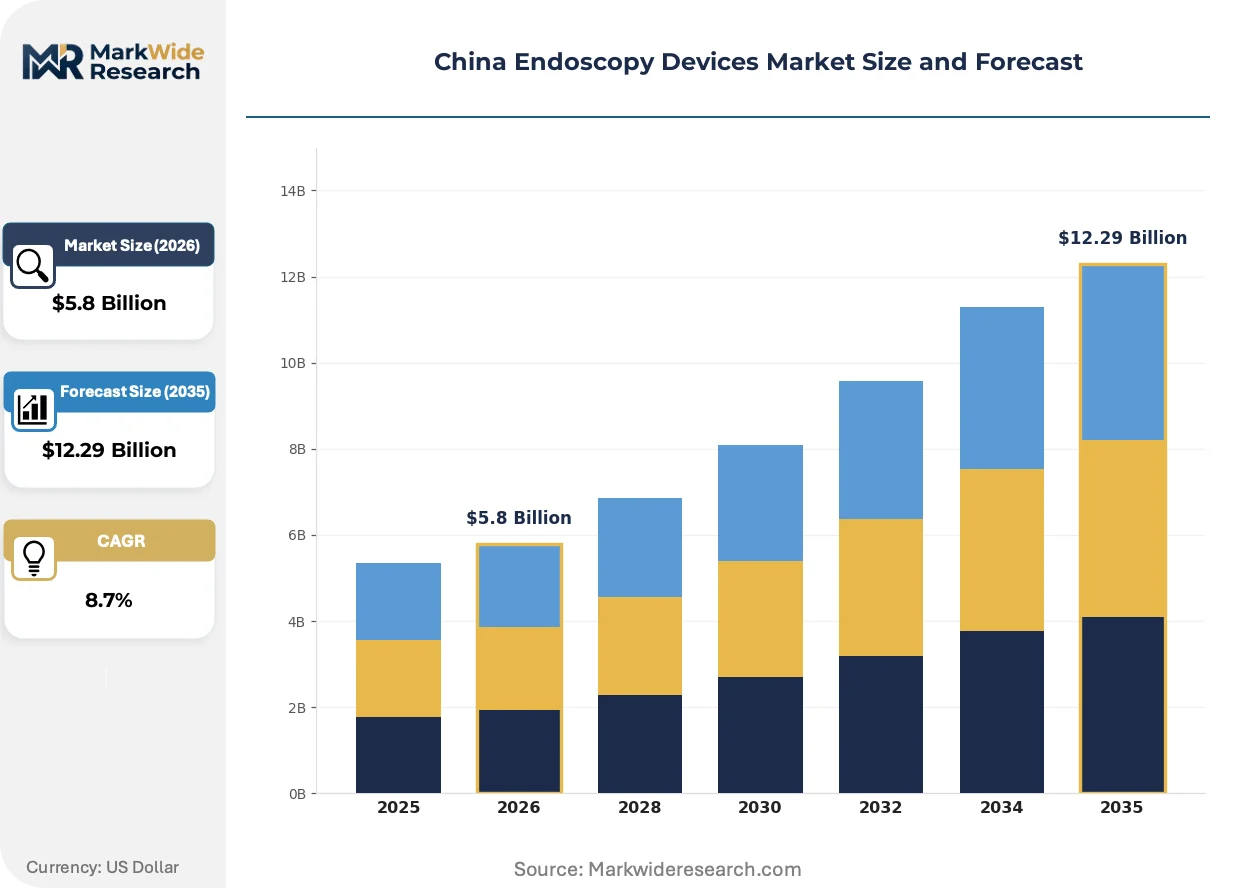
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Capsule Endoscopes, Endoscopic Retrograde Cholangiopancreatography Application: Gastroenterology, Pulmonology, Urology, Otolaryngology Technology: Optical Coherence Tomography, Video Endoscopy, Wireless Endoscopy, 3D Endoscopy End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Outpatient Clinics |
| Companies Covered | Johnson & Johnson, KARL STORZ SE & Co. KG, Olympus Corporation, Mindray Bio-Medical Electronics, Stryker Corporation, Medtronic plc, Fujifilm Holdings, Shanghai Aohua Photoelectricity Endoscope, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Endoscopy Devices Market Strategic Shifts
Digital imaging pipelines and disposable instrument economics are restructuring procurement patterns across Chinese hospital procurement consortia, with software-defined functionality displacing hardware-centric value capture.
Artificial intelligence-assisted detection algorithms are automating real-time polyp identification during colonoscopy procedures. Tertiary hospitals in Shanghai and Beijing are deploying these systems at scale within screening programs. The technology is automating diagnostic workflow steps previously requiring specialist physician attention, compressing procedure duration while standardizing detection sensitivity across operator experience levels.
NMPA's 2023 revised guidance on innovative medical device review establishes predicate-free pathways for breakthrough endoscopy technologies. Domestic manufacturers leverage these provisions to accelerate CMOS-based platform registrations previously dominated by imported fiber optic systems. Gastroenterology suites in Jiangsu province are responding by expanding pilot evaluations of locally-developed 4K visualization stacks.
Service contract unbundling is fragmenting traditional capital sale relationships into modular software subscription and maintenance components. Hospital procurement departments in tier-one cities are negotiating standalone image processing upgrades independent of hardware refresh cycles. This pattern is most visible among Guangdong province medical center consortia centralizing endoscope fleet management decisions.
China Endoscopy Devices Market Segmentation
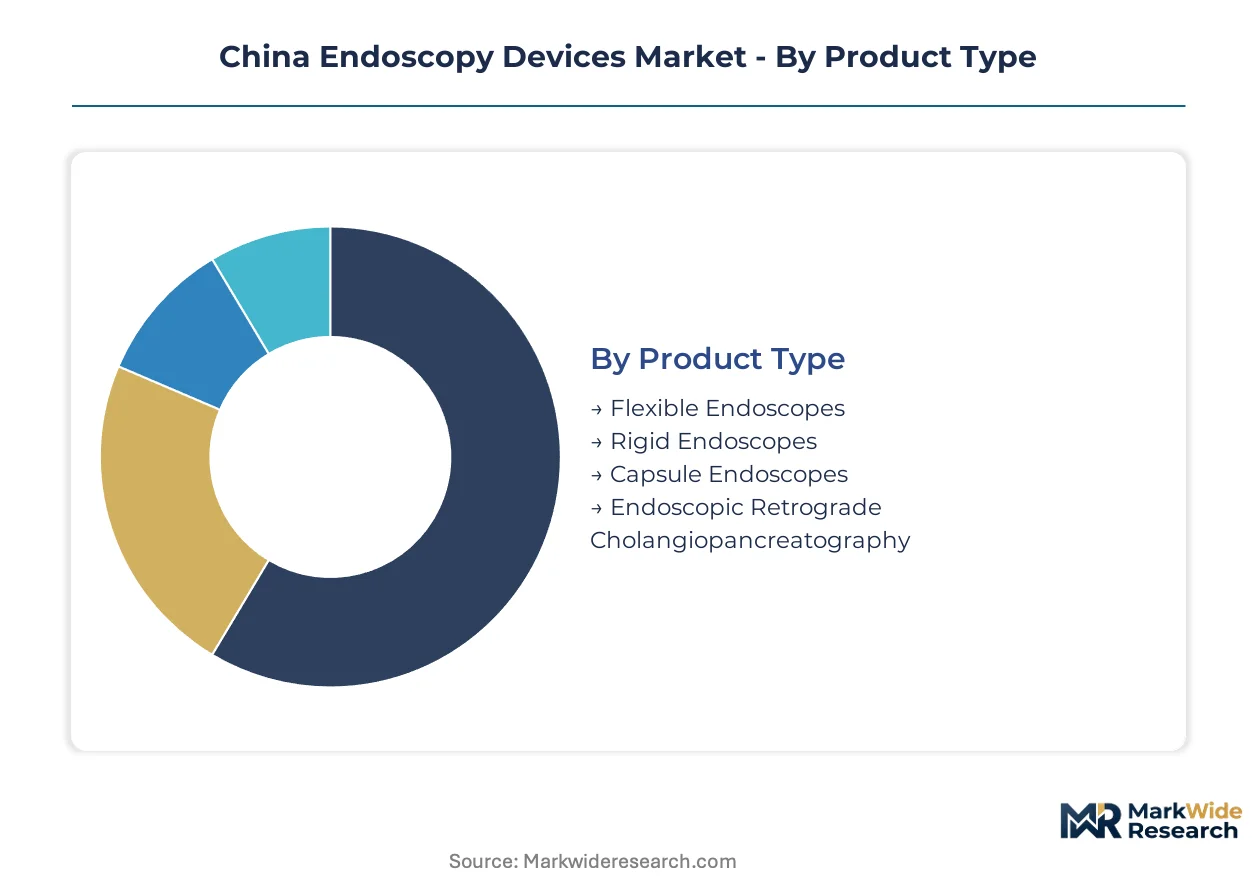
Endoscopy device procurement patterns in China diverge sharply across clinical settings and technological tiers. Capital allocation priorities and reimbursement pathways create distinct demand profiles that manufacturers must navigate through segmented go-to-market strategies.
Product Type:
Capital intensity varies dramatically across instrument architectures, with reusable flexible platforms requiring the heaviest upfront investment in reprocessing infrastructure and technician training.
- Flexible Endoscopes:Articulating insertion tubes with steerable distal tips integrate illumination bundles and working channels for biopsy forceps deployment. Guangdong tertiary hospitals concentrate procurement of high-definition gastroenterology suites driven by screening program volume mandates.
- Rigid Endoscopes:Rod-lens optical systems deliver superior image clarity for confined surgical spaces through fixed insertion profiles. Orthopedic and ENT surgical centers in tier-one cities prioritize these systems for arthroscopy and sinus procedures where maneuverability constraints are acceptable.
- Capsule Endoscopes:Ingestible wireless imagers capture intestinal mucosa during natural peristalsis without sedation requirements.
- Endoscopic Retrograde Cholangiopancreatography:Dual-channel duodenoscopes enable biliary cannulation and stone extraction through the ampulla of Vater.
Most installed capacity flows through flexible endoscope fleets. Expansion is steepest in capsule endoscopy as patient preference for non-sedated alternatives intensifies.
Application:
Procedure reimbursement rates and screening program mandates determine which clinical domains absorb the majority of capital equipment budgets.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures dominate hospital endoscopy suite utilization schedules. Jiangsu province health authorities have centralized procurement for gastroenterology visualization platforms across county-level hospital networks.
- Pulmonology:Bronchoscopy suites require specialized suction capabilities and narrow working channels for transbronchial needle aspiration. Beijing tertiary hospitals are expanding interventional pulmonology capacity for lung cancer staging procedures.
- Urology:Cystoscopy and ureteroscopy platforms address urinary tract malignancy surveillance and stone disease management.
- Otolaryngology:Laryngoscopy and sinus endoscopy systems serve head and neck surgical workflows.
Gastroenterology commands the largest installed base. Pulmonology is gaining share fastest as lung cancer screening protocols expand nationally.
Technology:
Image sensor migration from fiber optic bundles to solid-state CMOS arrays is redistributing value capture across hardware and software layers.
- Video Endoscopy:Digital imaging processors receive signals from distal tip sensors, enabling real-time enhancement and documentation. Urban medical centers in Shanghai have standardized on 4K video platforms for laparoscopic surgical suites.
- 3D Endoscopy:Stereoscopic visualization restores depth perception lost in conventional 2D laparoscopy, reducing suturing error rates. Sichuan and Shaanxi tertiary hospitals remain undersupplied relative to eastern coastal density.
- Optical Coherence Tomography:Interferometric depth-resolved imaging provides cross-sectional mucosal architecture visualization.
- Wireless Endoscopy:Radiofrequency transmission eliminates tether constraints for capsule and enteroscopy platforms.
Video endoscopy anchors current procurement volumes. 3D visualization is climbing the fastest as surgical precision requirements intensify.
End User:
Facility scale and case complexity determine whether capital purchase or disposable-per-procedure economics prevail.
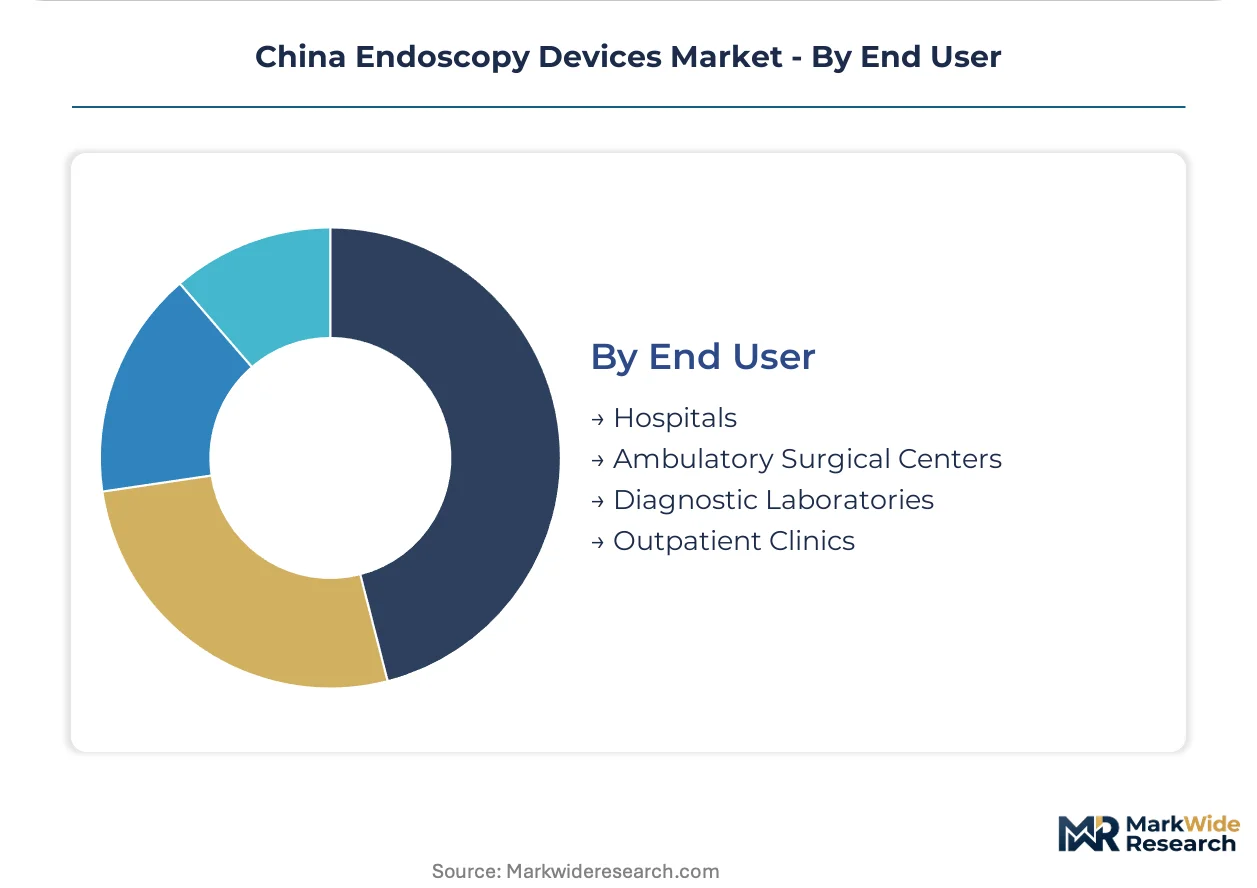
- Hospitals:Tertiary institutions with dedicated endoscopy departments maintain centralized sterile processing facilities and multi-specialty instrument fleets. NMPA innovation fast-tracks accelerate domestic platform evaluations in these settings.
- Ambulatory Surgical Centers:Freestanding facilities prioritize single-use endoscopes to eliminate reprocessing infrastructure investments. Guangdong province has licensed over forty new ASC endoscopy suites in the past eighteen months.
- Diagnostic Laboratories:Independent pathology providers contract for capsule endoscopy reading services.
- Outpatient Clinics:Community-based practices concentrate on screening colonoscopy and flexible sigmoidoscopy.
Hospitals retain dominant installed capacity. Ambulatory surgical centers are expanding most quickly as provincial authorities liberalize site-of-service regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's CMOS sensor fabrication infrastructure outpaces German optical glass supply chains in serving Chinese endoscopy device assembly lines, while South Korean display panel manufacturers compete for visualization processor contracts in Shanghai surgical suites.
Guangdong Province
Tertiary hospital clusters in Guangzhou and Shenzhen generate concentrated demand for high-definition gastroenterology suites driven by provincial screening program mandates. NMPA innovation fast-tracks accelerate domestic platform evaluations in these settings. The Pearl River Delta medical device manufacturing corridor supplies flexible endoscope insertion tubes to assembly facilities across the province.
Jiangsu Province
County-level hospital networks have centralized procurement for gastroenterology visualization platforms under provincial health authority directives. GB electrical safety compliance testing extends validation timelines for novel illumination fiber materials. Nanjing and Suzhou host sterile processing technician training centers addressing workforce scarcity constraints.
Beijing-Tianjin-Hebei
Interventional pulmonology capacity expansion for lung cancer staging procedures drives bronchoscopy suite investments in Beijing tertiary hospitals. SAMR pricing surveillance mechanisms monitor premium video endoscopy platform transactions. The Beijing medical technology corridor concentrates AI-assisted polyp detection algorithm development partnerships.
Sichuan-Chongqing
Western China tertiary hospitals remain undersupplied with 3D visualization platforms relative to eastern coastal density. MEE environmental compliance credits favor domestic producers adopting low-carbon sterilization process technologies. Chengdu medical device distribution hubs serve as transshipment points for western province hospital procurement consortia.
Shandong Peninsula
Qingdao and Yantai manufacturing zones produce rigid endoscope rod-lens optical systems for orthopedic surgical centers. Provincial centralized procurement mechanisms squeeze premium pricing flexibility for imported video endoscopy platforms. The Shandong medical device export processing zone supplies sterilization equipment to domestic endoscope reprocessing facilities.
China Endoscopy Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational instrument developers holding installed base advantages in tertiary hospital visualization suites while domestic assemblers capture single-use disposable economics. The vendor base organizes into three strategic archetypes: optical technology specialists leveraging lens assembly heritage, diversified medical device conglomerates cross-selling surgical platform ecosystems, and domestic challengers exploiting NMPA registration speed and manufacturing cost structures. Competitive moves concentrate on service contract unbundling into modular software subscriptions and sterile processing infrastructure partnerships that lock in fleet management relationships.
Among Japan-originating optical specialists, Olympus Corporation exemplifies the service-anchored archetype through nationwide maintenance infrastructure deployment. German precision instrument developers including KARL STORZ SE & Co. KG occupy positions within rigid endoscope specialization tiers for surgical suite applications. Chinese domestic manufacturers represented by Mindray Bio-Medical Electronics sit within the cost-optimized, rapid-registration archetype targeting provincial procurement channels.
| Leading Market Players |
|---|
| Johnson & Johnson |
| KARL STORZ SE & Co. KG |
| Olympus Corporation |
| Mindray Bio-Medical Electronics |
| Stryker Corporation |
| Medtronic plc |
| Fujifilm Holdings |
| Shanghai Aohua Photoelectricity Endoscope |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals and MEE green manufacturing directives gate qualified supply access for sterilization equipment and single-use device producers, while simultaneously stratifying pricing tiers across NMPA-certified premium platforms and unbundled software subscriptions. Domestic manufacturers capturing environmental compliance credits command premium positioning in provincial procurement channels, whereas import-dependent assemblers face cost compression from carbon-border adjustment exposure.
Pricing Analysis
Capacity additions in Jiangsu and Guangdong provinces are reshaping price floors for CMOS-based visualization platforms as domestic manufacturers exploit NMPA fast-track registrations. Three-tier pricing structure across premium, standard, and economy levels differentiates by NMPA certification grade and after-sales service bundling, with tier-two hospital buyers exhibiting highest price sensitivity and tertiary urban centers least. Pricing pressure stems from provincial centralized procurement mechanisms squeezing imported video endoscopy margins.
Supply Chain Analysis
Endoscope refurbishment and reprocessing equipment remanufacturing flows concentrate in Shandong and Jiangsu manufacturing zones, feeding secondary market demand from county-level hospital networks. Optical glass supply draws from German and Japanese lens assembly suppliers, while CMOS sensors source from South Korean and Japanese fabrication facilities. Single-source vulnerability in illumination fiber inputs creates tariff exposure through trans-Pacific logistics corridors. Distribution runs through Pearl River Delta medical device corridors into western province transshipment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as tertiary hospital procurement shifts toward 4K visualization and AI-assisted detection specifications that command lifetime value pricing. Premium-tier differentiation now hinges on software-defined functionality and sterile processing infrastructure partnerships rather than hardware refresh cycles alone.
For Market Incumbents: Anchor service contract unbundling strategies to capture recurring revenue from installed flexible endoscope fleets, countering domestic challenger pressure through rapid NMPA software upgrade pathways. Prioritize backward integration into CMOS sensor sourcing to reduce Japanese supplier dependency exposure. Defensive consolidation through sterile processing technician training center partnerships locks in fleet management relationships across Guangdong and Jiangsu hospital consortia.
For New Entrants and Emerging Players: Western province ASC operators represent the most penetrable buyer archetype, as Sichuan and Shaanxi ambulatory surgical centers remain undersupplied with single-use endoscope economics relative to eastern coastal density. Target infection-sensitive department procurement in tier-two cities where reprocessing infrastructure scarcity favors disposable-per-procedure models. Go-to-market execution through Chengdu distribution hub partnerships enables western province hospital procurement consortia access without direct tertiary hospital sales force investment.
For Investors and Strategic Acquirers: Roll-up economics work for domestic CMOS-platform specialists because NMPA innovation fast-tracks accelerate registration timelines relative to multinational incumbent pathways, creating consolidation arbitrage. Five-to-ten year viability centers on software subscription attach rates and environmental compliance credit monetization. Monitor NMPA policy revisions on predicate-free breakthrough device approvals as inflection indicator for domestic substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovation Fast-Track Registration | Accelerates time-to-market for domestic CMOS-based platforms in tertiary hospital evaluations. |
| Sterile Processing Infrastructure Partnership | Locks in fleet management relationships across Jiangsu county-level hospital networks. |
| AI-Assisted Polyp Detection Software Development | Creates premium service tier differentiation in Beijing and Shanghai urban screening centers. |
| Single-Use Endoscope Manufacturing Scale-Up | Captures ASC demand growth as Guangdong liberalizes site-of-service regulations. |
| Dual Carbon Manufacturing Compliance Investment | Qualifies domestic producers for MEE environmental credits and provincial procurement preference. |
Study Parameters
Coverage spans eastern coastal provinces, western China corridors, and Beijing-Tianjin-Hebei clusters, with primary inputs from each region combined with secondary validation. Interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and sterile processing technicians informed demand-side dynamics. Secondary sources include NMPA registration databases, provincial centralized procurement announcements, hospital procurement records, and MEE environmental compliance filings. Bottom-up installation base modeling triangulates against top-down healthcare expenditure flows.
Granularity-level modeling disaggregates volume and value outputs by product architecture, clinical application, imaging technology tier, and facility type across the projection horizon. Segmentation dimensions include flexible versus rigid versus capsule instrument categories, gastroenterology versus pulmonology versus surgical specialty applications, and hospital versus ASC versus diagnostic laboratory end-user settings. CAGRs derive from procedural volume trend extrapolation, equipment replacement cycle analysis, and technology migration assumptions. Forecast inputs incorporate NMPA registration pipeline tracking and provincial screening program mandate implementation schedules.
Inputs from hospital procurement databases and NMPA filing records were available through the study window; gaps in real-time ASC licensing data introduce uncertainty bands around ambulatory surgical center expansion trajectories. Forecasts reflect documented assumptions regarding CMOS sensor cost curves and sterilization regulation evolution. Practitioners should monitor NMPA guidance revisions on innovative device review timelines and provincial dual carbon implementation intensity for early signals of domestic substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Japan Endoscopy Devices Market
Endoscopy
United Kingdom Endoscopy Devices Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Endoscopy Operative Devices Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
Capsule Endoscopy Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Global Endoscopes Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Australia Endoscopy Devices Market
Endoscopy
High-Resolution Anoscopy Market