
 Endobronchial Ultrasound Biopsy Market | 2026-2036
Endobronchial Ultrasound Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Endobronchial Ultrasound Biopsy Market Analysis
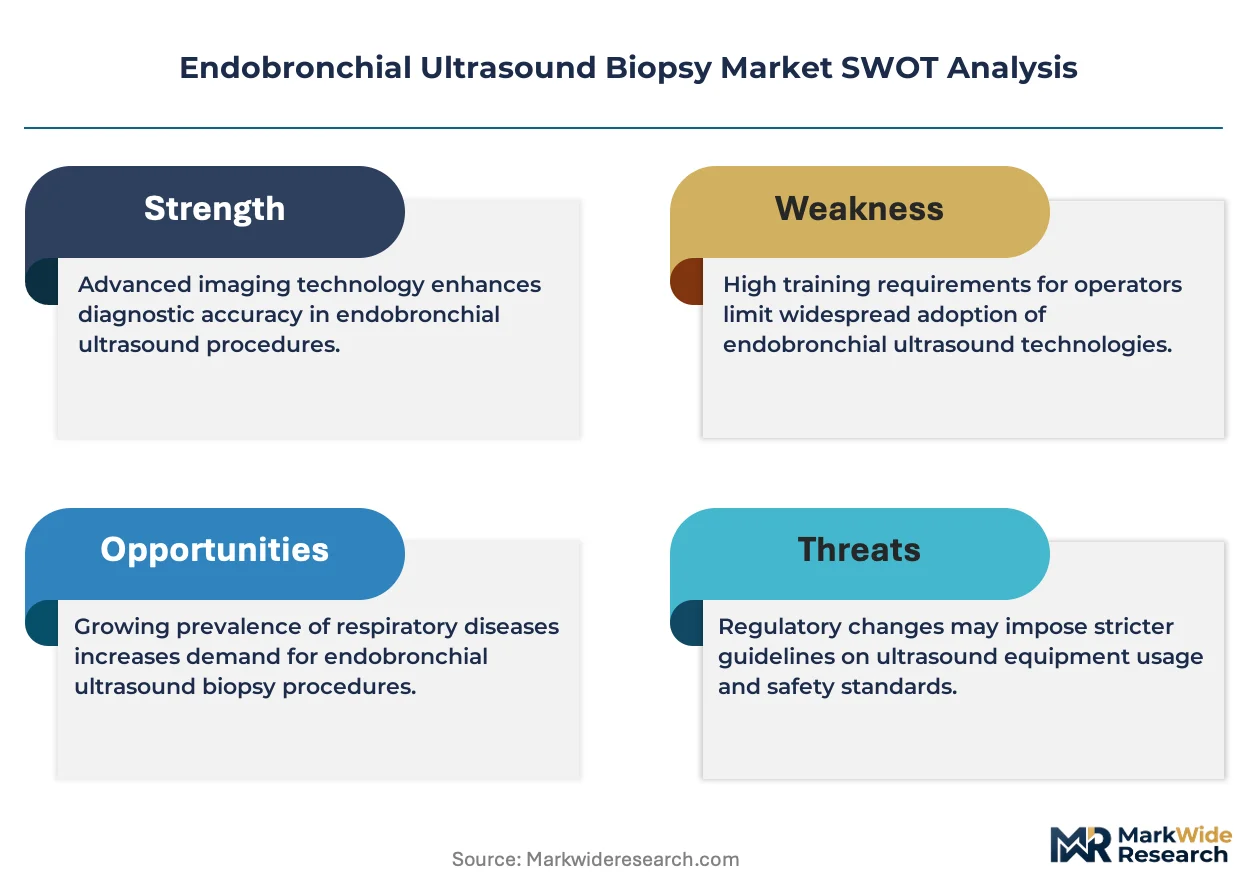
High-definition imaging specification tiers is bifurcating the competitive landscape into premium visualization platforms and cost-optimized alternatives. Olympus Corporation leverages its optical engineering heritage to sustain leadership in flexible bronchoscope resolution benchmarks. Boston Scientific Corporation competes through specialized needle system portfolios designed for transbronchial aspiration precision. FUJIFILM Holdings Corporation anchors its position via integrated ultrasound-processor ecosystems that reduce procedural setup complexity.
Endobronchial ultrasound biopsy employs a bronchoscope-mounted ultrasonic transducer to visualize mediastinal and peribronchial structures, enabling real-time needle aspiration of lymph nodes and lesions under sonographic guidance with operating frequencies typically ranging from 5 to 20 MHz. Linear EBUS technology dominates procedural revenue due to its utility in lung cancer staging and nodal sampling, while robotic-assisted platforms represent the fastest-growing segment as hospitals seek to standardize diagnostic yield across operator experience levels. Needle systems command concentrated margin pools because disposable consumption scales directly with procedure volume and repeat sampling protocols.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device commercialization, with the former mandating substantial equivalence demonstrations for new bronchoscopic ultrasound platforms and the latter enforcing risk-based process controls across manufacturing. The EU Medical Device Regulation imposes enhanced clinical evidence thresholds for Class IIa and IIb bronchoscopic instruments entering European markets. Stakeholders must monitor reimbursement coding revisions for EBUS-guided procedures and interventional pulmonology workforce expansion rates as determinants of installed base utilization.
Market Dynamics
Robotic-assisted bronchoscopy platforms are compressing operator-to-operator diagnostic yield variance, forcing academic medical centers to accelerate replacement cycles for conventional flexible systems and reshaping capital allocation across interventional pulmonology service lines.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for minimally invasive bronchoscopic devices with substantial equivalence demonstrations accelerate hospital procurement decisions and reduce time-to-revenue for manufacturers.
- Interventional pulmonology workforce expansion:Fellowship program growth at major academic medical centers in the United States creates sustained installed base utilization and drives repeat consumable demand for needle systems.
- Linear EBUS staging protocols:Standardized lung cancer nodal sampling guidelines from oncology societies embed linear transducer technology into clinical pathways, locking in procedure volume growth.
Market Restraints
- Capital equipment intensity:Robotic bronchoscopy platforms require substantial upfront investment and dedicated procedure room infrastructure, limiting penetration at community hospitals and ambulatory surgical centers.
- Disposable needle cost structure:Single-use aspiration needles and specimen collection devices generate recurring per-procedure expenses that strain fixed reimbursement rates under current coding frameworks.
- EU MDR clinical evidence thresholds:Enhanced documentation requirements for Class IIb bronchoscopic instruments entering European markets extend commercialization timelines and inflate regulatory compliance costs.
Strategic Opportunities
- Outpatient bronchoscopy migration:Ambulatory surgical centers in the United States seek compact ultrasound-processor ecosystems that reduce procedural setup complexity and enable same-day discharge protocols.
- Artificial intelligence integration:Real-time image analysis algorithms paired with EBUS platforms promise automated lesion detection and standardized sampling guidance across operator experience levels.
- Needle system portfolio expansion:Specialized aspiration devices designed for transbronchial tissue acquisition beyond lymph nodes open adjacent revenue pools in peripheral lung lesion diagnosis.
Industry Challenges
- Operator training bandwidth:Robotic platform adoption requires dedicated proctoring and credentialing pathways that strain interventional pulmonology fellowship programs and extend deployment timelines.
- Reimbursement coding lag:Current procedural terminology for EBUS-guided sampling fails to capture robotic assistance complexity, creating margin pressure as hospitals absorb capital amortization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endobronchial Ultrasound Biopsy Market |
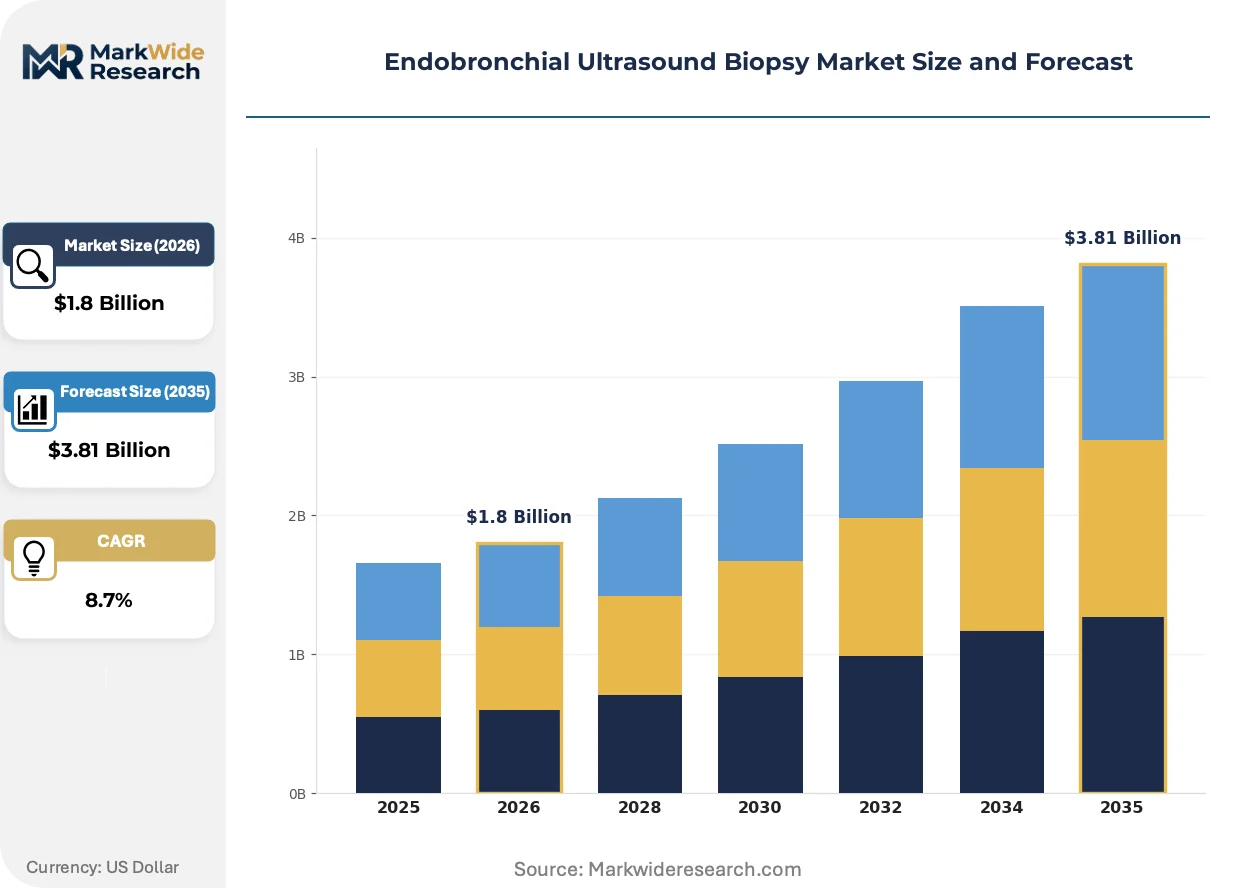
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bronchoscope, Needle Systems, Ultrasound Machines, Accessories Application: Lung Cancer, Mediastinal Masses, Sarcoidosis, Tuberculosis End User: Hospitals, Diagnostic Centers, Research Institutions, Specialty Clinics Technology: Radial EBUS, Linear EBUS, Conventional Bronchoscopy, Robotic-Assisted |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, FUJIFILM Holdings Corporation, GE Healthcare, Siemens Healthineers, Cook Group Incorporated, Medtronic, Pentax Medical, Medi-Globe Technologies GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endobronchial Ultrasound Biopsy Market Emerging Trajectories
Digital imaging pipelines and single-use bronchoscope alternatives are compressing traditional equipment economics while expanding access points for diagnostic bronchoscopy beyond tertiary referral centers.
High-definition CMOS sensor technology is fragmenting the flexible bronchoscope landscape into modular visualization systems that separate image capture from proprietary processor architectures. Community hospitals and ambulatory centers adopt these platforms to avoid locked-in service contracts and enable component-level upgrades. This modularity is fragmenting vendor control over replacement cycles and redirecting margin capture toward disposable sheaths and single-use distal tips.
The EU Medical Device Regulation imposes enhanced post-market surveillance and clinical evidence requirements for bronchoscopic ultrasound platforms entering European markets. Manufacturers must maintain systematic literature reviews and periodic safety update reports across their device portfolios. Class IIb instruments face the steepest compliance burden, prompting some suppliers to prioritize FDA 510(k) clearance pathways for initial commercialization.
Hospital procurement committees now bundle EBUS system acquisitions with multi-year needle supply agreements and service training packages. This consolidation displaces standalone equipment purchases and shifts vendor selection criteria toward total cost-of-ownership models. Academic medical centers in the United States lead this behavioral shift, using procedure volume commitments to extract preferential pricing on disposable consumption.
Endobronchial Ultrasound Biopsy Market Segmentation
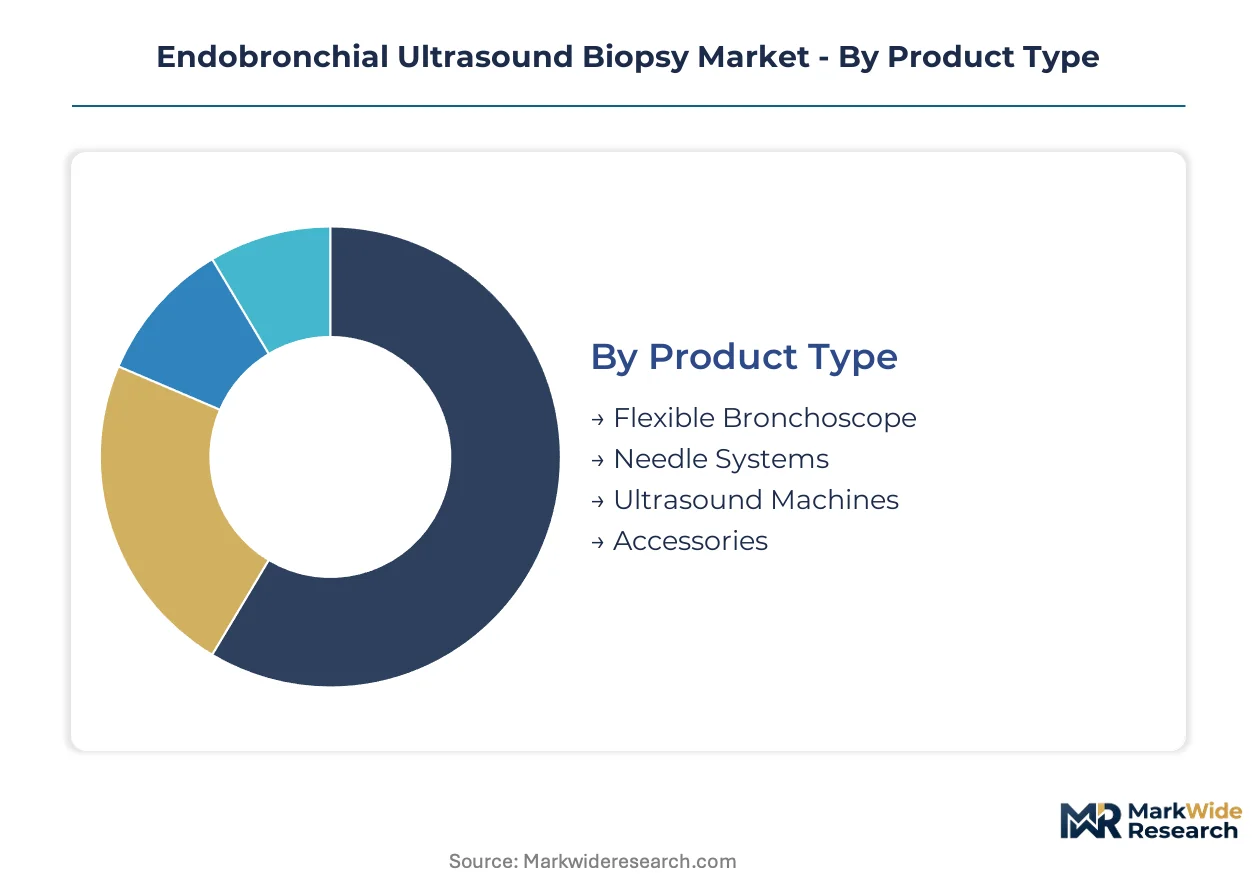
Segmentation in the Endobronchial Ultrasound Biopsy Market reveals how procurement committees allocate capital across visualization hardware, disposable consumables, and service infrastructure. Understanding where margin pools concentrate helps vendors prioritize R&D investment and pricing strategy.
Product Type:
Margin pools concentrate in disposable needle systems and proprietary ultrasound-processor ecosystems that lock hospitals into recurring consumable purchases.
- Needle Systems:Single-use aspiration devices and specimen collection tools feature specialized tip geometries for transbronchial tissue acquisition. Academic medical centers in the United States drive volume through repeat sampling protocols and lung cancer staging guidelines. FDA 510(k) clearance requirements govern design iterations.
- Ultrasound Machines:Integrated processor-transducer ecosystems reduce procedural setup complexity and enable real-time image guidance. Demand clusters at hospitals expanding interventional pulmonology service lines. Capital amortization timelines stretch replacement cycles.
- Flexible Bronchoscope:High-definition CMOS sensor technology fragments procurement toward modular visualization platforms.
- Accessories:Disposable sheaths, suction adapters, and biopsy valves complete procedural kits.
The dominant share belongs to Needle Systems, while Ultrasound Machines is closing the gap fastest.
Application:
Procedure volume scales directly with oncology society guidelines embedding EBUS into standardized diagnostic pathways.
- Lung Cancer:Linear EBUS technology enables real-time mediastinal lymph node sampling under sonographic guidance for TNM staging. United States academic medical centers anchor demand through fellowship-trained interventional pulmonologists. Reimbursement coding frameworks shape hospital investment decisions.
- Mediastinal Masses:Transbronchial aspiration differentiates benign from malignant mediastinal lesions without surgical biopsy. Community hospitals in North America adopt compact systems to retain referrals locally. Diagnostic yield variance drives robotic platform interest.
- Sarcoidosis:Bronchoscopic ultrasound guides transbronchial lung biopsy for granulomatous disease confirmation.
- Tuberculosis:EBUS-TBNA samples mediastinal nodes for mycobacterial culture and molecular testing.
Lung Cancer commands the largest procedure volume, though Mediastinal Masses is expanding most quickly as community sites build capability.
End User:
Procurement authority shifts from standalone equipment purchases toward bundled agreements spanning capital, consumables, and training.
- Hospitals:Academic medical centers lead replacement cycles for robotic-assisted platforms while community hospitals defer capital expenditure. United States health systems negotiate multi-year needle supply agreements tied to procedure volume commitments. Infrastructure requirements limit penetration at smaller facilities.
- Diagnostic Centers:Ambulatory surgical centers seek compact ultrasound-processor ecosystems enabling same-day discharge protocols. Outpatient migration trends concentrate investment in streamlined setup workflows. Reimbursement differentials favor hospital-based procedures currently.
- Specialty Clinics:Interventional pulmonology group practices deploy portable systems for satellite locations.
- Research Institutions:Clinical trial sites utilize EBUS platforms for biomarker collection and device validation studies.
Hospitals retain the dominant installed base, while Diagnostic Centers is climbing the fastest on outpatient migration.
Technology:
Operator experience variance compresses fastest where automation and image guidance standardize procedural execution.
- Linear EBUS:Transducer operating at 5-12 MHz enables parallel needle alignment for real-time mediastinal lymph node aspiration. Oncology society staging protocols embed this technology into clinical pathways. United States fellowship programs train operators on linear transducer manipulation.
- Robotic-Assisted:Electromagnetic navigation and steerable catheters reduce operator-to-operator diagnostic yield variance. Academic medical centers accelerate replacement cycles for conventional flexible systems. Capital intensity limits community hospital adoption.
- Radial EBUS:Rotating transducers at 20 MHz visualize peripheral pulmonary lesions for guided biopsy.
- Conventional Bronchoscopy:White-light examination without ultrasound guidance serves diagnostic and therapeutic indications.
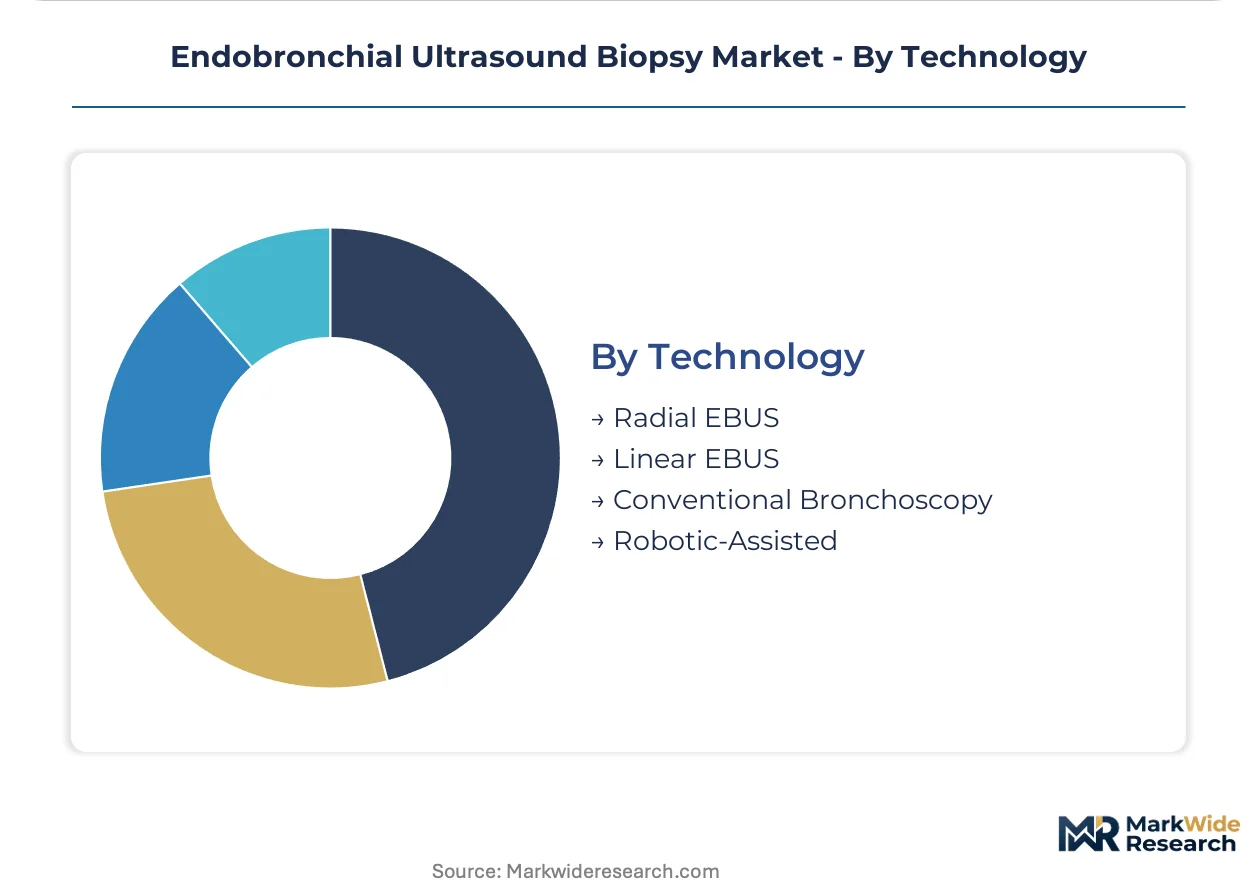
Linear EBUS holds the dominant procedural share, while Robotic-Assisted is gaining share fastest on standardization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters in Japan, Germany, and the United States supply the majority of EBUS platforms worldwide. Procurement decisions at academic medical centers in these markets drive specification standards that diffuse into secondary markets through training networks and reference site influence.
United States
Fellowship-trained interventional pulmonologists at academic medical centers in Boston, New York, and Houston anchor replacement cycles for robotic-assisted bronchoscopy platforms. FDA 510(k) clearance pathways for minimally invasive bronchoscopic devices have tightened post-market surveillance requirements following recent guidance updates. Major health systems in the Southeast and Midwest negotiate multi-year needle supply agreements tied to procedure volume commitments.
Germany
University hospitals in Munich, Heidelberg, and Berlin drive adoption of integrated ultrasound-processor ecosystems that reduce procedural setup complexity. The EU Medical Device Regulation imposes enhanced clinical evidence thresholds for Class IIb bronchoscopic instruments entering European markets. Manufacturing precision clusters in Baden-Württemberg supply optical components to global bronchoscope assemblers.
Japan
Optical engineering heritage concentrated in Tokyo and Osaka sustains leadership in flexible bronchoscope resolution benchmarks. PMDA regulatory frameworks align with international standards while maintaining distinct documentation requirements for novel transducer technologies. Academic medical centers in the Kanto region train operators on linear EBUS manipulation for lung cancer staging protocols.
China
Domestic manufacturers in Shanghai and Shenzhen develop cost-optimized alternatives to premium visualization platforms for hospital procurement committees. NMPA clearance timelines for bronchoscopic ultrasound devices have compressed through priority review pathways for innovative medical equipment. Tier-one hospitals in Beijing and Guangzhou expand interventional pulmonology service lines with imported systems.
United Kingdom
NHS England specialized commissioning frameworks concentrate EBUS procedures at designated cancer centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining conformity assessment routes for established device categories. Academic collaborations in Cambridge and Oxford validate novel needle system designs for transbronchial tissue acquisition.
Endobronchial Ultrasound Biopsy Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates that span visualization hardware, disposable consumables, and service infrastructure. The market structure rewards integrated platform vendors capable of bundling capital equipment with recurring needle supply agreements. Three archetypes dominate: optical engineering specialists leveraging heritage in flexible endoscope design, diversified health technology conglomerates with imaging modality breadth, and interventional device pure-plays focused on aspiration precision. Competitive moves center on multi-year procurement bundling and AI-enabled image guidance partnerships.
Among diversified health technology conglomerates, Boston Scientific Corporation and Medtronic exemplify the integrated device-and-consumable model. Olympus Corporation anchors the optical engineering specialist tier, while FUJIFILM Holdings Corporation occupies a position bridging imaging processor ecosystems with endoscopic hardware. These three entities represent distinct strategic postures: procedure volume capture through disposable scaling, resolution benchmark leadership, and workflow integration through bundled ultrasound-processor platforms.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| FUJIFILM Holdings Corporation |
| GE Healthcare |
| Siemens Healthineers |
| Cook Group Incorporated |
| Medtronic |
| Pentax Medical |
| Medi-Globe Technologies GmbH |
| Others |
Supply Flow & Price Mechanics
Capital equipment utilization rates at academic medical centers in the United States create scale economies that compress per-procedure consumable costs while elevating price floors for premium visualization platforms. This concentration of high-volume sites concentrates vendor bargaining power and locks community hospitals into cost-optimized alternatives.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across EBUS platforms, with substantial equivalence demonstrations separating premium visualization systems from cost-optimized alternatives. ISO 13485 certification tiers differentiate needle system pricing, while volume scale and after-sales service bundling create additional stratification. Cost compression in disposable needle systems is intensifying because fixed reimbursement rates under current CPT coding fail to capture robotic assistance complexity. Community hospitals exhibit highest price sensitivity due to capital constraints, whereas academic medical centers prioritize diagnostic yield over unit economics.
Supply Chain Analysis
Strategic stockpiling of CMOS sensors and optical components dominates inventory strategy among Japanese and German bronchoscope manufacturers, contrasting with just-in-time preferences for disposable needle systems. Manufacturing concentration centers on Japan, Germany, and the United States, with precision optical components drawing from Baden-Württemberg engineering clusters and transducer assemblies resting on Tokyo-Osaka electronics corridors. Single-source vulnerability in high-definition sensor supply creates structural risk. Distribution runs through hospital procurement committees and GPO contracts rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Replacement cycle acceleration at United States academic medical centers signals cyclical recovery driven by robotic platform adoption compressing operator-to-operator variance. Fellowship program expansion sustains installed base utilization through the projection horizon.
For Market Incumbents: Fortify market position by deepening backward integration into CMOS sensor supply and securing multi-year needle supply agreements with Southeast health systems. Emerging pure-play entrants specializing in AI-enabled image guidance threaten margin pools in premium visualization tiers. FDA 510(k) clearance investment remains the priority defensive lever. For New Entrants and Emerging Players: Differentiate on compact ultrasound-processor ecosystems designed for ambulatory surgical center workflows. The most penetrable white space sits in community hospital outpatient bronchoscopy migration, where streamlined setup protocols and same-day discharge enablements command premium positioning. Reimbursement strategy partnerships with regional GPOs accelerate initial traction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among needle system pure-plays with FDA-cleared portfolios and established hospital supply agreements. Long-term viability over the next decade hinges on consumable scaling rather than capital equipment cyclicality. Acquisition targets should demonstrate installed base density in United States academic medical centers. The signal to watch as inflection indicator is interventional pulmonology fellowship program expansion rates at major teaching hospitals.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance enables European market entry for Class IIb bronchoscopic instruments. |
| Hospital System Partnership | Multi-year procurement bundling with Southeast United States health systems secures needle volume commitments. |
| Software Companion Development | Real-time lesion detection algorithms paired with EBUS platforms standardize diagnostic yield. |
| Reimbursement Strategy | CPT coding advocacy for robotic assistance complexity captures capital amortization costs. |
| Backward Integration | In-house CMOS sensor production reduces optical component dependency on German suppliers. |
Methodological Framework
Desk research of FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR technical documentation preceded structured interviews with interventional pulmonologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary fieldwork across Boston, New York, Houston, Munich, and Tokyo validated secondary findings on replacement cycle timing and procurement bundling trends. Bottom-up procedure volume modeling and top-down capital equipment shipment analysis were triangulated against installed base estimates.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume projections weighted by average selling price evolution. Key forecast inputs include fellowship program graduation rates affecting operator supply and EU MDR implementation timelines influencing European commercialization pacing.
Material uncertainties — reimbursement coding revisions, robotic platform adoption curves, and regulatory clearance delays — sit outside the modeled envelope. Forecasts reflect documented assumptions on procedure volume growth and capital replacement cycles. Revision becomes warranted when robotic-assisted diagnostic yield variance compression crosses adoption thresholds triggering accelerated replacement decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Rigid Endoscopes Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Disposable Bronchoscopes Market
Endoscopy
China Arthroscopy Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
US Colonic Stents Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Endoscopy Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
India Endoscopy Devices Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Spain Endoscopy Devices Market