
 Dermatology Endoscopy Devices Market | 2026-2036
Dermatology Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Endoscopy Devices Market Outlook
German optical engineering clusters is recalibrating output priorities toward medical-grade dermatoscope lenses as Asian contract manufacturers scale CMOS sensor integration. DermLite LLC leverages its polarized light patents to dominate North American handheld segments. HEINE Optotechnik GmbH and Co. KG anchors European hospital procurement through its direct sales force and ISO 13485-certified production in Herrsching. Canfield Scientific Inc. competes on software-augmented imaging workflows for melanoma tracking.
Dermatology endoscopy devices combine magnified optical visualization with digital image capture to enable non-invasive examination of skin lesions at 10x to 100x magnification, typically employing cross-polarized or immersion fluid techniques to suppress surface glare and reveal subsurface structures. Their primary purpose is to enhance diagnostic accuracy for pigmented lesion assessment while creating standardized image archives for longitudinal comparison. Optical dermatoscopes retain the largest installed base among product types, though digital endoscopes capture the fastest replacement demand as practices abandon film-based documentation. Videodermatoscopy leads technology adoption in high-volume clinics, while reflectance confocal microscopy concentrates in academic medical centers where reimbursement supports advanced subsurface cellular imaging.
FDA 510(k) clearance pathways govern market entry for digital dermatoscopes in the United States, while the EU Medical Device Regulation requires notified body intervention for Class IIa imaging devices and mandates unique device identifiers for traceability. Germany's KBA does not regulate this sector; instead, Germany's national pharmaceutical and medical device regulator enforces BfArM registration for software-integrated diagnostic systems. Stakeholders must monitor whether FDA draft guidance on artificial intelligence-enabled lesion classification will require premarket submission for algorithm-augmented dermatoscopes already in commercial distribution.
Market Dynamics
The EU Medical Device Regulation's tightened classification requirements for diagnostic imaging equipment is compressing vendor certification timelines while concentrating procurement authority among German dermatology clinics with dedicated regulatory affairs capabilities.
Growth Catalysts
- Teledermatology platform integration:United States health systems are replacing handheld video endoscopy systems at accelerated cycles to enable remote lesion consultation workflows.
- EU MDR traceability mandates:Unique device identifier requirements are forcing clinic infrastructure upgrades that favor digital dermatoscope procurement over optical legacy systems.
- CMOS sensor cost curves:Asian contract manufacturers are scaling medical-grade sensor integration, expanding addressable volume for mid-tier digital dermatoscope segments.
Market Restraints
- Optical component supply concentration:German optical engineering clusters control medical-grade dermatoscope lens production, creating geographic single-point vulnerability.
- Algorithm validation costs:FDA draft guidance on artificial intelligence-enabled lesion classification threatens to require premarket submissions for existing algorithm-augmented devices.
- Reimbursement stratification:Reflectance confocal microscopy remains concentrated in academic medical centers where subsurface cellular imaging receives dedicated procedural codes.
Strategic Opportunities
- Software-augmented melanoma tracking:Image archive standardization for longitudinal comparison represents underpenetrated workflow automation potential in community dermatology practices.
- BfArM registration pathways:Germany's national pharmaceutical and medical device regulator offers streamlined software-integrated diagnostic system approvals distinct from EU MDR complexity.
- Cross-polarized technique expansion:Immersion fluid technique alternatives are enabling non-invasive examination protocols in primary care extension settings beyond specialist dermatology.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for production facilities in Herrsching and comparable manufacturing clusters are extending lead times for new market entrants.
- Legacy film-based documentation migration:Practices abandoning analog archives face data integrity verification costs and staff retraining burdens during digital transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Endoscopy Devices Market |
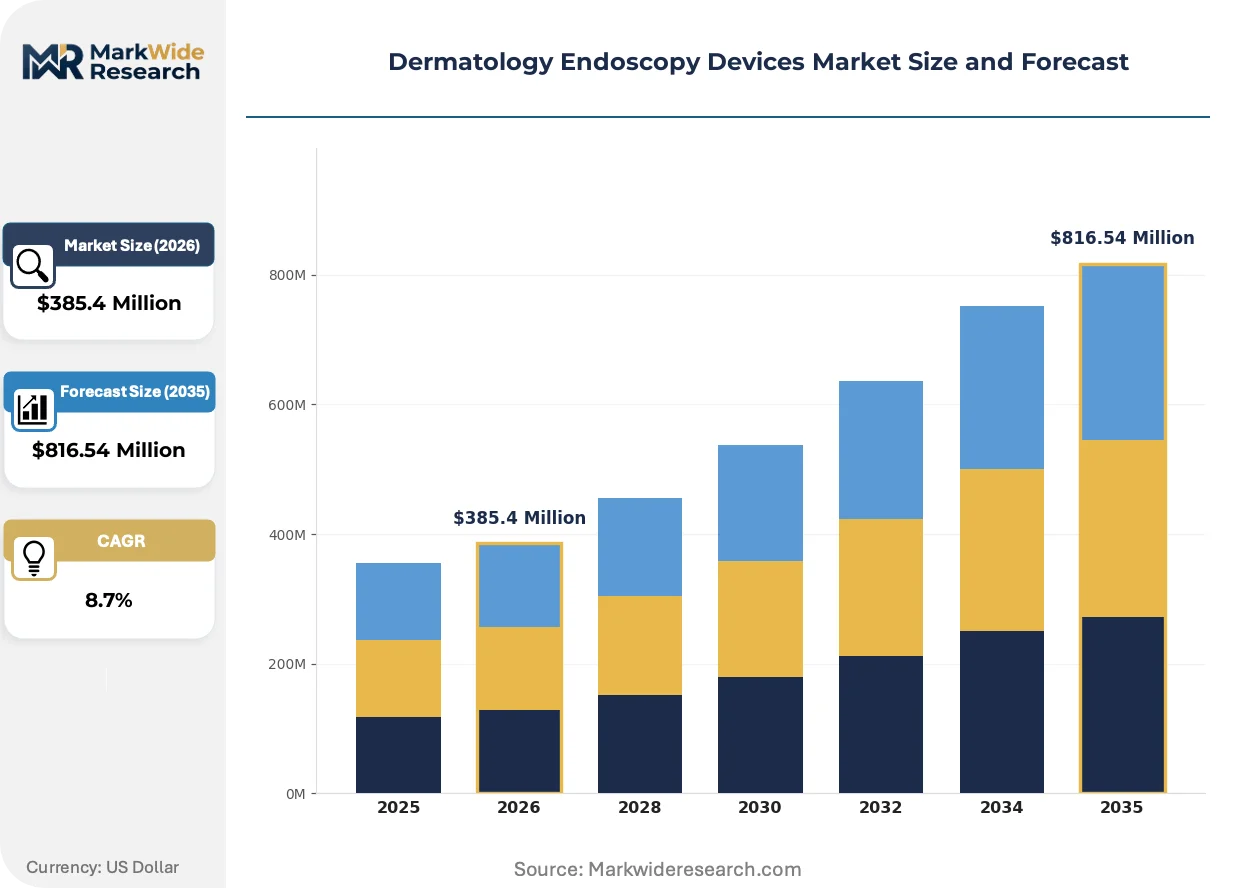
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Dermatoscopes, Fiber-Optic Endoscopes, Digital Endoscopes, Video Endoscopes Application: Skin Cancer Detection, Melanoma Assessment, Psoriasis Diagnosis, Dermatitis Examination End User: Dermatology Clinics, Hospitals, Research Laboratories, Cosmetic Surgery Centers Technology: Videodermatoscopy, Confocal Microscopy, Reflectance Confocal Microscopy, Optical Coherence Tomography |
| Companies Covered | DermLite LLC, MetaOptima Technology Inc., Canfield Scientific Inc., Pixience Healthcare Technology Solutions, 3Gen Inc., HEINE Optotechnik GmbH and Co. KG, DermoScan GmbH, Rudolf Riester GmbH, FotoFinder Systems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Endoscopy Devices Market Strategic Shifts
Digital capture workflows are displacing optical-only examination protocols across dermatology practice settings, compressing the installed base transition timeline while elevating software differentiation as a competitive variable.
Polarized light dermatoscopy is consolidating examination standardization across high-volume United States clinics. The technique suppresses surface glare to reveal subsurface structures at 10x to 100x magnification. Academic medical centers and community dermatology groups are adopting polarized systems at replacement-cycle velocity. This consolidation is compressing demand for immersion-fluid alternatives and elevating patent-protected optical configurations as a vendor moat.
EU MDR Class IIa imaging device requirements are mandating notified body intervention for digital dermatoscope commercialization. The regulation imposes unique device identifiers for traceability across the device lifecycle. German dermatology clinics with established quality management systems are responding by consolidating procurement authority and disqualifying vendors without notified body relationships.
Integrated platform purchasing is displacing standalone device procurement in United States health systems. Hospital-affiliated dermatology groups are bundling handheld video endoscopy with electronic health record connectivity and cloud storage subscriptions. This shift is most visible in Medicare Advantage network contracts where capitated reimbursement rewards longitudinal lesion tracking infrastructure.
Dermatology Endoscopy Devices Market Segmentation
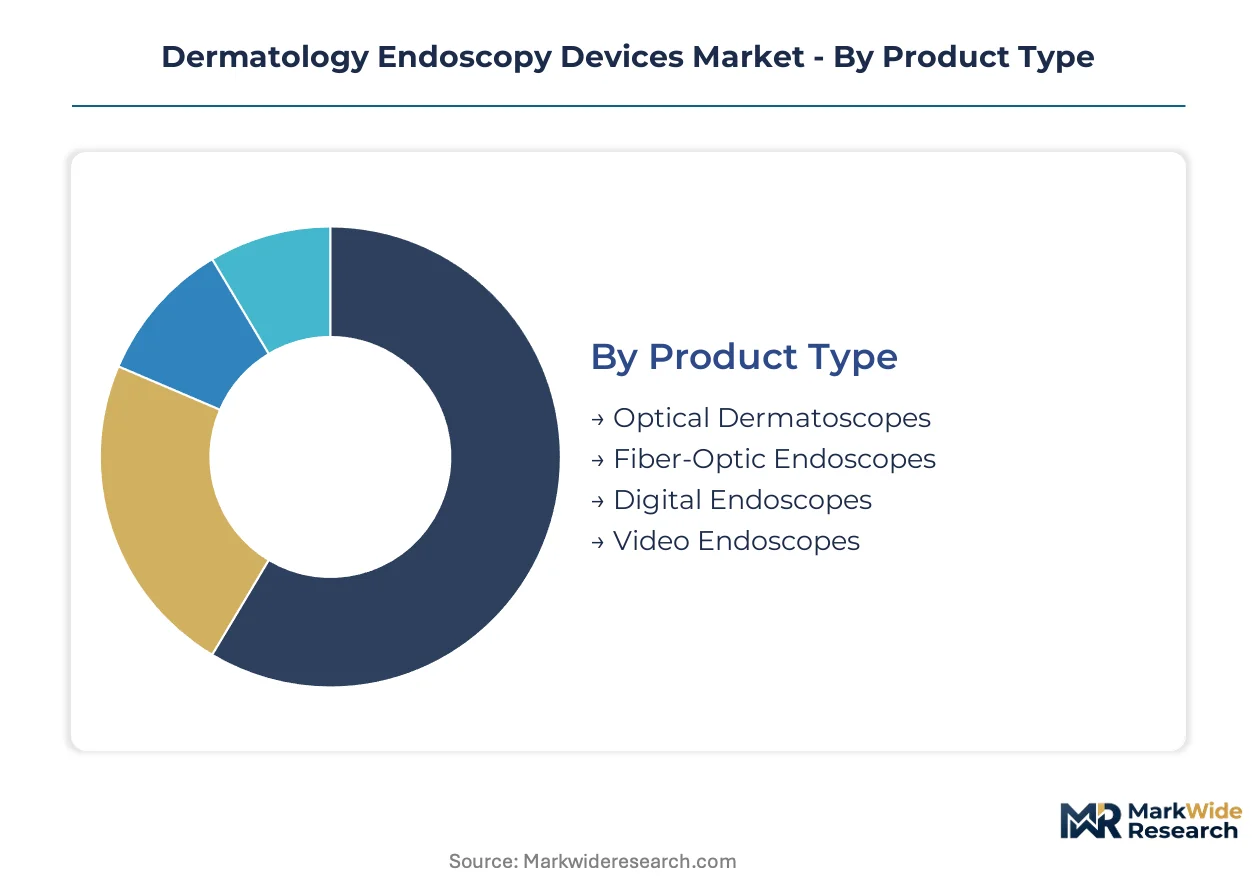
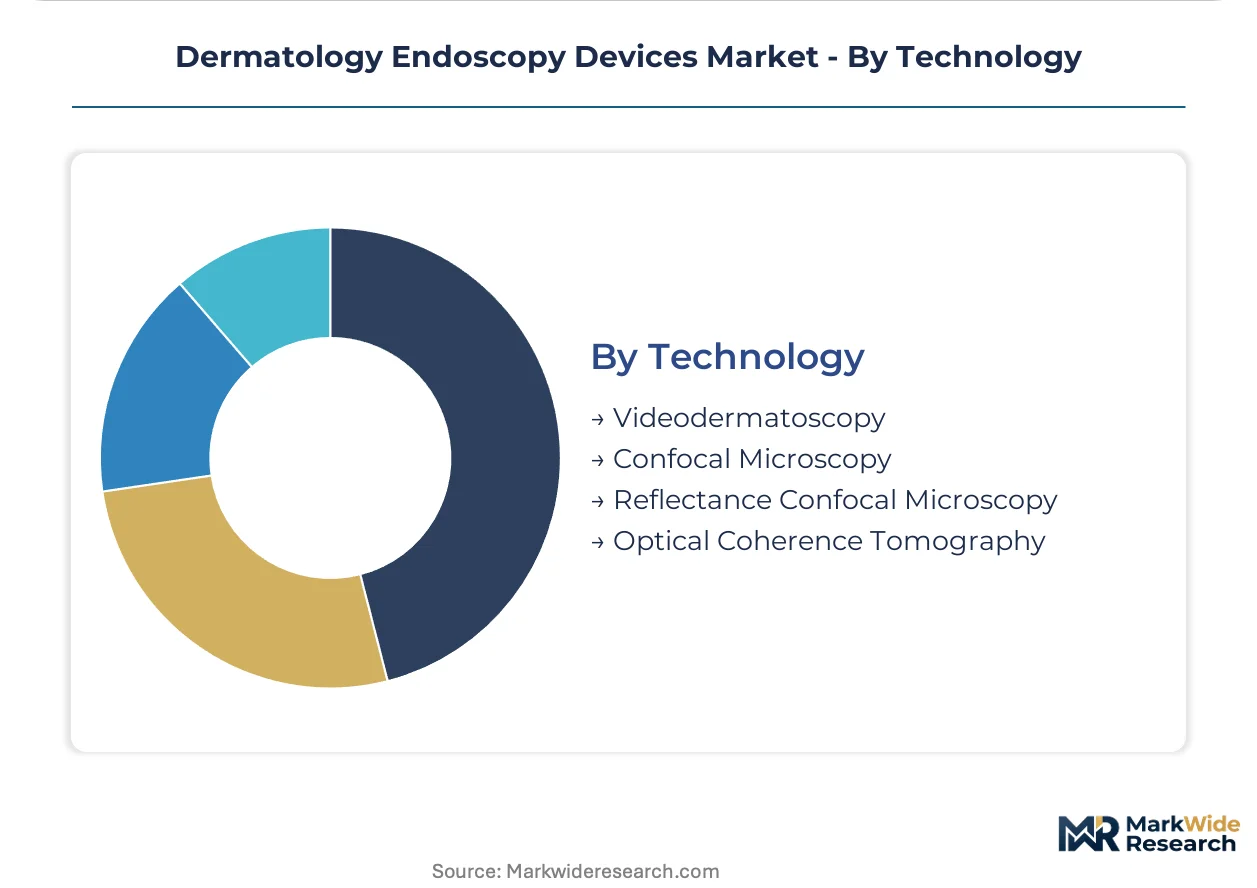
Dermatology endoscopy devices fragment across four distinct axes that determine procurement patterns and technology adoption velocity. Product type and technology classifications drive capital expenditure cycles, while application and end-user segments dictate feature requirements and reimbursement pathways.
Product Type:
Magnification architecture and image capture capability define the competitive tier for each device class.
- Optical Dermatoscopes:Cross-polarized lens systems deliver 10x to 100x magnification without digital capture. Demand concentrates in German dermatology clinics navigating EU MDR transition timelines for legacy equipment replacement.
- Digital Endoscopes:CMOS-integrated sensors enable standardized image archives for longitudinal lesion comparison. United States health systems are accelerating procurement to satisfy teledermatology platform integration requirements and Medicare Advantage capitated reimbursement structures.
- Fiber-Optic Endoscopes:Flexible illumination bundles support narrow anatomical examination. Research laboratories in academic medical centers represent the concentrated installed base.
- Video Endoscopes:Real-time display systems with handheld form factors. Replacement cycles are compressing as integrated platform purchasing displaces standalone procurement.
Mature deployment sits with optical dermatoscopes. Newer deployment is concentrated in digital endoscopes.
Application:
Diagnostic purpose determines reimbursement coding and required imaging depth.
- Skin Cancer Detection:Basal cell carcinoma and squamous cell carcinoma screening protocols drive volume procurement in community dermatology practices. United States clinic networks prioritize devices with FDA 510(k) clearance for pigmented lesion assessment workflows.
- Melanoma Assessment:ABCDE criteria documentation and dermoscopic pattern analysis require high-resolution subsurface visualization. Academic medical centers in Germany concentrate demand for software-augmented melanoma tracking with BfArM-registered diagnostic systems.
- Psoriasis Diagnosis:Plaque morphology documentation supports biologic therapy authorization. Hospital-affiliated dermatology groups represent the primary procurement channel.
- Dermatitis Examination:Eczema and contact dermatitis assessment protocols favor cost-efficient examination devices. Cosmetic surgery centers are expanding adoption for pre-procedure skin condition evaluation.
Reimbursement density peaks with melanoma assessment. Volume expansion is climbing the fastest in skin cancer detection.
End User:
Facility type determines capital budget scale and regulatory compliance burden.
- Dermatology Clinics:Private practice and group practice settings drive replacement-cycle velocity for handheld systems. German clinics with dedicated regulatory affairs capabilities are consolidating procurement authority following EU MDR classification tightening.
- Hospitals:Inpatient and outpatient departments require enterprise-grade connectivity and electronic health record integration. United States hospital systems are bundling device procurement with cloud storage subscriptions.
- Research Laboratories:Translational dermatology and clinical trial endpoints drive demand for reflectance confocal microscopy. Subsurface cellular imaging capabilities concentrate in academic medical center settings.
- Cosmetic Surgery Centers:Aesthetic procedure planning and post-treatment monitoring represent emerging application expansion. Primary care extension settings are adopting cross-polarized technique alternatives for non-specialist examination protocols.
Procurement volume concentrates in dermatology clinics. Technology sophistication peaks in research laboratories.
Technology:
Imaging depth and resolution specification determine device positioning across diagnostic workflows.
- Videodermatoscopy:Digital capture at 10x to 100x magnification with real-time display. High-volume United States clinics are consolidating examination standardization around polarized light configurations.
- Reflectance Confocal Microscopy:Cellular-level subsurface imaging without tissue excision. Academic medical centers command the installed base where dedicated procedural codes support reimbursement.
- Confocal Microscopy:Laser scanning variants for research-grade morphological analysis. Research laboratories in Germany anchor European demand.
- Optical Coherence Tomography:Cross-sectional imaging analogous to ultrasound at optical wavelengths. Experimental deployment in specialized melanoma centers is evaluating diagnostic accuracy against histopathology gold standards.
Commercial maturity centers on videodermatoscopy. Steepest expansion trajectory belongs to reflectance confocal microscopy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical engineering clusters supply medical-grade dermatoscope lenses that anchor European production capacity. Asian contract manufacturers in Taiwan and South Korea scale CMOS sensor integration for digital capture modules. United States health systems drive replacement-cycle velocity through integrated teledermatology procurement.
United States
Medicare Advantage capitated reimbursement rewards longitudinal lesion tracking infrastructure in hospital-affiliated dermatology groups. FDA 510(k) clearance pathways govern market entry for digital dermatoscopes with algorithm-augmented classification features. Greater Boston and Pacific Northwest health systems anchor enterprise-grade connectivity bundling with electronic health record integration.
Germany
Dermatology clinics in Bavaria and North Rhine-Westphalia consolidate procurement authority following EU MDR classification tightening for diagnostic imaging equipment. The country's national pharmaceutical and medical device regulator enforces BfArM registration for software-integrated diagnostic systems distinct from EU MDR complexity. Herrsching anchors ISO 13485-certified production for hospital procurement channels.
China
Domestic CMOS sensor fabrication scales cost-efficient digital dermatoscope modules for mid-tier market segments. NMPA medical device registration governs commercialization timelines for pigmented lesion assessment workflows. Yangtze River Delta contract manufacturers expand medical-grade sensor integration capacity for export markets.
Japan
PMDA regulatory pathways shape approval timelines for reflectance confocal microscopy systems in academic medical centers. METI industrial policy supports precision optics manufacturing for dermatoscope lens assemblies. Kanto region research laboratories concentrate demand for subsurface cellular imaging capabilities.
India
Community dermatology practices in Maharashtra and Karnataka expand adoption of cost-efficient videodermatoscopy systems for skin cancer detection protocols. CDSCO medical device rules govern import registration for handheld video endoscopy equipment. Delhi-NCR diagnostic chains drive volume procurement for teledermatology platform integration.
Dermatology Endoscopy Devices Market Competitive Environment
Global majors compete with regional champions across regulatory certification capabilities and direct sales force coverage. The vendor base stratifies into three tiers: patent-protected optical specialists, software-integrated imaging platform providers, and Asian contract manufacturers scaling sensor integration. Strategic moves concentrate on notified body relationship building for EU MDR compliance and cloud storage subscription bundling for United States health system contracts.
Within the patent-protected optical tier, DermLite LLC and HEINE Optotechnik GmbH and Co. KG exemplify geographic specialization strategies. Canfield Scientific Inc. occupies a position among software-augmented workflow providers competing on melanoma tracking standardization. These three anchors represent distinct competitive archetypes: polarized light configuration dominance, European hospital procurement anchoring, and image archive automation respectively.
| Leading Market Players |
|---|
| DermLite LLC |
| MetaOptima Technology Inc. |
| Canfield Scientific Inc. |
| Pixience Healthcare Technology Solutions |
| 3Gen Inc. |
| HEINE Optotechnik GmbH and Co. KG |
| DermoScan GmbH |
| Rudolf Riester GmbH |
| FotoFinder Systems GmbH |
| Others |
Value Chain & Pricing Dynamics
CMOS sensor integration scaling by Asian contract manufacturers is simultaneously compressing mid-tier digital dermatoscope production costs and concentrating procurement leverage among German optical engineering clusters. This dual dynamic elevates lens assembly premiums while eroding margins on commoditized capture modules.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier vendors from unbundled economy alternatives in United States health system contracts. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and software-augmented melanoma tracking capability. Cost compression in mid-tier digital endoscopes is intensifying because Yangtze River Delta CMOS fabrication scales medical-grade sensor output. Community dermatology practices in India exhibit highest price sensitivity, while academic medical centers in Germany demonstrate lowest sensitivity due to dedicated reimbursement codes for subsurface cellular imaging.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise-grade demand from United States health systems, while distributor networks serve German dermatology clinics. Medical-grade dermatoscope lens production draws from German optical engineering clusters in Herrsching and Bavaria. CMOS sensor modules source from Taiwan and South Korea contract manufacturers. Supply chain risk centers on single-source vulnerability for polarized light optical configurations protected by patent estates. Distribution runs through specialized medical device distributors with notified body relationships for EU MDR compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German ISO 13485-certified production capacity operates at effective utilization ceilings, propping pricing power for lens assembly suppliers. This supply-constrained structure rewards early capacity commitments.
For Market Incumbents: Lock in notified body relationships for EU MDR Class IIa imaging device recertification before competitor queue formation. Anchor hospital procurement channels through direct sales force expansion in Bavaria and North Rhine-Westphalia. Defend against Asian contract manufacturer vertical integration into digital capture module assembly by patent thicketing polarized light configurations. For New Entrants and Emerging Players: Teledermatology platform partnerships offer lowest-friction customer acquisition routes for algorithm-augmented dermatoscope vendors. White-space concentrates in community dermatology practices abandoning film-based documentation for digital archive workflows. Target Maharashtra and Karnataka clinic networks in India with cost-efficient videodermatoscopy systems. Pursue BfArM registration pathways for software-integrated diagnostic systems as differentiation from EU MDR complexity. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to imaging platform consolidators seeking FDA 510(k) clearance portfolios. Long-term viability favors vendors with dual regulatory footprints spanning United States FDA and Germany BfArM jurisdictions. Acquisition target archetype: software-augmented workflow providers with Medicare Advantage network contracts. Monitor FDA draft guidance finalization on artificial intelligence-enabled lesion classification as inflection indicator for algorithm validation cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance for algorithm-augmented pigmented lesion assessment unlocks Medicare Advantage network contracts. |
| CE Marking Pathway | Notified body intervention for Class IIa imaging devices satisfies EU MDR traceability mandates. |
| Hospital System Partnership | Bundled procurement with electronic health record integration anchors United States enterprise demand. |
| Software Companion Development | Melanoma tracking standardization for longitudinal comparison penetrates community dermatology workflows. |
| Reimbursement Strategy | Dedicated procedural codes for reflectance confocal microscopy concentrate academic medical center adoption. |
Study Parameters
Independent corroboration across dermatology clinic procurement managers, biomedical engineers at academic medical centers, GPO contracts administrators, and regulatory affairs specialists at notified bodies underwrites the qualitative findings. Primary interviews with clinicians and hospital purchasing committees combined with secondary validation from FDA 510(k) filings, BfArM registration databases, EU MDR notified body certificates, and hospital procurement records establish demand-side parameters. Bottom-up triangulation across product type shipment estimates and top-down reconciliation against health system capital expenditure disclosures validate market sizing.
Rate-of-change decomposition across the projection horizon separates volume expansion from pricing dynamics. Segmentation dimensions modeled include product type, application, end user, and technology tier alongside regional regulatory cluster differentiation. CAGRs derive from fitted growth curves anchored to replacement cycle velocity and teledermatology platform adoption trajectories. Forecast inputs incorporate CMOS sensor cost curve projections and EU MDR compliance timeline assumptions.
The model holds under stable regulatory classification frameworks; deviation in FDA artificial intelligence guidance finalization or EU MDR implementation enforcement would shift vendor certification timelines. Forecasts reflect assumptions regarding reimbursement code stability for subsurface cellular imaging and teledermatology platform integration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Video Laryngoscope Market
Endoscopy
Endobronchial Ultrasound Biopsy Market
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Mexico Endoscopy Devices Market
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Endoscopic Insufflators Market
Endoscopy
South Africa Endoscopy Devices Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Chile Endoscopy Devices Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Italy Endoscopy Devices Market
Endoscopy
Disposable Bronchoscopes Market