
 Veterinary Endoscopy Devices Market | 2026-2036
Veterinary Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Endoscopy Devices Market Intelligence
Software-as-a-Service (SaaS) platforms for image management and diagnostics is rebalancing the traditional hardware-focused sales model toward recurring revenue streams. Karl Storz SE & Co. KG leverages its strong brand in human medicine to establish a premium position in veterinary rigid endoscopes. Fujifilm Holdings Corporation differentiates through its advanced imaging technologies integrated into flexible endoscopes. Biovision Veterinary Endoscopy LLC specializes in portable and smaller-scale devices for clinics.
Veterinary endoscopy devices are medical instruments designed for minimally invasive examination of an animal's internal organs and cavities. These instruments incorporate fiber optics or digital imaging sensors, with diameters ranging from under 2mm to over 12mm to accommodate various animal sizes. Flexible endoscopes command a significant share for gastrointestinal diagnostics, while rigid endoscopes are prevalent in surgical applications like arthroscopy. Animal hospitals constitute the primary end-user base, while research institutions demand advanced systems with optical coherence tomography.
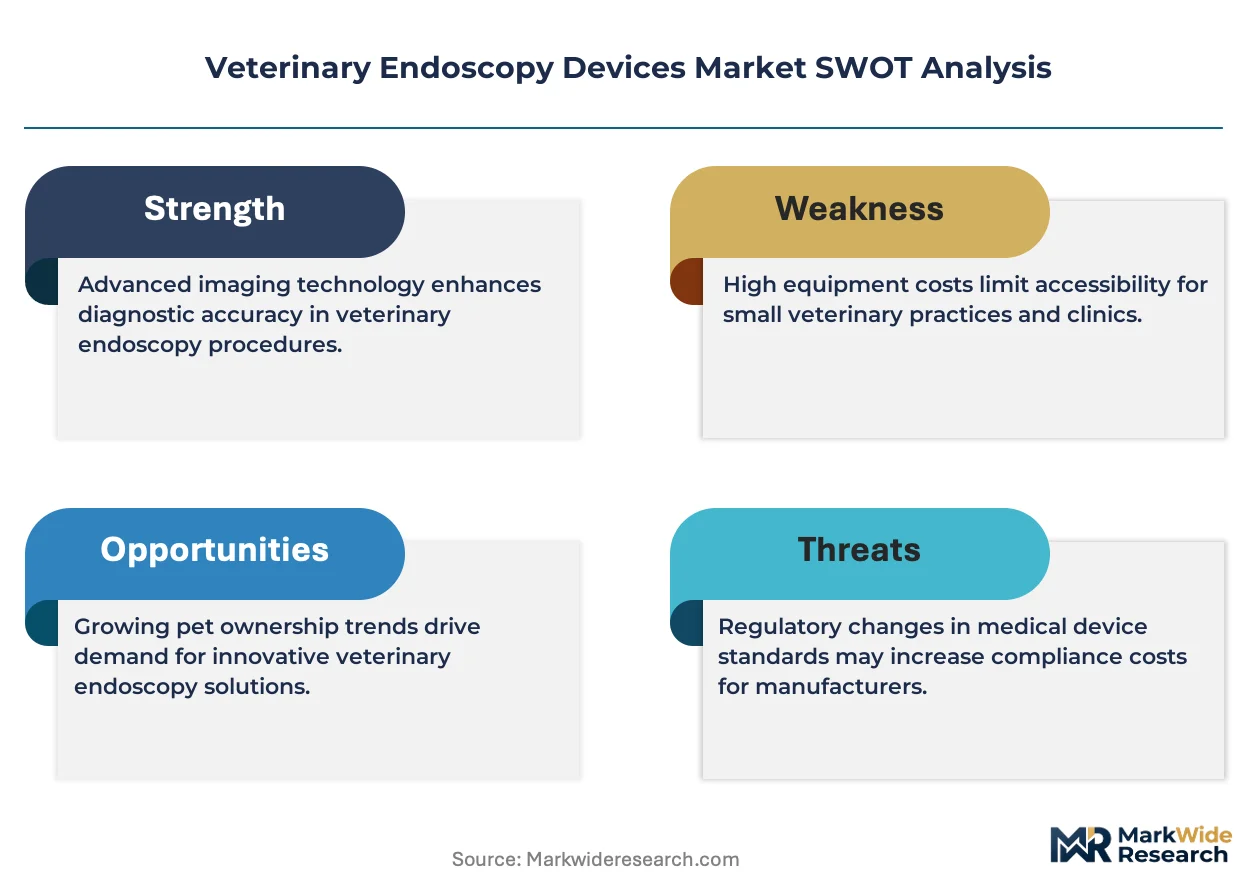
Manufacturers navigate quality standards like ISO 13485 and oversight from regulators including the US FDA's Center for Veterinary Medicine. Compliance with principles from Europe's CE marking framework for human devices increasingly serves as a market differentiator for veterinary equipment. Stakeholder success depends on balancing advanced imaging feature development against the demand for affordable, robust devices for clinical use.
Market Dynamics
The central force shaping the market is the transfer of regulatory and technological standards from human medicine into the veterinary field. This pull, driven by rising pet owner expectations and the formalization of veterinary specialty practices, elevates device quality and expands procedural capabilities beyond basic diagnostics.
Growth Catalysts
- Pet Humanization and Spending:Increased owner willingness to pay for advanced, minimally invasive procedures for companion animals, particularly in North America and Europe, directly fuels demand for specialized endoscopic equipment in private clinics.
- Advanced Imaging Integration:The incorporation of high-definition, narrow-band, and fluorescence imaging technologies, originally developed for human endoscopy, enhances diagnostic accuracy for conditions like early-stage cancer in animals, driving adoption in specialty hospitals.
- Standardization via ISO 13485:Voluntary adoption of the ISO 13485 quality management standard, a benchmark for human medical devices, is becoming a key differentiator, signaling reliability and safety to large institutional buyers and veterinary groups.
Market Restraints
- High Capital Investment:The substantial upfront cost of endoscopic towers, scopes, and associated sterilization equipment remains a significant barrier for smaller, independent veterinary practices and clinics in emerging economies.
- Technical Miniaturization Limits:Developing durable, high-fidelity endoscopes with diameters under 2mm for avian and exotic animal practice presents significant engineering and material science challenges, limiting procedural availability for these segments.
- Veterinary-Specific Regulatory Gaps:Outside of general oversight from bodies like the FDA's Center for Veterinary Medicine, the lack of a globally harmonized, stringent regulatory framework specifically for veterinary devices can lead to inconsistent quality and performance standards.
Strategic Opportunities
- Large Animal and Livestock Applications:There is significant potential for developing endoscopy applications beyond companion animals, specifically for diagnostics and minimally invasive procedures in equine sports medicine and high-value production animals.
- AI-Powered Diagnostic Software:Integrating artificial intelligence algorithms into imaging platforms to assist in lesion detection, characterization, and measurement offers a new value proposition, shifting sales toward software-enabled systems.
- Telemedicine and Remote Consultation:The development of portable, connected endoscopy systems facilitates remote expert consultations and training, enabling general practitioners to perform more complex procedures with specialist guidance.
Industry Challenges
- Specialized Training Scarcity:A shortage of veterinarians and technicians with certified training in advanced endoscopic procedures limits the full utilization of installed equipment and slows the adoption of new techniques.
- Instrument Reprocessing Complexity:Ensuring proper cleaning, disinfection, and sterilization of delicate, small-lumen flexible endoscopes is operationally challenging and costly, posing a risk of cross-contamination and device damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Endoscopy Devices Market |
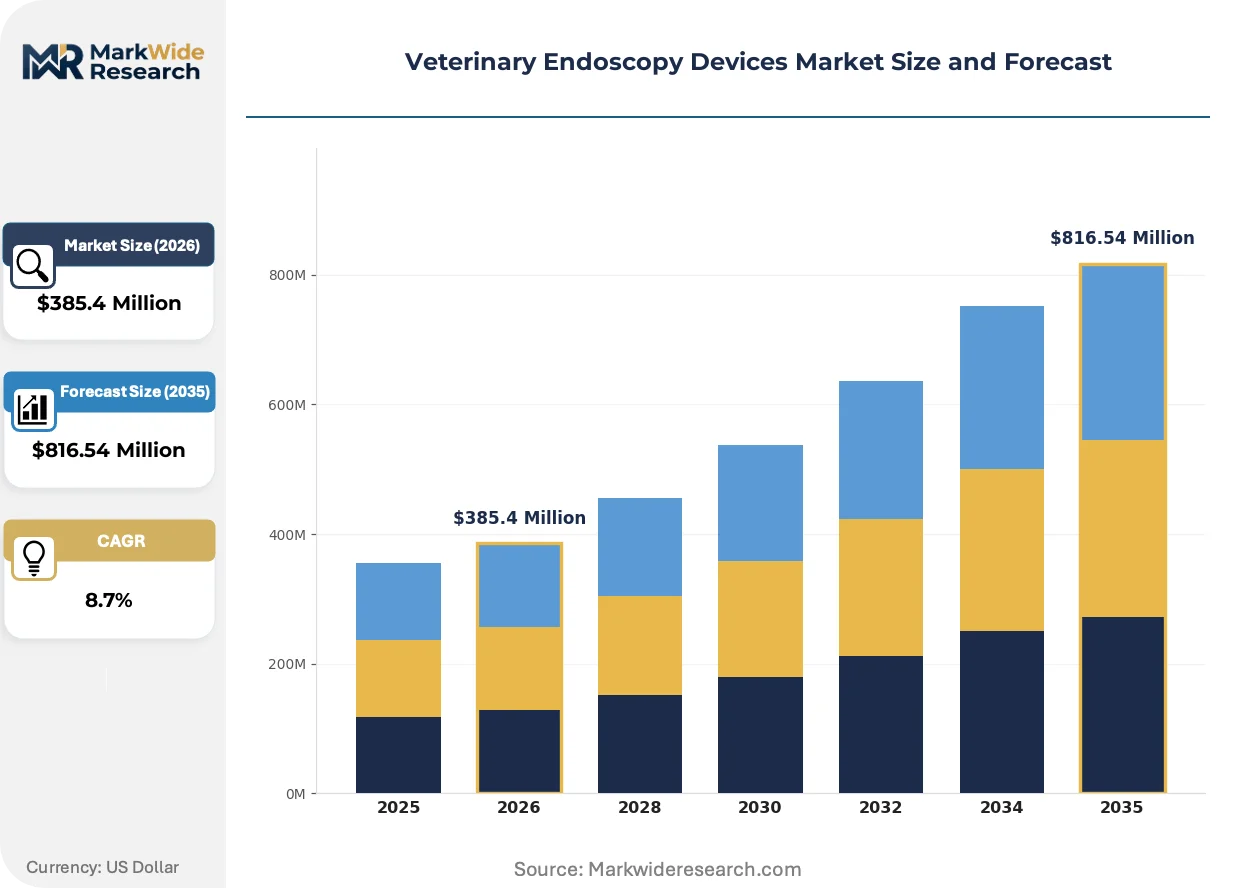
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Endoscopes, Rigid Endoscopes, Video Endoscopes, Accessories Technology: Optical Coherence Tomography, Digital Imaging, LED Lighting, Miniaturization Application: Gastrointestinal Disorders, Respiratory Conditions, Urology, Surgery End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Emergency Services |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Fujifilm Holdings Corporation, Biovision Veterinary Endoscopy LLC, STERIS, Dr. Fritz Endoscopes GmbH, Eickemeyer, Infiniti Medical, HOYA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Endoscopy Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the rapid transfer of technologies and business models from the larger human medical device sector. This migration is accelerating the availability of advanced diagnostic tools while also introducing new service-based revenue streams that challenge the traditional capital equipment sales cycle.
Single-use endoscopes, particularly those utilizing integrated CMOS sensor technology, are emerging to address concerns about reprocessing and cross-contamination. Veterinary hospitals and emergency clinics are the primary adopters, using them for specific procedures where quick turnaround or guaranteed sterility is paramount. This disposable device trend is converging with the established reusable scope market, creating a hybrid ecosystem where clinics choose systems based on procedural volume and economic trade-offs.
Europe's Medical Device Regulation (MDR), while governing human devices, is indirectly elevating standards across the veterinary equipment landscape. The regulation's stringent requirements for quality management and clinical evidence are pressuring manufacturers to improve documentation and post-market surveillance for their veterinary lines. Consequently, companies targeting the European market are increasingly aligning their veterinary device development with principles from ISO 13485 and the MDR framework to demonstrate superior safety and performance.
A notable behavioral change involves a move from standalone hardware sales toward integrated subscription services. This model bundles the endoscopic equipment with SaaS platforms for image archiving, cloud-based sharing for consultations, and sometimes even AI-driven diagnostic aids. This trend is most prominent within large, multi-site veterinary hospital groups in the United States, which prioritize standardized workflows and predictable operational expenditures over large, intermittent capital outlays.
Veterinary Endoscopy Devices Market Segmentation
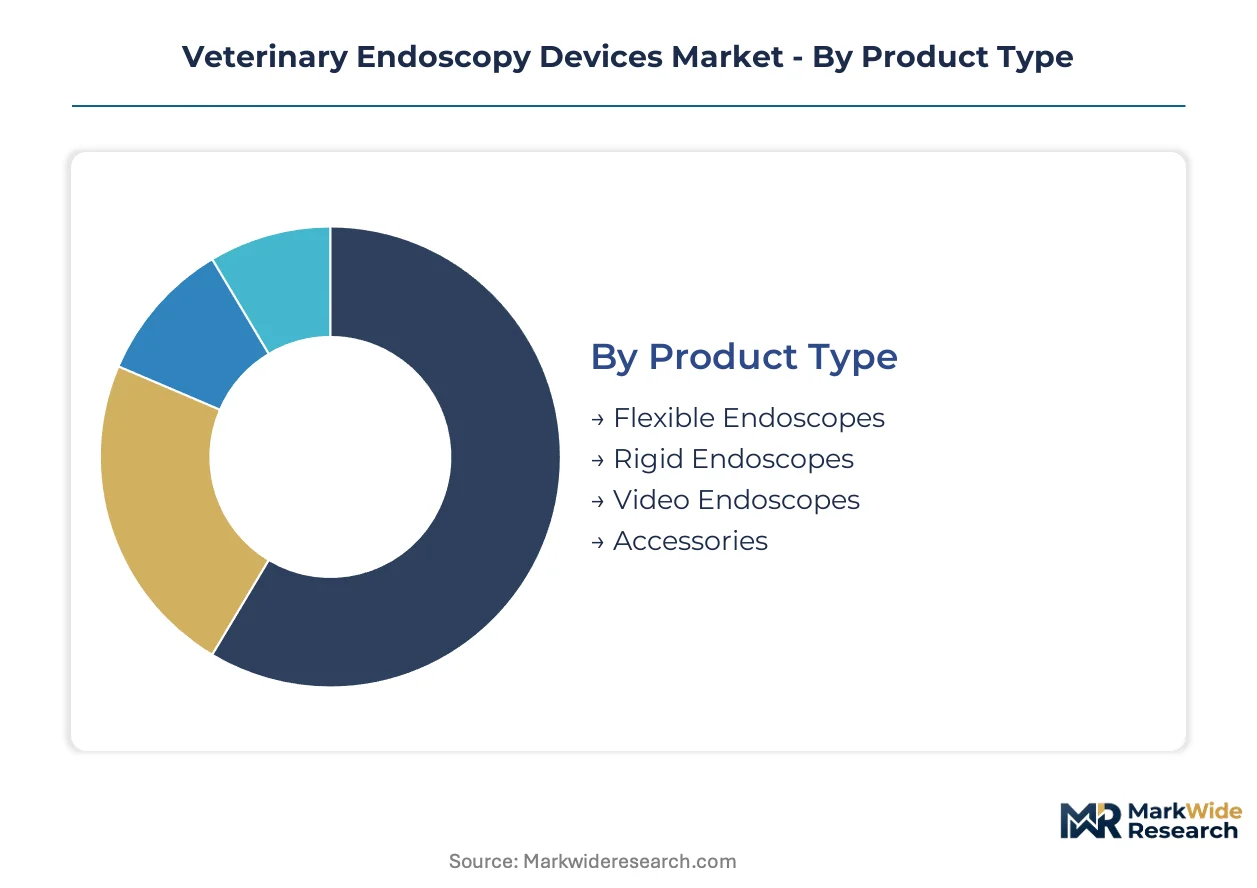
Understanding the segmentation of the veterinary endoscopy devices market reveals distinct demand patterns and technological priorities across different user groups. Device specifications, from diameter to imaging capabilities, directly influence their utility in varied animal sizes and clinical scenarios. This granular view highlights where innovation and investment are most impactful for market participants.
Product Type:
The market for veterinary endoscopy devices shows a clear split between high-volume, general diagnostic tools and premium, specialized surgical instruments. This differentiation influences pricing strategies and distribution channels for manufacturers.
- Flexible Endoscopes:These instruments feature a steerable tip and fiber optic or digital imaging sensors, allowing navigation through tortuous anatomical pathways for internal examination. Demand concentrates in companion animal specialty hospitals, driven by the need for minimally invasive gastrointestinal diagnostics in dogs and cats.
- Rigid Endoscopes:Characterized by a straight, unbending tube with high-definition optics, these devices provide precise visualization for surgical interventions and examination of joint spaces. Demand concentrates in advanced veterinary surgical centers across North America, for procedures like arthroscopy and laparoscopy.
- Video Endoscopes:Integrate a camera sensor directly at the tip, delivering high-resolution images and video directly to a monitor without fiber optic bundles.
- Accessories:Encompass a range of supplementary items such as biopsy forceps, cleaning brushes, light sources, and irrigation pumps, essential for complete endoscopic procedures.
Mature deployment sits with Flexible Endoscopes. Newer deployment is concentrated in Video Endoscopes.
Technology:
Technological advancements in veterinary endoscopy devices span from foundational imaging improvements to highly specialized diagnostic modalities, often reflecting cost-benefit considerations for different clinical settings.
- Digital Imaging:Replaces traditional fiber optic light guides with CCD or CMOS sensors, providing superior image resolution, brightness, and advanced image processing capabilities. Demand concentrates in high-volume clinics seeking enhanced diagnostic accuracy for a diverse range of animal species.
- Miniaturization:Focuses on developing endoscopes with diameters under 2mm, specifically engineered for avian, exotic, and very small companion animal patients, addressing anatomical size constraints. Demand concentrates in specialized practices for smaller patients, driven by a need for less invasive diagnostic and therapeutic options.
- Optical Coherence Tomography:Provides cross-sectional imaging at microscopic resolution, enabling detailed examination of tissue microstructure in research and advanced diagnostic applications.
- LED Lighting:Offers brighter, more consistent illumination with a longer lifespan and reduced heat generation compared to traditional halogen or xenon light sources.
Digital Imaging is expanding most quickly. Optical Coherence Tomography is gaining traction for advanced research.
Application:
The application landscape for veterinary endoscopy devices is broad, ranging from routine diagnostic procedures to complex surgical interventions, each demanding specific instrument characteristics and operator expertise.
- Gastrointestinal Disorders:Involves endoscopic examination of the esophagus, stomach, duodenum, and colon to diagnose conditions like inflammatory bowel disease, foreign body ingestion, or neoplasia. Demand concentrates in companion animal hospitals where chronic digestive issues are common, driving repeat diagnostic procedures.
- Surgery:Utilizes endoscopes for minimally invasive surgical procedures, including arthroscopy for joint examination, laparoscopy for abdominal surgeries, and thoracoscopy for chest procedures. Demand concentrates in specialty surgical centers, driven by benefits of reduced recovery times and patient discomfort.
- Respiratory Conditions:Focuses on examining the nasal passages, pharynx, larynx, trachea, and bronchi to diagnose issues such as infections, foreign bodies, or collapsing airways.
- Urology:Involves endoscopic visualization of the bladder, urethra, and sometimes kidneys, primarily for diagnosing and treating conditions like urinary stones or tumors.
Gastrointestinal Disorders applications are gaining share fastest. Urology applications show consistent growth.
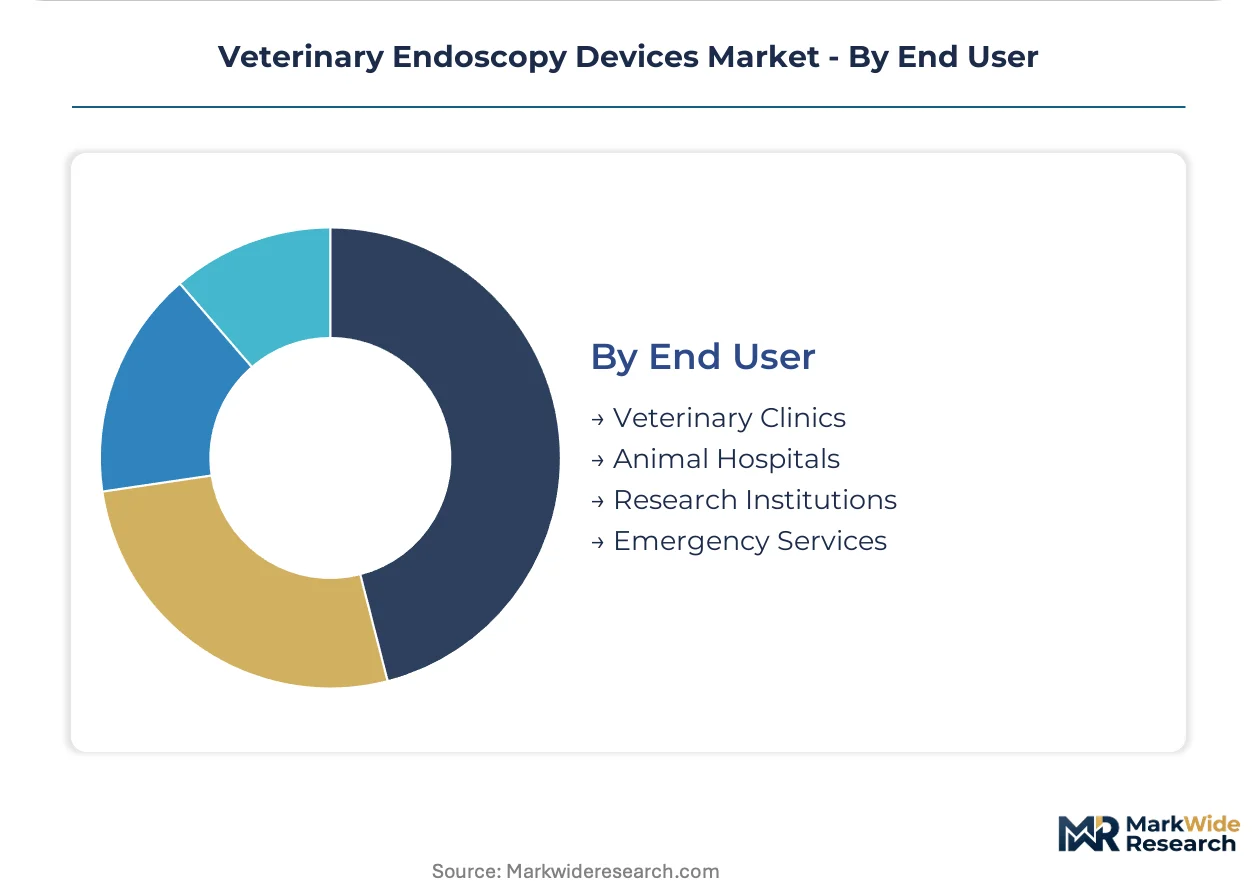
End User:
The end-user base for veterinary endoscopy devices spans a diverse range of facilities, each with unique requirements for equipment sophistication, portability, and throughput.
- Animal Hospitals:Large, multi-specialty facilities offering comprehensive veterinary care, often equipped with advanced diagnostic and surgical departments and handling high patient volumes. Demand concentrates here for versatile, high-end endoscopic systems, driven by a need for diverse diagnostic and surgical capabilities.
- Research Institutions:Academic or private entities focused on veterinary science, animal model development, or pharmaceutical testing, requiring highly specialized and often experimental endoscopic systems. Demand concentrates here for advanced systems, including those with optical coherence tomography, for detailed physiological studies.
- Veterinary Clinics:General practice facilities providing primary animal healthcare, typically requiring more affordable and user-friendly endoscopic solutions for common diagnostic procedures.
- Emergency Services:Provide immediate medical and surgical care for critical animal cases, often prioritizing portable and quick-to-deploy endoscopic equipment for rapid assessment.
Animal Hospitals exhibit the steepest expansion trajectory. Veterinary Clinics represent a stable demand segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global veterinary endoscopy devices market exhibits a notable divide between regions driving technological innovation and those with high consumption rates. Advanced manufacturing hubs in Europe and Asia develop sophisticated systems, while North America leads in demand for specialized diagnostic and surgical equipment. This dual dynamic shapes investment and market penetration strategies across continents.
United States
Demand for veterinary endoscopy devices in the United States stems from high pet humanization and significant pet healthcare expenditure. The US FDA's Center for Veterinary Medicine oversees device safety and efficacy, influencing manufacturer compliance. Major veterinary hospital groups in dense urban corridors like the Northeast prioritize integrated software platforms for imaging.
Germany
Germany's market for veterinary endoscopy devices benefits from a strong tradition of medical device manufacturing and stringent quality standards. Compliance with ISO 13485 and principles from Europe's CE marking framework differentiates local manufacturers. The Stuttgart region, a hub for precision engineering, sees companies developing advanced rigid endoscopes.
Japan
Japan shows a steady demand for veterinary endoscopy, driven by advanced imaging technologies and a focus on companion animal welfare. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous approval processes for veterinary medical instruments. Companies in the Tokyo metropolitan area specialize in miniaturized flexible endoscopes.
United Kingdom
The United Kingdom's veterinary endoscopy market is characterized by rising pet owner expectations and the formalization of specialty practices. Adherence to quality standards influenced by Europe's MDR and ISO 13485 remains crucial for market access. Veterinary referral centers in London and the Southeast increasingly invest in high-definition video endoscopes.
France
France demonstrates consistent growth in veterinary endoscopy, supported by a robust animal healthcare infrastructure. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) regulates medical devices, ensuring product quality. Veterinary clinics in the Lyon region, a center for biosciences, are adopting portable endoscopy systems for diagnostics.
Veterinary Endoscopy Devices Market Key Industry Players
Top-tier vendors anchor the premium segment with advanced, high-end systems, while mid-tier specialists focus on specific applications or cost-effective solutions. The market exhibits a tiered structure, with established medical device giants competing alongside niche veterinary endoscopy providers. Strategic archetypes include integrated solution providers, imaging technology specialists, and portable device innovators. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Within the premium segment, Karl Storz SE & Co. KG and Fujifilm Holdings Corporation represent established players leveraging extensive medical device expertise. Karl Storz SE & Co. KG, a German company, anchors the market for rigid endoscopes with its strong brand heritage, aligning with integrated solution providers. Fujifilm Holdings Corporation, a Japan-based entity, exemplifies differentiation through integrated advanced imaging technologies for flexible endoscopes, positioning itself as an imaging technology specialist. Biovision Veterinary Endoscopy LLC, an American specialist, occupies a position focused on portable and smaller-scale devices tailored for veterinary clinics, serving as a portable device innovator. These companies collectively illustrate the blend of high-end innovation and application-specific solutions across the market.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Fujifilm Holdings Corporation |
| Biovision Veterinary Endoscopy LLC |
| STERIS |
| Dr. Fritz Endoscopes GmbH |
| Eickemeyer |
| Infiniti Medical |
| HOYA Corporation |
| Others |
Cost & Logistics Intelligence
The integration of SaaS platforms is reshaping veterinary endoscopy's cost economics, transitioning from hardware-centric sales to recurring revenue models. This shift influences supply chain concentration, favoring integrated solution providers.
Pricing Analysis
Cost-down pressure on general veterinary clinics accelerates due to high capital investment requirements for endoscopy equipment. The market exhibits a hybrid pricing model, blending per-unit transactional sales for hardware with subscription-based services for SaaS platforms. Price differentiation stems from brand premium, seen with Karl Storz, and advanced imaging features, a Fujifilm strength. Smaller, independent practices remain highly price-sensitive, while large animal hospitals prioritize advanced capabilities and are less sensitive to cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risks in the veterinary endoscopy supply chain. Manufacturing concentration sits in Germany for rigid endoscopes and Japan for flexible imaging technologies, alongside specialized US producers. The supply chain relies on high-precision optics and advanced digital imaging sensors, facing single-source vulnerability for miniaturized components. Distribution runs through direct sales channels for major hospital groups and specialized medical device distributors for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary endoscopy market is currently in a technology-transition phase, as digital imaging sensors increasingly replace traditional fiber optic systems. This shift enables higher resolution and more advanced diagnostic capabilities for clinicians.
For Market Incumbents:Acquire AI-powered diagnostic software capabilities to integrate into existing imaging platforms, countering the threat from specialized software-enabled systems. Deepen investment in R&D for advanced miniaturization, addressing the limitations in exotic animal practice. Expand subscription-based service models to secure recurring revenue streams, mitigating pressure from hardware commoditization. Reinforce ISO 13485 certification to maintain a premium position against emerging competitors.
For New Entrants and Emerging Players:Launch via direct-to-clinic sales channels, offering portable and cost-effective endoscopy solutions for general veterinary practices. Target the underpenetrated large animal and livestock applications, focusing on equine sports medicine. The most penetrable segment involves smaller, independent clinics seeking affordable devices with remote consultation capabilities. Emphasize telemedicine integration as a key go-to-market angle, enabling specialist guidance for general practitioners.
For Investors and Strategic Acquirers:Exit pathways concentrate in niche technology specialists focusing on miniaturization or AI-powered diagnostics. The market maintains strong long-term viability over the next 5-10 years, driven by pet humanization and advanced imaging integration. Acquisition targets should include innovators like Biovision Veterinary Endoscopy, known for portable devices. A critical signal to watch is the development of a globally harmonized regulatory framework for veterinary devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Single-use Endoscopes | Addresses cross-contamination concerns and streamlines procedural workflows in emergency settings. |
| Platform Integration: AI Diagnostic Software | Enhances diagnostic accuracy for lesion detection, improving clinical decision-making for veterinarians. |
| Strategic Partnership: Telemedicine Providers | Facilitates remote expert consultations, extending specialist care to general veterinary practices. |
| Geographic Expansion: Large Animal Applications | Unlocks new market segments for diagnostics and minimally invasive procedures in equine medicine. |
| Regulatory Approval Pathway: EU MDR Alignment | Elevates quality standards and market access for veterinary devices across European markets. |
Research Approach
FDA Center for Veterinary Medicine reports, ISO 13485 standards, and EU MDR guidelines formed the secondary backbone for this analysis. Primary interviews with veterinary specialists, hospital procurement managers, and device engineers provided qualitative insights. This approach combined bottom-up data aggregation with top-down market validation, ensuring robust data integrity. Triangulation across these sources validated market sizing and growth projections.
A bottom-up analytical framework, validated by top-down market assessments, guided the forecast across the analysis window. Segmentation dimensions modeled included product type, technology, application, end user, and animal size. Compound Annual Growth Rates were derived from historical data trends and projected future demand. Key forecast inputs included pet healthcare expenditure trends and veterinary device regulatory approval rates.
Regulatory changes, technological breakthroughs in imaging, and veterinarian training scarcity are the dominant revision risks for market forecasts. These projections reflect current market dynamics and anticipated developments. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Laryngeal Mirrors Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
Endorectal Balloon Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Video Laryngoscope Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
US Colonic Stents Market