
 Robot-Assisted Endoscope Market | 2026-2036
Robot-Assisted Endoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Robot-Assisted Endoscope Market Analytics
Capital-intensity divergence between integrated platform developers and component suppliers is unwinding competitive dynamics in the robot-assisted endoscope sector. Intuitive Surgical Inc. leverages its installed base of multiport systems to sustain recurring instrument revenue. Medtronic anchors its position through upstream control over haptic feedback engineering. Johnson & Johnson competes via its Ethicon endomechanical portfolio paired with robotic docking stations.
A robot-assisted endoscope combines motorized articulation, real-time optical feedback, and surgeon-driven console interfaces to navigate luminal anatomy with submillimeter precision; systems typically employ CMOS sensors capturing 1080p to 4K resolution at 60 frames per second for diagnostic and therapeutic visualization. Flexible endoscopes with automated navigation dominate procedural volume in gastrointestinal applications, while 3D visualization platforms command premium placement in complex pulmonary interventions. Laser imaging modules represent the fastest-expanding technology segment as hospitals prioritize depth-perception accuracy during mucosal resection.
FDA premarket notification requirements and EU MDR conformity assessment procedures govern robot-assisted endoscope commercialization, with both frameworks mandating biocompatibility testing and software validation under IEC 62304 standards. The EU AI Act introduces additional scrutiny for augmented reality guidance algorithms classified as high-risk medical devices. Stakeholders must monitor how Japan's PMDA adapts its sakigake fast-track pathway to accommodate autonomous navigation features before committing regional launch sequencing.
Market Dynamics
Capital-intensity divergence between integrated platform developers and component suppliers is unwinding competitive dynamics in the robot-assisted endoscope sector. Intuitive Surgical Inc. leverages its installed base of multiport systems to sustain recurring instrument revenue. Medtronic anchors its position through upstream control over haptic feedback engineering. Johnson & Johnson competes via its Ethicon endomechanical portfolio paired with robotic docking stations.
Growth Catalysts
- EU MDR conformity assessment:Tightened premarket validation standards under the EU Medical Device Regulation are accelerating hospital procurement of certified systems, compressing replacement cycles for legacy equipment.
- Gastrointestinal procedural volume:Minimally invasive colorectal and upper GI interventions are expanding robot-assisted platform utilization in dedicated surgical centers across the United States, Germany, and Japan.
- CMOS sensor resolution advancement:4K optical modules at 60 frames per second are displacing 1080p standards, enabling submillimeter mucosal visualization that drives system upgrades.
Market Restraints
- Biocompatibility testing costs:IEC 62304 software validation requirements and polymer safety assessments are inflating premarket expenditure for flexible endoscope manufacturers.
- Haptic feedback component concentration:Precision force-sensor supply chains cluster in specialized German and Japanese component foundries, creating input vulnerability.
- Capital equipment substitution:Conventional manual endoscopes retain cost advantage in high-volume screening programs, limiting robot-assisted penetration in budget-constrained health systems.
Strategic Opportunities
- Autonomous navigation algorithms:The EU AI Act's high-risk medical device classification for augmented reality guidance creates first-mover advantage for validated autonomous pathfinding systems.
- Pulmonary intervention expansion:3D visualization platforms command premium placement in complex bronchoscopic procedures, opening therapeutic applications beyond diagnostic gastrointestinal use.
- Japan's sakigake fast-track pathway:PMDA regulatory adaptation for autonomous navigation features enables accelerated market entry relative to standard FDA 510(k) timelines.
Industry Challenges
- Console-to-instrument integration complexity:Surgeon-driven interfaces require specialized biomedical engineering talent for calibration and maintenance, constraining deployment scale.
- Laser imaging module certification timelines:Depth-perception accuracy validation for mucosal resection applications extends regulatory review periods beyond conventional optical systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot-Assisted Endoscope Market |
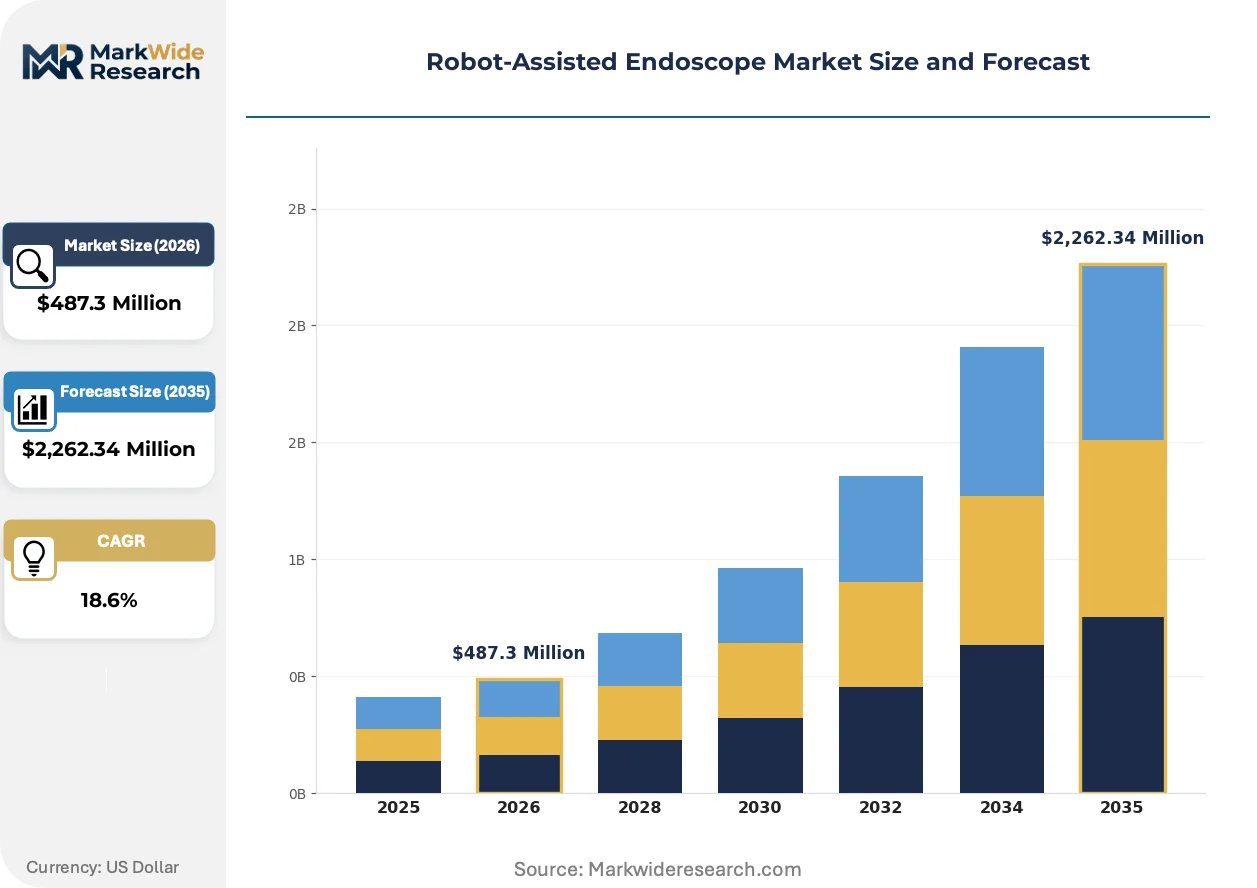
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Endoscope Systems, Flexible Endoscopes, Surgical Robots, Accessories Technology: Laser Imaging, 3D Visualization, Automated Navigation, Augmented Reality End User: Hospitals, Surgical Centers, Research Institutions, Specialty Clinics Application: Gastrointestinal Procedures, Pulmonary Procedures, Urological Procedures, Otolaryngology |
| Companies Covered | Intuitive Surgical Inc., Johnson & Johnson, Olympus Corporation, Asensus Surgical Inc., Brainlab AG, Medtronic, Boston Scientific Corporation, Stryker Corporation, Auris Health Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot-Assisted Endoscope Market Evolving Landscape
Laser imaging modules represent the fastest-expanding technology segment as hospitals prioritize depth-perception accuracy during mucosal resection. Three interconnected developments are reshaping product architecture, regulatory pathways, and procurement behavior.
Multi-spectral laser imaging is decomposing conventional white-light endoscopy by enabling real-time tissue characterization without dye-based chromoendoscopy. Academic medical centers in the United States and Germany are piloting these systems for early neoplasia detection. The technology is compressing diagnostic procedure times while elevating hardware cost structures.
EU AI Act implementation is reclassifying augmented reality guidance algorithms as high-risk medical devices, mandating additional conformity assessment procedures for software-enabled navigation. This regulatory friction is delaying product launches for AR-integrated platforms. Manufacturers are responding by segregating hardware and software certification timelines to preserve market access.
Hospital procurement committees are consolidating vendor relationships around full-platform contracts that bundle consoles, instruments, and service agreements. This concentration is displacing component-level purchasing from independent endoscope suppliers. The shift is most pronounced in United States integrated delivery networks and German university hospital clusters.
Robot-Assisted Endoscope Market Segmentation
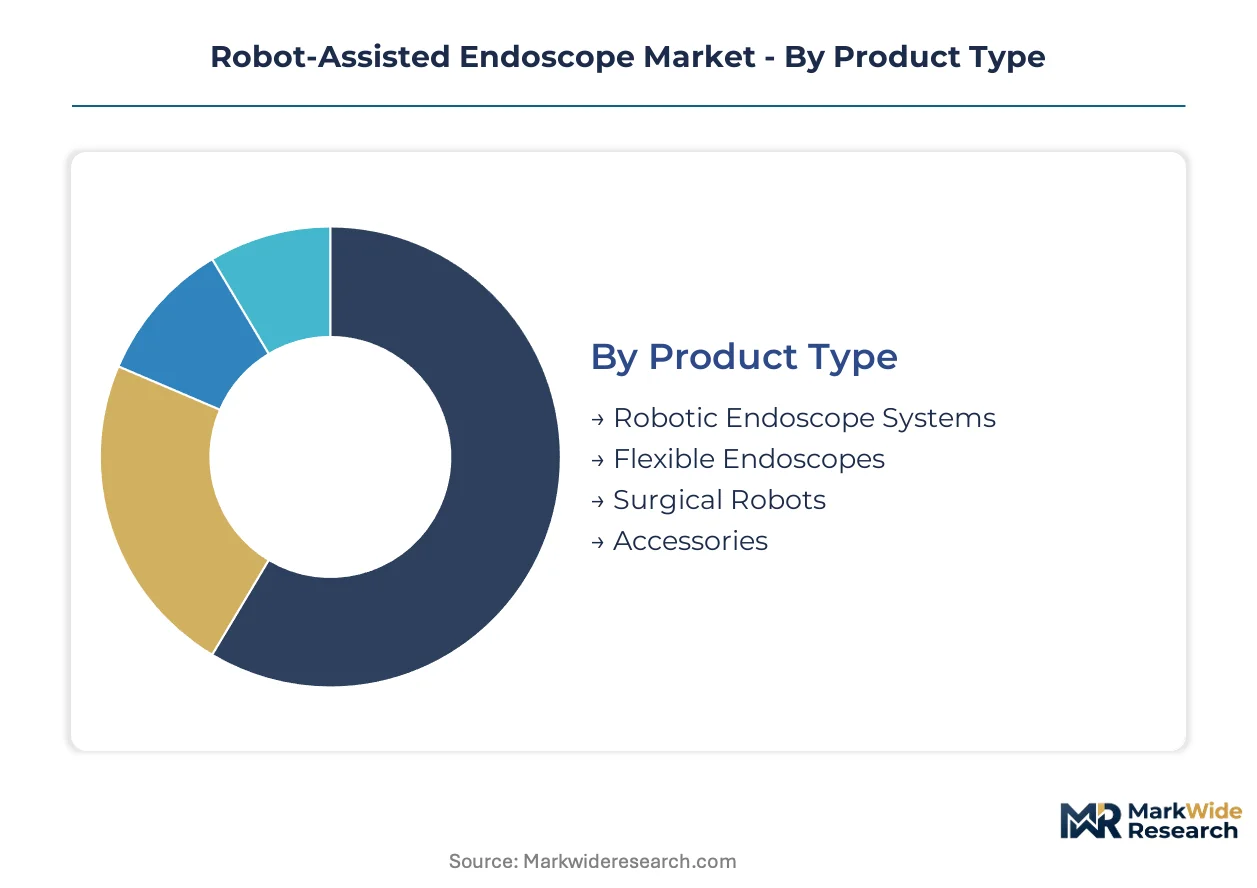
Segmentation in the robot-assisted endoscope market reveals how capital allocation, regulatory pathways, and procedural specialization diverge across product architectures and clinical settings. Understanding these divides enables stakeholders to align R&D investment with reimbursement realities and hospital procurement patterns.
Product Type:
Domestic production of complete robotic platforms concentrates in the United States and Germany, while flexible endoscope component manufacturing spreads across Japanese and South Korean optical suppliers. Export-led segments face longer FDA and EU MDR validation timelines than integrated domestic systems.
- Robotic Endoscope Systems:Integrated platforms combine motorized articulation, surgeon consoles, and disposable instrument channels into unified capital equipment. Demand clusters in United States academic medical centers and German university hospitals building dedicated robotic surgery institutes, driven by bundled service contracts that lock in recurring instrument revenue.
- Flexible Endoscopes:Articulated insertion tubes with CMOS sensors and automated navigation capabilities dominate gastrointestinal procedural volume. Japanese manufacturers supply the majority of export volumes to North American and European markets, constrained by IEC 62304 software validation requirements for autonomous pathfinding features.
- Surgical Robots:Multiport systems with endoscope docking interfaces leverage installed base economics to sustain aftermarket revenue.
- Accessories:Disposable forceps, biopsy channels, and sterilization components generate recurring revenue streams tethered to primary system placements.
Robotic endoscope systems hold the largest share; momentum sits with flexible endoscopes as hospitals prioritize upgrade compatibility over full platform replacement.
Technology:
Cost tiering separates premium visualization modules from standard optical systems, with laser imaging commanding three-to-five-year payback horizons against conventional white-light platforms. Budget-constrained health systems in Southern Europe and parts of the United States defer 3D visualization adoption despite clinical advantages.
- Laser Imaging:Multi-spectral modules enable real-time tissue characterization without dye-based chromoendoscopy, compressing diagnostic procedure times. United States and German academic centers pilot these systems for early neoplasia detection, prioritizing depth-perception accuracy during mucosal resection.
- 3D Visualization:Stereoscopic displays with depth mapping command premium placement in complex bronchoscopic and upper GI interventions. Japanese and German hospitals lead procurement as reimbursement frameworks accommodate higher procedural coding for advanced visualization.
- Automated Navigation:Pathfinding algorithms reduce operator dependency in tortuous luminal anatomy. EU AI Act high-risk classification delays launches for European markets relative to Japanese PMDA sakigake fast-track approvals.
- Augmented Reality:Overlay guidance systems face additional conformity assessment under EU MDR software validation rules, fragmenting regulatory timelines across geographies.
3D visualization captures the dominant installed base; laser imaging is climbing the fastest as depth-perception accuracy becomes a procurement priority.
End User:
Customer type determines purchasing authority and contract structure. United States integrated delivery networks consolidate vendor relationships around full-platform agreements, while European surgical centers retain component-level procurement flexibility.
- Hospitals:Tertiary institutions with dedicated robotic surgery centers drive capital equipment volume, bundling consoles, instruments, and multi-year service agreements. German university hospital clusters and United States academic medical centers anchor demand through centralized procurement committees.
- Surgical Centers:Ambulatory facilities prioritize flexible endoscope compatibility with existing manual systems, constrained by capital budgets and lower procedural reimbursement rates.
- Research Institutions:Academic labs pilot autonomous navigation and laser imaging modules under premarket investigation exemptions, generating clinical evidence for regulatory submissions.
- Specialty Clinics:Gastroenterology and pulmonology practices concentrate in United States metropolitan areas and Japanese urban centers, selecting systems based on payer mix and procedure volume.
Hospitals command the dominant revenue share; specialty clinics are gaining share fastest as outpatient procedural migration accelerates.
Application:
Volume concentration in gastrointestinal procedures creates scale economies that pulmonary and urological applications have yet to match. Procedure coding and reimbursement parity determine cross-specialty adoption rates.
- Gastrointestinal Procedures:Colorectal and upper GI interventions account for the majority of robot-assisted endoscope utilization, with United States, German, and Japanese hospitals expanding dedicated centers. CMOS sensor resolution advancement to 4K standards drives system replacement cycles.
- Pulmonary Procedures:Complex bronchoscopic interventions leverage 3D visualization and automated navigation for peripheral lesion access. Academic medical centers in the United States and Germany pilot therapeutic applications beyond diagnostic use.
- Urological Procedures:Cystoscopic and ureteroscopic applications remain secondary to dedicated urological robotic platforms, limiting endoscope-specific penetration.
- Otolaryngology:Transnasal and transoral robotic surgery represents a nascent application with concentrated demand in specialized head-and-neck centers.
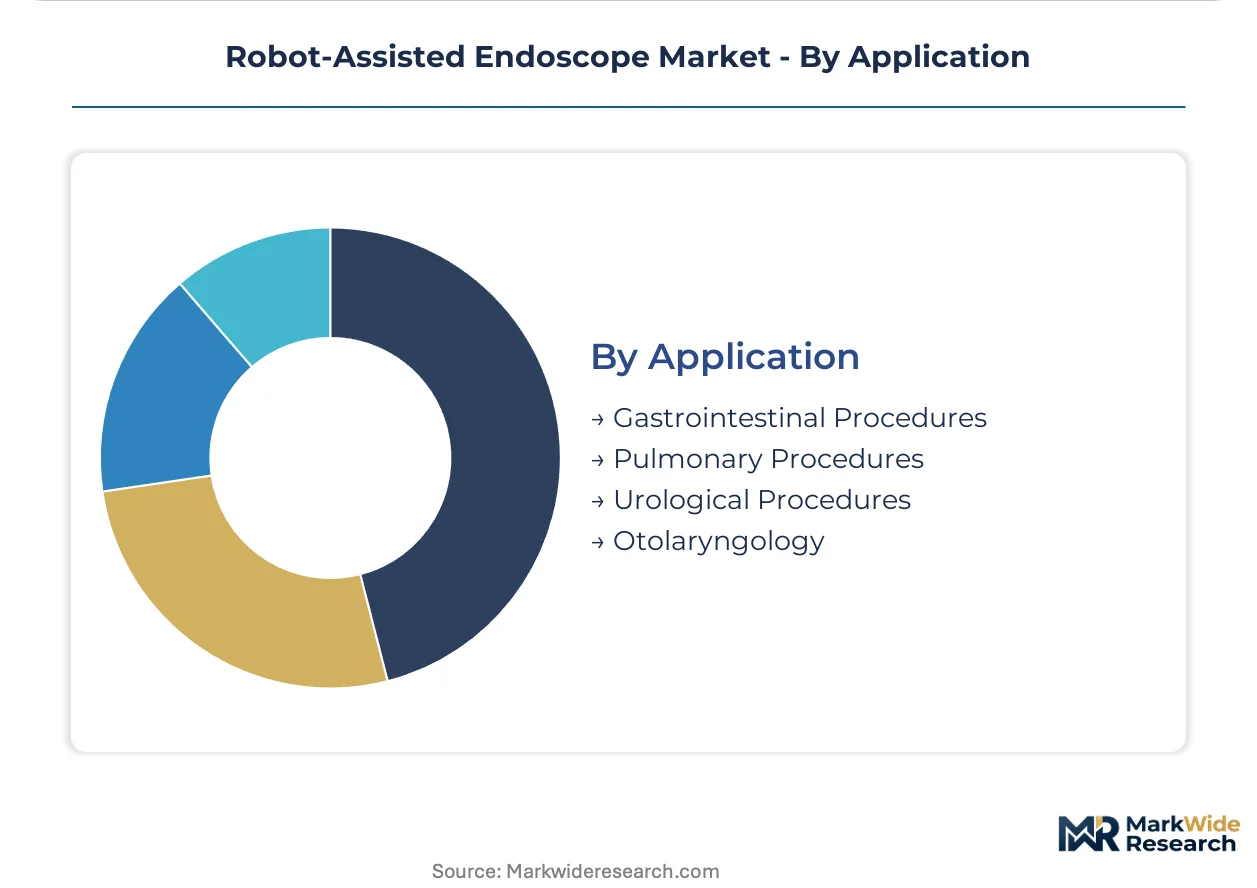
Gastrointestinal procedures hold the largest share; pulmonary procedures show the steepest expansion trajectory as 3D visualization enables therapeutic bronchoscopy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German university hospital clusters and United States academic medical centers, while Japanese manufacturers compete on component cost efficiency. Demand formation diverges between bundled service-contract markets and upgrade-compatible flexible endoscope segments.
United States
Integrated delivery networks in Texas and the Northeast Corridor consolidate vendor relationships around full-platform contracts. FDA 510(k) premarket notification pathways govern robot-assisted endoscope commercialization, mandating biocompatibility testing under established device frameworks. Academic medical centers in Boston and Houston anchor demand through dedicated robotic surgery institutes.
Germany
University hospital clusters in Bavaria and North Rhine-Westphalia drive capital equipment procurement for multi-spectral laser imaging systems. EU MDR conformity assessment procedures tighten premarket validation standards, compressing replacement cycles for legacy equipment. The Eindhoven-Frankfurt medical technology corridor concentrates haptic feedback component engineering talent.
Japan
Metropolitan surgical centers in Tokyo and Osaka prioritize flexible endoscope compatibility with existing manual systems. PMDA sakigake fast-track pathway adaptation for autonomous navigation features enables accelerated market entry relative to standard FDA timelines. Japanese optical suppliers in the Nagoya region dominate CMOS sensor export volumes.
United Kingdom
NHS procurement committees in London and the Midlands defer 3D visualization adoption amid budget constraints. MHRA recognition of EU MDR certificates post-Brexit creates parallel conformity assessment requirements for market access. Private hospital groups in Greater Manchester pilot laser imaging modules for early neoplasia detection.
South Korea
Seoul Capital Area tertiary institutions expand robot-assisted gastrointestinal procedural volume through bundled console-instrument agreements. MFDS medical device approval pathways align with IEC 62304 software validation standards for automated navigation features. Daegu-Gyeongbuk manufacturing clusters supply precision force-sensor components to German system integrators.
Robot-Assisted Endoscope Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform developers commanding premium pricing while component suppliers compete on manufacturing scale. The vendor base concentrates around three strategic tiers: full-system integrators with installed base economics, specialized optical manufacturers with upstream sensor control, and diversified medtech conglomerates with endomechanical portfolio breadth. Dominant competitive moves include backward integration into haptic feedback engineering and geographic expansion through regulatory fast-track sequencing.
Among United States-based platform developers, Intuitive Surgical Inc. and Auris Health Inc. exemplify the installed-base archetype, leveraging console placements to sustain recurring instrument revenue. Olympus Corporation represents Japanese optical manufacturing scale, while Medtronic and Johnson & Johnson occupy diversified conglomerate positions with upstream control over surgical robotics ecosystems. Asensus Surgical Inc. and Brainlab AG sit within the specialized navigation tier, with Boston Scientific Corporation and Stryker Corporation bridging component and system integration domains.
| Leading Market Players |
|---|
| Intuitive Surgical Inc. |
| Johnson & Johnson |
| Olympus Corporation |
| Asensus Surgical Inc. |
| Brainlab AG |
| Medtronic |
| Boston Scientific Corporation |
| Stryker Corporation |
| Auris Health Inc. |
| Others |
Value Network & Pricing Analysis
Full-platform service contracts lock in multi-year instrument revenue while anchoring price visibility against component spot-market volatility. German university hospital clusters and United States integrated delivery networks negotiate these bundled agreements to secure haptic feedback component access from specialized Nagoya and Daegu-Gyeongbuk foundries.
Pricing Analysis
Configured-to-order pricing for customized laser imaging modules commands substantial premiums over standard 1080p optical configurations. Three-tier pricing structure across premium, standard, and economy levels separates 4K multi-spectral systems from conventional white-light platforms and refurbished legacy equipment. Cost compression in the standard tier is intensifying because Japanese optical suppliers are scaling CMOS sensor production for export volumes. Ambulatory surgical centers exhibit highest price sensitivity, deferring upgrades to accommodate capital budget constraints, while German academic medical centers demonstrate lowest sensitivity as reimbursement frameworks accommodate advanced procedural coding.
Supply Chain Analysis
Japan and South Korea anchor precision CMOS sensor and force-feedback component manufacturing, while Germany concentrates haptic engineering talent along the Eindhoven-Frankfurt corridor. Robot-assisted endoscope production draws from specialized polymer suppliers for biocompatible insertion tubes, rare-earth laser diodes for multi-spectral imaging, and precision-machined articulation mechanisms. Single-source vulnerability concentrates in German and Japanese component foundries serving multiple competing system integrators. Distribution runs through hospital procurement committees and GPO contracts rather than direct manufacturer-to-facility sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
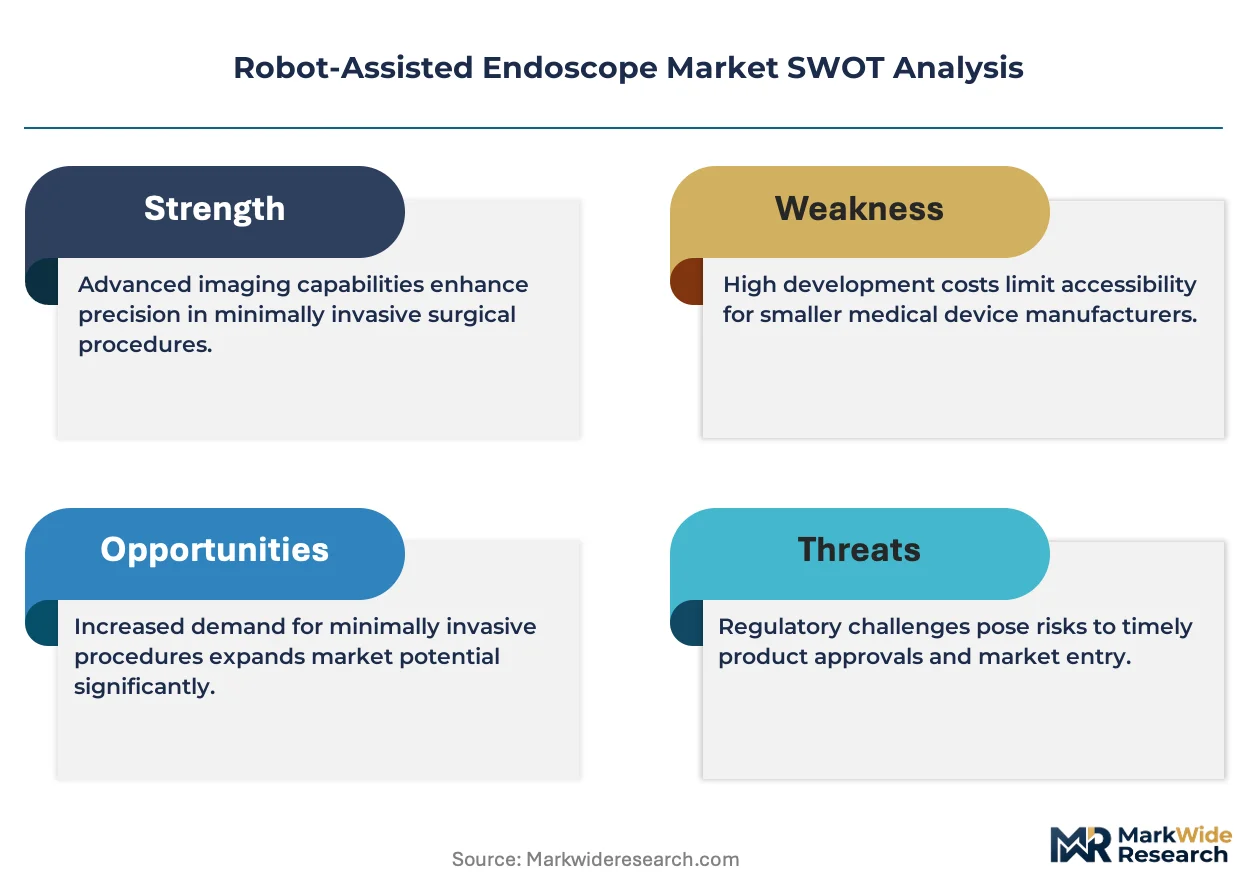
Conventional manual endoscopes pose a persistent substitution threat as cost-conscious health systems prioritize screening program scalability over robotic precision. Incumbents must navigate this trade-off between clinical differentiation and budget accessibility.
For Market Incumbents: Consolidate installed base economics by extending service contract durations and locking in disposable instrument channel exclusivity. Backward integration into haptic feedback engineering reduces exposure to Nagoya component supply bottlenecks. Prioritize FDA 510(k) pathway familiarity to accelerate clearance timelines against emerging competitors. For New Entrants and Emerging Players: Post-market surveillance and maintenance service gaps in existing vendor relationships create entry points for specialized service providers. Target ambulatory surgical centers in United States metropolitan areas with flexible endoscope compatibility solutions that bridge manual and robotic platforms. Pursue Japan's PMDA sakigake fast-track pathway to establish clinical evidence before FDA submission. For Investors and Strategic Acquirers: Capital is best deployed toward autonomous navigation algorithm developers with validated IEC 62304 software frameworks. Long-term viability hinges on regulatory moats against EU AI Act high-risk classification delays. Monitor PMDA regulatory adaptation timelines as an inflection indicator for accelerated market entry opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment accelerates hospital procurement of certified systems over legacy equipment. |
| Hospital System Partnership | Bundled console-instrument agreements with German university clusters lock in recurring revenue streams. |
| Software Companion Development | Autonomous navigation algorithms validated under IEC 62304 standards differentiate against AR-integrated competitors. |
| Reimbursement Strategy | Advanced procedural coding for 3D visualization platforms expands addressable market in pulmonary interventions. |
| Backward Integration | In-house haptic feedback engineering reduces supply vulnerability to Japanese and German component concentration. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary interviews with clinicians and procurement directors across United States academic medical centers and German university hospital clusters combined with secondary validation from FDA 510(k) filings, EU MDR certificates, CMS Medicare procedural data, and hospital procurement databases. Bottom-up segmentation modeling triangulated against top-down market sizing from capital equipment shipment tracking.
Segmentation dimensions modeled include product architecture, visualization technology tier, end-user facility type, and application specialty across the projection horizon. CAGRs derive from installed base replacement cycle analysis, procedural volume expansion rates, and technology adoption S-curves. Forecast inputs incorporate reimbursement framework evolution, regulatory clearance timeline differentials, and supply chain capacity constraints in precision component manufacturing.
Forecasts assume regulatory continuity in FDA premarket notification, EU MDR conformity assessment, and PMDA sakigake pathways; material policy shifts would require re-modeling. Specific risks include EU AI Act implementation delays for augmented reality guidance, biocompatibility testing cost inflation, and haptic feedback component supply disruption. Recalibration cycles align with material shifts in reimbursement parity, regulatory classification precedents, and autonomous navigation validation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscopic Vessel Harvesting Systems Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Endobronchial Ultrasound Biopsy Device Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Endoscopy Equipment and Software Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Global Veterinary Endoscopy Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Automated Endoscopy Reprocessor Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
North America Disposable Endoscopes Market