
 Electrostatic Discharge (ESD) Films Market | 2026-2036
Electrostatic Discharge (ESD) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Discharge (ESD) Films Market Analysis
Multi-source procurement of conductive polymer formulations is expanding across tier-one electronics packaging programs. Sealed Air Corporation leverages its blown film extrusion network to sustain supply continuity for clean room applications in North America and Europe. Smurfit Kappa Group anchors its position through integrated paperboard-laminate operations that compete on total cost for component shipping trays. BASF differentiates via proprietary carbon nanotube masterbatch technologies that dominate high-performance static decay specifications.
Electrostatic Discharge (ESD) Films are multilayer polymer structures engineered with surface resistivity between 10^4 and 10^11 ohms per square, manufactured through coextrusion or vapor-deposited metallization to dissipate electrostatic charges without generating triboelectric voltage. These films protect sensitive semiconductor devices, printed circuit assemblies, and precision medical instruments from field-induced damage during handling, transit, and storage. Sheet films occupy the largest volume position due to their ubiquity in die-cut liner applications for electronics OEMs, while static control bags command premium pricing through anti-static and shielding dual-functionality required for aerospace component logistics. Polyethylene formulations lead material consumption because of cost-efficient calendering and compatibility with carbon black and amine-based conductive additives, though PET laminates are gaining traction in medical device packaging where optical clarity and gamma sterilization resistance prove essential.
EPA regulations governing volatile organic compound emissions from solvent-based coating operations are pressuring converters toward waterborne or extruded conductive layers in the United States. The EU REACH framework restricts certain phthalate plasticizers and persistent organic pollutants used in legacy PVC ESD formulations, compelling reformulation toward polyethylene and polypropylene alternatives. FDA device packaging guidelines for sterile medical electronics further tighten extractables and leachables testing protocols for films contacting implantable components. Stakeholders must monitor evolving state-level extended producer responsibility mandates in California and New York that could impose end-of-life recovery obligations on single-use static control packaging.
Market Dynamics
Semiconductor fabrication capacity expansion in Taiwan and South Korea is concentrating demand for static control packaging around 300mm wafer transport specifications, while REACH and RoHS compliance deadlines force rapid material reformulation across European supply chains.
Growth Catalysts
- Wafer Transport Standardization:Semiconductor fabs in Taiwan and South Korea are mandating dual-layer static shielding bags for 300mm wafer cassettes, pulling film volumes upward.
- EU RoHS Phase-Out Deadlines:Legacy PVC formulations containing restricted phthalates face mandatory replacement, accelerating polyethylene and polypropylene ESD film adoption.
- Carbon Nanotube Masterbatch Maturation:Conductive polymer doping technologies now achieve surface resistivity below 10^6 ohms per square without metallic fillers, opening aerospace and medical device segments.
Market Restraints
- Ethylene Feedstock Volatility:Polyethylene resin prices fluctuate with naphtha-cracking margins, compressing converter margins on fixed-price OEM contracts.
- Blown Film Concentration Risk:North American clean room film supply depends on a limited extrusion base concentrated in the Great Lakes industrial corridor.
- Gamma Sterilization Compatibility Limits:Amine-based anti-static additives degrade under medical device sterilization protocols, restricting PET laminate penetration in implantable electronics.
Strategic Opportunities
- China Eastern Coastal Manufacturing Corridor:Electronics contract manufacturers in Jiangsu and Guangdong provinces are consolidating packaging specifications, creating volume aggregation points for qualified suppliers.
- FDA Device Packaging Guidelines:Extractables and leachables testing protocols for implantable medical electronics create certified-supplier premiums for compliant film producers.
- Waterborne Coating Convergence:EPA volatile organic compound regulations are pushing solvent-based converters toward extruded conductive layers, rewarding early capital deployment in waterborne alternatives.
Industry Challenges
- Clean Room Technician Scarcity:Blown film extrusion operators with ISO 14644 clean room certification command wage premiums that elevate fixed production costs.
- Dual Certification Timelines:Simultaneous REACH substance registration and FDA master file submission stretches regulatory affairs capacity at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Discharge (ESD) Films Market |
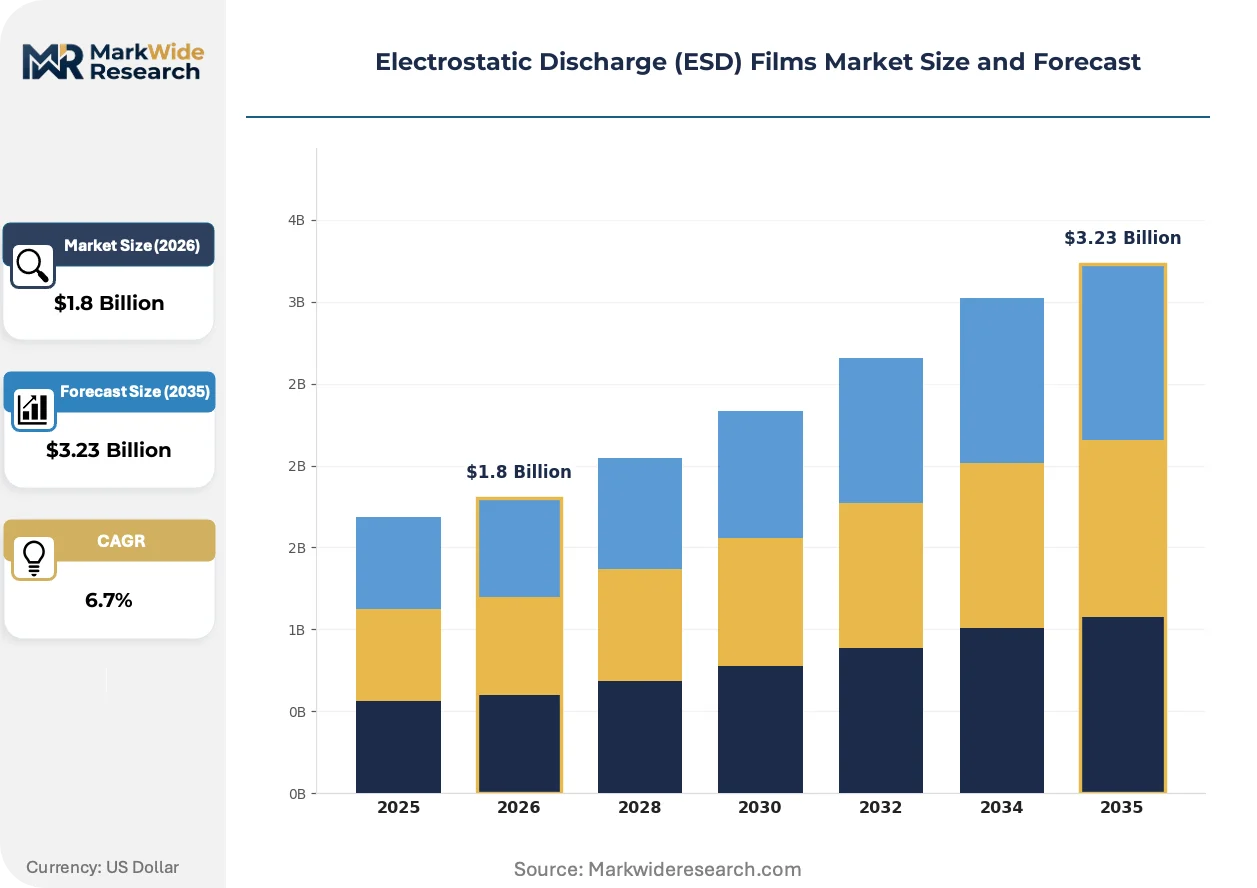
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Films, Roll Films, Static Control Bags, Laminated Films Material: Polyethylene, Polypropylene, PVC, PET End User: Electronics, Aerospace, Automotive, Medical Devices Application: Packaging, Surface Protection, Clean Room Applications, Component Handling |
| Companies Covered | Sealed Air Corporation, Elcom, Smurfit Kappa Group, Transcendia, Teknis, DESCO Industries, Pregis, BASF, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Discharge (ESD) Films Market Emerging Trajectories
Material science advances and regulatory compression are restructuring how static control films achieve conductivity, with vapor-deposited metallization and carbon nanostructure doping converging on performance thresholds once reserved for metallic laminates.
Multilayer coextrusion with vapor-deposited aluminum metallization is unifying surface resistivity control with optical clarity in medical device packaging. Gamma sterilization-resistant PET laminates are capturing share from opaque polyethylene in implantable electronics trays. This unification of performance attributes collapses the historical trade-off between static decay rates and visual inspection requirements.
REACH substance restrictions on persistent organic pollutants and phthalate plasticizers are eliminating legacy PVC ESD formulations from European medical and aerospace supply chains. Reformulation toward polyethylene and polypropylene alternatives requires requalification of entire packaging specifications. German and French medical device OEMs are accelerating supplier audits to lock in compliant film sources before 2025 registration deadlines.
Electronics OEMs in China's eastern coastal manufacturing belt are consolidating vendor bases around integrated packaging suppliers offering die-cut liners, formed trays, and static control bags under single qualification. This concentration favors converters with captive thermoforming and in-house conductive compounding. Taiwan-based semiconductor packaging houses are driving the tightest consolidation, reducing qualified film sources from six to two per component category.
Electrostatic Discharge (ESD) Films Market Segmentation
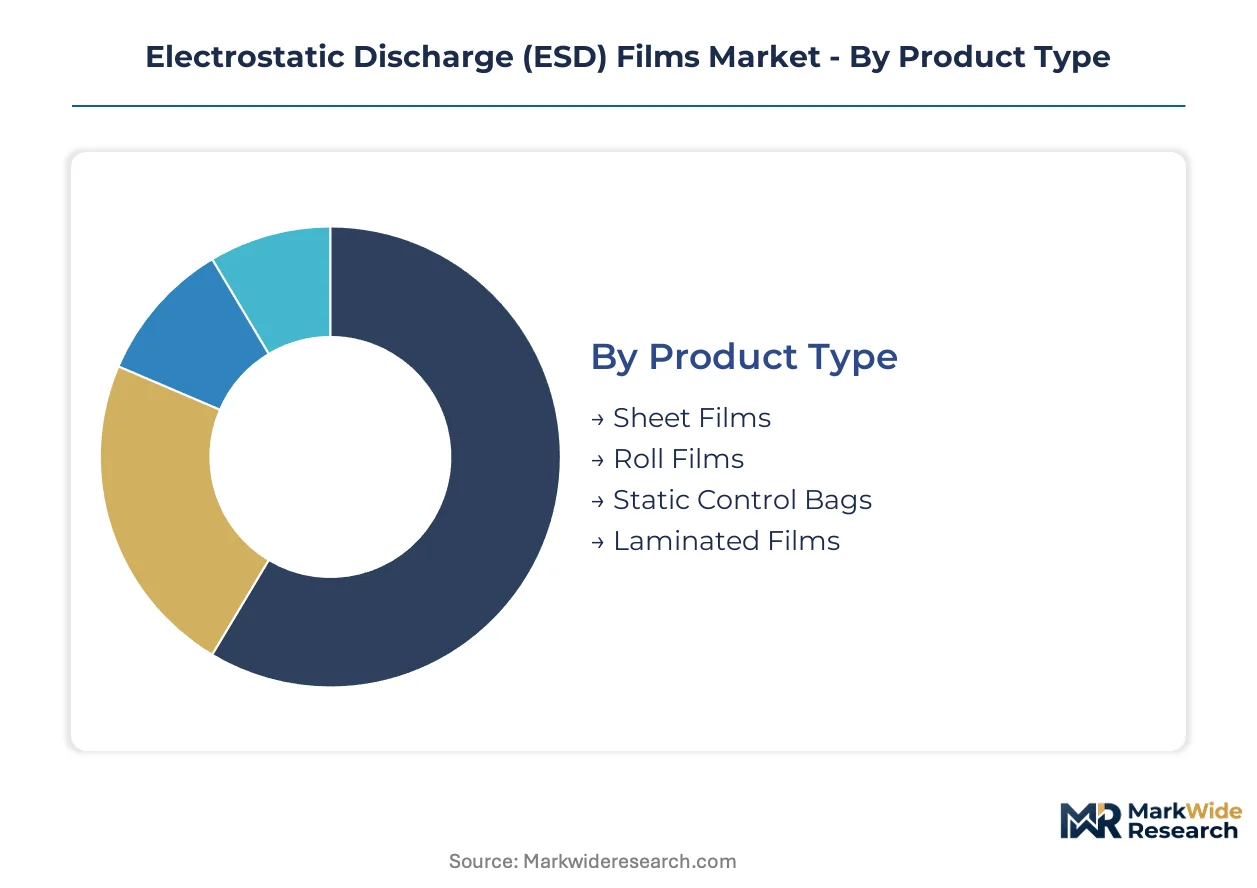
Segmentation in ESD films determines qualification pathways, margin structures, and capital allocation priorities. Each dimension—product format, base polymer, end-use vertical, and functional application—carries distinct technical specifications and regulatory compliance requirements that reshape supplier positioning.
Product Type:
Blown film extrusion capacity concentrates around high-volume formats, with converter investments favoring lines that can pivot across multiple product configurations.
- Sheet Films:Die-cut from extruded rolls into liner formats for electronics OEMs, these dominate volume consumption through compatibility with automated pick-and-place operations. Taiwanese semiconductor packaging houses specify 0.15mm caliper polyethylene sheets for wafer cassette interleaving.
- Static Control Bags:Dual-layer shielding constructions with vapor-deposited aluminum metallization command premium positioning. Aerospace component logistics in Germany and France mandate these for satellite electronics transport under ESA cleanliness protocols.
- Roll Films:Supplied to contract converters for downstream die-cutting and thermoforming, these serve high-throughput electronics manufacturing in China's Jiangsu province.
- Laminated Films:PET-polyethylene composites address medical device gamma sterilization requirements where optical clarity and barrier performance converge.
Sheet films absorb the bulk of installed capacity; static control bags are expanding most quickly.
Material:
Feedstock sourcing strategies diverge sharply between commodity polyethylene and engineering-grade alternatives, with REACH compliance deadlines forcing rapid portfolio rebalancing.
- Polyethylene:Carbon black and amine-based additives integrate cleanly into LDPE and HDPE matrices, enabling cost-efficient calendering at scale. South Korean semiconductor fabs specify these formulations for 300mm wafer transport bags.
- PET:Biaxially oriented constructions with vapor-deposited coatings serve medical device OEMs requiring gamma sterilization resistance and visual inspection capability. German implantable electronics manufacturers are accelerating PET laminate qualification.
- Polypropylene:Random copolymer grades with inherently lower surface resistivity reduce additive loading requirements for clean room applications.
- PVC:Legacy formulations face phased elimination under EU RoHS and REACH phthalate restrictions, with remaining demand concentrated in non-European aerospace maintenance operations.
Polyethylene commands the deepest converter expertise; PET is climbing the fastest as medical device packaging specifications tighten.
End User:
Customer concentration patterns vary dramatically by vertical, with electronics OEMs driving volume and medical device manufacturers extracting steepest certification premiums.
- Electronics:Contract manufacturers in Guangdong province consolidate packaging specifications across die-cut liners, formed trays, and static control bags. Taiwan-based semiconductor houses have reduced qualified film sources from six to two per component category.
- Medical Devices:FDA extractables and leachables protocols for implantable electronics create certified-supplier premiums. French and German OEMs are locking in compliant film sources ahead of registration deadlines.
- Aerospace:ESA and NASA cleanliness specifications drive dual-layer shielding requirements for satellite and avionics component logistics.
- Automotive:Electric vehicle power electronics and sensor modules generate emerging demand for static control during module assembly.
Electronics verticals dominate current offtake; medical devices are gaining share fastest on certification-driven pricing power.
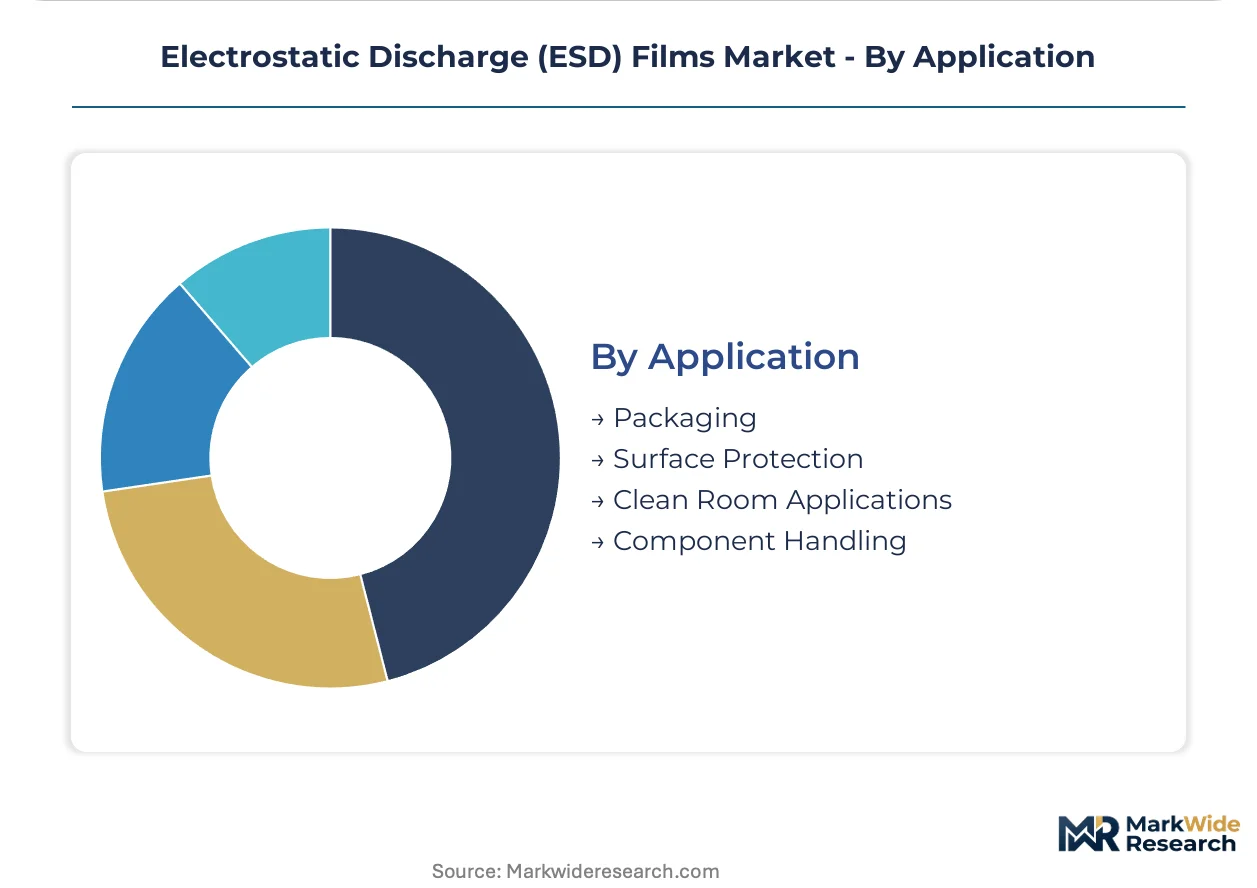
Application:
Functional use cases determine performance thresholds, with clean room and component handling applications imposing the most stringent particulate and static decay specifications.
- Packaging:Encompasses bags, pouches, and formed containers for transit and storage. Chinese contract manufacturers are consolidating vendor bases around integrated suppliers offering complete packaging systems.
- Clean Room Applications:ISO 14644 Class 100-1000 compatibility requires blown film extrusion with controlled particulate generation. North American supply concentrates in the Great Lakes industrial corridor.
- Surface Protection:Temporary films for precision instrument faces and display panels during assembly and shipping.
- Component Handling:Trays, carriers, and workstation mats for direct contact with sensitive devices during manufacturing operations.
Packaging captures the largest volume commitment; clean room applications are expanding most quickly on semiconductor fab construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene cracking capacity along the US Gulf Coast anchors North American polyethylene feedstock supply for ESD film converters. Taiwan and South Korea semiconductor fabrication clusters drive Asia-Pacific demand concentration. German chemical compounding expertise shapes European material compliance pathways.
United States
Semiconductor fabs in Arizona and Texas are scaling 300mm wafer transport packaging specifications. EPA volatile organic compound regulations pressure solvent-based coating operations toward waterborne alternatives. The Great Lakes industrial corridor concentrates blown film extrusion capacity for ISO 14644 clean room applications.
Taiwan
Wafer packaging houses are consolidating qualified film sources from six to two per component category. The island's semiconductor fabrication expansion mandates dual-layer static shielding bags for cassette transport. Hsinchu Science Park anchors the tightest vendor consolidation in Asia-Pacific electronics packaging.
Germany
Medical device OEMs in Baden-Württemberg are accelerating supplier audits ahead of REACH registration deadlines. ECHA substance restrictions on phthalate plasticizers eliminate legacy PVC formulations from implantable electronics supply chains. The Stuttgart industrial cluster drives PET laminate qualification for gamma sterilization-resistant packaging.
South Korea
Memory and logic chip fabs specify carbon black-doped polyethylene formulations for 300mm wafer transport. MFDS medical device packaging guidelines tighten extractables testing for films contacting implantable components. The Pyeongtaek-Dongtan semiconductor corridor concentrates demand for static control bags with sub-10^6 ohm surface resistivity.
China
Electronics contract manufacturers in Jiangsu and Guangdong provinces are consolidating packaging specifications across die-cut liners and formed trays. MEE enforcement of dual carbon goals pressures converters toward lower-emission extrusion processes. The Yangtze River Delta manufacturing belt aggregates volume for qualified static control film suppliers.
Electrostatic Discharge (ESD) Films Market Vendor Landscape
Global majors compete with regional champions across material science capabilities and clean room certification tiers. The vendor base stratifies between integrated packaging conglomerates with captive film extrusion and specialized converters focused on conductive compounding. Three archetypes dominate: blown film specialists with ISO 14644 certification, integrated paperboard-laminate operators competing on total landed cost, and chemical compounders with proprietary conductive masterbatch technologies. Capacity expansion and strategic qualification partnerships represent the dominant competitive moves as OEMs reduce approved vendor lists.
Within the integrated packaging tier, Sealed Air Corporation and Smurfit Kappa Group exemplify scale-driven positioning across North American and European electronics supply chains. Among chemical compounders with materials science depth, BASF occupies a position anchored in carbon nanotube masterbatch development for high-performance static decay specifications. These three companies represent contrasting pathways: blown film network coverage, paperboard-laminate integration, and conductive additive innovation.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Elcom |
| Smurfit Kappa Group |
| Transcendia |
| Teknis |
| DESCO Industries |
| Pregis |
| BASF |
| DS Smith |
| Others |
Supply Flow & Price Mechanics
EU REACH substance restrictions and RoHS phthalate phase-out deadlines gate qualified supply for European medical and aerospace buyers, while simultaneously compressing margin structures for converters still running legacy PVC formulations. Premium-tier pricing access now requires simultaneous ECHA registration and FDA master file submission, creating dual-certification cost barriers that stratify the supplier base into compliant and non-compliant tiers.
Pricing Analysis
Warranty-backed clean room certification and extractables-leachables testing documentation are increasingly bundled into long-term supply contracts rather than offered as unbundled add-ons. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14644 Class 100-certified film from general industrial grade and commodity converter stock. Price differentiation hinges on certification grade and volume scale, with semiconductor packaging houses in Taiwan extracting steepest discounts through consolidated category sourcing. Cost compression in standard-grade polyethylene formulations is intensifying because ethylene feedstock volatility has compressed converter margins on fixed-price OEM contracts. Contract manufacturers in China's Jiangsu province demonstrate highest price sensitivity, while German implantable electronics OEMs show lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Dual-sourcing mandates from Taiwan-based semiconductor packaging houses and South Korean memory fabs require qualified backup suppliers for all critical film specifications, stretching regulatory affairs capacity at mid-scale converters. Geographic supply concentration centers on Taiwan, South Korea, and the United States for high-performance static shielding films, with China's eastern coastal corridor serving volume die-cut liner production. Raw material dependencies draw from naphtha-cracking derived polyethylene resin, carbon black conductive additives, and vapor-deposited aluminum metallization services. Single-source vulnerability persists in blown film extrusion capacity concentrated in the Great Lakes industrial corridor for North American clean room applications. Distribution runs through integrated packaging suppliers offering captive thermoforming and in-house conductive compounding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into conductive masterbatch compounding and captive blown film extrusion has become the defining competitive race, as OEM vendor consolidation rewards suppliers controlling both formulation and fabrication. Players are pursuing downstream integration into die-cut liner and formed tray operations to capture category volume aggregation points.
For Market Incumbents: Hedge against REACH registration deadline disruptions by accelerating PET laminate qualification programs ahead of PVC phase-out timelines. Secure dual-source qualified status at Taiwan semiconductor packaging houses through ISO 14644 clean room certification investments. Capacity addition in China's Yangtze River Delta manufacturing belt captures volume aggregation from consolidating electronics contract manufacturers. Certification investment in gamma sterilization-resistant formulations defends position against carbon nanotube masterbatch specialists targeting medical device segments. For New Entrants and Emerging Players: Begin with automotive electric vehicle power electronics, where static control specifications remain underdeveloped relative to semiconductor and medical verticals. Target Jiangsu and Guangdong province contract manufacturers with waterborne coating capabilities that satisfy MEE dual carbon enforcement without legacy solvent-based infrastructure. The most penetrable segment is surface protection films for precision instrument assembly, where qualification timelines compress versus clean room applications. Go-to-market angle: position as dedicated single-source partner for mid-tier OEMs bypassing vendor consolidation at top-tier houses. For Investors and Strategic Acquirers: FDA master file submissions for implantable electronics packaging are the leading indicator that a converter has achieved viable long-term positioning in the highest-margin segment. Five-to-ten year viability hinges on simultaneous REACH and FDA certification depth rather than commodity scale. Acquisition target archetype: mid-scale converters with existing ECHA substance registration and captive thermoforming capability but lacking carbon nanotube masterbatch partnerships. Signal to watch: Taiwan packaging house reduction of qualified film sources from six to two per component category, which accelerates consolidation premiums for remaining qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Masterbatch | BASF's carbon nanotube technology dominance demonstrates formulation control as margin defense. |
| Clean Room Certification Investment | ISO 14644 Class 100 qualification opens Taiwan semiconductor packaging house vendor lists. |
| Waterborne Coating Transition | EPA volatile organic compound compliance creates first-mover advantage in North American supply. |
| Gamma Sterilization-Resistant Formulation | PET laminate qualification captures German implantable electronics OEM premium pricing. |
| Vendor Consolidation Partnership | Single-source qualification at Chinese contract manufacturers locks in volume aggregation points. |
Methodological Framework
SEC 10-K filings, ECHA substance registration databases, and FDA master file repositories formed the secondary backbone for supply-side capacity and regulatory compliance mapping. Primary interviews with blown film extrusion operators, semiconductor packaging procurement managers, medical device regulatory affairs directors, and conductive additive R&D leads validated qualification timelines and vendor consolidation patterns. Bottom-up triangulation against top-down trade flow analysis ensured volume estimates reconciled with installed extrusion capacity across the Great Lakes, Hsinchu Science Park, and Pyeongtaek-Dongtan corridors.
Historical trendline analysis of polyethylene resin pricing volatility and carbon black additive cost structures informed margin compression modeling across the projection horizon. Segmentation dimensions included product format, base polymer chemistry, end-use vertical, and functional application, with additional modeling of certification tier and geographic regulatory cluster. CAGRs were derived from wafer fabrication capacity expansion schedules and medical device packaging specification evolution. Industry-specific forecast inputs incorporated REACH registration deadline impacts and MEE dual carbon enforcement trajectories.
Underlying measurement precision varies by segment; static control bags and medical device laminates carry tighter precision than commodity sheet films due to concentrated buyer pools and visible contract structures. Forecasts reflect assumptions regarding semiconductor fab construction timelines, regulatory deadline adherence, and conductive additive technology maturation. Deviation in ethylene feedstock pricing or REACH substance restriction scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market