
 Asia-Pacific Electrostatic Discharge (ESD) Trays Market | 2026-2036
Asia-Pacific Electrostatic Discharge (ESD) Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electrostatic Discharge (ESD) Trays Market Insights
China's GB/T 32304 electrostatic control standards for electronics manufacturing is repositioning material specifications across the Asia-Pacific ESD tray supply base. Elcom (U.K.) Ltd. leverages its conductive polymer formulations to serve high-volume semiconductor handlers in Taiwan and South Korea. GWP Group Limited anchors its regional footprint through specialized thermoforming capacity aimed at precision electronics packaging. Shepherd Thermoforming & Packaging Inc. competes on custom tooling capabilities for aerospace-grade tray configurations.
Asia-Pacific electrostatic discharge trays are thermoformed or injection-molded containers engineered with surface resistivity between 10^3 and 10^11 ohms per square, typically fabricated from carbon-filled or inherently dissipative polymers to shield sensitive electronic components from electrostatic field damage during transit and storage. Stackable Trays dominate procurement volumes due to their nesting efficiency in automated warehouse systems across Japanese electronics plants. Polycarbonate variants command premium positioning where repeated autoclave sterilization cycles are required by healthcare device manufacturers in Australia. Anti-Static Trays lead growth velocity as Vietnamese and Indonesian contract manufacturers upgrade from basic corrugated alternatives to certified ESD handling systems.
Japan's METI enforces JIS C 61340-5-1 compliance for electrostatic protected areas, while China's SAMR administers mandatory GB standard testing for plastics used in semiconductor cleanrooms. Australia's TGA imposes parallel material traceability rules on ESD packaging destined for implantable medical device supply chains. Buyers must monitor divergence between national test protocols to avoid dual-certification cost burdens as intra-regional component trade intensifies.
Market Dynamics
China's SAMR enforcement of GB/T 32304 electrostatic control standards is compressing supplier qualification timelines and forcing polymer reformulation investments across regional tray manufacturers serving semiconductor fabs.
Growth Catalysts
- Semiconductor Fab Expansion:Wafer handling volume at South Korean and Taiwanese fabrication plants is pulling specialized conductive polymer tray procurement into multi-year supply agreements with thermoforming specialists.
- GB Standard Tightening:China's SAMR-mandated surface resistivity testing for cleanroom plastics is disqualifying legacy carbon-load formulations and certifying next-generation inherently dissipative polymers.
- Automated Warehouse Density:Japanese electronics manufacturers are specifying nesting-optimized stackable tray geometries to maximize vertical storage utilization in high-bay retrieval systems.
Market Restraints
- Acrylonitrile Butadiene Styrene Volatility:ABS resin price swings tied to crude oil derivatives are compressing margins for injection-molded tray producers serving Vietnamese contract manufacturers.
- Single-Source Carbon Black Supply:Conductive filler procurement concentrates among three regional compounders, exposing tray molders to allocation risk during semiconductor demand surges.
- Autoclave Cycle Limitations:Polycarbonate variants degrade after repeated 134°C sterilization exposures, restricting reuse economics for Australian medical device sterilization service providers.
Strategic Opportunities
- Indonesian Contract Manufacturing Upgrade:Electronics assembly clusters in Batam and Jakarta are transitioning from corrugated cardboard to certified ESD handling systems, opening first-mover certification contracts.
- Healthcare Device Convergence:Implantable medical device supply chains in Australia are merging ISO 13485 quality mandates with JIS C 61340-5-1 electrostatic protocols, requiring dual-certified tray configurations.
- Biodegradable Polymer Development:Malaysia's national plastics sustainability roadmap is incentivizing tray producers to qualify polylactic acid-based dissipative formulations for consumer electronics export packaging.
Industry Challenges
- Cleanroom Polymer Compounding Expertise:Regional tray manufacturers face 18-24 month skill development cycles to replicate carbon nanotube dispersion techniques mastered by Japanese specialty compounders.
- Dual Certification Timeline Compression:Suppliers must parallel-track GB standard testing in China with JIS compliance verification for Japanese automotive electronics buyers, stretching quality engineering bandwidth.
- Legacy Thermoforming Asset Obsolescence:Precision vacuum forming equipment calibrated to 2mm wall thickness tolerances cannot produce next-generation 0.8mm thin-wall trays demanded by semiconductor wafer shippers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electrostatic Discharge (ESD) Trays Market |
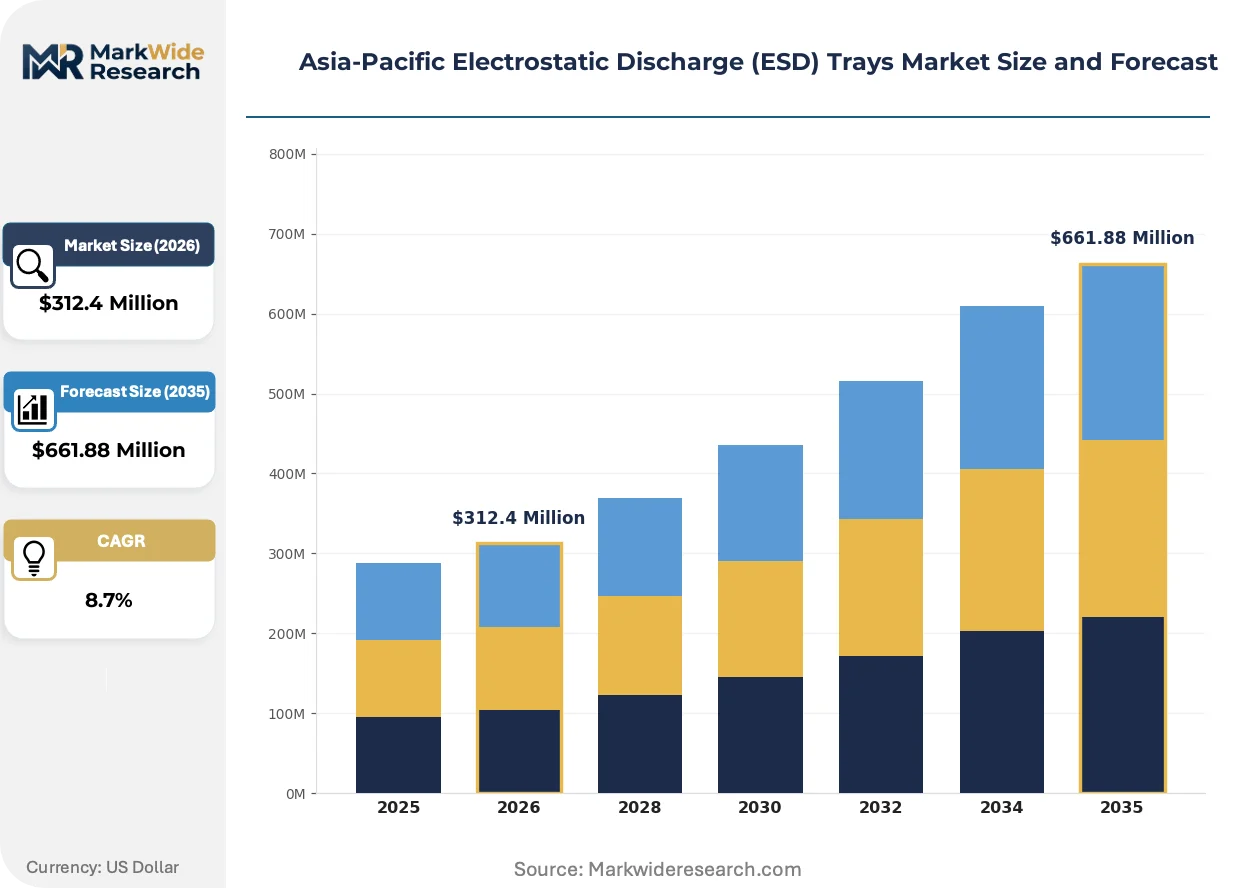
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Trays, Rimmed Trays, Lidded Trays, Anti-Static Trays Material: Polypropylene, Polystyrene, PVC, Polycarbonate End User: Electronics Manufacturers, Automotive Suppliers, Healthcare Providers, Aerospace Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Elcom (U.K.) Ltd., Tandem Equipment Sales, Inc., GWP Group Limited, Utz Group, Teknis Limited, AUER Packaging, Helios Packaging Pvt. Ltd., Shepherd Thermoforming & Packaging Inc., Conductive Containers, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electrostatic Discharge (ESD) Trays Market Trends and Innovations
Material science advances and regulatory protocol harmonization are restructuring competitive position in Asia-Pacific ESD tray supply, with conductivity engineering and sustainability mandates now primary differentiation vectors.
Carbon nanotube-loaded thermoplastic compounds are displacing conventional carbon black formulations in high-value semiconductor wafer trays. Taiwanese foundry procurement teams are specifying these materials for 300mm wafer transport applications. The technology is converging with thin-wall thermoforming processes to enable 40% weight reduction without surface resistivity degradation.
Japan's METI is accelerating JIS C 61340-5-1 revision cycles to align test methodologies with IEC 61340-5-1 international standards. This harmonization reduces dual-certification burden for tray suppliers serving cross-border electronics supply chains. Australian medical device exporters are leveraging this convergence to access both Japanese automotive electronics and domestic TGA-regulated implantable device markets with single qualification runs.
Consolidated procurement through electronics manufacturing service aggregators is compressing supplier negotiation leverage in Vietnam and Indonesia. Tier-one contract manufacturers are mandating vendor-managed inventory programs with 48-hour replenishment commitments. This behavioral shift is most pronounced in Ho Chi Minh City and Jakarta industrial zones, where localized thermoforming capacity struggles to match inventory turns demanded by Foxconn and Luxshare procurement teams.
Asia-Pacific Electrostatic Discharge (ESD) Trays Market Segmentation
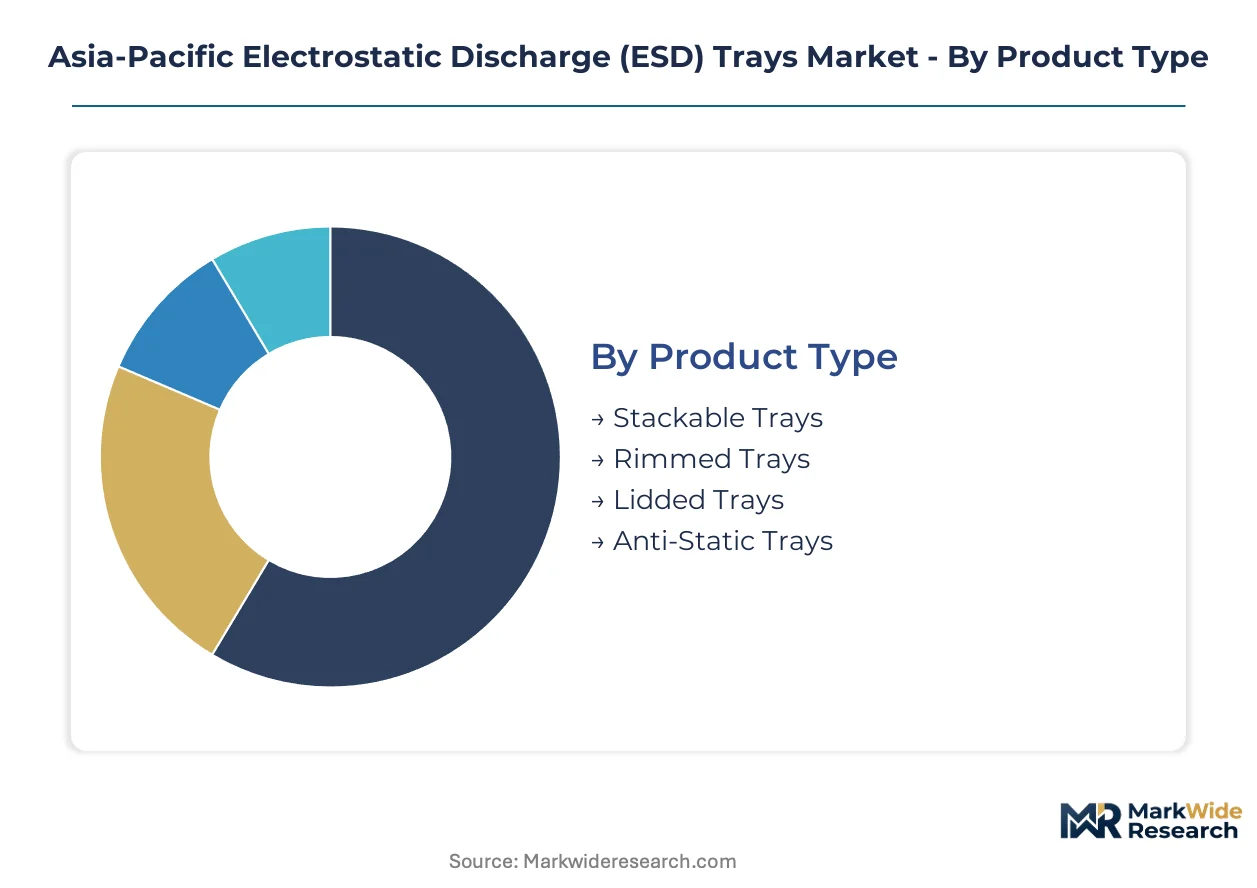
Segmentation in Asia-Pacific ESD trays reveals how procurement patterns diverge between high-volume semiconductor handlers seeking nesting efficiency and specialized medical device manufacturers demanding sterilization durability. Material selection and channel configuration directly determine qualification timelines for suppliers navigating China's SAMR testing protocols and Japan's METI compliance requirements.
Product Type:
Stackable configurations serve as standalone handling systems in automated warehouses, while lidded and rimmed variants integrate into broader contamination-controlled logistics chains.
- Stackable Trays:Nesting geometries with vertical interlock features maximize cubic utilization in high-bay retrieval systems. Japanese electronics plants in Osaka and Nagoya specify these for component-to-assembly line replenishment cycles where floor space commands premium valuations.
- Anti-Static Trays:Surface-treated dissipative polymers meet JIS C 61340-5-1 protected area requirements without carbon filler loading. Taiwanese foundry procurement teams favor these for cleanroom wafer staging where particulate shedding from carbon compounds risks yield loss.
- Rimmed Trays:Raised perimeter edges prevent lateral component displacement during manual handling operations. Vietnamese contract manufacturers deploy these in surface-mount technology assembly cells.
- Lidded Trays:Hinged or separate cover configurations seal against humidity and particulate ingress for extended storage cycles. Australian medical device sterilization service providers specify these for implantable component quarantine protocols.
Volume placements concentrate in Stackable Trays; the faster expansion belongs to Anti-Static Trays.
Material:
Cost tiers separate commodity thermoplastics from engineered compounds capable of withstanding repeated autoclave exposure or semiconductor-grade outgassing limits.
- Polycarbonate:Amorphous thermoplastic retaining dimensional stability across 134°C steam sterilization cycles. Australian TGA-regulated implantable device supply chains mandate this grade for tray reuse economics in centralized sterilization facilities.
- Polypropylene:Semi-crystalline olefin with inherent moisture resistance and broad chemical compatibility. Indonesian electronics clusters in Batam specify this for cost-sensitive consumer electronics handling where tray replacement cycles are shorter.
- Polystyrene:Rigid amorphous polymer offering precise thermoforming detail reproduction at low tooling cost. South Korean automotive electronics suppliers utilize this for prototype and low-volume production runs.
- PVC:Chlorinated polymer with established conductive compounding pathways and flame retardant options. Chinese manufacturers leverage existing extrusion infrastructure for basic ESD protection in non-cleanroom environments.
Polycarbonate commands the premium tier; polypropylene captures the highest shipment volumes across the region.
End User:
Customer maturity separates semiconductor fabs with multi-year qualification protocols from automotive suppliers operating on compressed product development timelines.
- Electronics Manufacturers:Contract assemblers and original equipment manufacturers handling integrated circuits, printed circuit boards, and discrete components. Procurement concentrates in China's eastern coastal provinces where Foxconn and Luxshare operate at scale.
- Healthcare Providers:Hospitals, clinics, and sterilization service providers managing implantable device supply chains. Australia's TGA imposes material traceability requirements that extend to ESD packaging in cardiac and orthopedic device logistics.
- Automotive Suppliers:Tier-one and tier-two component manufacturers supplying infotainment, advanced driver assistance, and power electronics modules. Japanese automotive electronics buyers parallel-track JIS compliance with IEC 61340-5-1 alignment.
- Aerospace Companies:Maintenance, repair, and overhaul operations plus original equipment manufacturing for avionics and satellite systems. Shepherd Thermoforming & Packaging Inc. targets this segment with custom tooling for mission-critical component handling.
Electronics Manufacturers generate the dominant order flow; Healthcare Providers are climbing the fastest as implantable device supply chains merge ISO 13485 with electrostatic protocols.
Distribution Channel:
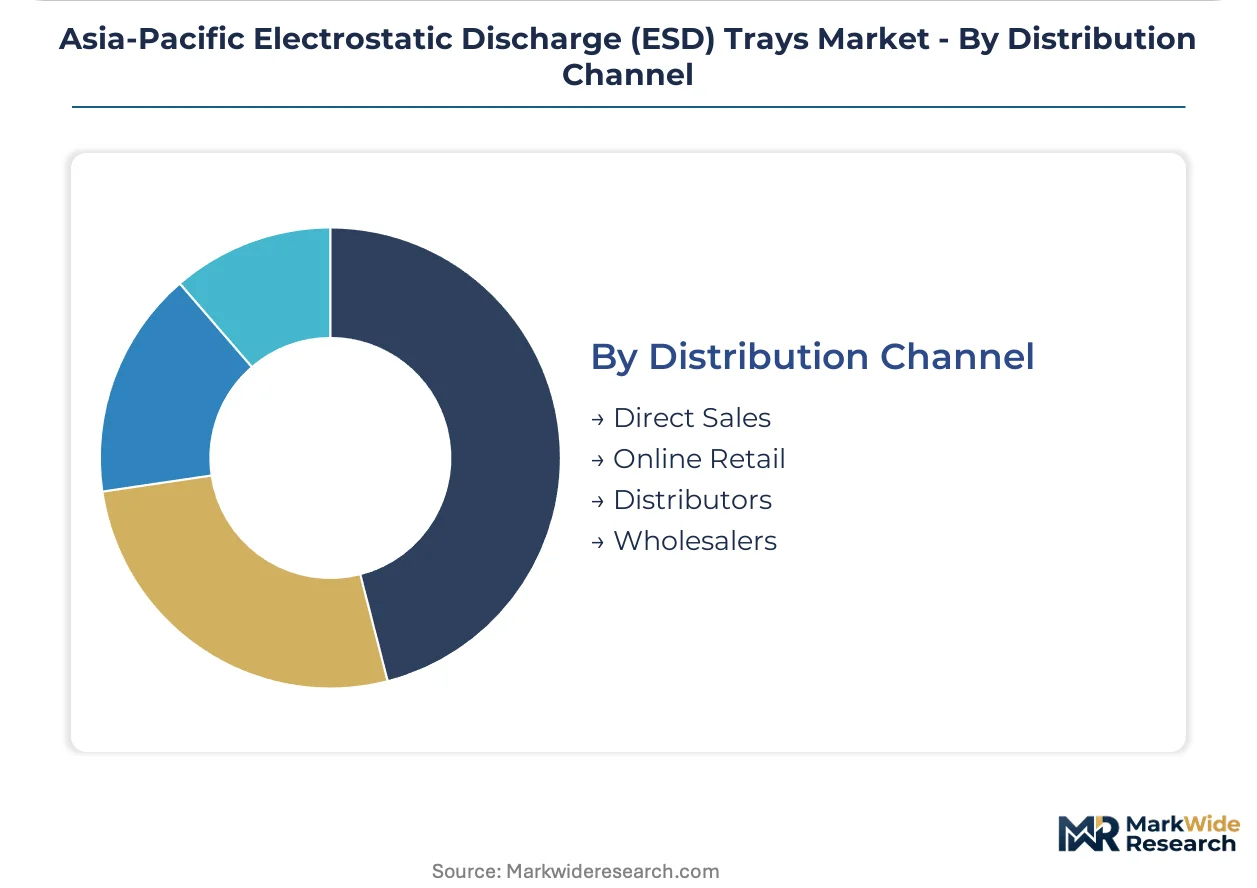
Channel selection reflects buyer scale and technical support requirements, with direct relationships dominating high-volume semiconductor procurement and intermediaries serving fragmented manufacturing bases.
- Direct Sales:Manufacturer-to-end-user relationships with embedded application engineering and vendor-managed inventory programs. Taiwanese foundry procurement teams mandate 48-hour replenishment commitments through these channels.
- Distributors:Authorized intermediaries holding regional inventory and providing technical certification documentation. GWP Group Limited anchors its regional footprint through specialized distributor partnerships.
- Online Retail:E-commerce platforms serving small-batch procurement and emergency replacement needs. Indonesian and Vietnamese contract manufacturers utilize these for standard stackable tray configurations.
- Wholesalers:Bulk aggregation points for commodity-grade ESD handling products without application engineering support. Legacy carbon-load formulations flow through this channel as GB standard tightening disqualifies them from certified supply chains.
Direct Sales capture the highest value transactions; Distributors are expanding most quickly as regional manufacturers seek localized technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in South Korean and Taiwanese semiconductor fabrication corridors while consumption pulls from contract electronics clusters across China's eastern seaboard. This spatial disconnect shapes logistics networks and supplier qualification protocols across the region.
China
SAMR enforcement of GB/T 32304 electrostatic control standards is disqualifying legacy carbon-load formulations from certified supply chains. The regulator mandates surface resistivity testing for all plastics entering semiconductor cleanrooms. Procurement volumes concentrate in Jiangsu and Guangdong provinces where Foxconn and Luxshare operate massive electronics assembly campuses.
South Korea
Wafer handling volume at Samsung and SK Hynix fabrication plants is pulling specialized conductive polymer trays into multi-year supply agreements. MFDS-aligned material traceability rules extend to ESD packaging in medical device export supply chains. Gyeonggi Province hosts the densest concentration of tray-qualified thermoforming capacity serving semiconductor handlers.
Taiwan
TSMC and UMC foundry procurement teams specify carbon nanotube-loaded compounds for 300mm wafer transport applications. The island's semiconductor supply chain operates under IEC 61340-5-1 protocols with parallel JIS alignment for Japanese automotive electronics buyers. Hsinchu Science Park anchors regional demand for thin-wall thermoformed configurations.
Japan
METI enforces JIS C 61340-5-1 compliance for electrostatic protected areas in automotive electronics plants. The regulator is accelerating revision cycles to harmonize test methodologies with IEC standards. Osaka and Nagoya industrial zones specify nesting-optimized stackable geometries to maximize vertical storage utilization in high-bay retrieval systems.
Vietnam
Contract manufacturers in Ho Chi Minh City industrial zones are upgrading from corrugated cardboard to certified ESD handling systems. Procurement teams at Foxconn and Luxshare facilities mandate vendor-managed inventory programs with 48-hour replenishment commitments. Localized thermoforming capacity struggles to match inventory turns demanded by tier-one electronics manufacturing service aggregators.
Asia-Pacific Electrostatic Discharge (ESD) Trays Market Competitive Landscape
The competitive structure tilts toward specialized thermoforming specialists with cleanroom polymer compounding expertise. Regional tray manufacturers face 18-24 month skill development cycles to replicate carbon nanotube dispersion techniques mastered by Japanese specialty compounders. Three archetypes dominate: conductive polymer formulators serving semiconductor fabs, precision thermoformers targeting medical device sterilization protocols, and custom tooling shops addressing aerospace-grade configurations. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers parallel-track GB standard testing with JIS compliance verification.
Among UK-based fabricators, Elcom (U.K.) Ltd. and GWP Group Limited occupy positions within the conductive polymer formulation tier. Shepherd Thermoforming & Packaging Inc. exemplifies the custom tooling archetype for mission-critical component handling. These three entities represent distinct competitive vectors: formulation chemistry, precision thermoforming capacity, and aerospace-grade configuration expertise respectively.
| Leading Market Players |
|---|
| Elcom (U.K.) Ltd. |
| Tandem Equipment Sales, Inc. |
| GWP Group Limited |
| Utz Group |
| Teknis Limited |
| AUER Packaging |
| Helios Packaging Pvt. Ltd. |
| Shepherd Thermoforming & Packaging Inc. |
| Conductive Containers, Inc. |
| Others |
Pricing and Supply Chain Analysis
Taiwanese foundry procurement teams commanding multi-year supply agreements for 300mm wafer transport trays dictate contract-based pricing structures that compress margin flexibility for regional thermoformers. Their vendor-managed inventory mandates with 48-hour replenishment commitments force suppliers to absorb working capital costs that spot-market buyers would reject.
Pricing Analysis
Margin tightening in polycarbonate sterilization-grade trays reflects acrylonitrile butadiene styrene resin volatility tied to crude oil derivatives. Three-tier pricing structure across premium carbon nanotube-loaded compounds, standard inherently dissipative polymers, and economy carbon-black formulations separates semiconductor fabs from Vietnamese contract manufacturers. Pricing pressure accelerates in polypropylene variants as Indonesian electronics clusters upgrade from corrugated alternatives. Healthcare providers in Australia prove least price-sensitive due to TGA-mandated traceability requirements, while Batam consumer electronics handlers prioritize unit cost above certification tier.
Supply Chain Analysis
Freight costs from South Korean and Taiwanese thermoforming corridors to Chinese eastern coastal provinces amplify total landed cost differentials against localized Vietnamese capacity. Raw material procurement draws from carbon black compounders in Japan, conductive polymer formulators in Taiwan, and ABS resin suppliers in South Korea. Single-source vulnerability concentrates among three regional carbon black compounders, exposing molders to allocation risk during semiconductor demand surges. Distribution runs through direct manufacturer relationships for high-volume foundry procurement, with distributor partnerships serving fragmented Indonesian and Vietnamese contract manufacturing bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as China's SAMR disqualifies legacy carbon-load formulations, forcing 18-24 month qualification investments that weaker regional manufacturers cannot fund.
For Market Incumbents: Lock in multi-year supply agreements with TSMC and Samsung procurement teams before carbon nanotube dispersion expertise becomes table stakes. Defend position by accelerating thin-wall thermoforming capacity in Gyeonggi Province to match 0.8mm wafer shipper specifications. Channel control through vendor-managed inventory programs creates switching costs that emerging Vietnamese capacity cannot replicate. For New Entrants and Emerging Players: Carbon nanotube-loaded compound development offers a technology-first wedge against incumbent carbon-black formulators facing SAMR disqualification. Target Indonesian Batam electronics clusters transitioning from corrugated handling systems, where first-mover certification contracts remain available. Pursue polylactic acid-based dissipative formulations aligned with Malaysia's plastics sustainability roadmap as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors thermoforming specialists with cleanroom polymer compounding expertise and existing JIS C 61340-5-1 compliance infrastructure. Long-term viability rests on suppliers capable of parallel-tracking GB standard testing with METI harmonization protocols. Watch for SAMR enforcement acceleration in Jiangsu and Guangdong provinces as the inflection indicator for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Nanotube Compound Qualification | Displaces legacy carbon-black formulations disqualified under SAMR's GB/T 32304 testing protocols. |
| Thin-Wall Thermoforming Capacity Expansion | Enables 0.8mm tray production demanded by TSMC and UMC for 300mm wafer transport applications. |
| Dual Certification Parallel-Tracking | Reduces cost burden for suppliers serving cross-border electronics supply chains under METI and SAMR. |
| Vendor-Managed Inventory Programs | Matches 48-hour replenishment commitments mandated by Foxconn and Luxshare procurement teams. |
| Biodegradable Polymer Development | Captures Malaysian sustainability incentives for consumer electronics export packaging qualification. |
Research Methodology
Independent corroboration across procurement executives at Taiwanese foundries, quality engineering leads at South Korean semiconductor fabs, and thermoforming operations managers in Gyeonggi Province underwrites the qualitative findings. Secondary validation draws from SAMR regulatory filings, METI standard revision notices, JIS C 61340-5-1 test protocol documentation, and customs trade data for conductive polymer imports. Bottom-up shipment estimates from regional thermoforming capacity triangulate against top-down demand calculations from wafer handling volume disclosures.
Comparable-period anchoring connects the projection horizon to historical procurement patterns through semiconductor fabrication capacity expansion cycles. Segmentation modeling spans product type configurations, material grade tiers, end-use industry verticals, and distribution channel structures. CAGRs derive from elasticity-adjusted volume projections calibrated to foundry capital expenditure trajectories and contract electronics manufacturing output indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ABS resin price spikes or accelerated SAMR enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market