
 ESD Workstations Market | 2026-2036
ESD Workstations Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Workstations Market Foresight
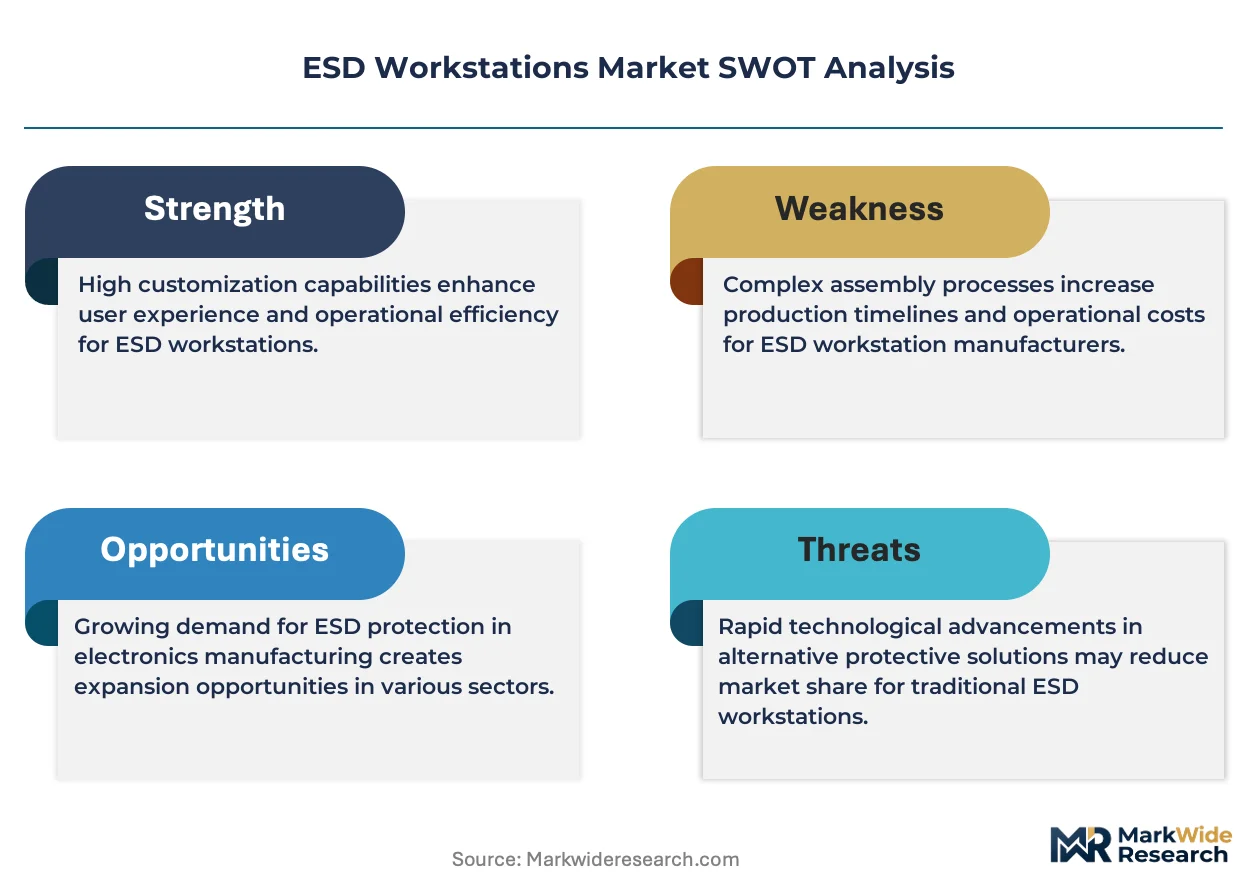
Subscription-based calibration and grounding verification services is rebalancing how ESD workstation vendors capture lifetime value from installed bases. Treston leverages its Nordic manufacturing footprint to sustain premium positioning in modular systems for aerospace electronics. Desco Industries Inc. anchors the North American aftermarket through deep channel control in static-control consumables and workstation accessories. Bosch Rexroth AG competes by extending its aluminum framing expertise from automation into configurable ESD bench architectures.
An ESD workstation is an electrically grounded work surface assembly designed to dissipate static charges from personnel, tools, and components, typically incorporating conductive or static-dissipative materials with resistance between 10^6 and 10^9 ohms to ground. Its primary purpose is preventing electrostatic discharge damage to sensitive electronic components during assembly, test, and repair operations. Benchtop configurations occupy the largest installed base across mature electronics manufacturing regions, while modular systems capture the fastest growth as facilities reconfigure lines for mixed-product assembly. Steel-framed units dominate price-sensitive procurement in high-volume contract manufacturing, whereas aluminum and laminated wood variants command margin premiums in laboratory and precision instrument settings where thermal stability and chemical resistance matter.
IEC 61340-5-1 and ANSI/ESD S20.20 establish the foundational grounding and personnel grounding requirements that determine workstation design specifications and factory audit compliance. The EPA mandates workplace grounding standards through OSHA electrical safety regulations, while the EU RoHS directive and REACH framework constrain surface material chemistries and conductive coating formulations. Stakeholders must monitor how evolving IEC standards for automated handling equipment integrate with workstation grounding architectures, as robotics penetration in electronics assembly redraws the boundary between fixed bench and mobile ESD-controlled environments.
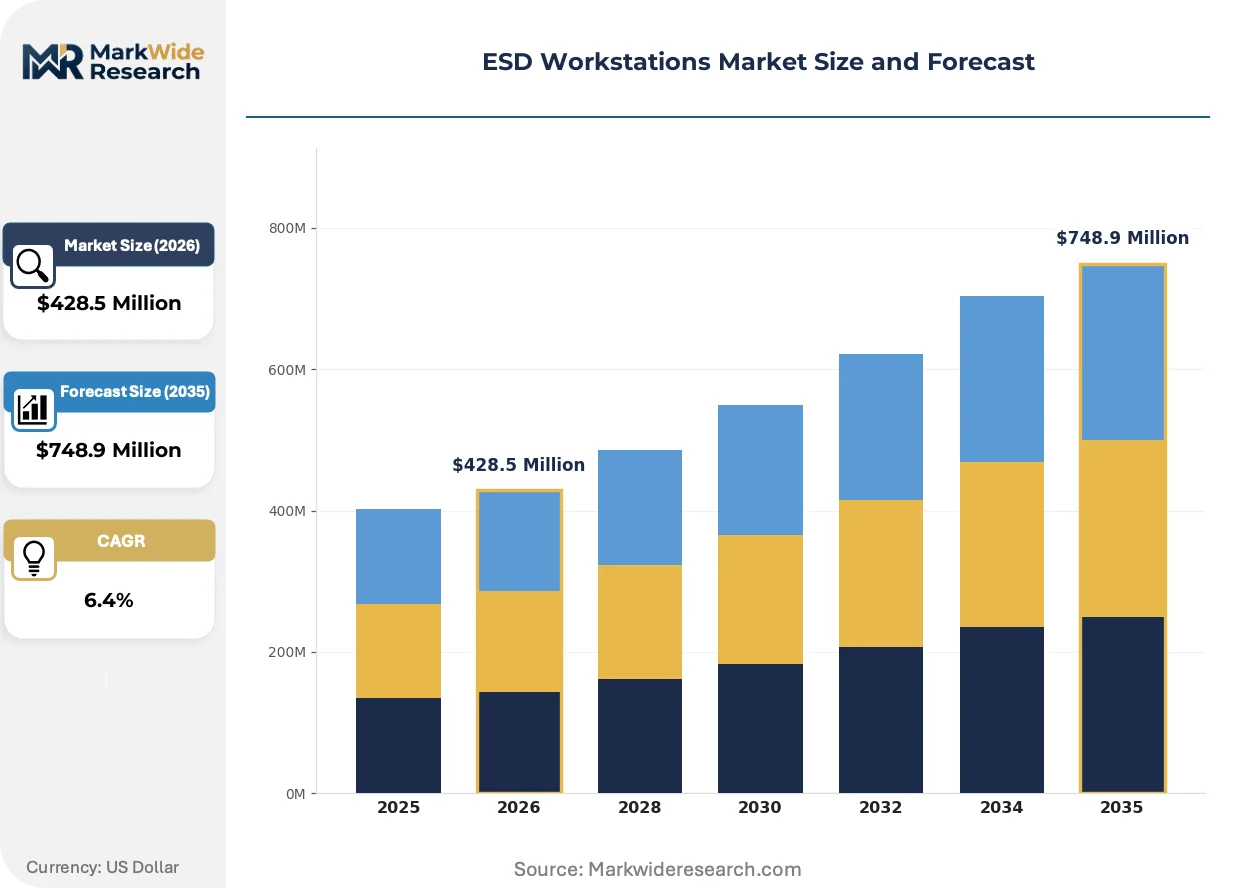
Market Dynamics
Modular bench architectures are displacing fixed installations as semiconductor fabs in Taiwan, South Korea, and the United States reconfigure cleanroom footprints for heterogeneous product mixes. This structural shift compresses replacement cycles and elevates grounding verification services from aftermarket add-on to core procurement criteria.
Growth Catalysts
- IEC 61340-5-1 compliance mandates:Electronics manufacturers in Mexico and Vietnam face audit pressure from OEM customers, forcing standardized ESD bench configurations into new contract assembly facilities.
- Lead-free soldering transition:Higher process temperatures in RoHS-compliant assembly increase static generation risks, tightening workstation grounding specifications across surface-mount operations.
- Cleanroom expansion:Wafer fabrication investments in Hsinchu and Pyeongtaek drive procurement of aluminum-framed modular systems with integrated ionization.
Market Restraints
- Copper and aluminum price volatility:Conductive surface materials and grounding busbars expose vendors to London Metal Exchange fluctuations, compressing margins on steel-alternative configurations.
- Regional supply concentration:Laminated wood work surface production clusters in Nordic and Baltic states, creating lead time vulnerability for premium laboratory-grade installations.
- Legacy facility retrofit costs:Older electronics plants in industrial zones lack adequate earth grounding infrastructure, raising total installation cost for IEC-compliant systems.
Strategic Opportunities
- Subscription calibration services:Vendors can capture recurring revenue through annual grounding verification contracts tied to ANSI/ESD S20.20 audit schedules.
- Robotics integration:Automated handling equipment in electronics assembly creates demand for mobile ESD-controlled environments bridging fixed bench and floor systems.
- India electronics manufacturing:PLI scheme incentives for semiconductor and component assembly concentrate new demand for standardized bench configurations in Gujarat and Tamil Nadu.
Industry Challenges
- Grounding technician certification gaps:Factory maintenance teams lack trained personnel for ANSI/ESD S20.20 internal audit execution, forcing reliance on third-party service providers.
- Multi-standard harmonization delays:Divergent IEC 61340-5-1 and ANSI/ESD S20.20 update cycles complicate product design for vendors serving both European and North American customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Workstations Market |
| Market Size in 2026 | $428.5 Million |
| Market Size in 2035 | $748.9 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Modular, Portable, Custom Material: Steel, Aluminum, Laminated Wood, Plastic Feature: Anti-Static Flooring, Grounding Systems, Adjustable Height, Work Surface Application: Electronics Assembly, Lab Work, Repair Services, Manufacturing |
| Companies Covered | Treston, IAC Industries, Bimos, Static Solutions Inc., Lista International Corp, Desco Industries Inc., 3M, Bosch Rexroth AG, Terra Universal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Workstations Market Shifts & Advancements
Real-time grounding monitoring is migrating from quality assurance laboratory to production floor, embedding sensor networks directly into bench architectures. This instrumentation shift redefines vendor value propositions from hardware supply to continuous compliance assurance.
IoT-enabled resistance monitoring is converging with ESD workstation grounding architectures to deliver continuous verification rather than periodic audit snapshots. Aerospace electronics manufacturers in Toulouse and Hamburg adopt these instrumented benches first, accepting 15-20% price premiums for automated alert capabilities. The technology is converging with predictive maintenance platforms, compressing the boundary between static control hardware and factory digitalization infrastructure.
REACH substance restrictions are constraining conductive coating chemistries used in static-dissipative work surfaces, forcing reformulation of carbon-loaded polymer top layers. ECHA's expanding SVHC candidate list pressures suppliers to eliminate legacy phthalate plasticizers ahead of sunset dates. European laboratory and medical device segments respond fastest, specifying certified halogen-free surfaces that command margin premiums over standard industrial grades.
Certification-driven procurement now dominates large electronics manufacturing services contracts, with ANSI/ESD S20.20 facility accreditation becoming a gate criterion for supplier qualification. Tier-one contract manufacturers in Shenzhen and Guadalajara unbundle workstation specification from general facility construction, engaging specialized ESD vendors directly rather than through general contractors. This pattern concentrates most visibly in automotive electronics supply chains, where OEM traceability requirements propagate downstream through multiple assembly tiers.
ESD Workstations Market Segmentation
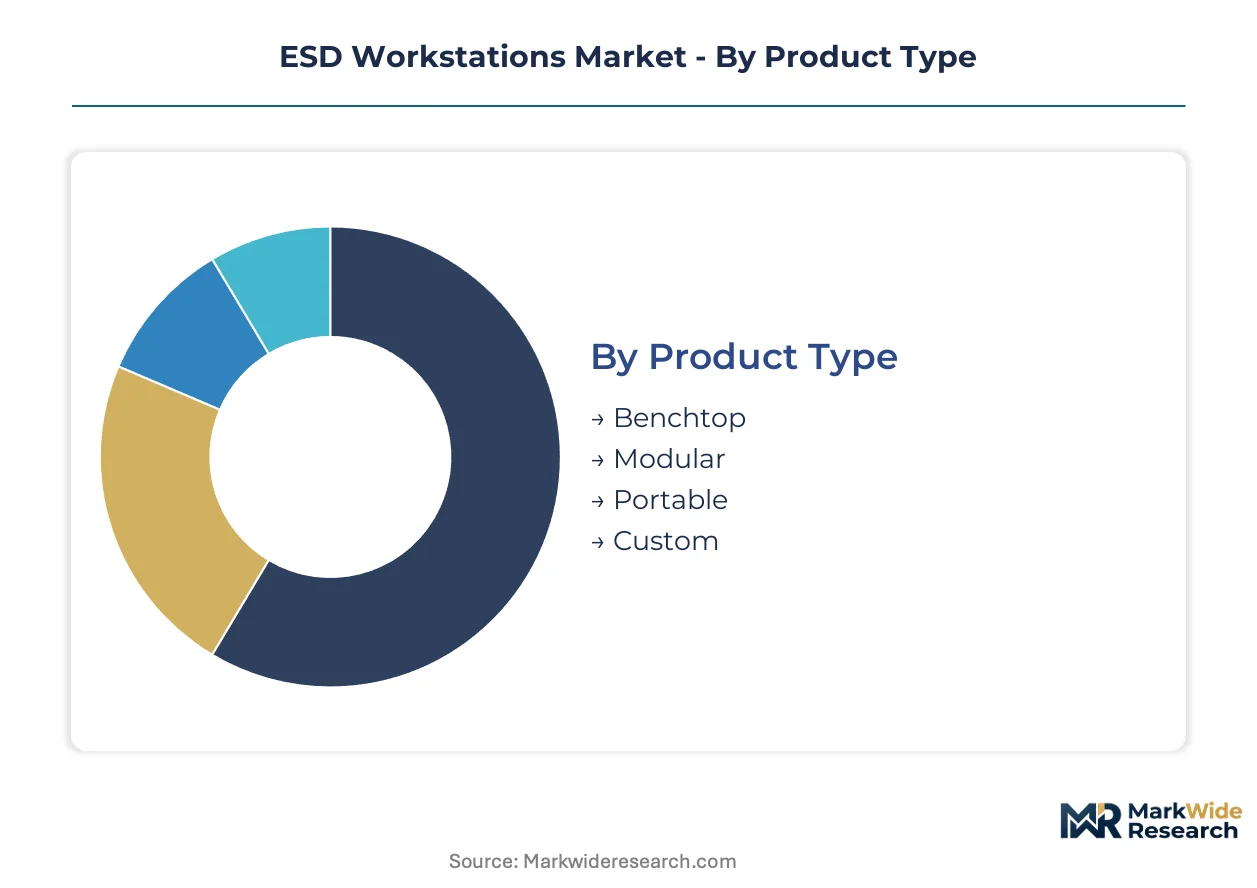
ESD workstation procurement decisions split sharply between certification-driven specifications for semiconductor fabs and cost-optimized configurations for contract assembly. Segmentation reveals how grounding architecture, material selection, and feature integration map to distinct compliance burdens and facility investment cycles.
Product Type:
Benchtop systems carry ANSI/ESD S20.20 facility accreditation requirements for electronics manufacturing services contracts, while modular architectures face evolving IEC standards for automated handling equipment integration.
- Benchtop:Fixed-surface assemblies with integrated wrist strap grounding points and static-dissipative mats dominate mature electronics manufacturing regions. Demand concentrates in Shenzhen and Guadalajara contract assembly corridors where OEM traceability requirements propagate through automotive electronics supply chains.
- Modular:Reconfigurable aluminum-framed systems with interchangeable work surfaces capture replacement cycle compression as Taiwan and South Korean semiconductor fabs retool for heterogeneous product mixes. Hsinchu and Pyeongtaek cleanroom expansions drive procurement with integrated ionization modules.
- Portable:Mobile grounding stations serve field repair operations and temporary production lines.
- Custom:Purpose-built configurations address aerospace electronics manufacturers in Toulouse and Hamburg requiring instrumented benches with IoT-enabled resistance monitoring.
Leading the category by volume: Benchtop. Growing fastest: Modular.
Material:
Material selection directly determines thermal stability, chemical resistance, and grounding path reliability across laboratory versus industrial environments.
- Steel:Carbon and stainless steel frames dominate price-sensitive procurement in high-volume contract manufacturing across Mexico and Vietnam. London Metal Exchange price volatility compresses margins when copper-aluminum alternatives face cost pressure.
- Aluminum:Extruded aluminum framing extends automation expertise into configurable ESD bench architectures with superior thermal stability for precision instrument settings. Taiwan semiconductor fabs specify these for cleanroom chemical resistance requirements.
- Laminated Wood:Nordic and Baltic production clusters create lead time vulnerability for premium laboratory-grade installations requiring halogen-free surface certification under REACH SVHC constraints.
- Plastic:Conductive polymer formulations face ECHA pressure to eliminate legacy phthalate plasticizers ahead of sunset dates.
Steel commands the largest installed base. Aluminum gains share fastest in semiconductor applications.
Feature:
Feature bundling separates periodic audit compliance from continuous verification models now migrating to production floors.
- Grounding Systems:Wrist strap and mat resistance verification circuits form the core compliance layer for ANSI/ESD S20.20 internal audit execution. Subscription-based calibration services reposition this feature from capital equipment to recurring revenue.
- Work Surface:Static-dissipative top layers with 10^6 to 10^9 ohms resistance specifications constrain formulation options as REACH restricts carbon-loaded polymer chemistries.
- Anti-Static Flooring:Integrated floor-to-bench grounding busbars protect against field-induced CDM failures in high-volume surface-mount operations.
- Adjustable Height:Ergonomic actuation systems add cost but reduce repetitive strain injury exposure in mixed-product assembly environments.
Grounding systems anchor every configuration. Real-time monitoring features expand most quickly.
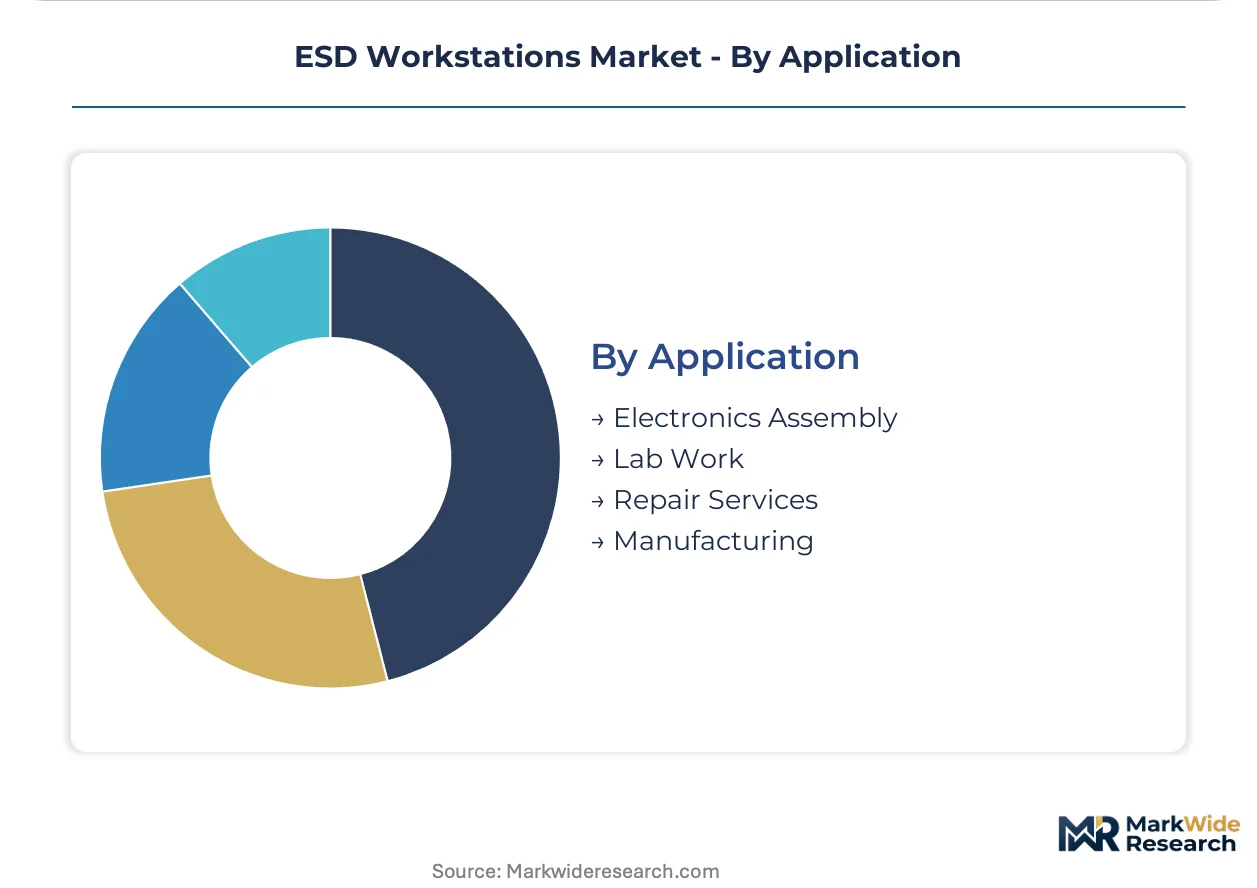
Application:
Application segmentation tracks how lead-free soldering transitions and cleanroom expansion reshape specification intensity.
- Electronics Assembly:Surface-mount and through-hole operations face tightened workstation grounding specifications as RoHS-compliant lead-free processes elevate static generation risks. India PLI scheme incentives concentrate new demand in Gujarat and Tamil Nadu.
- Lab Work:Medical device and analytical instrument settings command margin premiums for certified halogen-free surfaces and thermal stability. European segments respond fastest to ECHA substance restrictions.
- Repair Services:Field and depot maintenance operations prioritize portable configurations with rapid deployment capability.
- Manufacturing:General industrial applications absorb standardized bench configurations where IEC 61340-5-1 compliance mandates penetrate contract electronics assembly.
Electronics assembly generates the highest volume. Lab work delivers the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Nordic and Baltic manufacturing clusters while consumption gravitates toward semiconductor fabrication corridors in East Asia and contract assembly zones in North America. This geographic split creates divergent specification requirements across procurement markets.
United States
OSHA electrical safety regulations enforce workplace grounding standards that elevate compliance investment for electronics manufacturers. EPA mandates intersect with cleanroom expansion in Arizona and Texas semiconductor corridors. Austin and Phoenix fabs drive aluminum-framed modular system procurement with integrated ionization.
Taiwan
Hsinchu Science Park wafer fabrication investments compress replacement cycles for reconfigurable bench architectures. IEC 61340-5-1 compliance audits from OEM customers force standardized configurations into new facilities. Taichung and Tainan cleanroom footprints expand with heterogeneous product mix requirements.
South Korea
Pyeongtaek semiconductor complex drives demand for thermal-stable aluminum framing with chemical resistance specifications. MFDS-equivalent industrial safety frameworks tighten grounding verification protocols. Suwon and Gwangju electronics corridors absorb premium laboratory-grade installations.
China
MIIT standards for electronics manufacturing equipment intersect with RoHS-aligned lead-free soldering transitions. Shenzhen contract assembly corridors face ANSI/ESD S20.20 accreditation pressure from automotive OEM supply chains. Dongguan and Suzhou absorb standardized bench configurations for export-oriented production.
Germany
REACH SVHC constraints on conductive coating chemistries force reformulation of carbon-loaded polymer surfaces ahead of ECHA sunset dates. CE marking requirements propagate through medical device and analytical instrument procurement. Stuttgart and Munich aerospace electronics manufacturers specify instrumented benches with IoT-enabled monitoring.
ESD Workstations Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ESD workstation market. The vendor base separates between integrated manufacturers controlling conductive surface material supply and specialized assemblers sourcing standardized components. Three archetypes dominate: Nordic modular system specialists, North American aftermarket service integrators, and automation-derived aluminum framing entrants. Competitive moves concentrate on geographic footprint expansion through distribution partnerships and subscription-based calibration service bundling.
Among Nordic-based fabricators, Treston exemplifies premium modular positioning for aerospace and precision electronics applications. Desco Industries Inc. anchors the North American aftermarket through channel control in static-control consumables and workstation accessories. Bosch Rexroth AG represents the automation-to-bench extension archetype, leveraging extruded aluminum expertise from factory automation into configurable ESD architectures.
| Leading Market Players |
|---|
| Treston |
| IAC Industries |
| Bimos |
| Static Solutions Inc. |
| Lista International Corp |
| Desco Industries Inc. |
| 3M |
| Bosch Rexroth AG |
| Terra Universal |
| Others |
Supply & Pricing Matrix
London Metal Exchange copper and aluminum price volatility cascades through ESD workstation manufacturing, compressing margins on premium aluminum-framed configurations while reinforcing steel's dominance in price-sensitive contract assembly procurement across Mexico and Vietnam.
Pricing Analysis
Margin tightening in steel-framed bench systems reflects London Metal Exchange commodity pressure and concentrated buyer power among high-volume electronics manufacturing services. Three-tier pricing structure across premium, standard, and economy levels separates instrumented IoT-enabled benches for aerospace electronics from standardized configurations for automotive supply chains and bare-bones steel units for contract assembly. Certification grade under ANSI/ESD S20.20 and IEC 61340-5-1 drives price differentiation, with laboratory-grade halogen-free surfaces commanding substantial premiums over industrial grades. Cost-down pressure on economy tiers accelerates because Vietnam and Mexico facility construction absorbs standardized configurations at volume scale. Contract manufacturers in Shenzhen and Guadalajara exhibit highest price sensitivity, while semiconductor fabs in Hsinchu and Pyeongtaek prioritize thermal stability and chemical resistance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns serving European aerospace electronics and Asian semiconductor corridors. Manufacturing concentrates in Nordic and Baltic states for laminated wood work surfaces, Germany for extruded aluminum framing, and China for steel components and conductive polymer formulations. Raw material dependencies draw from copper and aluminum smelters, carbon-loaded polymer compounders, and halogen-free resin suppliers. Single-source vulnerability in Nordic laminated wood production creates lead time exposure for premium laboratory-grade installations. Distribution runs through specialized industrial equipment distributors, direct OEM relationships for large fab projects, and aftermarket service networks for calibration and grounding verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ESD workstation market is consolidating around vendors controlling both hardware supply and recurring calibration services, with REACH substance restrictions and IoT instrumentation investments forcing smaller assemblers toward exit or acquisition.
For Market Incumbents: Extend subscription-based calibration service bundling to capture lifetime value from installed bases in Taiwan and South Korean semiconductor fabs. Deepen backward integration into conductive surface material supply to offset London Metal Exchange volatility and REACH reformulation costs. Anchor channel control in static-control consumables to defend against automation-derived aluminum framing entrants from factory automation sectors. For New Entrants and Emerging Players: IoT-enabled resistance monitoring technology offers entry wedge into aerospace electronics manufacturers in Toulouse and Hamburg accepting price premiums for automated compliance assurance. Target India's PLI scheme electronics manufacturing incentives in Gujarat and Tamil Nadu for standardized bench configurations ahead of incumbent distribution buildout. Pursue direct engagement with tier-one contract manufacturers unbundling workstation specification from general facility construction. For Investors and Strategic Acquirers: Distressed-cycle entries favor Nordic modular system specialists with captive laminated wood supply and established aerospace certification relationships. Long-term viability centers on vendors bridging static control hardware with factory digitalization infrastructure over the coming decade. Monitor ECHA SVHC candidate list expansion pace as inflection indicator for conductive coating reformulation cost exposure and margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Calibration Service Launch | Transforms vendor economics from transactional hardware to recurring revenue anchored in ANSI/ESD S20.20 audit schedules. |
| Backward Integration into Conductive Surfaces | Captive supply of carbon-loaded polymer formulations insulates margins from REACH-driven raw material substitution costs. |
| IoT-Enabled Monitoring Platform Development | Converges ESD workstation grounding with predictive maintenance infrastructure for aerospace and precision electronics segments. |
| India Distribution Footprint Establishment | Positions ahead of PLI scheme semiconductor and component assembly concentration in Gujarat and Tamil Nadu corridors. |
| Halogen-Free Surface Certification Investment | Captures margin premiums from European medical device and laboratory segments responding fastest to ECHA substance restrictions. |
Research Methodology
Document review covered IEC and ANSI/ESD standards documentation, EPA and OSHA regulatory filings, ECHA SVHC candidate lists, and semiconductor fab construction announcements, complemented by interviews with ESD workstation procurement managers at contract manufacturers, cleanroom engineering directors, grounding verification service technicians, and conductive material compounders. Secondary validation drew from customs trade data, industrial equipment distributor sales records, and electronics manufacturing services facility accreditation databases. Bottom-up unit shipment estimates triangulated against top-down facility investment and cleanroom expansion projections.
Segmented outputs across product type, material, feature, and application dimensions were generated through the projection horizon, with particular attention to modular system displacement of fixed installations and real-time monitoring feature penetration. CAGRs were derived from facility investment cycle analysis and replacement frequency compression in heterogeneous product mix environments. Forecast inputs incorporated London Metal Exchange price trajectory assumptions, REACH substance restriction implementation timelines, and PLI scheme incentive disbursement patterns.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting aluminum extrusion trade flows, unanticipated ECHA acceleration of phthalate plasticizer sunset dates, and semiconductor demand cyclicality beyond fab construction commitments already announced. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market