
 UAE Electrostatic Discharge (ESD) Films Market | 2026-2036
UAE Electrostatic Discharge (ESD) Films Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Electrostatic Discharge (ESD) Films Market Insights
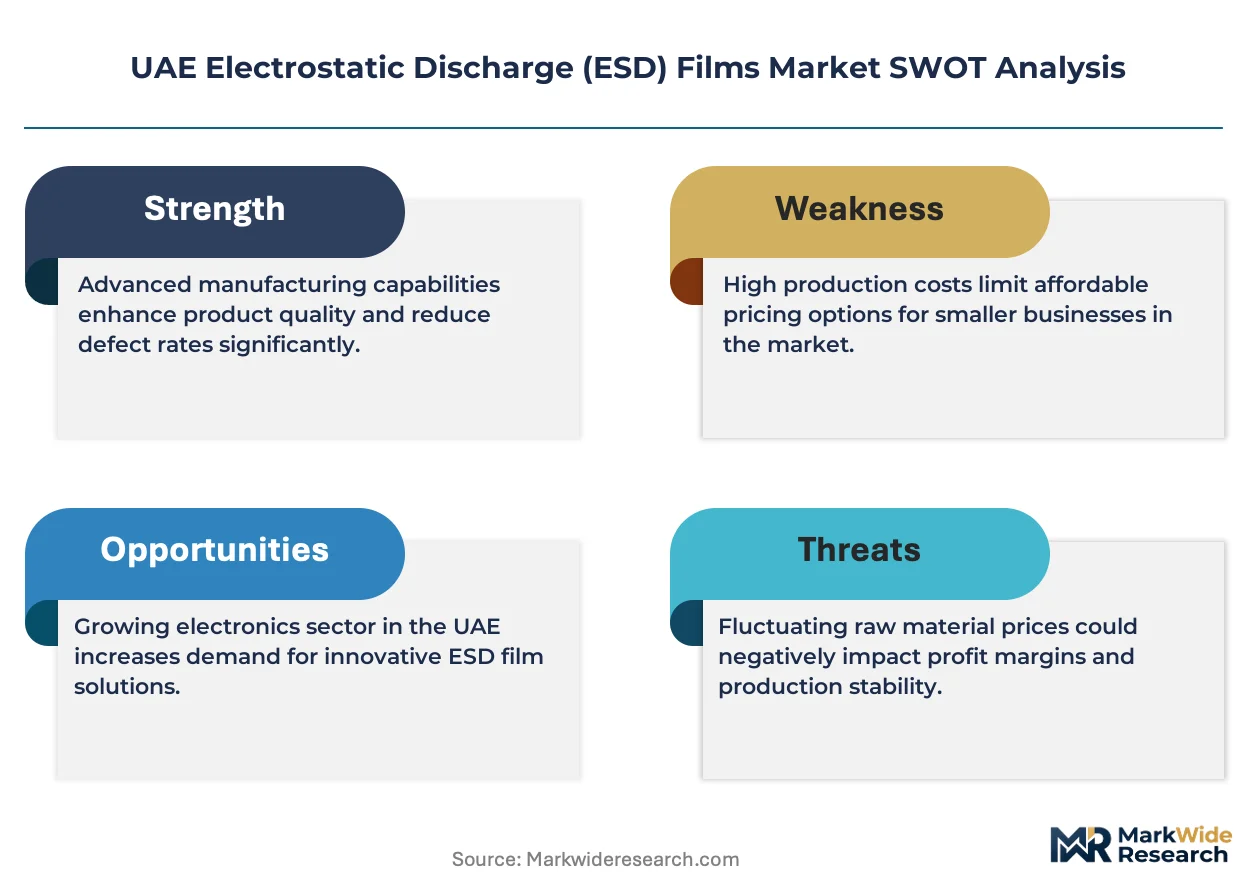
ANSI/ESD S20.20 certification is reorganizing competitive access across the UAE Electrostatic Discharge (ESD) Films Market, filtering out suppliers lacking verified static-control management systems. Desco Industries leverages its North American certification pedigree to anchor premium positioning among Emirates-based semiconductor assemblers. BASF competes through polymer R&D intensity, sustaining formulation advantages in conductive polyethylene grades. DowDuPont differentiates via backward integration into specialty resin production, controlling raw material consistency for thin-gauge ESD films.
Electrostatic Discharge (ESD) Films are multilayer polymer laminates engineered with carbon-loaded or metallic-conductive coatings to maintain surface resistivity between 10^4 and 10^11 ohms per square, dissipating static charges that would otherwise destroy sensitive electronic components during handling, transit, and storage. Polyethylene formulations dominate volume due to cost-efficient extrusion and broad compatibility with cleanroom protocols, while PET variants command margin pools in medical device packaging where optical clarity and barrier properties converge. The 100-micron thickness segment leads unit shipments across electronics applications, though 50-micron grades are gaining traction in automotive sensor packaging where miniaturization dictates material efficiency.
MOHAP's medical device import regulations and the UAE's mandatory ECAS conformity assessments under the Emirates Authority for Standardization and Metrology (ESMA) framework shape product compliance requirements, forcing film converters to maintain dual-certification portfolios for healthcare and industrial end-uses. The country's alignment with IEC 61340-5-1 international standards further tightens technical specifications for suppliers targeting electronics OEMs in Dubai Silicon Oasis and Abu Dhabi's industrial corridors. Stakeholders must monitor evolving ESMA technical regulations and MOHAP device-safety circulars to anticipate compliance-driven specification changes before they disrupt supply qualifications.
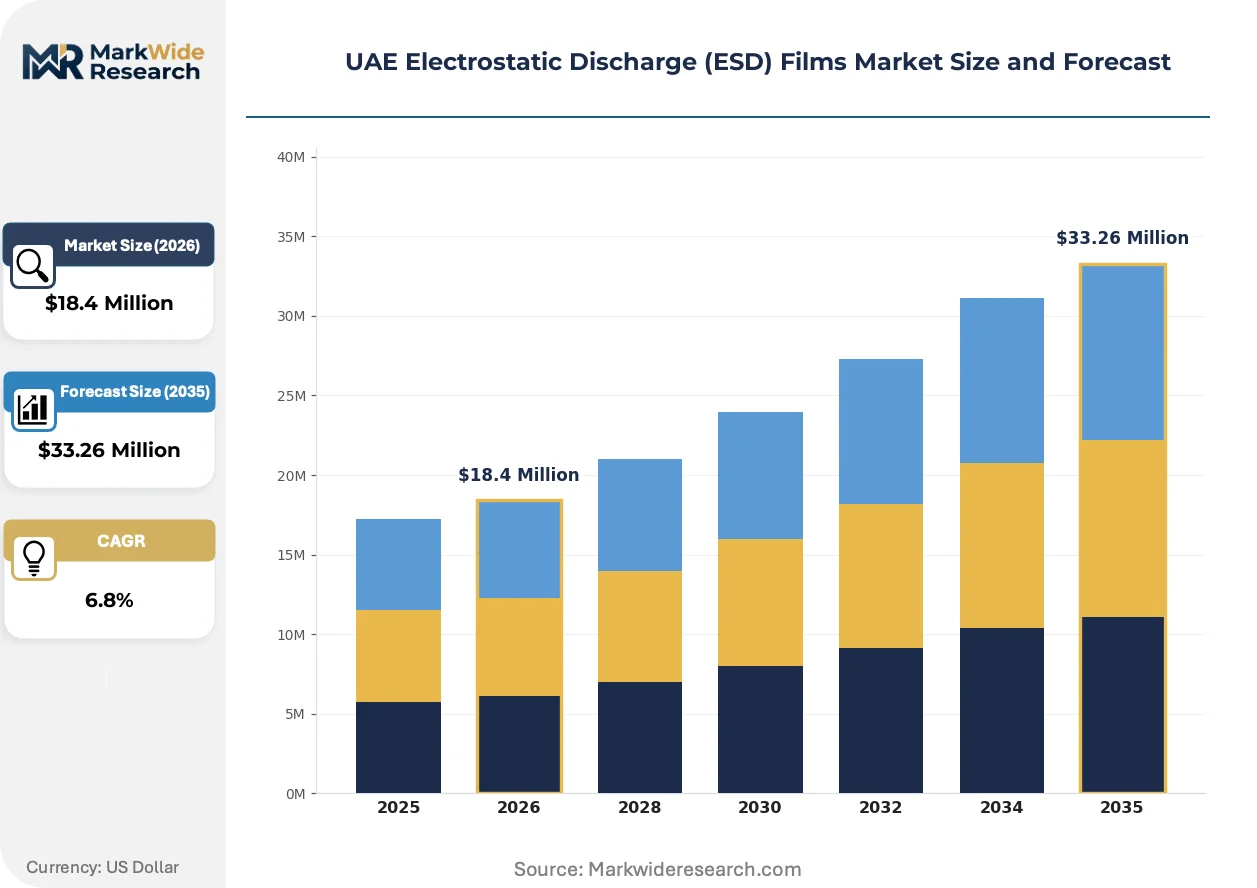
Market Dynamics
ANSI/ESD S20.20 certification requirements are reorganizing supplier access across the UAE Electrostatic Discharge Films Market, filtering out converters lacking verified static-control management systems and compressing procurement timelines for qualified vendors.
Growth Catalysts
- Semiconductor packaging expansion:Dubai Industrial City's cleanroom operations are scaling orders for ESD-compliant materials as chip assembly capacity expands.
- MOHAP medical device mandates:Static-control packaging is now compulsory for imported electronics under revised safety protocols, creating regulated demand pull.
- Advanced manufacturing clustering:Abu Dhabi's Khalifa Industrial Zone precision film requirements are concentrating specification-driven procurement among certified suppliers.
Market Restraints
- Conductive additive cost volatility:Carbon black and metallic filler prices fluctuate with petrochemical feedstock movements, squeezing converter margins.
- Specialty resin supply concentration:Polyethylene and PET grades with controlled conductivity depend on limited Gulf petrochemical producers.
- Dual-certification burden:ESMA ECAS conformity plus MOHAP medical protocols force redundant testing cycles for healthcare-industrial crossover suppliers.
Strategic Opportunities
- Ras Al Khaimah industrial corridor:Underpenetrated aerospace component manufacturing is emerging as a new demand pocket for precision ESD solutions.
- Automotive sensor packaging:EV battery management systems and LiDAR modules are opening specification windows for 50-micron thin-gauge films.
- ESMA technical regulation evolution:Anticipated alignment with updated IEC 61340-5-1 revisions will reward early-adopter certification investments.
Industry Challenges
- Cleanroom technician scarcity:Qualified personnel for extrusion line operation in ISO Class 7 environments are concentrated among a small pool of UAE-based converters.
- ANSI/ESD S20.20 audit timelines:Certification cycles stretch supplier qualification periods, delaying purchase order activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Electrostatic Discharge (ESD) Films Market |
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $33.26 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Packaging, Electronics, Automotive, Medical Thickness: 50 microns, 100 microns, 200 microns, 300 microns Customization Level: Standard, Custom, Pre-cut, Printed |
| Companies Covered | Desco Industries, BASF, Smurfit Kappa Group, DowDuPont, PPG Industries, Sealed Air Corporation, ACHILLES CORPORATION, Nefab Group, Widaco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Electrostatic Discharge (ESD) Films Market Trends and Innovations
Material science advances and regulatory harmonization are compressing product development cycles while fragmenting procurement patterns across industrial and medical end-uses in the UAE market.
Multilayer coextrusion with carbon-loaded interlayers is miniaturizing film gauges without sacrificing surface resistivity performance. Automotive sensor manufacturers in Dubai Silicon Oasis are adopting 50-micron constructions for battery management system packaging. This thickness compression is miniaturizing material consumption per unit while demanding tighter tolerances from extrusion equipment.
MOHAP's alignment with IEC 61340-5-1 technical specifications is tightening import documentation requirements for medical device packaging. Film converters must now maintain traceable resistivity testing records across production lots. Healthcare distributors in Abu Dhabi are responding by consolidating supplier relationships around dual-certified vendors.
Direct mill relationships are displacing traditional distributor intermediaries among large semiconductor assemblers. Emirates-based electronics OEMs now negotiate annual volume contracts with extrusion specialists rather than regional traders. This channel compression is most visible in Dubai Industrial City, where procurement teams have established technical qualification gates that bypass conventional stocking distributors.
UAE Electrostatic Discharge (ESD) Films Market Segmentation
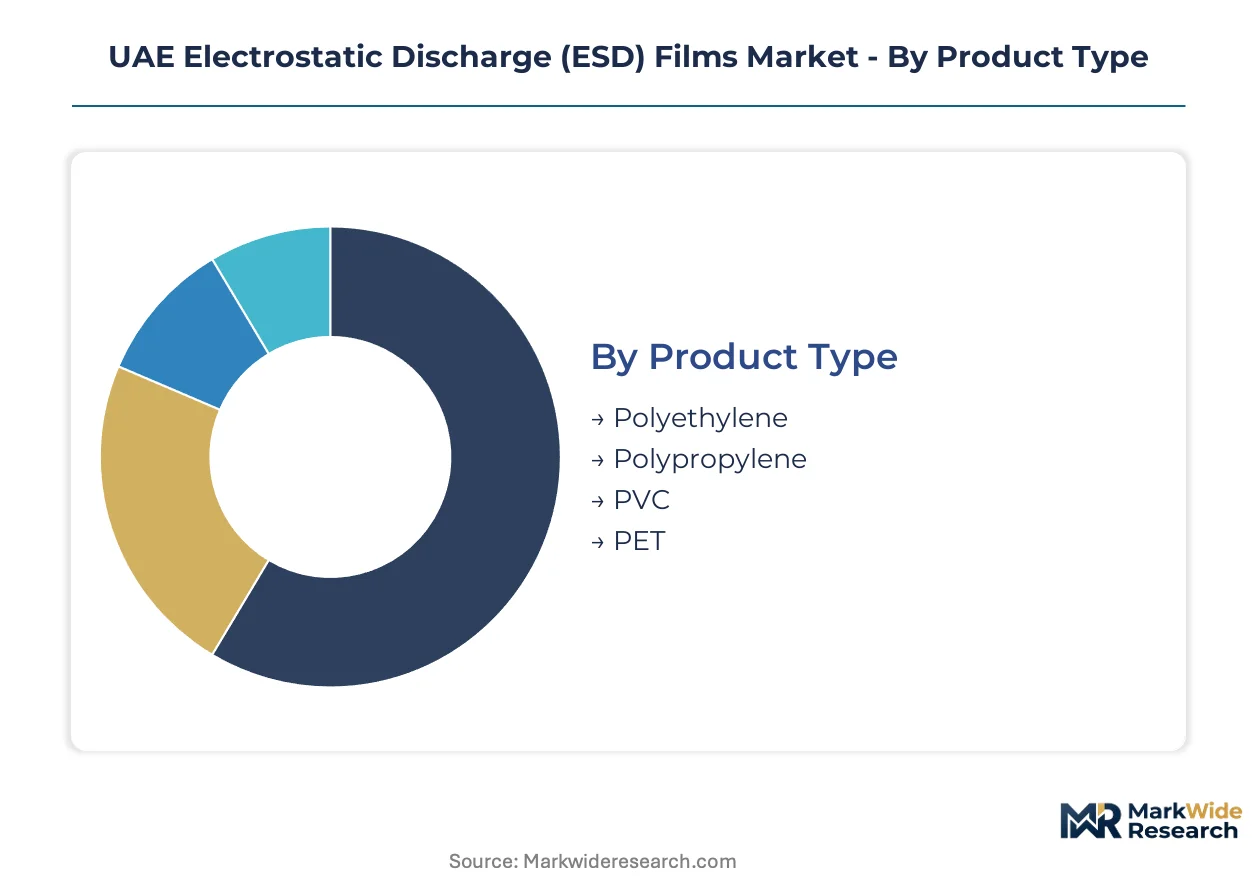
ESD film procurement across the Emirates fragments along technical specifications and end-use compliance requirements. Converter margins vary dramatically by thickness grade and certification burden, creating distinct competitive arenas within each category.
Product Type:
Polyethylene formulations anchor domestic consumption, while PET grades serve export-oriented medical device manufacturers under MOHAP protocols.
- Polyethylene:Carbon-loaded LDPE and LLDPE formulations dominate volume through cost-efficient extrusion and broad cleanroom compatibility. Dubai Industrial City's semiconductor packagers specify this grade for standard moisture-barrier applications where optical clarity is secondary.
- PET:Biaxially oriented polyester with vapor-deposited metallic coatings delivers the surface resistivity and barrier performance required for medical device packaging. Abu Dhabi healthcare distributors favor this grade under MOHAP's traceable resistivity documentation mandates.
- Polypropylene:Cast PP variants offer intermediate stiffness for automotive component trays serving Ras Al Khaimah aerospace suppliers.
- PVC:Plasticized formulations retain niche presence in legacy electronics warehousing applications with lower cleanliness requirements.
Polyethylene commands the established base. The steepest expansion runs through PET.
Application:
Cost tiers separate commodity packaging from regulated medical and precision automotive segments with divergent certification investments.
- Packaging:Standard shielding bags and tubing for general electronics distribution constitute the volume foundation. Khalifa Industrial Zone logistics operators drive specification standardization here.
- Medical:Sterile barrier systems with validated seal integrity attract premium positioning. MOHAP's static-control mandates for imported devices concentrate procurement among dual-certified converters in Abu Dhabi.
- Electronics:Wafer shipping boxes and disk drive enclosures require ANSI/ESD S20.20-compliant materials. Dubai Silicon Oasis cleanroom operations are the primary demand cluster.
- Automotive:LiDAR module and battery management system packaging is shifting toward 50-micron constructions for material efficiency. Dubai-based EV component assemblers are emerging as specification influencers.
Packaging absorbs the highest tonnage. Medical applications are climbing the fastest.
Thickness:
Volume concentration sits at 100 microns, though customer type differentiation is accelerating gauge fragmentation.
- 100 microns:The workhorse specification balances puncture resistance with material economy across electronics and industrial packaging. Most Dubai Industrial City extrusion lines are calibrated for this thickness.
- 50 microns:Miniaturized constructions for automotive sensors and portable medical devices demand tighter extrusion tolerances. Adoption is concentrating among Tier 1 automotive suppliers in Dubai.
- 200 microns:Heavy-duty cushioning for aerospace component shipping retains stable demand from Ras Al Khaimah manufacturers.
- 300 microns:Maximum protection grades for capital equipment transit represent a thin margin pool with limited converter participation.
100-micron films command the established base. The steepest expansion runs through 50-micron grades.
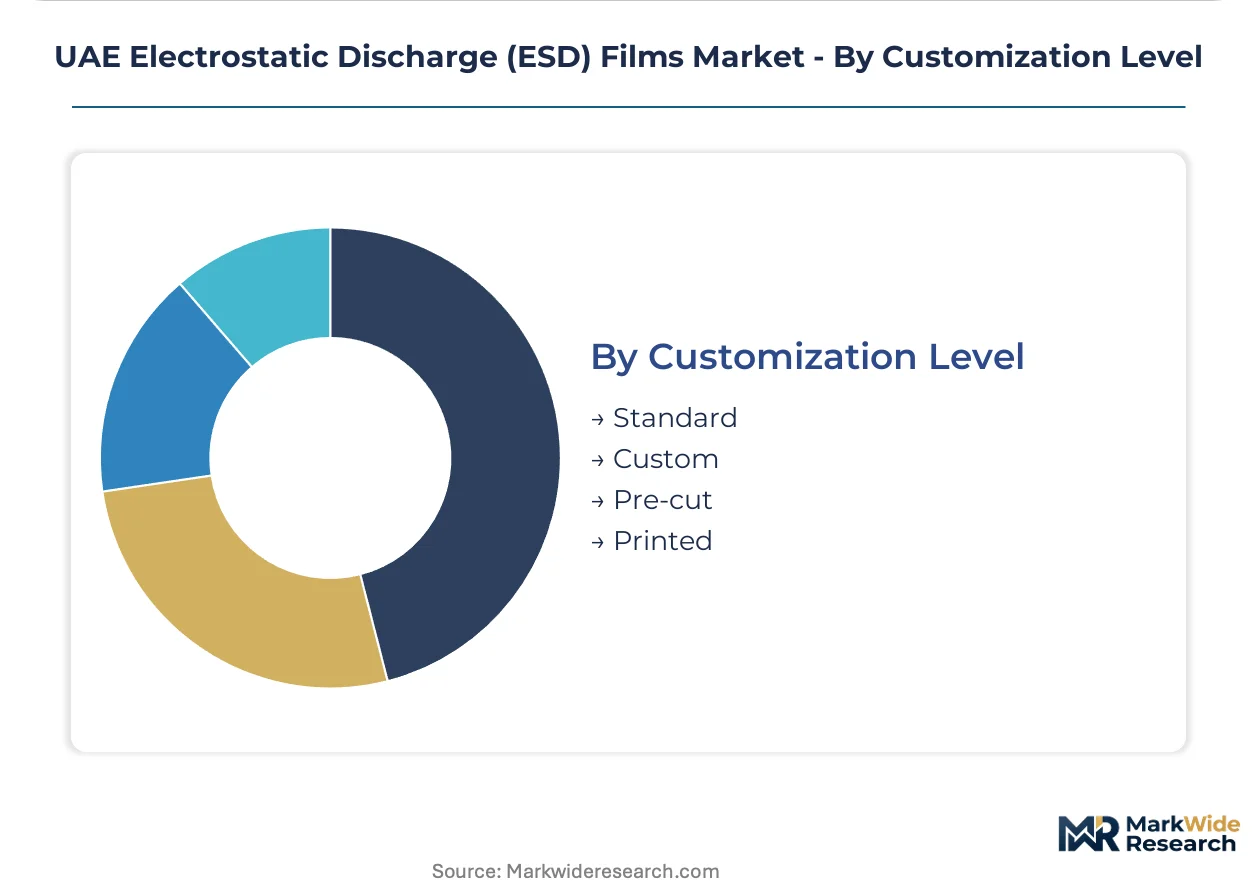
Customization Level:
Supply concentration favors standard products, while margin pools concentrate in value-added conversion services.
- Standard:Off-the-shelf rolls and bags dominate procurement for high-volume electronics distributors. ESMA ECAS conformity is the primary qualification gate.
- Custom:Tailored dimensions and multi-layer constructions for specialized cleanroom protocols attract premium pricing. Semiconductor OEMs in Dubai Silicon Oasis drive this segment.
- Pre-cut:Die-cut sheets and formed trays eliminate downstream processing for medical device assemblers. MOHAP lot traceability requirements favor established converters with validated cutting operations.
- Printed:Logo and warning mark integration serves branded medical packaging and aerospace component identification. Minimum order quantities restrict this tier to large healthcare distributors.
Standard products command the established base. Custom configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput capacity underwrites the UAE's distribution hub status for ESD film imports serving Gulf electronics manufacturing. Khalifa Port's deep-water berths anchor Abu Dhabi's petrochemical feedstock access for domestic extrusion operations.
Dubai
Dubai Industrial City's cleanroom packaging operations are scaling procurement of ANSI/ESD S20.20-certified films for semiconductor assembly. Dubai Silicon Oasis free zone regulations mandate static-control documentation for all electronics OEMs. Jebel Ali logistics corridors concentrate specification-driven distributor consolidation among certified converters.
Abu Dhabi
Khalifa Industrial Zone's advanced manufacturing clusters are driving precision film demand for medical device and aerospace component packaging. MOHAP's import safety protocols require traceable resistivity testing for all static-control materials entering healthcare supply chains. KIZAD's polymer conversion facilities are expanding extrusion capacity for PET-grade ESD laminates.
Sharjah
Sharjah's industrial zones are emerging as cost-competitive conversion locations for standard polyethylene ESD films serving Gulf electronics distributors. The emirate's proximity to Dubai's procurement hubs enables just-in-time logistics without premium land costs. Hamriyah Free Zone is attracting secondary-tier converters seeking ESMA ECAS certification for regional market access.
Northern Emirates
Ras Al Khaimah's aerospace component manufacturing corridor is generating new demand pockets for heavy-gauge ESD cushioning films. Al Ain industrial zones near the Oman border are developing as alternative extrusion locations for petrochemical feedstock from Borouge's Ruwais complex. Fujairah's port infrastructure is enabling direct carbon black and conductive additive imports bypassing Dubai transshipment.
UAE Electrostatic Discharge (ESD) Films Market Competitive Landscape
Listed leaders compete with private specialists across certification pedigree and polymer formulation capabilities. The supplier base fragments vertically between resin producers, extrusion specialists, and conversion houses. Three archetypes dominate: petrochemical majors with captive resin supply, North American certification leaders with ANSI/ESD S20.20 pedigree, and regional distributors with ESMA conformity expertise. Capacity expansion and backward integration into specialty resin production represent the dominant competitive moves.
Within the certification-pedigree tier, Desco Industries and DowDuPont exemplify North American-standard positioning among Emirates-based semiconductor assemblers. BASF anchors the petrochemical-major archetype with polymer R&D intensity sustaining formulation advantages. These three companies occupy positions that reflect the market's tension between global certification standards and regional compliance requirements.
| Leading Market Players |
|---|
| Desco Industries |
| BASF |
| Smurfit Kappa Group |
| DowDuPont |
| PPG Industries |
| Sealed Air Corporation |
| ACHILLES CORPORATION |
| Nefab Group |
| Widaco |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Dubai Industrial City semiconductor packagers and extrusion specialists lock in both supply access and price visibility, insulating qualified converters from carbon black cost volatility while compressing procurement timelines for buyers seeking ANSI/ESD S20.20-certified materials.
Pricing Analysis
Volume-discount tiering structures separate annual contract holders from spot purchasers across the Emirates, with three-tier pricing stratification across premium certified, standard industrial, and economy grades. Certification level—specifically ANSI/ESD S20.20 and ESMA ECAS dual compliance—commands the steepest premium, followed by customization depth and cleanroom compatibility. Pricing pressure stems from conductive additive cost volatility, particularly carbon black fluctuations tied to petrochemical feedstock movements. General electronics distributors exhibit highest price sensitivity, while MOHAP-mandated medical device packers prioritize traceability over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate Dubai Industrial City operations, though strategic stockpiling of specialty polyethylene resins persists among Abu Dhabi converters facing Borouge supply allocation constraints. Raw material sourcing draws from Saudi Arabia's petrochemical complexes, South Korean specialty resin producers, and German conductive additive suppliers. Carbon black supply concentration creates single-source vulnerability for thin-gauge film producers. Distribution runs through Jebel Ali Port's bonded warehousing for Gulf re-export, with direct mill relationships displacing traditional distributor intermediaries among large semiconductor assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE ESD Films Market rewards converters possessing verified cleanroom operations and dual-certification portfolios, with qualified technician scarcity creating defendable moats for incumbents who have already navigated ESMA and MOHAP compliance gauntlets.
For Market Incumbents: Secure backward integration into specialty resin production to control raw material consistency and buffer against carbon black price volatility. Expand extrusion capacity within Khalifa Industrial Zone to capture medical device packaging demand under MOHAP's traceable resistivity mandates. Defend against emerging regional competitors by deepening ANSI/ESD S20.20 audit relationships and accelerating certification cycle completion. For New Entrants and Emerging Players: ESMA ECAS fast-track certification offers the most viable entry path for regional converters seeking access to Dubai Industrial City's procurement gates. Target Sharjah's cost-competitive industrial zones for standard polyethylene film production serving Gulf electronics distributors. Ras Al Khaimah's underpenetrated aerospace component manufacturing presents a white-space opportunity for heavy-gauge ESD cushioning solutions. Differentiate through pre-cut and printed conversion services that eliminate downstream processing for medical device assemblers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap extrusion specialists with existing cleanroom infrastructure and dual-certification capabilities, positioned to consolidate fragmented regional supply. Long-term viability hinges on regulatory alignment rather than commodity volume scale. Watch for MOHAP protocol revisions expanding static-control mandates beyond imported electronics into domestic medical device manufacturing as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Production | DowDuPont's captive supply model demonstrates margin protection against petrochemical feedstock volatility. |
| Dual-Certification Investment | ESMA ECAS plus ANSI/ESD S20.20 compliance opens procurement gates at Dubai Silicon Oasis cleanroom operations. |
| Thin-Gauge Extrusion Capacity Expansion | 50-micron film production captures automotive sensor packaging demand from Dubai-based EV assemblers. |
| Direct Mill Relationship Development | Bypassing Jebel Ali distributors secures annual volume contracts with Khalifa Industrial Zone logistics operators. |
| Ras Al Khaimah Corridor Penetration | Aerospace component manufacturing generates new demand pockets for heavy-gauge ESD cushioning films. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing extrusion line managers at UAE-based converters, procurement leads at Dubai Industrial City semiconductor packagers, biomedical engineers at Abu Dhabi healthcare distributors, and logistics coordinators at Jebel Ali Port bonded warehousing facilities. Secondary validation drew from ESMA technical regulation circulars, MOHAP medical device safety protocols, IEC 61340-5-1 international standards documentation, and customs import records for conductive additive shipments. Bottom-up volume estimates from individual converter capacity were triangulated against top-down demand assessments derived from electronics manufacturing cluster expansion announcements.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, application end-use, thickness specification, and customization level, with particular attention to certification tier migration patterns. CAGRs were derived from segmented growth rate blending weighted by base-year value shares. Key inputs included semiconductor packaging capacity expansion timelines at Dubai Industrial City, MOHAP regulatory amendment schedules, and petrochemical feedstock price correlation models for conductive polyethylene formulations.
Underlying assumptions cover sustained petrochemical feedstock availability from Borouge's Ruwais complex, with deviation risk concentrated in carbon black supply disruptions and ANSI/ESD S20.20 audit backlog delays. Forecasts reflect these conditions holding within historical variance bands. Revision becomes warranted when MOHAP protocol expansions or ESMA technical regulation updates cross implementation thresholds that would respecify compliance requirements across the installed base.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market