
 Application Tapes Market | 2026-2036
Application Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Application Tapes Market Analysis
Asset-light leasing models for coating and converting equipment is rewriting competitive entry dynamics in the Application Tapes Market, enabling mid-scale regional converters to compete without capital-heavy solvent recovery infrastructure. 3M Company leverages its captive polymer science portfolio to sustain premium positioning across aerospace and medical bonding grades. Tesa SE anchors European automotive supply chains through direct OEM qualification programs that competitors struggle to replicate. Avery Dennison Corporation differentiates via integrated label-and-tape distribution networks controlling shelf space at industrial distributors.
Application tapes are pressure-sensitive adhesive constructions, typically 25–250 micrometers thick, comprising a facestock, adhesive layer, and release liner engineered for temporary or permanent bonding, surface protection, or assembly alignment across manufacturing workflows. Double-sided tapes and foam tapes lead product-type revenue pools due to structural bonding substitution in automotive lightweighting and electronics miniaturization, while transfer tapes capture the fastest expansion as display and semiconductor assembly demands near-invisible bond lines. Water-based adhesive technology now dominates new capacity investments as environmental compliance tightens, though solvent-based systems retain margin strength in high-performance aerospace and medical segments where outgassing specifications remain stringent.
EPA regulations on volatile organic compound emissions constrain solvent-based adhesive expansion in the United States, while REACH registration requirements in Europe redirect formulation investments toward water-based and hot-melt platforms. China's MEE enforcement of dual carbon goals accelerates domestic converter upgrades to cleaner coating technologies, reshaping import substitution patterns for foreign tape suppliers. Stakeholders must monitor evolving adhesive chemistries against regional compliance calendars and assess captive coating investments versus outsourced converting partnerships as tariff and carbon-border adjustments reshape landed cost structures.
Market Dynamics
Automotive OEMs are systematically replacing mechanical fasteners with bonding tapes to achieve lightweighting targets, compressing traditional fastener supply chains while expanding precision adhesive consumption across EV battery pack assembly and structural bonding applications.
Growth Catalysts
- EV Battery Assembly Expansion:Chinese EV manufacturers are scaling double-sided thermal interface tape consumption for module-to-pack bonding, creating sustained demand for high-temperature acrylic formulations.
- REACH Chemical Registration:European ECHA compliance deadlines are accelerating water-based adhesive capacity investments, opening conversion opportunities for regional converters with clean coating capabilities.
- Semiconductor Advanced Packaging:Die-attach and temporary bonding tapes for fan-out wafer-level packaging are capturing expanded share of assembly material spend as node sizes shrink.
Market Restraints
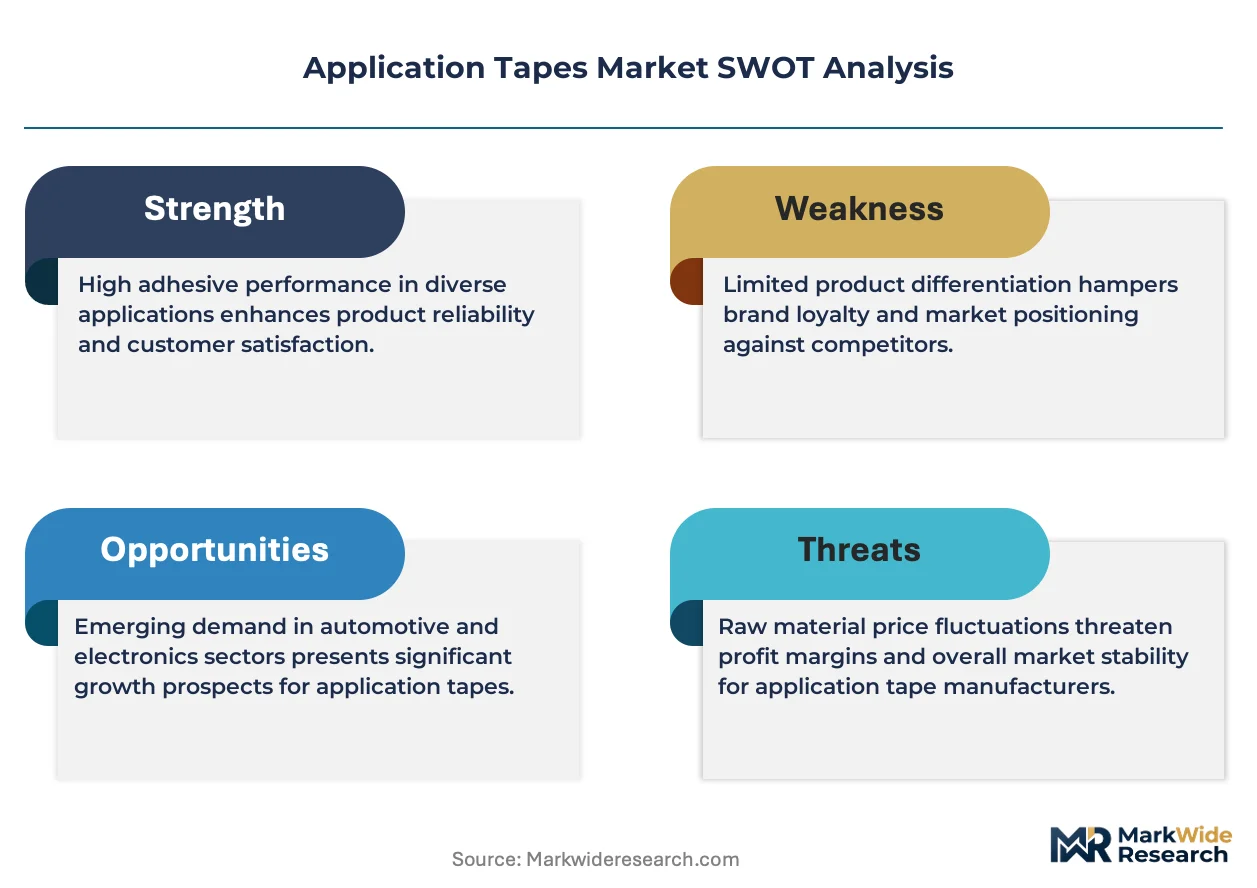
- Petrochemical Feedstock Volatility:Acrylic monomer and synthetic rubber prices fluctuate with crude oil indices, compressing margin stability for tape converters without backward integration into polymer production.
- Solvent Recovery Infrastructure Concentration:High-performance aerospace and medical tape production remains concentrated among North American and European coaters with EPA-compliant thermal oxidizer systems, limiting new entrant supply.
- Mechanical Fastener Substitution Resistance:Heavy-duty structural applications in commercial vehicle chassis assembly retain bolted and welded joints due to peel-strength limitations of current tape constructions.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for smartphone and component assembly are attracting tape distributors to establish converting partnerships near Noida and Sri City industrial corridors.
- Biodegradable Release Liners:Convergence of paper-based liner technology with compostable adhesive chemistries is opening sustainable positioning for premium consumer electronics packaging applications.
- Digital Print-on-Demand Converting:Short-run custom die-cutting services via e-commerce platforms are capturing prototype and maintenance-repair-operations demand previously served through industrial distributor networks.
Industry Challenges
- Adhesive Formulation Expertise Gap:Shortage of polymer chemists with pressure-sensitive adhesive compounding experience is extending product development cycles for regional converters attempting aerospace qualification.
- OEM Direct Qualification Timelines:Automotive Tier-1 supplier approval processes for structural bonding tapes require 18-36 month validation protocols, freezing out smaller competitors without dedicated application engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Tapes Market |
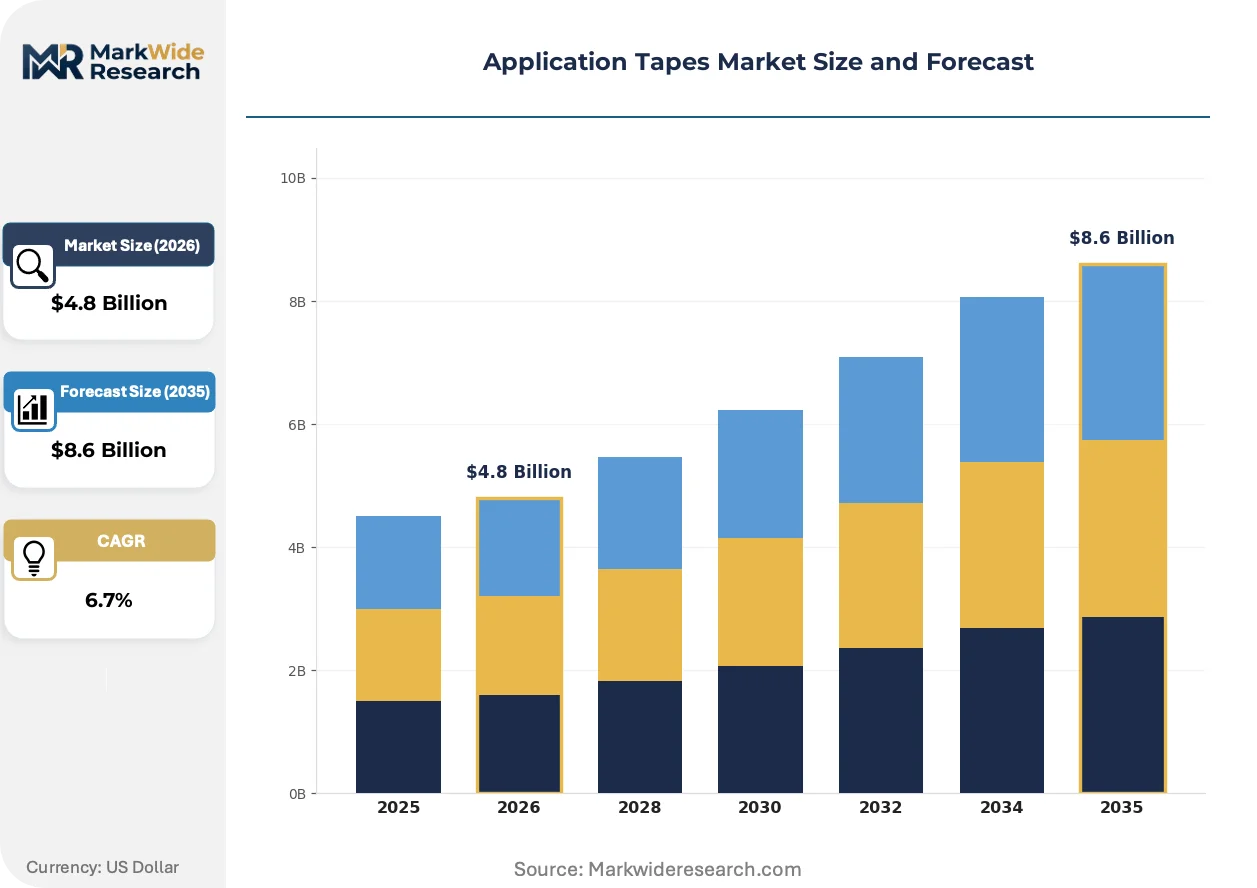
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tapes, Transfer Tapes, Specialty Tapes, Foam Tapes End User: Automotive, Electronics, Construction, Packaging Technology: Water-Based Adhesive, Solvent-Based Adhesive, Hot Melt Adhesive, Pressure-Sensitive Adhesive Application: Surface Protection, Labeling, Assembly, Bonding |
| Companies Covered | 3M Company, Avery Dennison Corporation, Tesa SE, Nitto Denko Corporation, Scapa Group, Intertape Polymer Group, Berry Global, Lintec Corporation, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Tapes Market Emerging Trajectories
Adhesive technology is converging with environmental compliance mandates and digital manufacturing workflows, reshaping how tape specifications are developed, tested, and commercialized across end-use verticals.
Hot-melt pressure-sensitive adhesive technology is hybridizing with UV-crosslinking chemistry to deliver solvent-free performance comparable to traditional acrylics. Automotive interior trim suppliers in Germany and Japan are adopting these systems for dashboard assembly to meet VOC emission protocols. This hybridization is compressing the performance gap between environmental compliance and bonding strength, enabling water-based platforms to penetrate applications previously reserved for solvent constructions.
China's MEE enforcement of dual carbon goals is mandating coating line upgrades to thermal oxidizer and carbon capture systems by 2025. Domestic tape converters in Jiangsu and Guangdong provinces are consolidating capacity to fund compliance investments, reducing supplier fragmentation. Foreign multinationals with established clean production assets are capturing expanded share of export-oriented electronics contract manufacturing demand as local competitors face retrofit capital constraints.
Specification-driven procurement is consolidating tape vendor lists at major aerospace and medical device manufacturers, replacing multi-source strategies with single or dual qualified suppliers per adhesive platform. Industrial distributors are responding by unbundling technical support services from product margins, creating fee-based application engineering offerings. This shift is most visible in North American medical device clusters around Minneapolis and Boston, where FDA 510(k) submission requirements favor incumbent tape suppliers with established regulatory file histories.
Application Tapes Market Segmentation
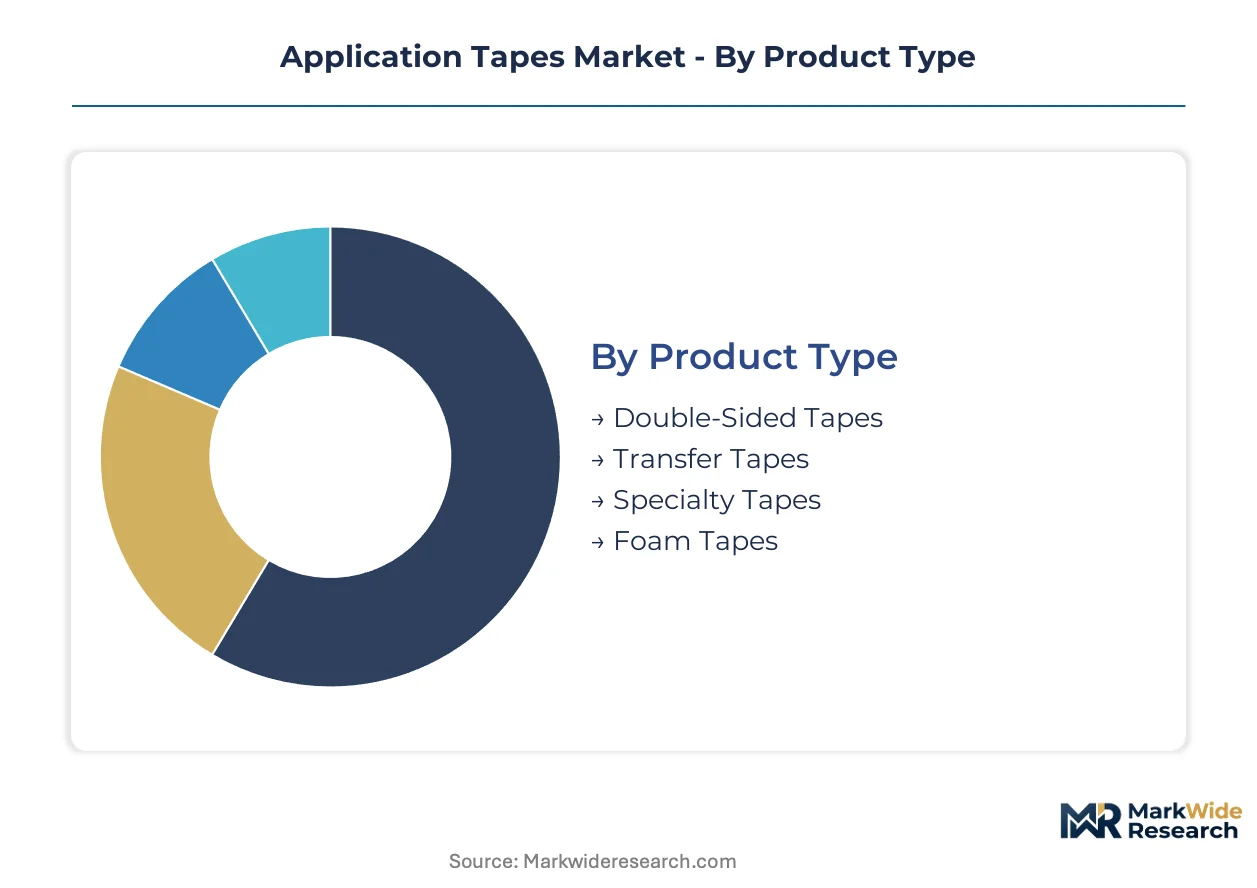
Application tapes span diverse bonding specifications across automotive lightweighting, electronics miniaturization, and industrial assembly. Segmentation reveals how adhesive chemistry, product construction, and end-use requirements drive purchasing decisions and supplier qualification pathways.
Product Type:
Construction thickness and adhesive carrier configuration separate performance tiers across load-bearing and precision bonding applications.
- Double-Sided Tapes:Carrier-supported adhesive constructions with facestock on both sides enable structural bonding without visible fasteners. Automotive OEMs in Germany and Japan specify these for dashboard and interior trim assembly to meet VOC emission protocols under REACH enforcement.
- Transfer Tapes:Adhesive films without carrier substrates deliver near-invisible bond lines critical for display lamination and semiconductor die-attach. Chinese EV battery manufacturers are scaling thermal interface tape consumption for module-to-pack bonding, driving acrylic formulation demand.
- Specialty Tapes:Custom-engineered constructions for aerospace outgassing specifications and medical device biocompatibility requirements.
- Foam Tapes:Compressible adhesive carriers for gap-filling and vibration damping in appliance and HVAC assembly.
Double-sided tapes command the established base. The steepest expansion runs through transfer tapes.
End User:
Customer verticals impose distinct certification, volume, and technical service requirements on tape suppliers.
- Automotive:Structural bonding substitution for mechanical fasteners dominates procurement, with 18-36 month OEM qualification timelines freezing out smaller competitors lacking dedicated application engineering teams.
- Electronics:Display assembly and semiconductor packaging drive demand for ultra-thin, clean-removal tapes. China's MEE enforcement of dual carbon goals is mandating coating line upgrades, reshaping supplier fragmentation among domestic converters.
- Construction:Weather sealing and temporary surface protection applications favor cost-optimized acrylic and rubber formulations.
- Packaging:E-commerce fulfillment acceleration sustains carton sealing and label adhesion consumption across industrial distribution networks.
Automotive represents the highest-value qualification pathway. Electronics displays the steepest volume climb.
Technology:
Adhesive chemistry platforms differentiate on environmental compliance, bond strength, and process compatibility.
- Water-Based Adhesive:Acrylic emulsion systems dominate new capacity investments as EPA and REACH regulations constrain solvent-based expansion. European ECHA compliance deadlines are accelerating water-based capacity investments among regional converters.
- Solvent-Based Adhesive:High-performance aerospace and medical segments retain these systems where outgassing specifications remain stringent. Production concentrates among North American and European coaters with EPA-compliant thermal oxidizer infrastructure.
- Hot Melt Adhesive:UV-crosslinking hybrids deliver solvent-free performance for automotive interior applications in Germany and Japan.
- Pressure-Sensitive Adhesive:The foundational mechanism across all carrier configurations, with formulation expertise gaps extending product development cycles for regional converters.
Water-based platforms capture the compliance-driven shift. Solvent-based retains premium positioning in regulated medical and aerospace niches.
Application:
Functional use case determines specification priority—temporary protection versus permanent structural integrity.
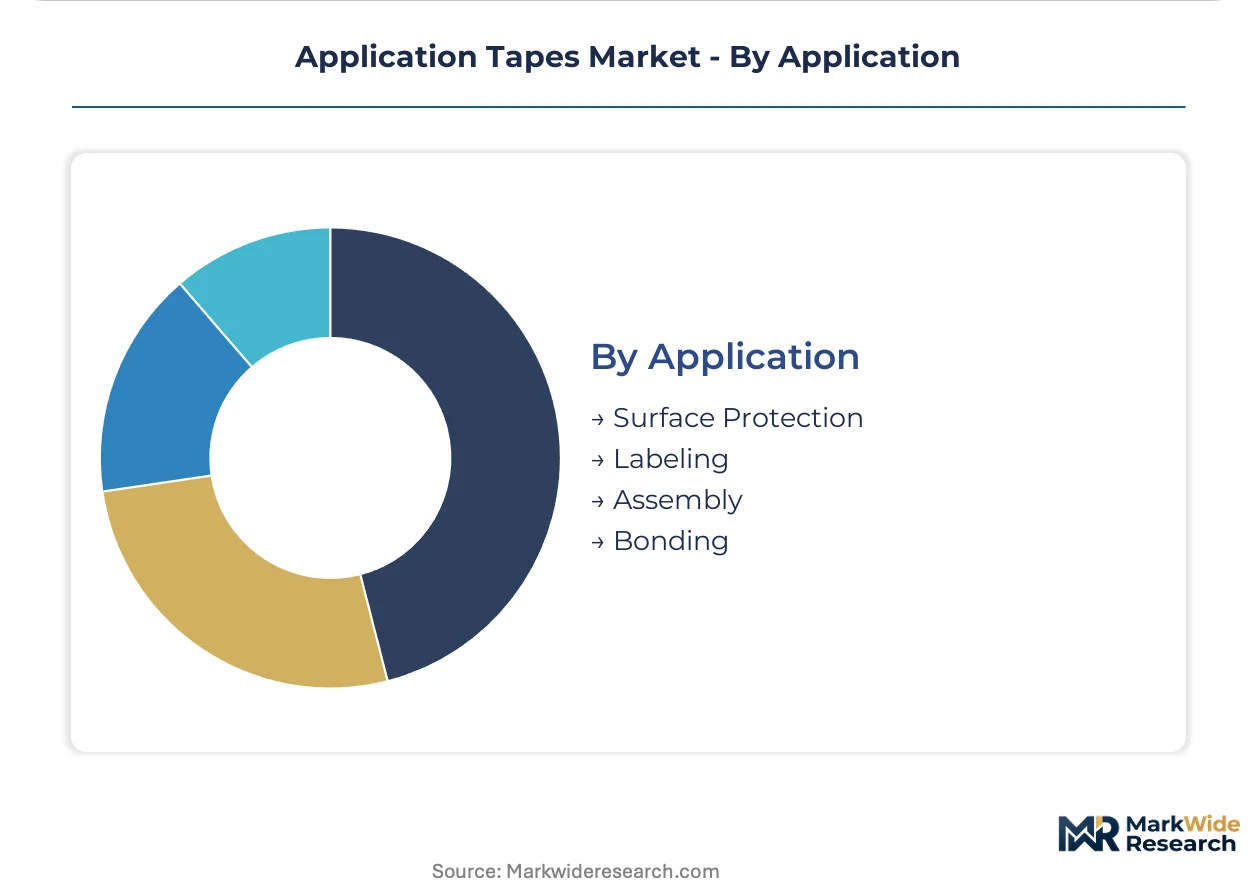
- Surface Protection:Temporary films for painted automotive panels and polished metal during assembly and transit. Biodegradable release liner convergence is opening sustainable positioning for premium consumer electronics packaging.
- Labeling:Facestock adhesion for variable information and branding applications across industrial distribution.
- Assembly:Positioning and alignment aids for component fit-up in appliance and furniture manufacturing.
- Bonding:Permanent load-bearing attachment displacing welds and mechanical fasteners in automotive structural applications.
Bonding commands the structural substitution momentum. Surface protection gains share fastest through sustainable liner innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and electronics contract manufacturers concentrate purchasing power across four demand poles. Each geography imposes distinct qualification protocols and environmental compliance calendars that reshape supplier access.
United States
EV battery assembly plants in Michigan and Tennessee are scaling thermal interface tape procurement for module bonding. EPA VOC emission constraints on solvent-based coating operations favor domestic converters with thermal oxidizer infrastructure. Minneapolis and Boston medical device clusters drive FDA 510(k) submission requirements that freeze out unqualified tape suppliers.
Germany
Automotive interior trim suppliers specify low-VOC bonding tapes for dashboard assembly under REACH enforcement. ECHA registration deadlines accelerate water-based adhesive capacity investments among regional coaters. Stuttgart and Wolfsburg industrial corridors anchor OEM direct qualification programs that competitors struggle to replicate.
China
EV manufacturers in Jiangsu and Guangdong provinces consume double-sided acrylic tapes for battery pack module-to-pack bonding. MEE dual carbon enforcement mandates coating line upgrades to thermal oxidizer systems by 2025. Shenzhen and Suzhou electronics contract manufacturers are scaling precision tape consumption as domestic converters face retrofit capital constraints.
Japan
Semiconductor packaging facilities in Kyushu and Nagoya drive demand for ultra-thin transfer tapes with near-invisible bond lines. METI industrial standards guide adhesive formulation specifications for display lamination applications. Osaka-based automotive suppliers adopt UV-crosslinking hot-melt hybrids to meet interior VOC protocols.
India
Smartphone assembly incentives under the PLI scheme attract tape distributors to establish converting partnerships near Noida and Sri City. BIS certification requirements for industrial adhesives extend product approval timelines for foreign suppliers. Maharashtra and Karnataka electronics manufacturing corridors concentrate demand for surface protection and labeling tapes.
Application Tapes Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base separates into consolidated multinational coaters with captive polymer capabilities and regional converters leveraging asset-light leasing models. Three archetypes dominate: integrated materials-science conglomerates, automotive-direct qualification holders, and precision electronics specialists. Competitive moves concentrate on M&A for adhesive formulation expertise and strategic partnerships for regional converting capacity.
Among integrated materials-science conglomerates, 3M Company and Avery Dennison Corporation occupy positions defined by captive polymer portfolios and distribution network control. Tesa SE exemplifies the automotive-direct qualification archetype through European OEM supply chain anchoring. Nitto Denko Corporation represents precision electronics specialization with positioning in display and semiconductor assembly segments.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Tesa SE |
| Nitto Denko Corporation |
| Scapa Group |
| Intertape Polymer Group |
| Berry Global |
| Lintec Corporation |
| Lohmann GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
Jiangsu and Guangdong provinces anchor global coating capacity for pressure-sensitive adhesive tapes, and their consolidation under MEE dual carbon enforcement is compressing spot-market availability while amplifying contract pricing power for qualified suppliers with thermal oxidizer infrastructure.
Pricing Analysis
Certification level creates the primary spread across aerospace, medical, and industrial grades, with FDA 510(k) submission requirements and REACH registration status commanding 40-60% premia over standard industrial formulations. Three-tier pricing structure across premium, standard, and economy levels reflects qualification depth rather than raw material differentials alone. Price erosion runs through commodity-grade carton sealing and surface protection tapes as Chinese domestic converters add water-based capacity. Electronics contract manufacturers exhibit highest price sensitivity due to high-volume, specification-tight procurement, while medical device OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Electronics manufacturing services concentration in Shenzhen, Suzhou, and Penang shapes downstream demand aggregation for precision transfer tapes. Acrylic monomer supply draws from petrochemical complexes in South Korea, Japan, and the US Gulf Coast, with synthetic rubber feedstock anchored in Southeast Asian processing hubs. Single-source vulnerability concentrates in aerospace-qualified coaters with EPA-compliant thermal oxidizer systems. Distribution runs through industrial distributors unbundling technical support into fee-based application engineering services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application tape procurement is shifting toward specification-driven vendor consolidation, creating service-attach opportunities where application engineering and regulatory filing support generate recurring revenue streams expanding faster than base product margins.
For Market Incumbents: Harden qualification moats by deepening captive polymer formulation capabilities and expanding thermal oxidizer capacity in Jiangsu and Tennessee corridors. Lock in 18-36 month OEM direct qualification timelines before regional converters complete MEE-mandated coating line upgrades. Prioritize FDA 510(k) submission investments in Minneapolis and Boston medical device clusters. For New Entrants and Emerging Players: Pursue asset-light leasing models for coating equipment to bypass capital-heavy solvent recovery infrastructure requirements. Target India's PLI scheme corridors near Noida and Sri City for smartphone assembly tape partnerships. Lead with biodegradable release liner offerings to capture sustainable packaging demand from premium consumer electronics brands. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adhesive formulation specialists with clean-coating capabilities and established regulatory file histories. Five-to-ten year viability hinges on water-based and UV-crosslinking hybrid platform transitions. Monitor MEE enforcement compliance deadlines as inflection indicator for Chinese domestic converter consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Captive polymer supply secures margin stability against petrochemical feedstock volatility from crude oil indices. |
| Water-Based Coating Capacity Expansion | EPA and REACH compliance investments open automotive interior trim specifications previously reserved for solvent systems. |
| Application Engineering Service Unbundling | Fee-based technical support creates recurring revenue streams independent of product margin compression. |
| Biodegradable Release Liner Development | Compostable adhesive chemistries capture sustainable positioning in premium consumer electronics packaging. |
| Regional Converting Partnership in India | PLI scheme proximity reduces logistics costs for smartphone and component assembly tape demand. |
Methodological Framework
A standing panel of coating line operators, automotive Tier 1 procurement managers, electronics contract manufacturing engineers, and industrial distribution channel heads provided ongoing calibration against operational realities. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, customs and trade data, EPA enforcement records, and ECHA registration databases. Bottom-up capacity assessments across Jiangsu, Guangdong, Tennessee, and Stuttgart industrial corridors triangulated against top-down end-use demand modeling.
Scenario bracketing anchored volume and value outputs across conservative, baseline, and accelerated technology adoption pathways over the projection horizon. Segmentation dimensions modeled include adhesive chemistry platform, product construction type, end-use vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EV battery pack assembly intensity, semiconductor packaging node shrinkage rates, and REACH compliance deadline phasing.
Sensitivities concentrate around acrylic monomer price volatility, MEE enforcement timing for coating line upgrades, and automotive OEM qualification timeline extensions. Forecasts reflect documented assumptions on substitution rates for mechanical fasteners and water-based adhesive performance convergence. Quarterly review of thermal oxidizer installation permits, ECHA registration completion rates, and EV battery pack production schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Paper Gummed Tape Market
Tapes
Tape and Label Adhesives Market
Tapes
Global Printed Tape Market
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Acoustic Tape Market
Tapes
Dicing Tapes Market
Tapes
Tape Dispenser Market
Tapes
Invisible Tapes Market
Tapes
Nylon Cable Ties Market
Tapes
Electrical Shielding Tape Market
Tapes
Strapping Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Double Coated Film Tapes Market
Tapes
Carbon Tapes Market