
 ESD Totes Market | 2026-2036
ESD Totes Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Totes Market Foresight
Southeast Asia is reshaping ESD tote supply chains as Vietnam and Malaysia add injection-molding capacity for conductive plastics. Conductive Containers Inc. leverages decades of specialization in static-dissipative polymer formulations to serve aerospace cleanrooms. Schaefer Systems International anchors European demand through its modular container systems integrated into automated storage facilities. 3M Company competes across the value chain with proprietary conductive coating technologies applied to standard tote geometries.
ESD totes are rigid, reusable containers engineered with surface resistivity between 10^3 and 10^9 ohms per square, typically injection-molded from carbon-filled polypropylene or nylon composites to prevent electrostatic discharge damage to sensitive electronic components. Stackable totes dominate volume shipments due to standardized footprints compatible with automated guided vehicle systems, while custom solutions capture premium margin pools from semiconductor OEMs requiring particle-controlled environments. Polypropylene leads material selection for its chemical resistance and recyclability, though conductive plastics incorporating carbon nanotubes are gaining share in next-generation fabs demanding lower outgassing profiles.
FDA oversight of medical device manufacturing and EPA hazardous substance handling rules indirectly shape ESD containment specifications for electronics suppliers serving regulated end markets. OSHA workplace safety standards mandate grounded handling protocols in facilities assembling flammable or explosive components, directly driving tote replacement cycles. IEC 61340-5-1 certification requirements for electrostatic protected areas create compliance-based demand that resists pure price competition. Stakeholders must monitor how IEC revisions address emerging conductive polymer formulations and whether regional accreditation bodies fragment certification acceptance across major manufacturing hubs.
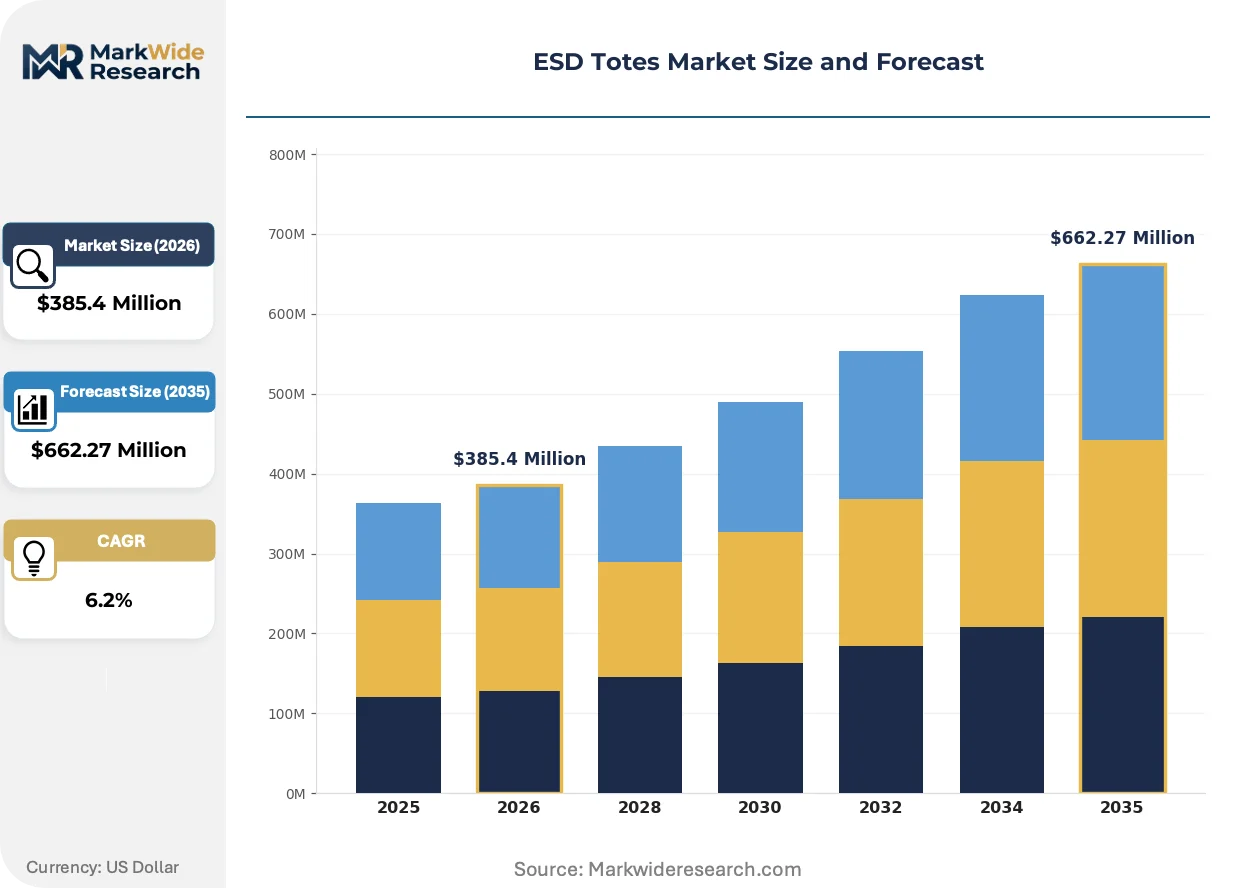
Market Dynamics
Semiconductor fabrication expansion in Taiwan and South Korea is compressing ESD tote replacement cycles as cleanroom density requirements intensify, while carbon nanotube conductive formulations are displacing legacy carbon-black compounds in next-generation fabs demanding lower outgassing thresholds.
Growth Catalysts
- IEC 61340-5-1 Certification Mandates:Electrostatic protected area standards in electronics assembly facilities create compliance-driven replacement demand that resists pure price competition across contract manufacturing clusters.
- EPA and OSHA Workplace Safety Directives:Grounded handling protocols for flammable component assembly in United States facilities mandate electrostatic discharge containment infrastructure upgrades.
- Guangdong Province Electronics Manufacturing Concentration:Contract manufacturing clusters in this Chinese province generate concentrated demand for specialized conductive handling equipment serving consumer electronics supply chains.
Market Restraints
- Conductive Polymer Input Cost Volatility:Carbon nanotube and specialized carbon-black prices fluctuate with petroleum feedstock markets and semiconductor-grade purity requirements, compressing compounder margins.
- Injection-Molding Capacity Concentration:Southeast Asian conductive plastics production centers in Vietnam and Malaysia create geographic supply risk for North American and European tote distributors.
- Technical Performance Ceiling:Surface resistivity maintenance across temperature and humidity extremes limits reuse cycles in outdoor electronics logistics applications.
Strategic Opportunities
- Medical Device Manufacturing Regulatory Tailwind:FDA oversight of electronics suppliers serving regulated end markets creates premium-grade ESD containment specifications with higher margin profiles.
- Aerospace Cleanroom Applications:Static-dissipative polymer formulations meeting particle-controlled environment standards open specialized demand pools beyond mainstream electronics.
- Automated Storage Integration:Modular container systems compatible with automated guided vehicle systems enable value-added positioning in warehouse automation retrofits.
Industry Challenges
- Certification Timeline Compression:IEC revision cycles for emerging conductive polymer formulations create product qualification delays that mismatch customer procurement schedules.
- Legacy Equipment Integration Friction:Standardized tote footprints must interface with existing automated handling infrastructure without triggering electrostatic discharge events during retrofit transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Totes Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Totes, Storage Bins, Dielectric Containers, Custom Solutions Material: Polypropylene, Conductive Plastics, Nylon, Metal End User: Electronics Manufacturers, Automotive Industry, Aerospace Providers, Telecommunications Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Conductive Containers Inc., Elkay Plastics Co., Inc., LewisBins+, Flexcon Container, Molded Fiber Glass Tray Company, GWP Group, Schaefer Systems International, 3M Company, ESD Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Totes Market Shifts & Advancements
Material science breakthroughs and regulatory recalibration are restructuring competitive advantage in ESD containment, with conductivity engineering and supply chain traceability emerging as distinct battlegrounds.
Carbon nanotube-infused polypropylene composites are collapsing the performance gap between standard conductive plastics and semiconductor-grade materials. Leading memory and logic chip fabricators in Taiwan and South Korea are accelerating qualification of these formulations for sub-7nm process node cleanrooms. The technology is collapsing traditional tiering between premium and standard product lines as resistivity specifications converge at lower price points.
REACH substance restrictions in Europe are tightening scrutiny of carbon-black sourcing and polymer additive leaching in conductive compounds. Industrial consequence includes mandatory supply chain documentation for electronics exporters serving EU medical device and automotive markets. Medical device contract manufacturers in Ireland and Germany are responding by demanding batch-level material traceability certificates from tote suppliers.
Buyer consolidation among tier-one electronics manufacturing services providers is compressing supplier qualification timelines and unbundling after-sales service contracts. Direct procurement relationships with compounders are displacing distributor intermediaries for high-volume cleanroom operations. This pattern is most visible in Guangdong Province and Vietnam, where Foxconn and Luxshare Precision operations are consolidating ESD containment spend under corporate-level agreements.
ESD Totes Market Segmentation
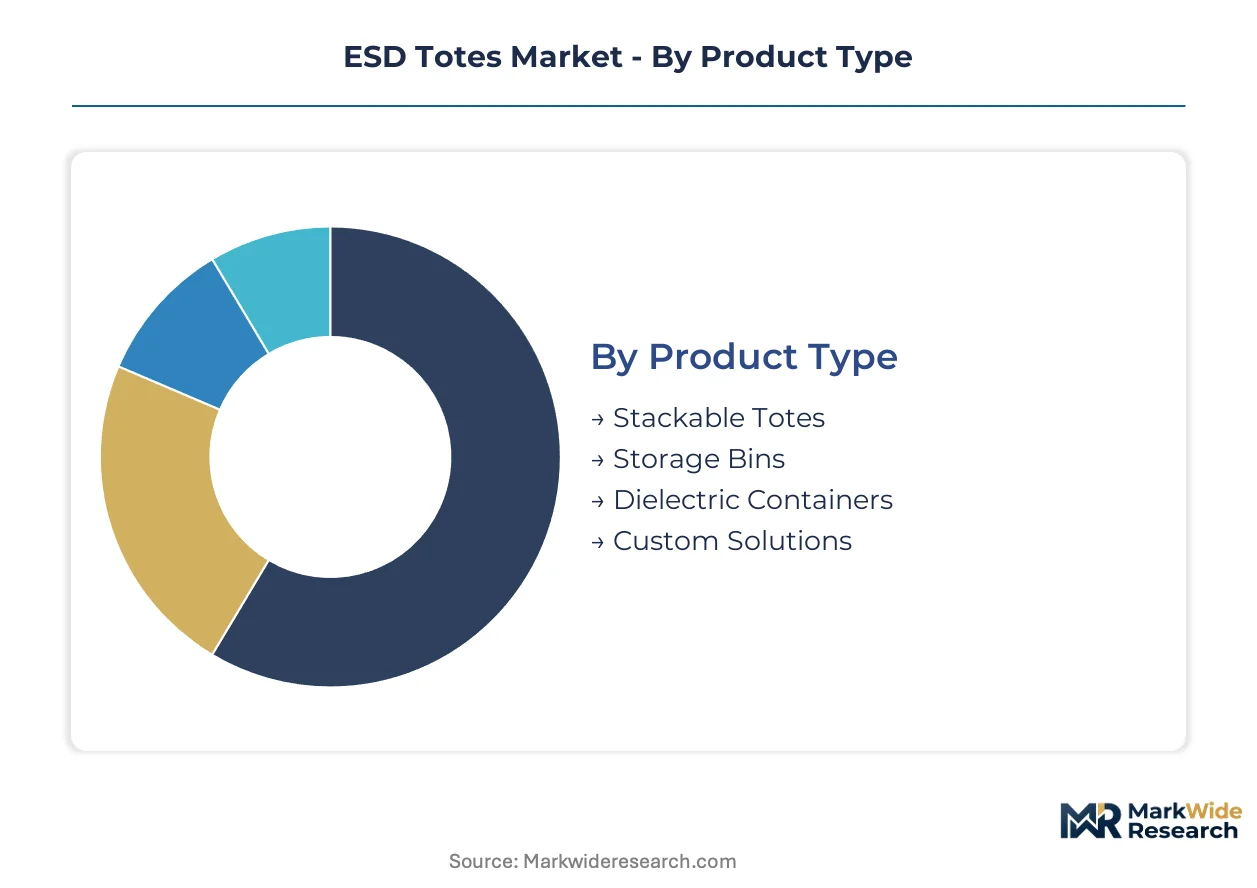
ESD tote segmentation reveals divergent replacement economics across product architectures and material formulations. Cycle times compress in semiconductor-grade applications while industrial logistics extend asset lifespans through standardized footprints.
Product Type:
Stackable totes turn over fastest in automated warehouse retrofits, whereas custom solutions cycle slowly through multi-year qualification protocols.
- Stackable Totes:Injection-molded containers with standardized footprints interface directly with automated guided vehicle systems in electronics distribution centers. Guangdong Province contract manufacturers drive volume demand for conductive polypropylene variants compatible with existing conveyor infrastructure.
- Custom Solutions:Engineered containers meeting particle-controlled environment specifications for sub-7nm semiconductor fabrication. Taiwan and South Korea cleanroom expansions compress procurement timelines for these premium-grade configurations.
- Storage Bins:Open-top conductive containers serve component kitting operations in automotive electronics assembly.
- Dielectric Containers:Insulative barriers isolate high-voltage assemblies in telecommunications infrastructure manufacturing.
Stackable totes anchor the volume base while custom solutions gain share at the steepest rate.
Material:
Cost tiers separate commodity conductive compounds from semiconductor-grade formulations with purity certifications.
- Conductive Plastics:Carbon nanotube-infused polymers achieve surface resistivity below 10^6 ohms per square for next-generation cleanroom applications. Memory chip fabricators in Taiwan accelerate qualification of these low-outgassing formulations.
- Polypropylene:Carbon-filled homopolymer dominates injection-molding throughput for standard electronics logistics. Vietnam and Malaysia compounders supply this grade to ASEAN contract manufacturing clusters.
- Nylon:Amide-based composites resist chemical exposure in aerospace solvent cleaning operations.
- Metal:Grounded stainless steel enclosures serve explosive component handling under OSHA-mandated protocols.
Polypropylene captures the volume base while conductive plastics climb the fastest on semiconductor demand.
End User:
Application maturity determines whether procurement follows compliance mandates or cost optimization logic.
- Electronics Manufacturers:Contract assembly operations in Guangdong Province and Vietnam generate concentrated demand for IEC 61340-5-1 certified handling systems.
- Aerospace Providers:Cleanroom specifications from FAA-registered facilities require particle-controlled static-dissipative formulations with batch traceability documentation.
- Automotive Industry:EV battery assembly lines drive grounded container requirements for flammable electrolyte handling.
- Telecommunications:5G infrastructure deployment sustains dielectric isolation needs for high-frequency component protection.
Electronics manufacturers anchor the volume base while aerospace providers expand most quickly on regulatory tailwinds.
Distribution Channel:
Customer scale and technical support requirements fragment procurement pathways across the value chain.
- Direct Sales:Foxconn and Luxshare Precision consolidate ESD containment spend under corporate-level agreements with compounders, bypassing distributor intermediaries.
- Distributors:Regional inventory positioning serves mid-tier electronics manufacturers requiring rapid replacement of standardized tote configurations.
- Online Retail:Small-batch procurement for prototype assembly operations favors catalog-based conductive container sourcing.
- Resellers:Value-added integrators bundle ESD totes with complete workstation grounding systems for facility retrofit projects.
Direct sales anchor the volume base while distributor relationships gain share fastest among mid-market manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung Port container throughput infrastructure underwrites Taiwan's central role in semiconductor-grade ESD containment logistics. South Korea's Gwangyang Bay Free Economic Zone anchors conductive plastics import flows for memory fabrication clusters. Shenzhen's Yantian Port serves as the primary distribution node for Guangdong electronics contract manufacturing ESD equipment procurement.
Taiwan
TSMC and United Microelectronics Corporation fabs in Hsinchu Science Park drive concentrated demand for carbon nanotube-infused tote formulations. The National Science and Technology Council enforces cleanroom particle standards that compress replacement cycles. Tainan Science Park expansion for sub-3nm process nodes accelerates qualification timelines for low-outgassing conductive containers.
South Korea
Samsung Electronics and SK Hynix Pyeongtaek memory complexes generate premium-grade ESD containment procurement at scale. The Ministry of Trade, Industry and Energy funds domestic conductive polymer compounder capacity under the K-Semiconductor Belt initiative. Busan-Ulsan logistics corridors concentrate injection-molded tote distribution for Gyeonggi-do electronics assembly operations.
United States
Intel Arizona and Texas Instruments Dallas fabs sustain demand for IEC 61340-5-1 certified handling systems. OSHA workplace safety directives mandate grounded container protocols for explosive component assembly. Phoenix-Tucson semiconductor corridor expansion drives regional distributor inventory positioning for conductive polypropylene variants.
China
Foxconn and Luxshare Precision operations in Shenzhen-Dongguan generate volume demand for stackable tote configurations. MIIT industrial standards for electrostatic protected areas create compliance-driven replacement schedules. Suzhou Industrial Park cleanroom density requirements accelerate carbon-filled nylon composite procurement for medical device electronics.
Germany
Infineon Technologies Dresden and Bosch Reutlingen facilities anchor European demand for particle-controlled static-dissipative formulations. REACH substance restrictions tighten carbon-black sourcing documentation requirements for medical device exporters. Bavarian automotive electronics clusters in Ingolstadt and Munich drive grounded container specifications for EV battery assembly lines.
ESD Totes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in conductive polymer formulation and precision injection molding. The vendor base organizes around three functional layers: compounders controlling carbon nanotube dispersion IP, molders with cleanroom-certified production lines, and systems integrators bundling totes with automated handling infrastructure. Consolidation pressures concentrate among mid-scale molders lacking direct compounder relationships. Dominant competitive moves include backward integration into conductive resin production and strategic partnerships with automated guided vehicle OEMs for footprint standardization.
Specialists in static-dissipative polymer formulations occupy positions exemplified by Conductive Containers Inc., which represents the dedicated ESD containment archetype with decades of focused market presence. Schaefer Systems International anchors the European systems integration tier through modular container architectures. 3M Company sits within the diversified materials conglomerate archetype, leveraging proprietary conductive coating technologies across standard tote geometries to compete across multiple value chain positions.
| Leading Market Players |
|---|
| Conductive Containers Inc. |
| Elkay Plastics Co., Inc. |
| LewisBins+ |
| Flexcon Container |
| Molded Fiber Glass Tray Company |
| GWP Group |
| Schaefer Systems International |
| 3M Company |
| ESD Systems |
| Others |
Supply & Pricing Matrix
Kaohsiung-to-Busan freight corridors transmit carbon nanotube price volatility directly into ESD tote landed costs, compressing compounder margins while amplifying volume-discount leverage for Foxconn-scale buyers against regional distributors serving mid-tier electronics manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade carbon nanotube formulations from carbon-filled polypropylene logistics variants from uncertified commodity containers. Price differentiation centers on IEC 61340-5-1 certification grade and cleanroom particle documentation depth. Cost compression in the standard tier is intensifying because Vietnamese compounders are adding conductive plastics capacity. Contract manufacturers in Guangdong Province exhibit highest price sensitivity; Taiwan memory fabricators show least sensitivity due to sub-7nm qualification requirements.
Supply Chain Analysis
US export-control restrictions on semiconductor-grade carbon nanotube production equipment limit technology transfer to Malaysian and Vietnamese compounders, constraining supply diversification. Manufacturing concentrates in Taiwan, South Korea, and China. Raw material flows draw from petroleum feedstock markets, semiconductor-grade carbon-black suppliers, and carbon nanotube dispersion specialists. Single-source vulnerability runs through TSMC-qualified compounders holding sub-10nm cleanroom certification. Distribution runs through direct procurement agreements for tier-one EMS providers and regional distributor networks for mid-market manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as buyer consolidation among tier-one electronics manufacturing services providers unbundles after-sales service contracts, creating specialist niches for compounders with batch-level traceability capabilities.
For Market Incumbents: Insulate qualification relationships with TSMC and Samsung Electronics by accelerating carbon nanotube formulation R&D ahead of IEC revision cycles. Secure backward integration into conductive resin production to offset petroleum feedstock volatility threatening compounder margins. Defend against Foxconn direct-procurement disintermediation through embedded inventory management services. For New Entrants and Emerging Players: German medical device contract manufacturers represent underpenetrated demand for REACH-compliant batch traceability documentation. Aerospace cleanroom applications in FAA-registered facilities offer second white-space target with lower qualification barriers than semiconductor-grade segments. Pursue value-added integrator partnerships bundling ESD totes with complete workstation grounding systems. For Investors and Strategic Acquirers: Cleanroom-certified molders lacking direct compounder relationships present acquisition targets as consolidation pressure concentrates among mid-scale players. Long-term viability rests on carbon nanotube dispersion IP control and automated guided vehicle footprint standardization partnerships. Watch for IEC revision announcements addressing emerging conductive polymer formulations as inflection signal requiring portfolio recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Resin Production | Captures margin from petroleum feedstock volatility affecting carbon-black compounders. |
| Carbon Nanotube Formulation R&D Acceleration | Qualifies sub-7nm cleanroom specifications for TSMC Tainan Science Park expansion. |
| Batch-Level Traceability Certification Investment | Meets REACH documentation requirements for German medical device exporters. |
| Automated Guided Vehicle Footprint Standardization Partnership | Locks in modular container compatibility with Schaefer Systems International retrofits. |
| Embedded Inventory Management Service Launch | Defends distributor positioning against Foxconn direct-procurement consolidation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cleanroom operations managers, ESD compliance officers at semiconductor fabs, conductive polymer compounder technical directors, and electronics manufacturing services procurement leads; and secondary validation through IEC certification databases, EPA workplace safety directive filings, customs trade data for conductive plastics, and SEC disclosures from diversified materials conglomerates. Bottom-up tote shipment estimates triangulated against top-down electronics manufacturing capex projections.
Forecast inputs considered product type segmentation across stackable totes, custom solutions, storage bins, and dielectric containers; material tiers spanning conductive plastics, polypropylene, nylon, and metal; and end-user categories including electronics manufacturers, aerospace providers, automotive industry, and telecommunications. CAGRs were derived from cleanroom density requirement trajectories and carbon nanotube formulation adoption curves across the projection horizon. Semiconductor fabrication expansion timelines and OSHA mandate implementation schedules served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by carbon nanotube dispersion IP holders would shift outcomes. Material shifts in IEC 61340-5-1 revision scope or REACH substance restriction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market