
 ESD Tray Market | 2026-2036
ESD Tray Market Size, Share, and Industry Trends Forecast 2026-2036
ESD Tray Market Insights
Semiconductor packaging demand is decoupling from general electronics logistics as advanced node chips require specialized static protection. Desco Industries Inc. leverages its vertical integration across conductive material compounding and tray thermoforming to control cost structures. Conductive Containers, Inc. anchors its position through deep specialization in custom-engineered tray geometries for aerospace component handling. Elcom (UK) Ltd. competes on regional proximity to European EMS clusters, reducing lead times for just-in-time tray replenishment.
An ESD tray is a thermoformed or injection-molded container fabricated from electrically conductive or dissipative polymers, typically surface resistivity-rated between 10^3 and 10^9 ohms per square, designed to shield sensitive electronic components from electrostatic discharge damage during handling, storage, and transport. Polypropylene dominates material selection for its chemical resistance and recyclability in cleanroom environments, while conductive foam inserts capture premium margin pools in die-level semiconductor shipping. The electronics end-user segment leads volume absorption, though aerospace applications sustain higher per-unit pricing due to traceability and lot-control specifications embedded in tray design.
The EPA enforces workplace static control standards under OSHA-aligned guidelines, compelling tray specification in electronics assembly facilities, while the EU RoHS and REACH frameworks restrict hazardous substances in conductive filler additives, reshaping material formulation roadmaps. China's GB standards for electrostatic protection, administered by SAMR, create a parallel compliance layer for trays entering domestic semiconductor supply chains. Stakeholders must monitor evolving dual-carbon targets in Asia-Pacific manufacturing hubs, as recycled content mandates in conductive polymers threaten to disrupt established resin supply agreements and tray pricing structures.
Market Dynamics
Semiconductor fabs are consolidating tray specifications around wafer-level packaging formats, forcing material suppliers to recalibrate conductive polymer formulations for thinner wall sections and tighter dimensional tolerances.
Growth Catalysts
- REACH RoHS compliance mandates:European electronics manufacturers are replacing legacy carbon-black loaded trays with halogen-free conductive compounds to satisfy substance restrictions.
- Wafer-level chip-scale packaging:Advanced node semiconductor production requires trays with surface resistivity below 10^6 ohms per square for die-level handling.
- China's domestic semiconductor buildout:SAMR-certified ESD protection is becoming mandatory for trays entering state-backed foundry supply chains.
Market Restraints
- Conductive filler cost volatility:Carbon nanotube and intrinsically conductive polymer prices fluctuate with specialty chemical feedstock availability.
- Single-source resin concentration:Medical-grade conductive polypropylene relies on three major compounders in Germany and Japan.
- Technical ceiling at sub-50-micron thickness:Thermoformed trays below this gauge lose structural rigidity for automated handling systems.
Strategic Opportunities
- India's EMS corridor expansion:PLI scheme incentives for electronics manufacturing are creating first-mover advantages for localized tray production.
- Reusable closed-loop logistics:Automotive battery module suppliers are piloting RFID-tracked tray pooling systems to reduce single-use packaging waste.
- Dual carbon alignment:China's MEE recycled content mandates favor bio-based conductive polymers in tray formulations.
Industry Challenges
- Cleanroom thermoforming technician shortage:Operating Class 1000-rated production lines requires specialized certification programs that lag demand.
- Multi-standard certification timelines:Simultaneous IEC 61340, ANSI/ESD S20.20, and GB 3007 compliance extends product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESD Tray Market |
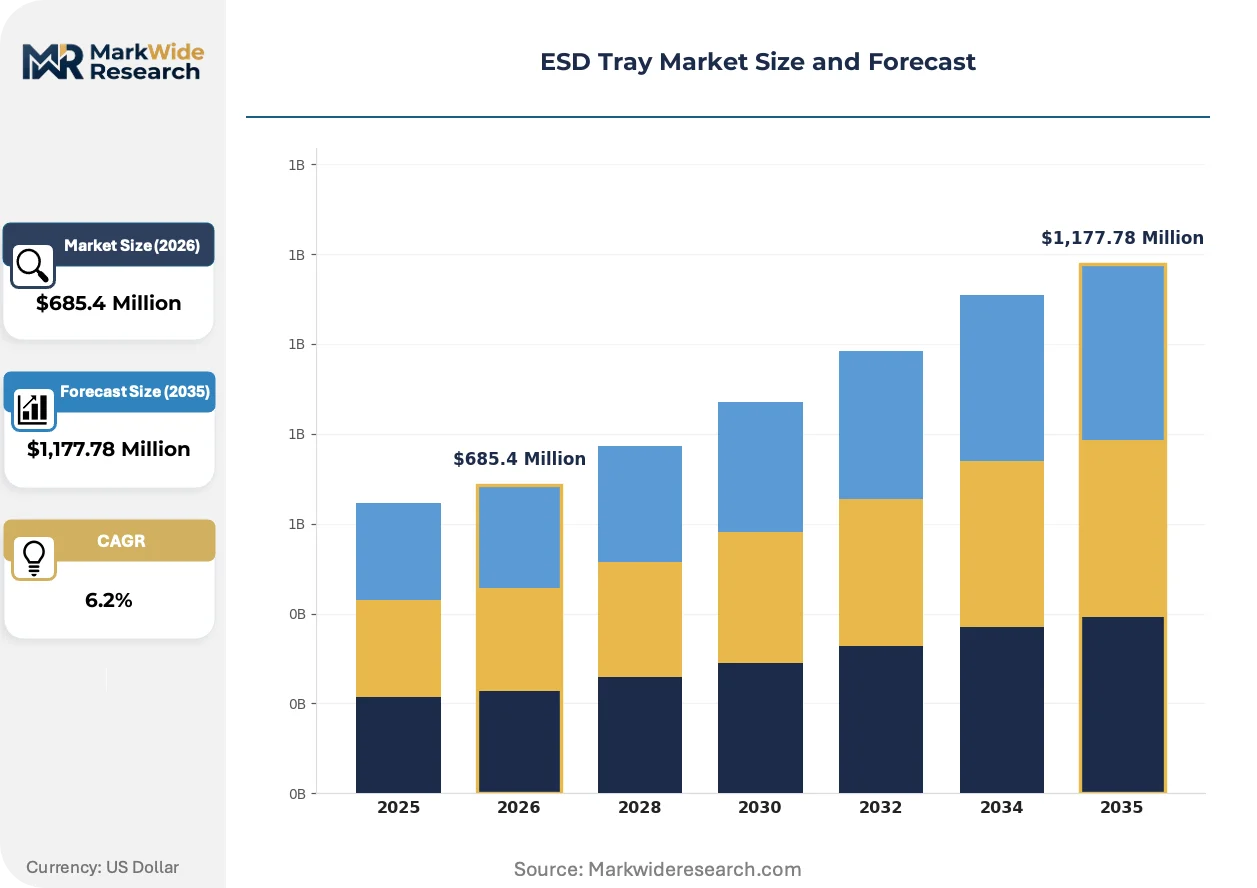
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trays, Boxes, Pallets, Inserts Material: Polypropylene, ABS, PVC, Conductive Foam End User: Electronics, Aerospace, Automotive, Telecommunications Application: Storage, Transportation, Packaging, Handling |
| Companies Covered | Desco Industries Inc., Conductive Containers, Inc., Elcom (UK) Ltd., Utz Group, ASE Group, Tek Pak, Inc., Tandem Equipment Sales, Inc., Botron Company Inc., Protektive Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESD Tray Market Trends and Innovations
Material science advances are compressing the performance gap between commodity conductive polymers and engineered compounds, while regulatory pressure on substance restrictions accelerates formulation turnover cycles.
Multi-wall carbon nanotube masterbatches are unifying electrical and mechanical performance in thin-gauge tray walls. Semiconductor packaging houses in Taiwan and South Korea are adopting these compounds for 300mm wafer shipping trays. The technology is unifying previously separate material qualification streams for static dissipation and structural durability.
REACH substance restriction updates are forcing reformulation of brominated flame retardants in conductive compounds. Compounders must resubmit technical dossiers to ECHA for authorization renewals. Medical device tray suppliers face the tightest compliance windows, with some accelerating transition timelines by eighteen months.
Consolidated vendor-managed inventory programs are replacing spot procurement for high-volume electronics manufacturers. Tier-one EMS providers in Mexico and Vietnam now require suppliers to maintain four-week buffer stocks at regional hubs. Aerospace component handlers remain the exception, insisting on lot-traceable direct shipments to maintain pedigree documentation.
ESD Tray Market Segmentation
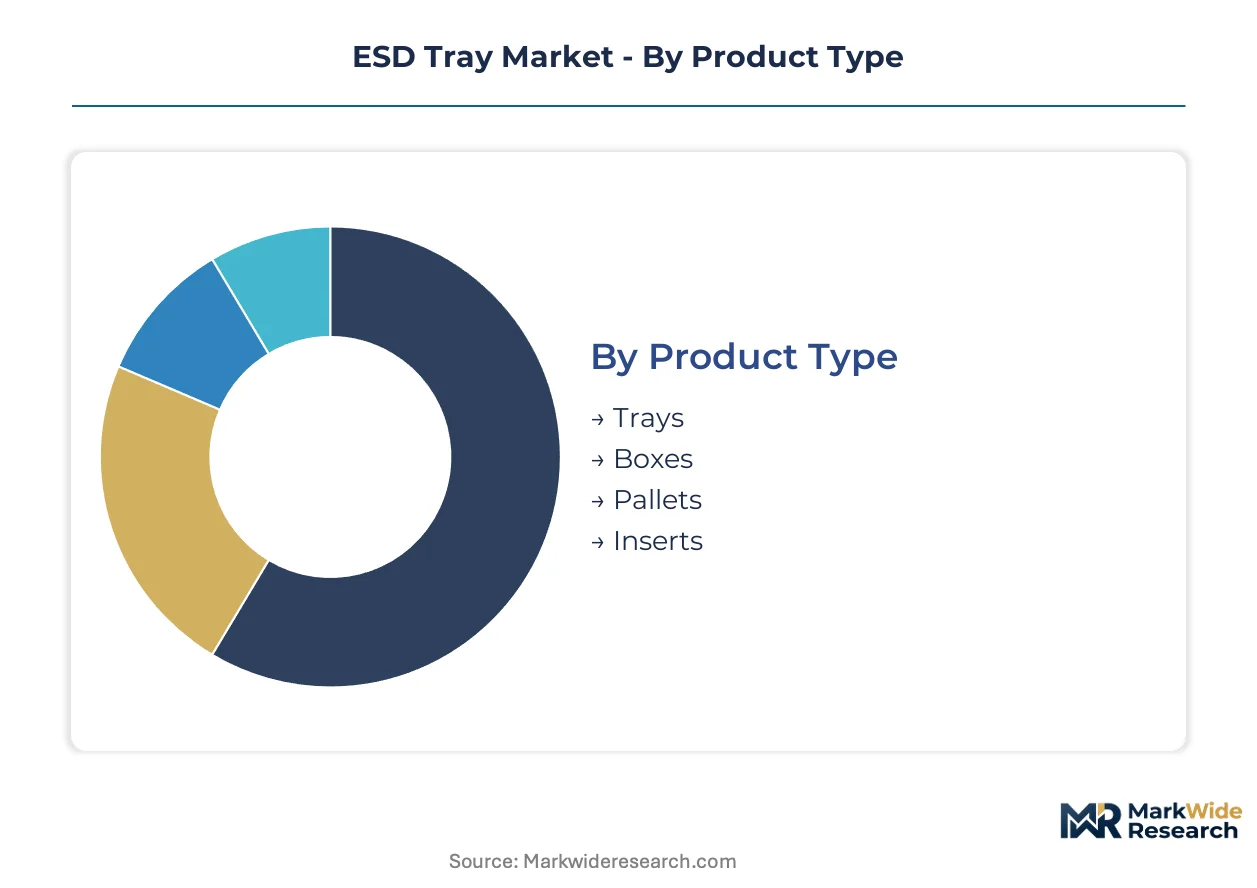
ESD tray procurement decisions hinge on material certification tiers, end-use regulatory exposure, and automation compatibility requirements. Each segmentation dimension carries distinct margin profiles and qualification burdens that reshape supplier positioning across electronics manufacturing clusters.
Product Type:
Certification requirements diverge sharply across product types, with semiconductor-grade trays demanding IEC 61340 and ANSI/ESD S20.20 dual compliance while logistics pallets face lighter ANSI/ESD STM 9.1 standards.
- Trays:Thermoformed conductive polymer containers with surface resistivity between 10^3 and 10^9 ohms per square dominate wafer-level chip-scale packaging applications in Taiwan and South Korea. Wafer shipping formats below 50-micron wall thickness require multi-wall carbon nanotube compounds to maintain structural rigidity for automated handling systems.
- Boxes:Injection-molded conductive enclosures with integrated lid systems capture premium pricing in medical device component logistics where lot traceability mandates embedded RFID tracking. Demand concentrates in German and Swiss precision manufacturing corridors where REACH substance restrictions force halogen-free conductive compound adoption.
- Pallets:Heavy-duty conductive platforms for bulk semiconductor wafer transport prioritize durability over precision resistivity specifications.
- Inserts:Conductive foam and thermoformed liners for custom component nesting address die-level semiconductor protection requirements.
Trays sit at the top of the volume ranking, with boxes climbing the fastest.
Material:
Cost tiers stratify around raw material input volatility and cleanroom processing requirements, with medical-grade compounds commanding substantial premiums over standard industrial formulations.
- Polypropylene:Chemical-resistant recyclable polymer dominates cleanroom environments in Japanese and German semiconductor fabrication facilities. The material's low outgassing properties satisfy NASA and ESA aerospace specifications, though three major compounders in Germany and Japan control medical-grade supply chains.
- ABS:Acrylonitrile butadiene styrene offers superior impact resistance for automotive battery module handling trays in Mexico and Vietnam EMS corridors. PLI scheme incentives in India are accelerating localized ABS conductive compound production for consumer electronics assembly.
- PVC:Cost-effective option for general electronics logistics with limited cleanroom exposure.
- Conductive Foam:Open-cell polyurethane and polyethylene foams with embedded carbon fillers protect die-level semiconductor shipments.
Polypropylene captures the dominant volume position, while conductive foam expands most quickly in advanced packaging applications.
End User:
Customer type determines pricing leverage and contract structure, with aerospace buyers insisting on lot-traceable direct shipments while electronics manufacturers accept vendor-managed inventory programs.
- Electronics:EMS providers and OEMs in China's Yangtze River Delta and Pearl River Delta manufacturing clusters drive baseline volume procurement. SAMR-certified ESD protection is becoming mandatory for trays entering state-backed foundry supply chains, forcing reformulation of legacy carbon-black loaded compounds.
- Aerospace:Component handlers sustain highest per-unit pricing due to traceability and lot-control specifications embedded in tray design. FAA and EASA pedigree documentation requirements favor regional suppliers in Toulouse, Hamburg, and Seattle aerospace corridors.
- Automotive:Battery module suppliers pilot RFID-tracked tray pooling systems to reduce single-use packaging waste.
- Telecommunications:5G infrastructure component handling drives demand for larger-format trays with enhanced structural loading capacity.
Electronics commands the volume base, with aerospace maintaining the steepest premium tier.
Application:
Geography shapes application prioritization, with Asian manufacturing hubs emphasizing transportation durability while European facilities prioritize storage-optimized footprint efficiency.
- Storage:Static-dissipative shelving and rack-mounted tray systems for component inventory management dominate Japanese automotive electronics facilities. JIS standards for electrostatic protection create distinct material specification requirements separate from IEC 61340 frameworks.
- Transportation:Shock-resistant tray designs with integrated cushioning capture demand in cross-border semiconductor logistics between Taiwan, South Korea, and China. GB 3007 compliance timelines extend product qualification cycles for trays entering domestic Chinese supply chains.
- Packaging:Single-use and reusable formats for finished goods protection in consumer electronics distribution.
- Handling:Ergonomic tray geometries for manual and automated assembly line feeding.
Transportation leads volume absorption, with storage gaining share fastest in precision manufacturing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting ESD tray procurement toward jurisdictions with streamlined certification pathways, as manufacturers seek to bypass the multi-standard qualification bottlenecks that extend product launch timelines in mature markets.
China
Domestic semiconductor fabrication buildout is accelerating tray demand across Yangtze River Delta and Pearl River Delta manufacturing clusters. SAMR-administered GB standards for electrostatic protection now mandate certification for trays entering state-backed foundry supply chains. Shanghai and Suzhou electronics manufacturing hubs are driving volume procurement of wafer-level packaging formats.
United States
EPA-aligned workplace static control standards under OSHA guidelines compel tray specification in electronics assembly facilities across Texas and Arizona semiconductor corridors. FDA traceability requirements for medical device component handling sustain premium pricing in Boston and Minneapolis precision manufacturing zones. Domestic fabs in Oregon and New Mexico are consolidating procurement around IEC 61340-compliant formats.
Germany
REACH substance restrictions and RoHS frameworks are forcing halogen-free conductive compound adoption across Bavarian and Baden-Württemberg automotive electronics facilities. ECHA authorization renewals for brominated flame retardants are compressing formulation transition timelines. Stuttgart and Munich industrial clusters prioritize vendor-managed inventory programs with four-week buffer stock requirements.
South Korea
Advanced node semiconductor production in Seoul Capital Area and Busan-Ulsan corridors demands trays with surface resistivity below 10^6 ohms per square for die-level handling. MFDS medical device regulations extend qualification cycles for trays serving diagnostic equipment manufacturers. Suwon and Pyeongtaek packaging houses are adopting multi-wall carbon nanotube compounds for 300mm wafer shipping formats.
India
PLI scheme incentives for electronics manufacturing are creating first-mover advantages for localized tray production in Maharashtra and Karnataka EMS corridors. BIS certification requirements for electrostatic protection are reshaping import substitution patterns. Chennai and Noida assembly hubs are piloting RFID-tracked tray pooling systems under automotive battery module supplier programs.
ESD Tray Market Competitive Landscape
Capacity expansion dominates the current landscape as material compounders and thermoformers add cleanroom-rated production lines to capture semiconductor packaging demand. The vendor base stratifies across three tiers: integrated conductive polymer compounders with captive tray fabrication, specialized thermoformers sourcing certified materials, and regional distributors assembling hybrid supply solutions. Two archetypes command disproportionate positioning: backward-integrated specialists controlling resin formulation through finished goods, and geography-anchored providers leveraging proximity to EMS clusters for just-in-time replenishment. Competitive intensity centers on M&A activity consolidating compounder-tray fabricator linkages, alongside strategic partnerships locking in multi-year resin supply agreements.
Among US-based fabricators, Desco Industries Inc. exemplifies the backward-integrated archetype through its control over conductive material compounding and tray thermoforming operations. Conductive Containers, Inc. occupies a position within the specialized thermoformer tier, while Elcom (UK) Ltd. anchors the geography-proximity model through its regional positioning relative to European EMS clusters. These three represent the dominant competitive vectors: captive supply chain control, deep specialization in custom geometries, and lead-time compression through regional hub strategies.
| Leading Market Players |
|---|
| Desco Industries Inc. |
| Conductive Containers, Inc. |
| Elcom (UK) Ltd. |
| Utz Group |
| ASE Group |
| Tek Pak, Inc. |
| Tandem Equipment Sales, Inc. |
| Botron Company Inc. |
| Protektive Pak |
| Others |
Pricing and Supply Chain Analysis
Multi-wall carbon nanotube masterbatch adoption in thin-gauge tray walls simultaneously compresses per-unit material costs and concentrates compounder bargaining power among German and Japanese suppliers. Semiconductor packaging houses in Taiwan and South Korea are driving this transition, forcing tier-two thermoformers to absorb reformulation costs or cede share to backward-integrated competitors.
Pricing Analysis
Distributor margins capture 15-25 points between compounders and EMS procurement desks, with direct-to-OEM contracts commanding 8-12 point discounts for four-week buffer stock commitments. Three-tier pricing structure across semiconductor-grade, medical-device, and general-electronics certification levels separates premium IEC 61340 dual-compliant trays from standard ANSI/ESD S20.20 formats. Cost compression in general-electronics tiers is intensifying because REACH halogen-free compound transitions are squeezing legacy carbon-black loaded tray margins. Electronics manufacturers in China's Yangtze River Delta exhibit highest price sensitivity, while aerospace handlers in Toulouse and Seattle sustain premium tolerance for lot-traceable direct shipments.
Supply Chain Analysis
Dual-sourcing mandates from tier-one EMS providers in Mexico and Vietnam are fragmenting resin procurement across German, Japanese, and emerging Indian compounders. Medical-grade conductive polypropylene supply concentrates in Germany and Japan, while ABS conductive compound production is localizing to Maharashtra and Karnataka under PLI scheme incentives. Raw material dependencies span carbon nanotube masterbatches, halogen-free flame retardant additives, and Class 1000 cleanroom thermoforming capacity. Single-source vulnerability in specialty conductive fillers threatens tray qualification timelines. Distribution runs through vendor-managed inventory programs at regional hubs, with aerospace exceptions requiring pedigree-documented direct shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ESD trays rests on carbon nanotube compound cost curves flattening and semiconductor-grade certification premiums widening against general-electronics commoditization.
For Market Incumbents: Anchor market position through captive supply of multi-wall carbon nanotube masterbatches and in-house production of sub-50-micron thermoforming capacity. Defend against emerging Indian compounders by locking four-year resin supply agreements with Taiwan and South Korea packaging houses. Prioritize IEC 61340 and ANSI/ESD S20.20 dual-certification investment to capture wafer-level chip-scale packaging demand. For New Entrants and Emerging Players: Capture first-mover positioning in India's PLI-subsidized EMS corridors by localizing ABS conductive compound production for consumer electronics assembly. Target automotive battery module tray pooling systems in Chennai and Noida, where RFID-tracked reusable logistics remain underpenetrated. Lead with SAMR GB 3007 compliance as the go-to-market wedge for state-backed Chinese foundry supply chains. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized thermoformers lacking captive compounder relationships, particularly those serving general-electronics logistics with spot procurement exposure. Long-term viability favors backward-integrated specialists controlling resin formulation through finished tray output. Watch multi-standard certification timeline compression as the inflection signal—simultaneous IEC 61340, ANSI/ESD S20.20, and GB 3007 qualification extending beyond eighteen months indicates compounder-tray fabricator consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Compounding | Captures carbon nanotube masterbatch margin pools and insulates against German-Japanese compounder concentration. |
| Multi-Standard Certification Investment | Accelerates Taiwan and South Korea semiconductor packaging qualification cycles ahead of REACH reformulation deadlines. |
| Regional Hub Capacity Expansion | Positions four-week buffer stock operations adjacent to Mexico and Vietnam EMS clusters for vendor-managed inventory capture. |
| RFID-Tracked Reusable Logistics Pilot | Aligns with automotive battery module supplier sustainability mandates in India and Germany. |
| Halogen-Free Compound Transition | Satisfies ECHA authorization renewal timelines for brominated flame retardant phase-out in European medical device trays. |
Research Methodology
Coverage spans Asia-Pacific, North America, and Europe, with primary inputs from each region's semiconductor packaging and EMS corridors. Primary interviews engaged cleanroom thermoforming technicians, conductive polymer compounder R&D directors, EMS procurement managers, aerospace component handling engineers, and SAMR certification specialists. Secondary validation drew from ECHA substance restriction updates, IEC 61340 and ANSI/ESD S20.20 standards documentation, PLI scheme incentive disclosures, and customs trade data for conductive polymer resin flows. Bottom-up tray volume estimates triangulated against top-down semiconductor wafer shipment forecasts.
Rate-of-change decomposition segmented growth across material certification tiers, end-use regulatory exposure, and automation compatibility requirements. The analytical framework modeled product type, material grade, end-user industry, and application dimensions across the projection horizon. CAGRs derived from wafer-level packaging format adoption curves, REACH RoHS compliance mandate timelines, and China's domestic semiconductor buildout trajectories. Forecast inputs incorporated carbon nanotube compound price elasticity and cleanroom thermoforming technician supply constraints.
Underlying measurement precision varies by segment; semiconductor-grade and medical-device trays carry tighter precision than general-electronics logistics due to consolidated vendor reporting. Forecasts reflect assumptions around SAMR certification enforcement intensity, ECHA authorization renewal schedules, and dual-carbon recycled content mandate implementation. Deviation in carbon nanotube feedstock availability or Class 1000 cleanroom capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market