
 Metallic Static Shielding Bags Market | 2026-2036
Metallic Static Shielding Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Static Shielding Bags Market Outlook
Specialized polymer metallization technicians is rotating toward Asia-Pacific contract manufacturers, tightening labor availability for North American and European bag converters. DuPont leverages its fluoropolymer expertise to supply high-barrier substrate films for multilayer shielding laminates. Desco Industries anchors its position through captive distribution to electronics assembly plants across Mexico and the United States. 3M competes via proprietary vapor-deposited aluminum coatings that achieve consistent surface resistivity below 10^9 ohms per square.
Metallic static shielding bags are multilayer flexible enclosures incorporating aluminum or metallized film lamination between polyester and polyethylene substrates, engineered to attenuate electrostatic fields and prevent triboelectric charge buildup on enclosed components. These bags typically achieve shielding effectiveness of 40-60 dB across surface resistivity ranges specified under ANSI/ESD S20.20 and IEC 61340-5-1 standards, serving primarily to protect integrated circuits, printed circuit assemblies, and precision sensors during transit and storage. Flat bags dominate current volume owing to standardized dimensions for consumer electronics, while ziplock configurations capture expanding share in semiconductor cleanroom operations where resealable access reduces contamination risk. Custom sized bags concentrate margin pools in aerospace component programs requiring lot-traceable packaging with embedded RFID tags and MIL-PRF-81705 qualification.
The EPA oversees volatile organic compound emissions from solvent-based adhesive lamination processes used in shielding bag production, while OSHA enforces workplace exposure limits for aluminum particulate during metallization. IEC 61340-5-1 and ANSI/ESD S20.20 establish the functional performance benchmarks that determine procurement eligibility for defense and commercial electronics contractors. Stakeholders must monitor tightening perfluorinated compound restrictions under REACH and emerging state-level extended producer responsibility laws that could reshape material recovery obligations for metallized multilayer films.
Market Dynamics
Semiconductor cleanroom protocols in Taiwan and South Korea are tightening specifications for wafer transport packaging, forcing bag converters to upgrade metallization precision and surface resistivity consistency to meet sub-10^9 ohm per square thresholds.
Growth Catalysts
- Cleanroom packaging mandates:Taiwan Semiconductor Manufacturing Company and Samsung Foundry are expanding protocols for 3nm wafer shipments, requiring ANSI/ESD S20.20-certified shielding bags with embedded lot traceability.
- EPA solvent emission rules:The United States Environmental Protection Agency is tightening volatile organic compound limits on adhesive lamination processes, accelerating water-based coating adoption among domestic converters.
- Aluminum sputtering advances:Vapor deposition equipment manufacturers in Japan have improved coating uniformity across polyester substrates, reducing pinhole defects that previously compromised shielding effectiveness in high-humidity corridors.
Market Restraints
- Aluminum supply concentration:Primary aluminum smelting concentrates in China and Russia, exposing bag laminators to tariff volatility and energy-cost pass-throughs that compress converter margins.
- Perfluorinated compound restrictions:REACH Annex XVII limitations on PFAS content in packaging films are forcing reformulation of high-barrier fluoropolymer substrates used in aerospace-qualified shielding bags.
- Polyester substrate cost volatility:Purified terephthalic acid feedstock prices fluctuate with crude oil benchmarks, creating margin instability for multilayer laminate producers serving price-sensitive consumer electronics segments.
Strategic Opportunities
- RFID-embedded aerospace packaging:Defense contractors in the United States are mandating MIL-PRF-81705 bags with integrated radio-frequency identification tags for component traceability, opening premium custom-sizing opportunities.
- India semiconductor manufacturing:Micron Technology's upcoming Gujarat assembly and test facility will require localized shielding bag supply chains, creating first-mover advantages for converters establishing domestic metallization capacity.
- Water-based adhesive incentives:The United States Inflation Reduction Act tax credits for low-emission manufacturing processes are accelerating capital deployment into solvent-free lamination lines serving electronics OEMs.
Industry Challenges
- Polymer metallization technician scarcity:Specialized vacuum coating operators are migrating to Asia-Pacific contract manufacturers, constraining North American and European converter expansion plans.
- IEC 61340-5-1 certification timelines:Third-party laboratory testing for surface resistivity and shielding effectiveness validation extends 12-18 weeks, delaying new product introductions for semiconductor cleanroom qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Static Shielding Bags Market |
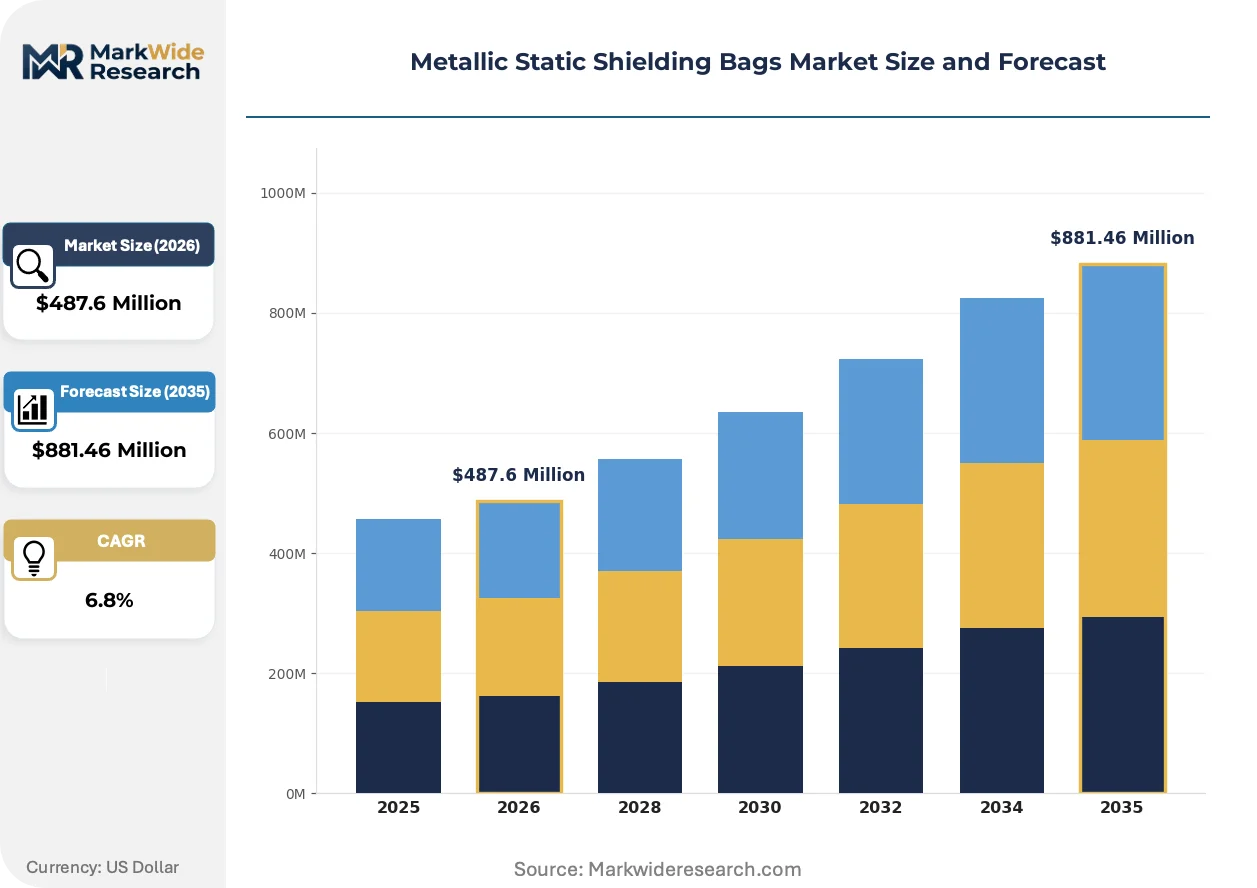
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Ziplock Bags, Custom Sized Bags Material: Aluminum, Polyester, Polyethylene, Metallized Film Application: Electronics Packaging, Pharmaceutical Storage, Semiconductors, Aerospace Components End User: Manufacturers, Retailers, Distributors, Repair Centers |
| Companies Covered | 3M, DuPont, Sealed Air Corporation, Mitsubishi Polyester Film, Desco Industries, Protective Packaging Corporation, Avery Dennison, GWP Group, Antistat Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Static Shielding Bags Market Strategic Shifts
Active barrier technologies and intelligent packaging features are redefining competitive differentiation in static shielding applications, moving beyond passive electrostatic protection toward integrated sensing and environmental monitoring capabilities.
Nano-layered aluminum oxide coatings are decomposing traditional thick-film metallization approaches in high-reliability aerospace applications. Defense contractors at Lockheed Martin and Raytheon are specifying these coatings for satellite component packaging where weight reduction drives launch economics. The technology is decomposing established supply relationships between legacy laminators and prime contractors as qualification protocols favor deposition precision over incumbent scale.
REACH perfluorinated substance restrictions are compelling substrate reformulation across European electronics supply chains. ECHA's 2023 PFAS restriction proposal threatens fluoropolymer barrier films used in moisture-sensitive device packaging, forcing DuPont and competitors to accelerate polyethylene-based alternatives. German automotive electronics suppliers are most exposed, with Bosch and Continental restructuring material specifications ahead of anticipated enforcement timelines.
Buyer consolidation among contract electronics manufacturers is compressing supplier negotiation cycles and unbundling technical service from unit pricing. Foxconn and Jabil are implementing centralized procurement platforms that benchmark shielding bag performance data across global facilities, displacing regional distributor relationships. This pattern concentrates most acutely in Mexico and Vietnam, where new assembly plant clusters lack legacy supplier entrenchment.
Metallic Static Shielding Bags Market Segmentation
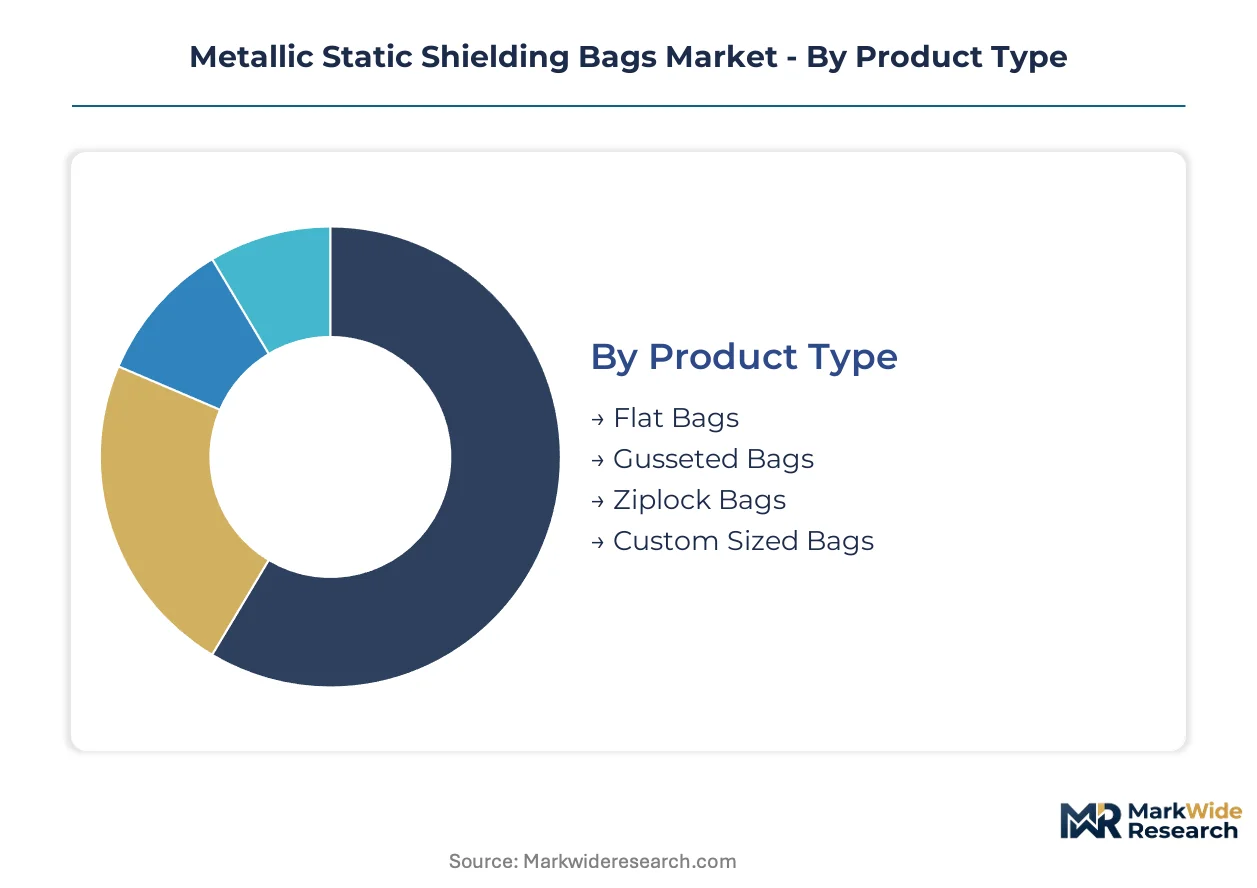
Segmentation in metallic static shielding bags reveals how technical specifications and procurement patterns split margin pools across converter tiers. Product geometry, substrate metallurgy, and end-use certification requirements each create distinct competitive battlegrounds with divergent pricing power and customer stickiness.
Product Type:
Margin pools concentrate in configurations serving semiconductor cleanrooms and aerospace qualification programs, where certification barriers protect pricing.
- Flat Bags:Standardized rectangular envelopes with aluminum-polyester-polyethylene lamination dominate consumer electronics procurement. Taiwan and South Korea fabs specify these for wafer cassette transport, with volumes scaling alongside 3nm process ramp-ups at TSMC and Samsung Foundry.
- Custom Sized Bags:Lot-traceable configurations with embedded RFID tags and MIL-PRF-81705 qualification capture premium pricing from Lockheed Martin and Raytheon satellite component programs. Defense contractors mandate these for serialized aerospace parts where launch weight economics reward nano-layered aluminum oxide coatings over traditional thick-film metallization.
- Gusseted Bags:Expandable side-seam construction accommodates bulkier PCB assemblies and cable harnesses.
- Ziplock Bags:Resealable track closures serve semiconductor cleanroom operations requiring repeated component access without contamination risk.
Flat bags hold installed capacity. Custom sized bags are rotating up the share rankings.
Material:
Substrate selection determines shielding effectiveness consistency and regulatory compliance exposure across converter operations.
- Metallized Film:Vapor-deposited aluminum on polyester substrates achieves ANSI/ESD S20.20 surface resistivity below 10^9 ohms per square. Japanese deposition equipment advances have reduced pinhole defects, improving humidity performance for Southeast Asian electronics corridors.
- Aluminum:Primary smelter supply concentrates in China and Russia, exposing laminators to tariff pass-throughs and energy cost volatility that compress margins on standard-grade consumer electronics bags.
- Polyester:Purified terephthalic acid feedstock prices track crude oil benchmarks, creating margin instability for multilayer laminate producers.
- Polyethylene:Moisture barrier layer in tri-laminate construction, with reformulation accelerating as REACH PFAS restrictions threaten fluoropolymer alternatives.
Metallized film dominates volume throughput. Aluminum is climbing the fastest on cost volatility concerns.
Application:
Certification intensity varies sharply, with aerospace and semiconductor segments demanding validation timelines that freeze out opportunistic converters.
- Semiconductors:Wafer transport protocols at TSMC and Samsung Foundry mandate sub-10^9 ohm per square surface resistivity with embedded lot traceability. IEC 61340-5-1 certification testing extends 12-18 weeks, creating qualification moats around approved suppliers.
- Aerospace Components:MIL-PRF-81705 bags with integrated RFID tags serve defense contractor traceability mandates. Weight reduction requirements favor nano-layered coatings that decompose legacy thick-film supply relationships.
- Electronics Packaging:Consumer device assembly drives standardized flat bag procurement through Foxconn and Jabil centralized platforms.
- Pharmaceutical Storage:Moisture-sensitive drug packaging applications with barrier requirements distinct from electrostatic protection.
Semiconductor applications anchor technical roadmaps. Aerospace components are gaining share fastest on premium pricing.
End User:
Procurement centralization among contract manufacturers is compressing supplier negotiation leverage and unbundling technical service from unit economics.
- Manufacturers:Foxconn and Jabil implement global benchmarking platforms that compare shielding bag performance data across Mexico and Vietnam assembly clusters, displacing regional distributor relationships where legacy supplier entrenchment is weakest.
- Distributors:Desco Industries maintains captive distribution to electronics assembly plants across Mexico and the United States, defending position through technical service integration.
- Retailers:Aftermarket component packaging with lower certification requirements and price-sensitive procurement.
- Repair Centers:Small-lot procurement of standardized flat bags for field service operations.
Manufacturers concentrate procurement volume. Distributors defend margin position through service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. East Asian semiconductor fabs prioritize sub-10^9 ohm surface resistivity with embedded traceability, while North American aerospace programs emphasize weight-optimized nano-layered coatings for launch economics.
United States
Defense contractors at Lockheed Martin and Raytheon drive MIL-PRF-81705 demand for satellite component packaging with integrated RFID tags. EPA volatile organic compound rules on adhesive lamination accelerate water-based coating adoption among domestic converters. The Inflation Reduction Act tax credits for low-emission manufacturing are reshaping capital deployment in solvent-free production lines across the Southwest and Southeast electronics corridors.
Taiwan
TSMC's 3nm wafer ramp-up mandates ANSI/ESD S20.20-certified shielding bags with lot traceability for cleanroom protocols. The island's Industrial Development Bureau enforces strict electrostatic discharge standards for semiconductor logistics. Hsinchu Science Park fabs are expanding metallization precision requirements that outpace standard consumer electronics specifications.
South Korea
Samsung Foundry and SK Hynix are tightening wafer transport packaging specifications for advanced memory and logic devices. KOSHA workplace safety rules govern aluminum particulate exposure during metallization operations. Pyeongtaek and Hwaseong semiconductor clusters are driving regional converter investment in deposition equipment upgrades.
Germany
Bosch and Continental are restructuring material specifications ahead of ECHA perfluorinated substance restrictions on fluoropolymer barrier films. REACH Annex XVII limitations are forcing polyethylene-based substrate reformulation for automotive electronics packaging. Bavarian automotive electronics suppliers face compressed qualification timelines as enforcement approaches.
Japan
Vapor deposition equipment manufacturers have improved coating uniformity across polyester substrates, reducing pinhole defects for high-humidity electronics corridors. METI industrial standards guide electrostatic protection benchmarks for precision component exports. Nagoya and Osaka industrial zones concentrate metallization technology development serving Southeast Asian assembly operations.
Metallic Static Shielding Bags Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale advantages separating captive substrate producers from regional laminators. The upper tier commands semiconductor cleanroom qualifications through in-house polymer metallization capabilities. Mid-tier converters compete on rapid custom sizing for aerospace programs. Dominant competitive moves include geographic expansion into India and Vietnam assembly corridors, plus strategic partnerships with vapor deposition equipment suppliers for coating uniformity advances.
Among diversified materials conglomerates, 3M and DuPont exemplify integrated substrate-to-laminate positioning. Desco Industries anchors the captive distribution archetype through direct technical service integration with electronics assembly plants. These three occupy distinct competitive vectors: proprietary coating technology, fluoropolymer barrier expertise, and channel control through service bundling respectively.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| Sealed Air Corporation |
| Mitsubishi Polyester Film |
| Desco Industries |
| Protective Packaging Corporation |
| Avery Dennison |
| GWP Group |
| Antistat Inc. |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-week IEC 61340-5-1 certification timelines compress converter margins while amplifying pricing power for qualified suppliers serving TSMC and Samsung Foundry cleanroom protocols. This lead-time band concentrates procurement leverage among pre-approved laminators who have secured ANSI/ESD S20.20 validation, creating tiered pricing separation between certified semiconductor-grade suppliers and standard consumer electronics converters.
Pricing Analysis
Long-term offtake agreements dominate semiconductor cleanroom procurement, with TSMC and Samsung Foundry locking in eighteen-to-twenty-four-month supply contracts that insulate qualified converters from spot-market aluminum volatility. Price differentiation separates MIL-PRF-81705 aerospace bags with embedded RFID tags from standardized flat bags for consumer electronics, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from Foxconn and Jabil centralized procurement platforms that benchmark performance data across Mexico and Vietnam assembly clusters, compressing regional distributor margins. Consumer electronics OEMs exhibit highest price sensitivity, while defense contractors at Lockheed Martin and Raytheon accept premium positioning for lot-traceable custom sizing.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Taiwan and South Korea semiconductor fabs, with wafer transport packaging delivered on daily replenishment cycles to Hsinchu Science Park and Pyeongtaek clusters. Primary aluminum smelting concentrates in China and Russia, while vapor deposition equipment manufacturing anchors in Japan and polyester substrate production centers on South Korea and Taiwan. Raw material dependencies rest on purified terephthalic acid feedstock, metallized film substrates, and solvent-based adhesive formulations. Single-source vulnerability runs through Chinese aluminum supply exposed to tariff pass-throughs. Distribution runs through captive technical service networks for aerospace programs and centralized procurement platforms for contract electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where IEC 61340-5-1 and ANSI/ESD S20.20 certification timelines create twelve-to-eighteen-week qualification moats that freeze out opportunistic converters. Switching costs concentrate among semiconductor cleanroom suppliers who have secured embedded lot-traceability mandates from TSMC and Samsung Foundry.
For Market Incumbents: Fortify certification portfolios by accelerating water-based adhesive lamination investments ahead of EPA volatile organic compound enforcement, while deepening captive distribution relationships in Mexico and Vietnam assembly corridors where Foxconn and Jabil centralized platforms threaten regional distributor displacement. Prioritize deposition equipment partnerships with Japanese vapor deposition manufacturers to sustain coating uniformity advantages over emerging Asia-Pacific contract metallizers. For New Entrants and Emerging Players: Lead with localized metallization capacity in India ahead of Micron Technology's Gujarat facility ramp-up, targeting first-mover positioning in a semiconductor assembly corridor lacking legacy supplier entrenchment. Pursue aerospace component qualifications with nano-layered aluminum oxide coatings that decompose incumbent thick-film supply relationships at Lockheed Martin and Raytheon. Emphasize rapid custom-sizing capabilities with MIL-PRF-81705 compliance as the primary go-to-market wedge. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration among contract electronics manufacturers and defense procurement centralization favor scaled converters with in-house polymer metallization capabilities over fragmented regional laminators. Target acquisition profiles emphasizing captive substrate production and established IEC 61340-5-1 certification portfolios. Watch aluminum tariff volatility and REACH perfluorinated compound enforcement timelines as inflection indicators for margin compression and substrate reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Transition | EPA volatile organic compound rules accelerate solvent-free lamination capex deployment among domestic converters. |
| RFID-Enabled Aerospace Packaging | MIL-PRF-81705 bags with integrated traceability tags capture premium pricing from Lockheed Martin satellite programs. |
| India Metallization Capacity Buildout | Micron Technology's Gujarat assembly facility creates localized supply chain requirements for first-mover converters. |
| Nano-Layered Coating Qualification | Aluminum oxide deposition precision decomposes legacy thick-film supply relationships in weight-sensitive launch applications. |
| Captive Distribution Expansion | Technical service integration with Mexico and United States electronics assembly plants defends margin position against platform centralization. |
Study Parameters
Initial hypotheses were tested against primary input from polymer metallization technicians, semiconductor packaging engineers at TSMC and Samsung Foundry, aerospace procurement officers at Lockheed Martin and Raytheon, and electronics assembly plant managers at Foxconn and Jabil facilities, then refined through secondary validation against IEC 61340-5-1 certification databases, EPA emission compliance filings, SEC 10-K disclosures from diversified materials conglomerates, and Japanese vapor deposition equipment manufacturer technical specifications. Bottom-up volume estimates from converter capacity utilization were triangulated against top-down semiconductor wafer shipment data and aerospace component packaging procurement disclosures.
Variance decomposition across product type, material substrate, application certification intensity, and end-user procurement structure shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier movements, with semiconductor cleanroom demand curves and aerospace program award cycles as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA emission guidelines and REACH Annex XVII enforcement regimes; material policy shifts would require re-modeling of lamination technology adoption curves and substrate reformulation timelines. Revision becomes warranted when aluminum tariff pass-through rates or perfluorinated compound restriction enforcement timelines cross thresholds that trigger converter margin compression or forced material substitution cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market