
 Saudi Arabia Electrostatic Discharge (ESD) Films Market | 2026-2036
Saudi Arabia Electrostatic Discharge (ESD) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Electrostatic Discharge (ESD) Films Market Insights
Polyester is restructuring cost-performance economics across Saudi ESD film portfolios as polycarbonate faces pressure from thinner-gauge alternatives with equivalent surface resistivity. BASF leverages its polymer compounding expertise to anchor supply relationships with domestic converters. Desco Industries specializes in static-control material systems and competes through channel control in Gulf electronics manufacturing clusters. Smurfit Kappa Group extends its packaging footprint by integrating ESD-certified films into corrugated protective solutions for regional semiconductor shippers.
Electrostatic Discharge Films are multilayer polymer laminates engineered to surface resistivity specifications between 10^4 and 10^11 ohms per square, manufactured through coextrusion or vapor-deposited metallization to dissipate static charge and protect voltage-sensitive components from catastrophic failure. Polyester films dominate volume consumption due to dimensional stability and compatibility with clean room protocols, while ultra-thin gauges represent the fastest-expanding thickness category as miniaturized electronics demand reduced packaging mass. Protective packaging applications command the largest margin pool because semiconductor and medical device shippers prioritize lot integrity over material cost in their procurement criteria.
SFDA and SASO frameworks govern material safety certifications for ESD films entering medical device and electronics supply chains, while Saudi Vision 2030 localization requirements are tightening import substitution timelines for polymer converters serving domestic manufacturing zones. The country's national standards body is aligning ESD test methodologies with IEC 61340 series specifications to qualify local production for export eligibility. Stakeholders must monitor how rapidly domestic compounding capacity scales relative to electronics assembly investments in the Kingdom's special economic zones.
Market Dynamics
Semiconductor packaging investments in Jeddah and Riyadh are compressing procurement cycles for ESD-certified films, forcing converters to localize compounding capacity ahead of domestic demand maturation.
Growth Catalysts
- Vision 2030 localization mandates:Electronics manufacturing zones in the Kingdom require domestic sourcing of protective materials, redirecting film procurement from imports to local converters.
- Advanced packaging proliferation:Flip-chip and wafer-level packaging operations demand ultra-thin ESD films with tighter surface resistivity tolerances.
- IEC 61340 alignment:SASO adoption of international ESD test standards qualifies Saudi-produced films for export to Gulf Cooperation Council electronics clusters.
Market Restraints
- Specialty polymer import dependence:Conductive masterbatches and vapor-deposition equipment originate primarily from German and Japanese suppliers, exposing converters to currency volatility.
- Clean room infrastructure scarcity:Jeddah and Riyadh host limited ISO Class 7-8 film slitting facilities, constraining domestic production scale-up.
- Polyethylene terephthalate glycol competition:Lower-cost anti-static PETG films from Southeast Asian producers threaten polyester ESD film margins in commodity applications.
Strategic Opportunities
- Neom special economic zone:Planned semiconductor foundry investments create captive demand for vertically integrated ESD film supply within the megacity's industrial corridor.
- Medical device packaging convergence:SFDA sterility requirements for implantable electronics are merging ESD and barrier film specifications, opening multi-layer laminate development.
- Direct converter-to-assembler contracting:Foxconn and Advanced Electronics Company procurement teams are bypassing distributors for volume ESD film agreements.
Industry Challenges
- Polymer compounding technician shortage:Domestic workforce development lags behind the technical demands of carbon nanotube dispersion and metallization process control.
- SASO certification timeline compression:New electronics material safety protocols require 12-18 month validation cycles that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Electrostatic Discharge (ESD) Films Market |
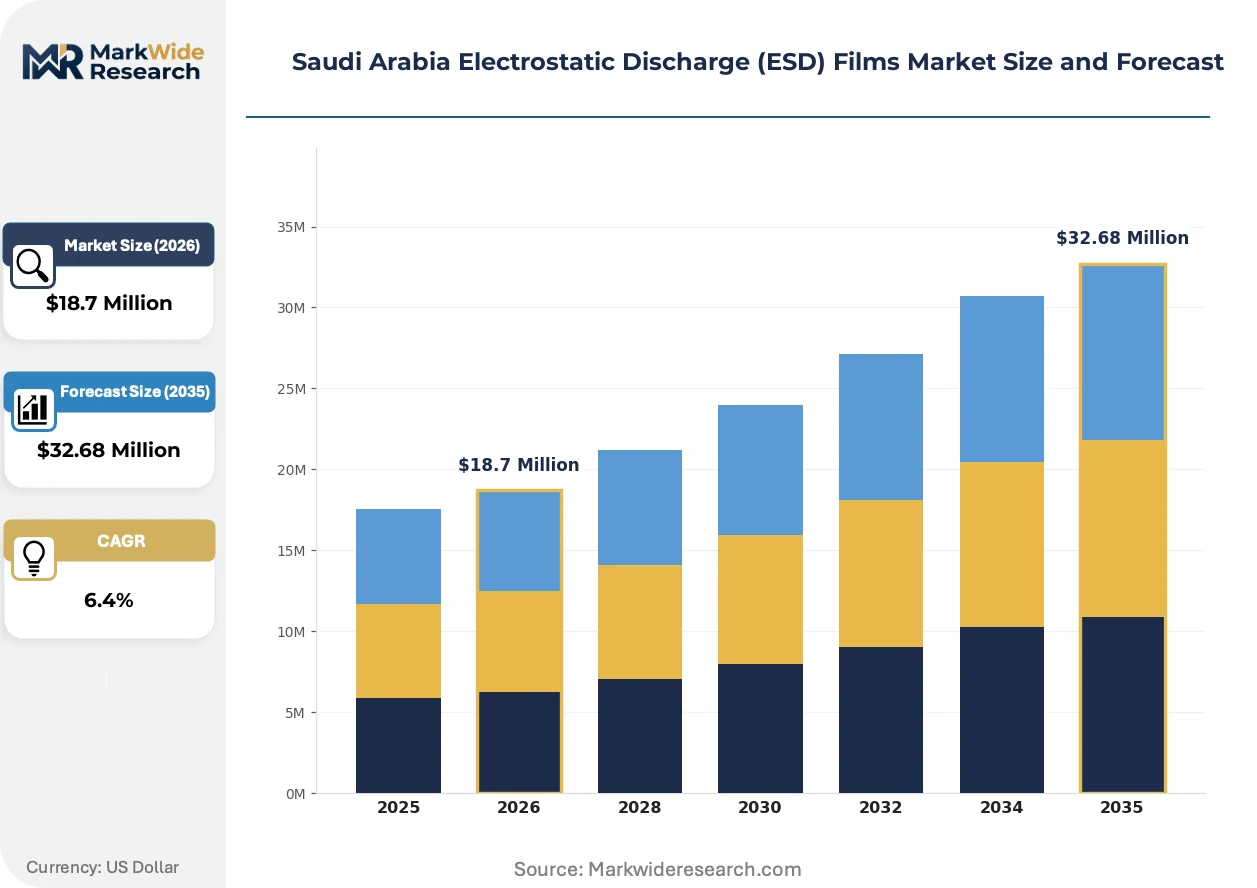
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $32.68 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polyester, Polycarbonate, PVC, Nylon End User: Electronics, Automotive, Aerospace, Medical Application: Protective Packaging, Surface Mount Devices, Manufacturing Processes, Clean Rooms Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | Desco Industries, Smurfit Kappa Group, BASF, DS Smith, Sealed Air Corporation, NEFAB Group, Teknis Limited, GWP Group, Storopack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Electrostatic Discharge (ESD) Films Market Trends and Innovations
Film architecture and procurement protocols are evolving in parallel, with thickness reduction and regulatory harmonization compressing traditional specification cycles across Saudi electronics manufacturing.
Multi-layer coextrusion with vapor-deposited aluminum metallization is rewriting performance benchmarks for static dissipation in miniaturized component packaging. Advanced packaging lines at semiconductor assembly facilities in Riyadh are specifying 25-micron gauges, half the thickness of legacy polyester constructions. The technology is rewriting cost structures by reducing polymer consumption while maintaining surface resistivity below 10^9 ohms per square.
SFDA alignment with IEC 61340-5-1 packaging standards is eliminating dual-certification burdens for medical device exporters. Electronics manufacturers serving both domestic hospitals and Gulf markets now qualify single film specifications across jurisdictions. Medical device shippers in Jeddah are consolidating supplier bases to capture this harmonization benefit.
Volume-based direct contracting is displacing distributor-mediated procurement for ESD film consumers above defined annual tonnage thresholds. Semiconductor assemblers and medical device original equipment manufacturers are negotiating multi-year supply agreements with compounders. The shift is most visible in Riyadh's King Salman Energy Park, where electronics clusters concentrate purchasing power for specialty polymer inputs.
Saudi Arabia Electrostatic Discharge (ESD) Films Market Segmentation
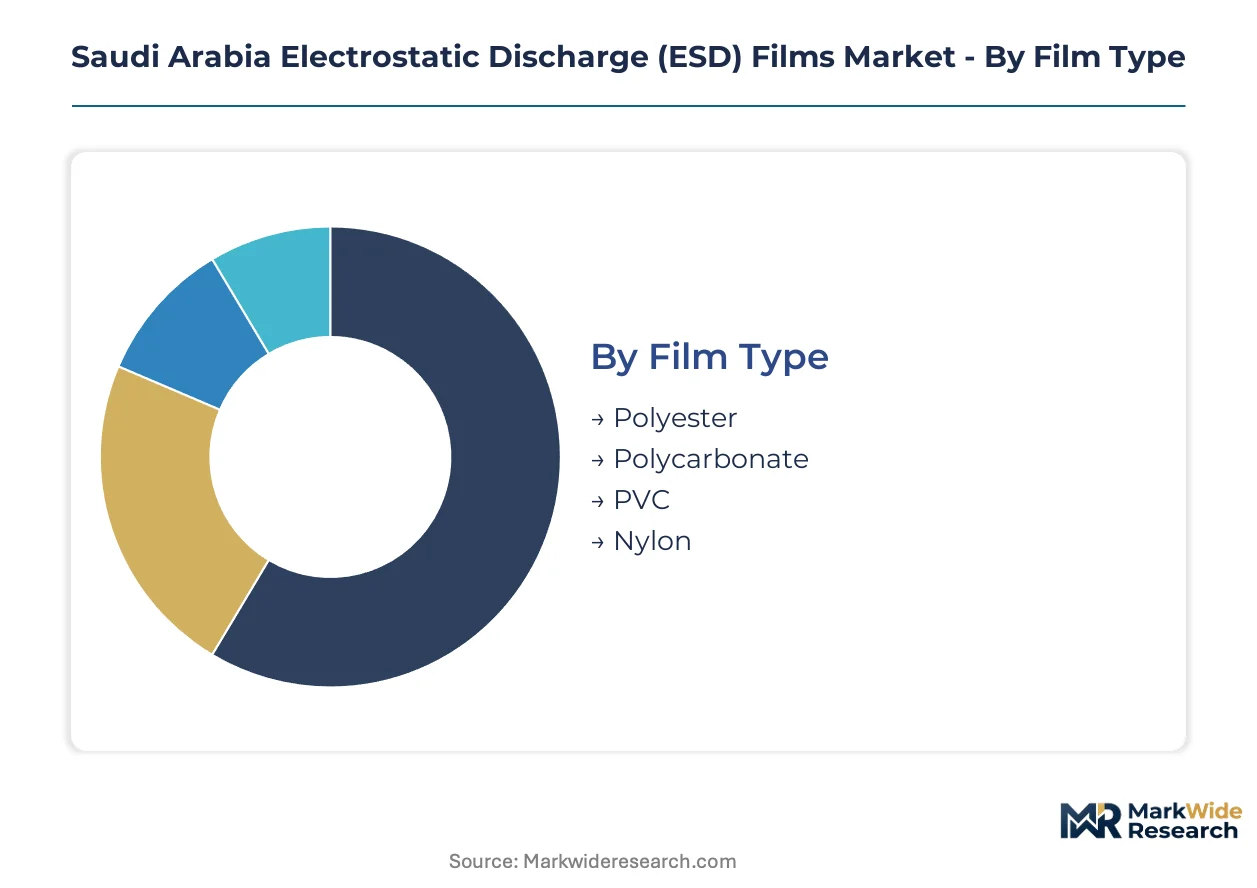
ESD film procurement in Saudi Arabia fragments across material chemistry, end-use specifications, and gauge requirements. Each dimension carries distinct capital requirements and certification burdens that reshape converter investment priorities.
Film Type:
Capital intensity peaks with vapor-deposition metallization equipment for surface resistivity control, while coextrusion lines demand less upfront outlay but higher polymer inventory carrying costs.
- Polyester:Biaxially oriented polyethylene terephthalate dominates volume through dimensional stability under clean room thermal cycling. Semiconductor packaging lines in Riyadh specify this substrate for flip-chip carrier tapes, though Jeddah converters face PETG price pressure from Southeast Asian imports.
- Polycarbonate:Optical clarity and impact resistance position this polymer for inspection windows and carrier trays where visual component verification matters. Thinner-gauge polyester alternatives are eroding share in cost-sensitive applications as miniaturization reduces mass requirements.
- PVC:Lower capital barriers attract regional compounders serving commodity anti-static sheeting for general electronics handling.
- Nylon:Moisture absorption challenges limit penetration despite toughness advantages in aerospace cable wrapping.
Most installed capacity flows through polyester. Expansion is steepest in polycarbonate as medical device packaging demands optical-grade clarity.
End User:
Customer concentration varies sharply — semiconductor assemblers consolidate purchasing power while aerospace buyers fragment across maintenance facilities.
- Electronics:Integrated circuit packaging, printed circuit board assembly, and component distribution drive absolute tonnage. Foxconn and Advanced Electronics Company procurement teams in Riyadh are negotiating direct multi-year supply agreements that bypass traditional distribution channels.
- Automotive:Advanced driver-assistance system module packaging and electric powertrain electronics create specification overlap with industrial ESD protocols. Tier-1 suppliers in Jeddah's automotive cluster are qualifying films for battery management system components.
- Aerospace:Military avionics and maintenance operations at King Abdulaziz Air Base generate intermittent high-specification demand with extended qualification cycles.
- Medical:Implantable electronics and diagnostic device packaging merge SFDA sterility requirements with IEC 61340-5-1 static control standards.
Electronics commands the dominant procurement volume. Medical is gaining share fastest as SFDA harmonization eliminates dual-certification burdens.
Application:
Margin structure inverts across the application stack — protective packaging captures premium pricing while manufacturing process films compete on unit economics.
- Protective Packaging:Multi-layer laminates with vapor-deposited aluminum metallization protect lot integrity during semiconductor shipment. Medical device shippers prioritize performance over material cost, supporting margin pools unavailable in commodity segments.
- Surface Mount Devices:Carrier tapes and cover tapes for tape-and-reel feeding systems demand precise surface resistivity tolerances. Miniaturization is compressing gauge specifications toward 25-micron constructions.
- Manufacturing Processes:Workstation mats, floor tiles, and garment fabrics serve assembly line static control with shorter replacement cycles.
- Clean Rooms:Curtain walls and equipment enclosures require ISO Class 7-8 compatible materials with low outgassing profiles.
Protective packaging absorbs the majority of specialty polymer inputs. Surface mount devices are expanding most quickly as advanced packaging proliferates.
Thickness:
Gauge selection directly determines polymer consumption per unit area and metallization equipment throughput rates.
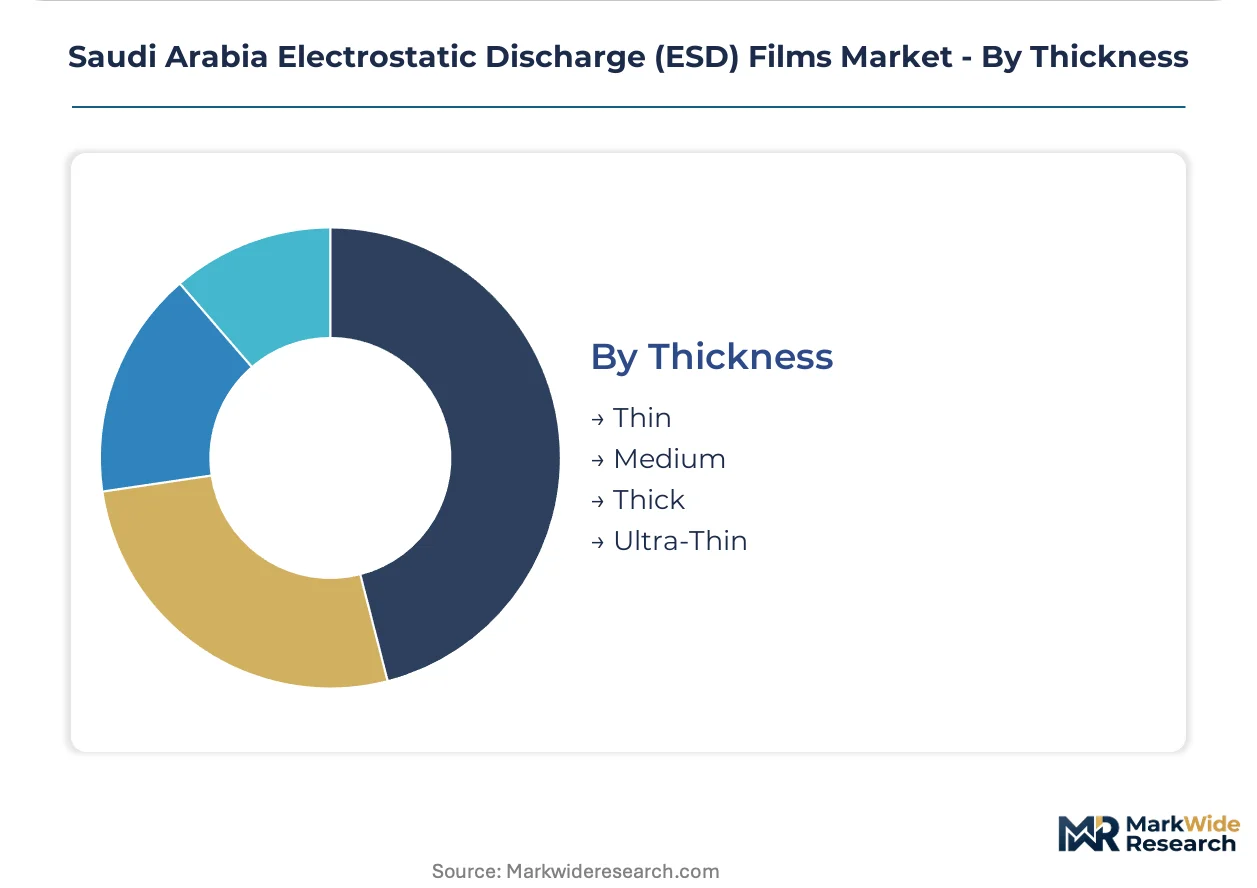
- Ultra-Thin:Sub-30 micron constructions reduce packaging mass for miniaturized components while maintaining surface resistivity below 10^9 ohms per square through optimized metallization density.
- Thin:30-50 micron range balances handling durability with material efficiency in high-volume semiconductor shipping.
- Medium:50-100 micron specifications dominate legacy carrier tape applications with established tooling compatibility.
- Thick:Above-100 micron gauges serve heavy-duty industrial applications and reusable shipping containers with extended duty cycles.
Medium gauges retain the largest installed equipment base. Ultra-thin is climbing the fastest as wafer-level packaging operations proliferate in Riyadh and Jeddah.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's King Salman Energy Park concentrates semiconductor packaging demand, compressing procurement cycles for ESD-certified films across the Kingdom's industrial zones.
Riyadh
Advanced Electronics Company and Foxconn procurement teams negotiate direct multi-year supply agreements for ultra-thin polyester films. SASO certification timelines for IEC 61340 alignment extend 12-18 months, delaying product commercialization for local converters. King Salman Energy Park hosts the densest concentration of electronics manufacturing, with flip-chip packaging lines specifying 25-micron gauge constructions.
Jeddah
Semiconductor assemblers drive consumption of vapor-deposited metallized films for carrier tape applications. SFDA sterility requirements for medical device exporters merge with static control standards, eliminating dual-certification burdens. The city's automotive cluster qualifies films for battery management system components in electric powertrain electronics.
Eastern Province
Petrochemical feedstock availability attracts polymer compounding investments for conductive masterbatch production. Saudi Aramco's industrial localization programs channel capital toward domestic converter capacity. Jubail's manufacturing zones remain underdeveloped for ISO Class 7-8 clean room film slitting, constraining scale-up.
NEOM Northwest
Planned semiconductor foundry investments create captive demand for vertically integrated ESD film supply within the megacity's industrial corridor. Saudi Vision 2030 mandates require domestic sourcing thresholds for protective materials entering special economic zones. The northwest location positions production for export eligibility to Gulf Cooperation Council electronics clusters.
Saudi Arabia Electrostatic Discharge (ESD) Films Market Competitive Landscape
Direct converter-to-assembler contracting dominates the current landscape, displacing traditional distributor channels for volume consumers above defined tonnage thresholds. The vendor base stratifies across three tiers: multinational chemical conglomerates with polymer compounding expertise, specialized static-control material systems providers, and integrated packaging converters extending protective film capabilities. Capacity expansion and strategic partnerships represent the primary competitive vectors as localization mandates compress procurement timelines.
Within the chemical conglomerate tier, BASF anchors supply relationships through polymer compounding expertise. Desco Industries occupies a specialist position in static-control material systems. Smurfit Kappa Group exemplifies the packaging converter archetype integrating ESD-certified films into corrugated protective solutions. These three represent distinct strategic positions: upstream material science, dedicated static-control engineering, and downstream packaging integration.
| Leading Market Players |
|---|
| Desco Industries |
| Smurfit Kappa Group |
| BASF |
| DS Smith |
| Sealed Air Corporation |
| NEFAB Group |
| Teknis Limited |
| GWP Group |
| Storopack |
| Others |
Pricing and Supply Chain Analysis
Conductive masterbatch costs from German and Japanese suppliers cascade through Saudi converter operations into three-tier pricing structures across premium, standard, and economy levels. Foxconn and Advanced Electronics Company procurement teams exploit volume concentration to compress contract terms, while PETG imports from Southeast Asia erode margins in commodity segments.
Pricing Analysis
Input-cost pass-through from specialty polymer feedstocks determines contract structures, with vapor-deposition equipment amortization driving premium tier separation from coextrusion-based standard offerings. Price differentiation hinges on IEC 61340 certification tier and volume scale, with medical device shippers showing lowest sensitivity due to lot integrity priorities. Cost compression in commodity polyester films is intensifying because of Southeast Asian PETG competition. Semiconductor assemblers demonstrate least price sensitivity; general electronics distributors face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese suppliers of conductive masterbatches and metallization equipment, exposing Saudi converters to currency volatility and extended lead times. Geographic supply concentration centers on Germany, Japan, and South Korea for critical polymer compounding technology and vapor-deposition systems. Raw material dependencies rest on polyethylene terephthalate resin, carbon nanotube concentrates, and aluminum sputtering targets. Tariff exposure compounds risks as localization mandates tighten import substitution timelines. Distribution runs through direct converter-to-assembler contracting for volume consumers above defined tonnage thresholds, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi ESD Films Market functions as a stable compounder anchored by irreversible localization mandates under Vision 2030 that guarantee sustained domestic demand growth regardless of global electronics cycles.
For Market Incumbents: Anticipate margin compression from PETG substitution by securing backward integration into conductive masterbatch compounding within King Salman Energy Park. Prioritize IEC 61340-5-1 certification investment to capture medical device packaging convergence opportunities before SASO timeline compression delays commercialization. Channel control in Gulf electronics manufacturing clusters remains the priority defensive lever against distributor disintermediation. For New Entrants and Emerging Players: The price-point gap between premium vapor-deposited metallized films and economy-grade coextruded polyester presents white-space opportunity in mid-tier medical device packaging. Target Jeddah's automotive cluster for battery management system component films where qualification cycles remain shorter than semiconductor packaging. Pursue direct contracting with Tier-1 automotive suppliers as the most penetrable entry vector. For Investors and Strategic Acquirers: Consolidation pressure builds where domestic compounding capacity scales lag electronics assembly investments in special economic zones. Frame long-term viability around captive supply relationships within vertically integrated industrial corridors. Acquisition target archetype: regional converters with existing SASO certification infrastructure and clean room slitting capability. Watch domestic workforce development velocity for polymer compounding technicians as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Masterbatch Production | Reduces import dependence from German and Japanese suppliers while capturing margin pool currently exported. |
| IEC 61340-5-1 Certification Investment | Qualifies Saudi-produced films for export to Gulf Cooperation Council electronics clusters under harmonized standards. |
| ISO Class 7-8 Clean Room Slitting Capacity Addition | Removes production bottleneck constraining domestic scale-up in Jeddah and Riyadh manufacturing zones. |
| Direct Converter-to-Assembler Long-term Supply Agreement | Bypasses distributor channels where Foxconn and Advanced Electronics Company procurement teams consolidate purchasing power. |
| Medical Device Packaging Multi-layer Laminate Development | Captures SFDA sterility requirement convergence with static control standards for implantable electronics. |
Research Methodology
Direct dialogue with polymer compounding technicians, semiconductor packaging procurement managers, medical device regulatory affairs leads, and SASO certification officials grounded qualitative insights. Secondary validation drew from SASO technical regulations, IEC 61340 series documentation, Saudi Vision 2030 industrial localization program disclosures, and customs trade data for polymer film imports. Bottom-up and top-down triangulation cross-referenced converter capacity announcements with electronics manufacturing investment flows across the Kingdom's special economic zones.
Bottom-up modeling segmented volume and value projections across film type, end user, application, and thickness dimensions. The analytical framework incorporated wafer-level packaging proliferation rates, clean room infrastructure buildout timelines, and workforce development velocity for specialized polymer technicians. CAGRs were derived from installed equipment base expansion, import substitution trajectory, and export eligibility qualification under harmonized Gulf standards. Industry-specific forecast inputs included semiconductor foundry investment announcements in NEOM and medical device packaging demand from SFDA-regulated exporters.
Caveats apply where Saudi Vision 2030 localization timeline acceleration or IEC 61340 adoption delays could materially shift the outlook. Forecasts reflect assumptions about domestic compounding capacity scaling relative to electronics assembly investments. Semiconductor cycle downturns, currency volatility in specialty polymer imports, and clean room infrastructure construction delays represent specific revision triggers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market