
 Asia-Pacific Electrostatic Discharge (ESD) Packaging Market | 2026-2036
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market Analytics
The EU Green Deal's extraterritorial reach into Asian supply chains is repositioning ESD packaging procurement toward recyclable conductive polymers and bio-based dissipative coatings. Dou Yee Enterprises leverages its Singapore-Johor manufacturing corridor to dominate anti-static tray supply for Malaysian semiconductor backend facilities. Desco Industries Inc. anchors North American-origin quality protocols across its Thailand and China distribution networks, competing on MIL-STD-3010 compliance traceability. Protektive Pak specializes in corrugated ESD solutions for aerospace MRO channels across Australia and India, where TGA and DGCA airworthiness directives govern component handling standards.
Asia-Pacific Electrostatic Discharge (ESD) Packaging encompasses engineered materials and containers designed to prevent triboelectric charge accumulation, typically achieving surface resistivity between 10^3 and 10^11 ohms per square through carbon-loaded or metallized substrates. These systems protect sensitive electronic components during transport, storage, and assembly operations in controlled environments. Bags and conductive foam trays together capture the dominant share of semiconductor and memory module shipments, with polyethylene formulations leading on cost efficiency for high-volume consumer electronics. Boxes and rigid containers command premium positioning in automotive ECU and medical device logistics, where JIS and BIS contamination standards require repeatable cleanroom-compatible designs.
Japan's METI enforces electrostatic control guidelines under its industrial standardization framework, while China's SAMR administers GB/T 32304 for static protective packaging through mandatory product certification. India's BIS has introduced phased compliance timelines for ESD materials used in PLI-linked electronics manufacturing, directly shaping supplier qualification requirements. Stakeholders must monitor divergence between Japan's JIS Z 0237 test methodologies and China's evolving GB standards, as dual certification burdens will determine factory gate access across the region's three largest electronics export economies.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are consolidating ESD packaging procurement around conductive foam trays and static-dissipative bags, compressing supplier qualification timelines and tightening compliance thresholds across the Asia-Pacific electronics corridor.
Growth Catalysts
- China's GB/T 32304 Certification:Mandatory product certification administered by SAMR is forcing contract assemblers in the Yangtze River Delta to upgrade static protective packaging, creating pull-through demand for certified conductive polymers.
- Electric Vehicle ECU Proliferation:Automotive electronics manufacturing in China and South Korea requires JIS-compliant rigid containers for power module logistics, expanding the addressable market beyond traditional semiconductor applications.
- Carbon-Loaded Polyethylene Formulations:Advances in cost-efficient conductive substrates are displacing metallized alternatives in high-volume consumer electronics shipments from Malaysian and Vietnamese contract manufacturers.
Market Restraints
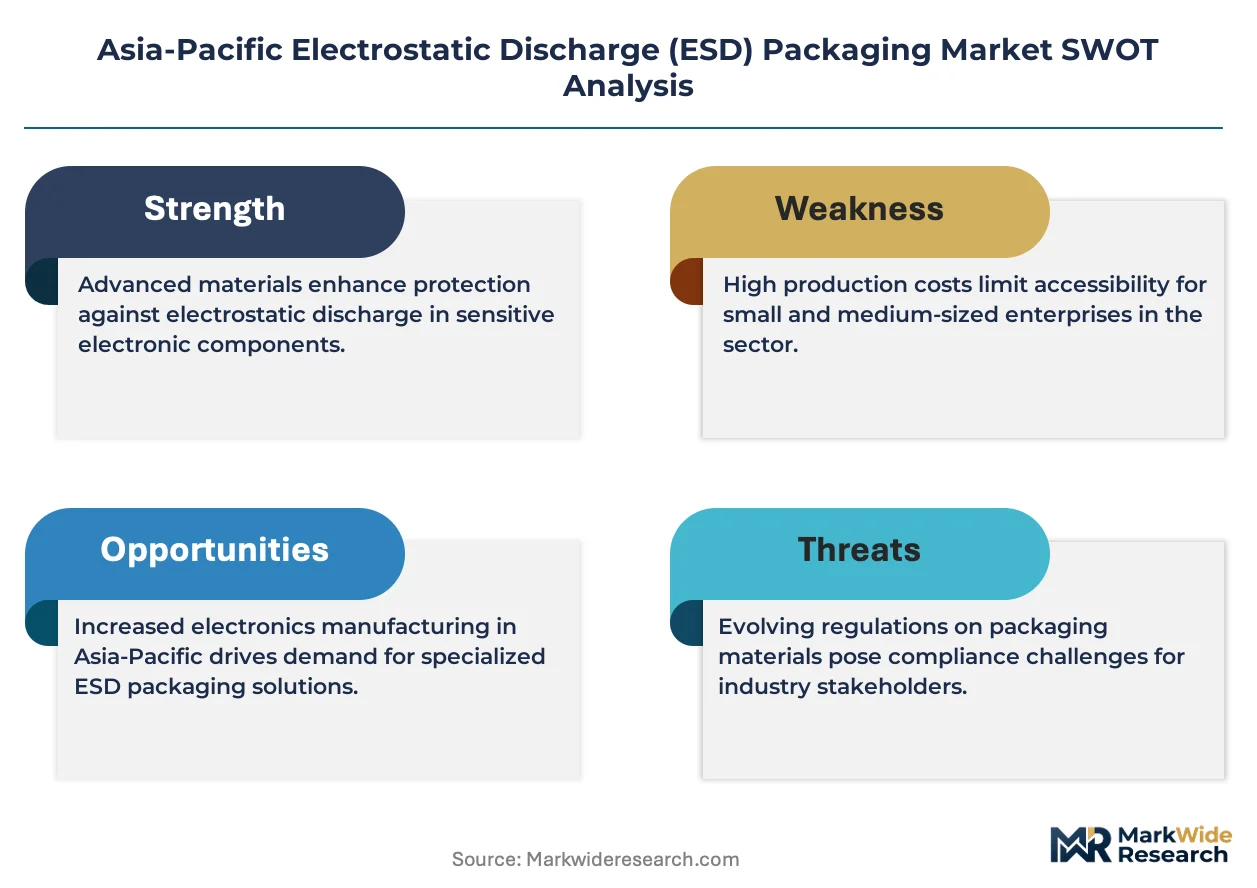
- Petrochemical Feedstock Volatility:Polyethylene and polypropylene price swings directly compress margins for conductive foam tray producers serving price-sensitive memory module assemblers.
- Supplier Concentration in Johor-Singapore Corridor:Heavy reliance on Dou Yee Enterprises and adjacent Malaysian backend facilities creates geographic vulnerability to port congestion and cross-border customs friction.
- Dual Certification Burden:Divergence between Japan's JIS Z 0237 test methodologies and China's evolving GB standards forces suppliers to maintain parallel qualification protocols, inflating compliance overhead.
Strategic Opportunities
- India's PLI-Linked Electronics Manufacturing:BIS phased compliance timelines for ESD materials create first-mover advantage for suppliers establishing qualification relationships with contract assemblers in Tamil Nadu and Karnataka.
- EU Green Deal Extraterritoriality:Recyclable conductive polymers and bio-based dissipative coatings are gaining procurement preference among export-oriented Taiwanese semiconductor fabs serving European automotive OEMs.
- Aerospace MRO Channels:TGA and DGCA airworthiness directives across Australia and India are mandating corrugated ESD solutions for component handling, opening specialized demand beyond mainstream electronics.
Industry Challenges
- Cleanroom Compatibility Engineering:Medical device and automotive ECU logistics require repeatable contamination control designs that meet both JIS and BIS standards simultaneously, stretching R&D bandwidth.
- Dual Certification Timeline Compression:Factory gate access across Japan, China, and India demands parallel track qualification against diverging test methodologies, extending sales cycles by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electrostatic Discharge (ESD) Packaging Market |
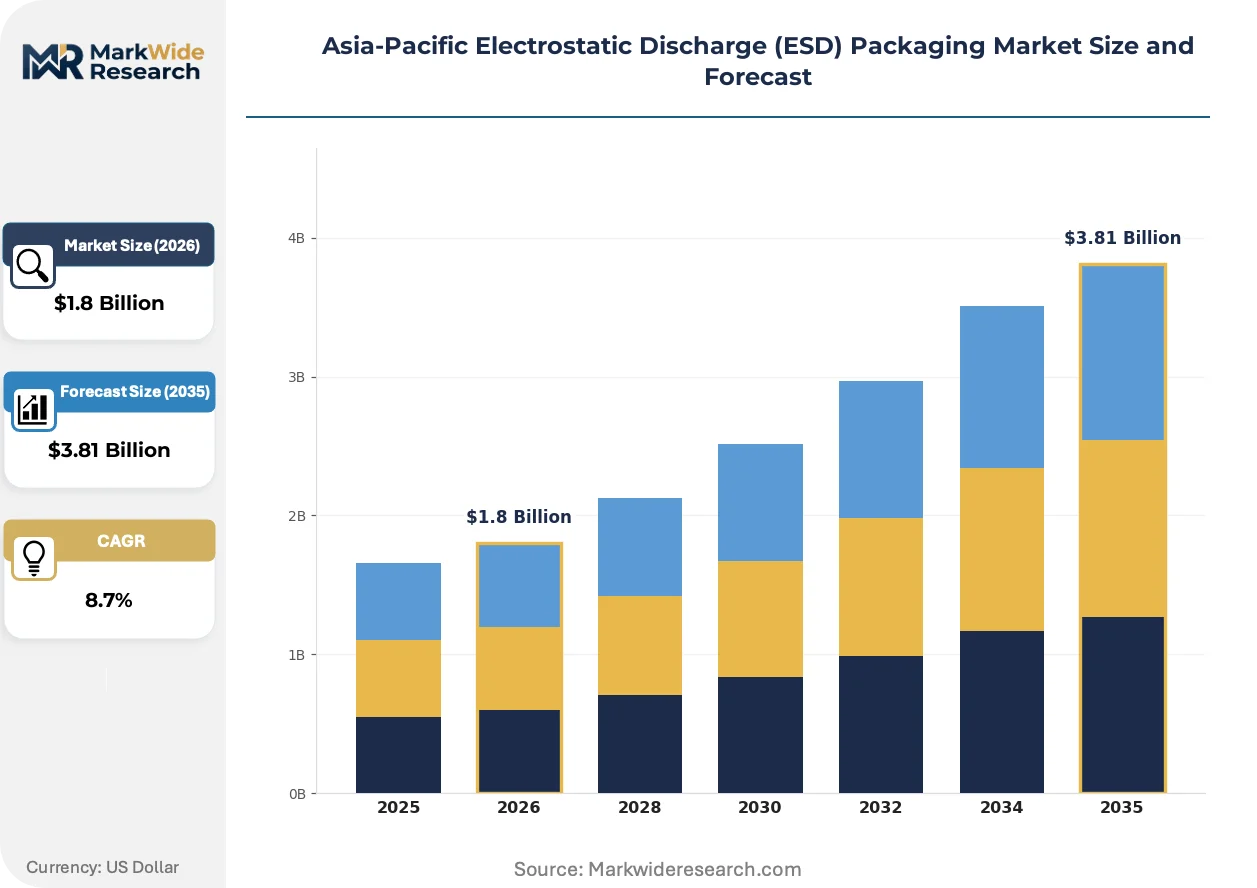
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bags, Boxes, Trays, Tapes Material: Polyethylene, Polypropylene, PVC, Conductive Foam End User: Electronics, Automotive, Aerospace, Healthcare Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Protektive Pak, Dou Yee Enterprises, Desco Industries Inc., Static Control Components, Nefab, GWP Group Limited, Teknis Limited, Smurfit Kappa Group, Summit Packaging Solutions, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market Evolving Landscape
Material science advances and regulatory extraterritoriality are converging to reshape ESD packaging specifications across Asia-Pacific electronics manufacturing, with sustainability mandates and semiconductor process evolution driving specification upgrades.
Multi-layer metallized film technology is unifying barrier protection and static dissipation in a single substrate architecture. Memory module assemblers in South Korea are transitioning procurement specifications toward these unified films at accelerated pace. This convergence is compressing demand for separate moisture-barrier and anti-static bag categories, forcing suppliers to consolidate product lines.
Japan's METI electrostatic control guidelines are tightening enforcement thresholds for cleanroom materials used in advanced node semiconductor production. Industrial standardization framework updates are mandating lower surface resistivity ranges for substrates entering sub-7nm fab environments. Taiwanese backend facilities serving Japanese IDM customers are pre-emptively adopting these stricter protocols across their entire Asia-Pacific supplier base.
Specification-driven vendor consolidation is concentrating procurement decisions at the OEM level rather than contract assembler level. Apple and Tesla supply chain mandates are displacing assembler-discretionary purchasing for ESD packaging across their China and Southeast Asian manufacturing partners. This shift is most visible in the Yangtze River Delta electronics corridor, where qualified supplier lists have contracted by half over the past qualification cycle.
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market Segmentation
ESD packaging specifications diverge sharply across Asia-Pacific electronics manufacturing, with semiconductor fabs demanding precision-engineered solutions while automotive contract assemblers prioritize cost-scalable formats. Segmentation reveals how material science and channel configuration determine supplier qualification success.
Packaging Type:
Volume concentration in high-shipment electronics corridors creates tiered demand, with premium rigid formats serving automotive ECU logistics and flexible solutions dominating consumer electronics throughput.
- Bags:Multi-layer metallized films achieve surface resistivity between 10^3 and 10^11 ohms per square through carbon-loaded polyethylene substrates. South Korean memory module assemblers are consolidating procurement around unified barrier-static dissipation films, compressing separate moisture-barrier and anti-static categories into single-substrate specifications.
- Trays:Conductive foam formulations protect bare die and packaged semiconductors during backend test-and-burn operations. Taiwan's expanding fab capacity is pulling disproportionate tray volumes through the Singapore-Johor manufacturing corridor, where port congestion risks create supply vulnerability.
- Boxes:Rigid containers meet JIS contamination standards for automotive power module logistics across China and South Korea.
- Tapes:Static-dissipative adhesive formats seal moisture-barrier bags in high-volume consumer electronics packaging from Vietnamese contract manufacturers.
Today's leader: Bags. Tomorrow's challenger: Trays.
Material:
Cost efficiency and regulatory compliance are reshaping substrate selection, with carbon-loaded polymers displacing metallized alternatives in price-sensitive applications while cleanroom-grade materials command automotive and medical premiums.
- Polyethylene:Carbon-loaded formulations dominate high-volume consumer electronics shipments from Malaysian and Vietnamese contract assemblers. China's SAMR-administered GB/T 32304 certification is forcing Yangtze River Delta upgraders toward certified conductive polyethylene grades, creating specification divergence from uncertified alternatives.
- Conductive Foam:Open-cell polyurethane structures cushion shock-sensitive semiconductors while maintaining consistent surface resistivity. Taiwan and South Korean fab expansions are compressing supplier qualification timelines for foam tray providers, tightening compliance thresholds across the region.
- Polypropylene:Rigid formulations serve reusable container applications in automotive ECU logistics where JIS standards apply.
- PVC:Legacy substrate retains niche presence in cost-constrained packaging from Indian electronics manufacturing zones.
Polyethylene captures current volume leadership. Conductive foam is climbing the fastest as semiconductor backend capacity expands.
End User:
Application-specific contamination thresholds and logistics durability requirements segment demand across precision electronics, heavy-duty automotive, and regulated aerospace and medical channels.
- Electronics:Semiconductor and memory module manufacturing concentrates demand in Taiwan, South Korea, and China's Yangtze River Delta. Apple's supply chain mandates are displacing assembler-discretionary ESD packaging purchasing across Southeast Asian manufacturing partners, consolidating procurement at OEM level.
- Automotive:Electric vehicle ECU proliferation requires JIS-compliant rigid containers for power module logistics. Tesla's China manufacturing is driving specification upgrades for static-dissipative boxes serving high-voltage electronics.
- Aerospace:TGA and DGCA airworthiness directives across Australia and India mandate corrugated ESD solutions for component handling.
- Healthcare:Medical device logistics require repeatable cleanroom-compatible designs meeting simultaneous JIS and BIS contamination standards.
Electronics maintains segment dominance. Automotive is gaining share fastest on EV ECU volume expansion.
Distribution Channel:
Channel selection reflects customer scale and certification complexity, with direct relationships dominating qualified supplier programs and distributors serving fragmented assembler demand.
- Direct Sales:OEM-level procurement consolidation favors direct supplier relationships for certified ESD packaging. Apple and Tesla supply chain mandates are compressing distributor intermediation in their qualified supplier networks.
- Distributors:Regional networks anchor supply for fragmented contract assembler demand across Malaysia and Vietnam. Desco Industries leverages Thailand and China distribution networks to extend North American-origin quality protocols.
- Online Retail:Digital channels serve small-batch prototyping demand from electronics design houses.
- Wholesalers:Volume aggregation points serve price-sensitive memory module assemblers with standardized bag specifications.
Direct sales leads on qualification intensity. Distributors defend position through regional coverage density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ESD packaging industrialization originated in Japan's precision electronics sector during the 1970s semiconductor boom, with JIS standardization frameworks later diffusing across Taiwan and South Korea as contract manufacturing scaled. Today's Asia-Pacific market reflects this lineage through regulatory fragmentation and clustered production geography.
China
Contract assemblers in the Yangtze River Delta electronics corridor serve Apple, Tesla, and domestic EV brands through expanding procurement of conductive foam trays and static-dissipative bags. SAMR-administered GB/T 32304 certification mandates are forcing packaging upgrades across Shenzhen and Suzhou manufacturing zones. Shanghai and surrounding Jiangsu province concentrate the highest certified supplier density.
Japan
Advanced node semiconductor fabs require METI-enforced electrostatic control guidelines with tightening cleanroom material thresholds. JIS Z 0237 test methodologies govern substrate specifications for sub-7nm production environments. Kyushu and Tohoku regions host backend facilities that pre-emptively export these stricter protocols across their Asia-Pacific supplier networks.
South Korea
Memory module assemblers are consolidating procurement around unified barrier-static dissipation films, compressing separate product categories into single-substrate specifications. Domestic industrial standards align with JIS frameworks for automotive power module logistics. Pyeongtaek and Hwaseong semiconductor clusters drive disproportionate tray and bag volumes.
Taiwan
Expanding fab capacity pulls conductive foam tray volumes through regional supply chains serving Japanese IDM customers. Export-oriented semiconductor facilities face EU Green Deal extraterritorial pressure toward recyclable conductive polymers. Hsinchu Science Park anchors backend test-and-burn operations with compressed supplier qualification timelines.
India
PLI-linked electronics manufacturing in Tamil Nadu and Karnataka is creating first-mover qualification opportunities for ESD material suppliers. BIS phased compliance timelines are shaping supplier selection criteria for contract assemblers. Delhi-NCR and Bengaluru industrial corridors concentrate emerging cleanroom-compatible packaging demand.
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and cleanroom compatibility tiers. The vendor base stratifies between multinational standard-bearers with MIL-STD traceability and regional fabricators competing on polyethylene cost efficiency. Three archetypes dominate: Japanese-heritage precision specialists, Singapore-Malaysia corridor logistics integrators, and North American-origin compliance anchors. Capacity expansion and geographic distribution partnerships constitute the dominant competitive moves.
Among Singapore-Malaysia corridor specialists, Dou Yee Enterprises exemplifies the logistics-integrated archetype through its Johor manufacturing footprint. Desco Industries Inc. represents North American-origin quality protocol extension across Thailand and China distribution networks. Protektive Pak occupies the aerospace-specialist position for corrugated solutions across Australia and India. These three anchors illustrate how geographic positioning and certification heritage determine factory gate access across diverging national standards.
| Leading Market Players |
|---|
| Protektive Pak |
| Dou Yee Enterprises |
| Desco Industries Inc. |
| Static Control Components |
| Nefab |
| GWP Group Limited |
| Teknis Limited |
| Smurfit Kappa Group |
| Summit Packaging Solutions |
| Others |
Value Network & Pricing Analysis
Apple and Tesla supply chain mandates have consolidated procurement decisions at the OEM level, compressing contract assembler pricing power and forcing three-tier pricing stratification across certified, standard, and uncertified supplier tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs ESD packaging transactions, with JIS and GB/T certification grade separating premium conductive foam trays from commodity polyethylene bags. Price differentiation hinges on cleanroom compatibility and dual-certification overhead, with Taiwanese semiconductor fabs showing lowest price sensitivity while Vietnamese consumer electronics assemblers drive hardest volume negotiations. Cost compression in standard-grade polyethylene runs through petrochemical feedstock volatility, squeezing Malaysian contract manufacturer margins most acutely.
Supply Chain Analysis
Workforce availability constraints in Johor and Singapore are tightening throughput capacity for conductive foam tray production serving Taiwan's expanding fab base. Manufacturing concentrates in Malaysia, China, and Thailand, with carbon-loaded polyethylene resins and open-cell polyurethane feedstocks drawing from regional petrochemical complexes. Single-source vulnerability around the Singapore-Johor corridor exposes supply chains to port congestion disruptions. Distribution runs through qualified supplier programs for OEM-direct procurement and regional distributor networks for fragmented assembler demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ESD packaging market represents a late-cycle quality story, with semiconductor process evolution toward sub-7nm nodes and EU Green Deal extraterritoriality shifting procurement specifications toward premium recyclable substrates.
For Market Incumbents: Deploy dual-certification infrastructure to capture factory gate access across Japan's METI-enforced guidelines and China's SAMR-administered GB/T 32304 mandates. Deepen backward integration into carbon-loaded polymer compounding to defend margin position against petrochemical price swings. Consolidate distributor relationships in the Yangtze River Delta before OEM procurement mandates eliminate assembler-discretionary purchasing entirely. For New Entrants and Emerging Players: Launch via India's PLI-linked electronics manufacturing corridors, where BIS phased compliance timelines create qualification windows before incumbent supplier lists harden. Target Tamil Nadu and Karnataka contract assemblers with cleanroom-compatible tray formats for medical device logistics. Pursue aerospace MRO channels in Australia and India, where TGA and DGCA airworthiness directives mandate corrugated ESD solutions with less entrenched competition. For Investors and Strategic Acquirers: Singapore-Malaysia corridor logistics integrators are the most active acquirer in this space, seeking Johor manufacturing footprints to serve Taiwanese backend facility expansion. Long-term viability centers on certification asset accumulation and geographic distribution density rather than commodity polyethylene scale. Watch for divergence between Japan's JIS Z 0237 test methodology updates and China's evolving GB standards as the signal for compliance overhead inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Infrastructure Investment | Factory gate access across Japan, China, and India requires parallel JIS and GB/T qualification protocols. |
| Backward Integration into Polymer Compounding | In-house carbon-loaded polyethylene production insulates margins from petrochemical feedstock volatility. |
| Johor Manufacturing Footprint Expansion | Singapore-Malaysia corridor concentration demands redundant capacity to mitigate port congestion risk. |
| Recyclable Conductive Polymer Development | EU Green Deal extraterritoriality is repositioning Taiwanese fab procurement toward bio-based substrates. |
| Aerospace MRO Channel Qualification | TGA and DGCA airworthiness directives in Australia and India open specialized demand beyond mainstream electronics. |
Research Methodology
Coverage spans East Asia, Southeast Asia, and South Asia, with primary inputs from each region's major electronics manufacturing clusters. The analysis combines structured interviews with semiconductor procurement directors, contract assembler supply chain managers, and ESD packaging distributor principals with secondary validation through SAMR certification databases, JIS standardization bulletins, and BIS phased compliance notifications. Customs records for carbon-loaded polyethylene and conductive foam tray shipments, SEC filings from listed electronics manufacturing services providers, and Taiwan's Hsinchu Science Park investment disclosures anchor quantitative triangulation. Bottom-up demand modeling from individual fab and assembler procurement specifications converges with top-down market sizing from regional electronics production value.
Granularity-level framing applies country-specific certification requirements and end-use contamination thresholds across the modeling period. Segmentation dimensions include packaging type, substrate material, end-user industry, and distribution channel, with additional modeling of dual-certification burden intensity by national regulatory cluster. CAGRs derive from volume trajectory analysis against capacity expansion announcements and qualification timeline compression. Semiconductor node migration patterns and automotive ECU proliferation rates constitute industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt JIS-GB standard divergence or sustained Johor port congestion. Forecasts reflect documented assumptions regarding OEM procurement mandate timing and PLI scheme implementation pace. Material deviation in EU Green Deal enforcement intensity or METI cleanroom threshold updates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market