
 South Korea Electrostatic Discharge (ESD) Trays Market | 2026-2036
South Korea Electrostatic Discharge (ESD) Trays Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Electrostatic Discharge (ESD) Trays Market Insights
Semiconductor OEMs are reorganizing procurement priorities toward custom ESD tray configurations that match advanced packaging geometries. ASE Group leverages backward integration into tray molding to secure captive supply for its test and assembly operations. Daewon anchors domestic production with conductive polymer compounding capabilities that reduce lead times for Korean chipmakers. SHINON differentiates through precision thermoforming expertise serving the laboratory and cleanroom segments.
Electrostatic Discharge (ESD) Trays are thermoformed or injection-molded containers engineered with surface resistivity between 10^3 and 10^11 ohms per square, typically fabricated from carbon-filled polypropylene or polystyrene blends to dissipate static charge during component handling and transport. These trays prevent latent damage to electrostatic-sensitive devices in semiconductor, electronics, and automotive supply chains. Custom Trays command premium positioning due to die-specific cavity designs required by advanced packaging formats like fan-out wafer-level packaging. Polypropylene dominates material selection for its chemical resistance and recyclability, though Conductive PVC retains share in cost-sensitive automotive parts applications where dimensional tolerance demands are less severe.
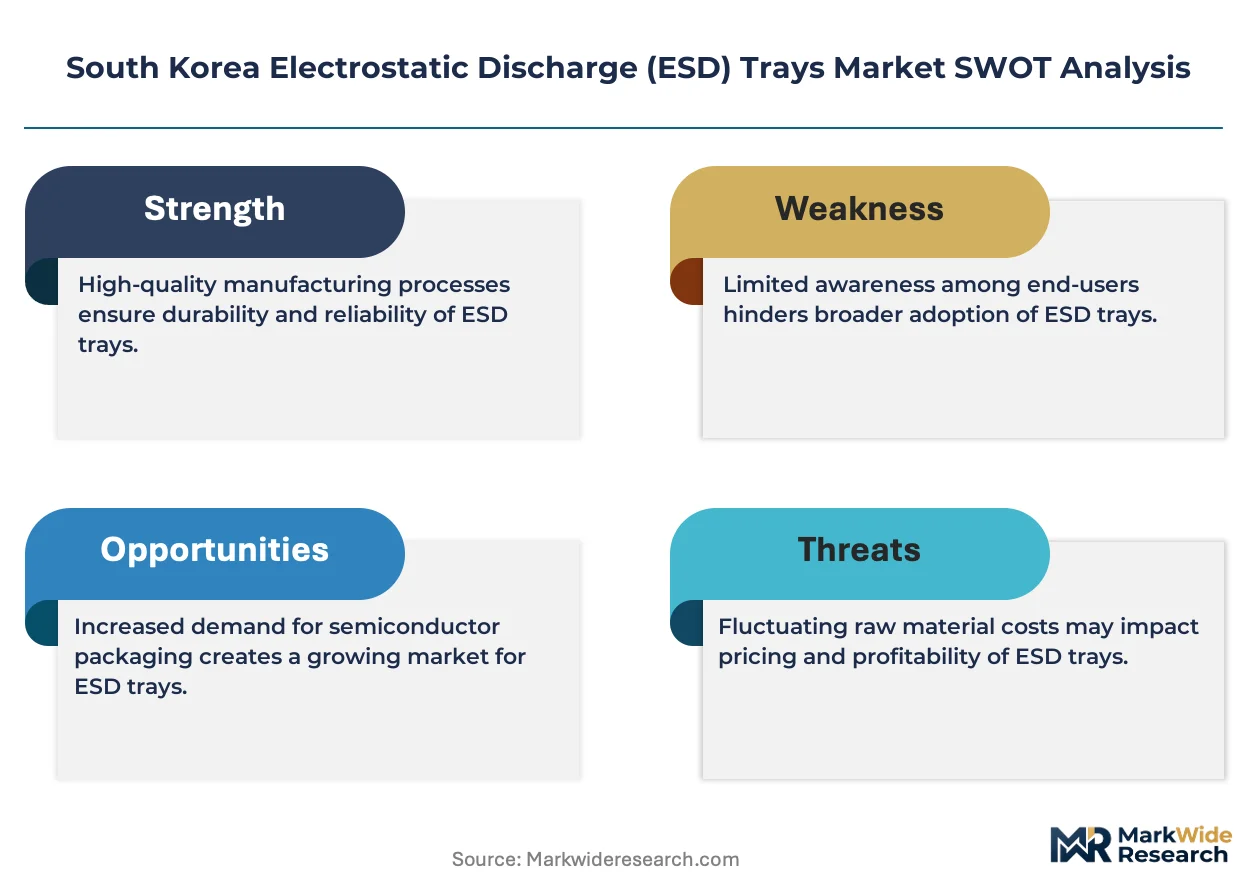
MFDS oversight of cleanroom material biocompatibility and KESD certification requirements shape tray surface property specifications for semiconductor handlers. The Korean Agency for Technology and Standards enforces GB-aligned conductivity testing protocols that filter non-compliant imports from regional competitors. Stakeholders must monitor how chip packaging roadmaps toward 3D stacking and chiplets alter cavity depth and pitch requirements before committing to new tray tooling investments.
Market Dynamics
Advanced packaging geometries in semiconductor manufacturing are compressing tray cavity tolerances below 50 microns, forcing molders to retool thermoforming lines and validate new conductive polymer formulations against KESD conductivity protocols.
Growth Catalysts
- Memory chip packaging expansion:SK Hynix and Samsung Electronics are scaling 3D NAND and HBM production, multiplying wafer-level tray consumption for die protection during stacking operations.
- MFDS cleanroom material mandates:Biocompatibility requirements for semiconductor handling equipment are filtering non-compliant imports and securing domestic tray demand.
- Carbon nanotube doping:Next-generation conductive polymers with enhanced surface resistivity uniformity are penetrating high-precision logic chip applications.
Market Restraints
- Petrochemical input volatility:Polypropylene and polystyrene resin prices fluctuate with naphtha cracking margins, squeezing molder gross margins unpredictably.
- Tooling capex concentration:Custom cavity designs for fan-out wafer-level packaging require aluminum mold investments exceeding $200,000 per configuration, favoring large foundry-aligned suppliers.
- Regional competitor inflow:Chinese thermoformers with GB-aligned conductivity certification are penetrating cost-sensitive automotive segments through price undercutting.
Strategic Opportunities
- Chungcheong Province cluster:Emerging foundry investments outside Seoul's Gyeonggi concentration are creating geographic whitespace for localized tray supply contracts.
- Chiplet packaging formats:Multi-die integration architectures demand novel tray designs with variable cavity depths and thermal management features.
- KESD certification acceleration:Fast-track compliance pathways for domestic molders are shortening qualification cycles versus import competitors.
Industry Challenges
- Precision thermoforming technician scarcity:Korean vocational programs produce insufficient operators capable of calibrating multi-zone heating systems for sub-100-micron tolerance trays.
- Conductivity drift validation:Long-term surface resistivity stability testing under cleanroom cycling conditions extends product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Electrostatic Discharge (ESD) Trays Market |
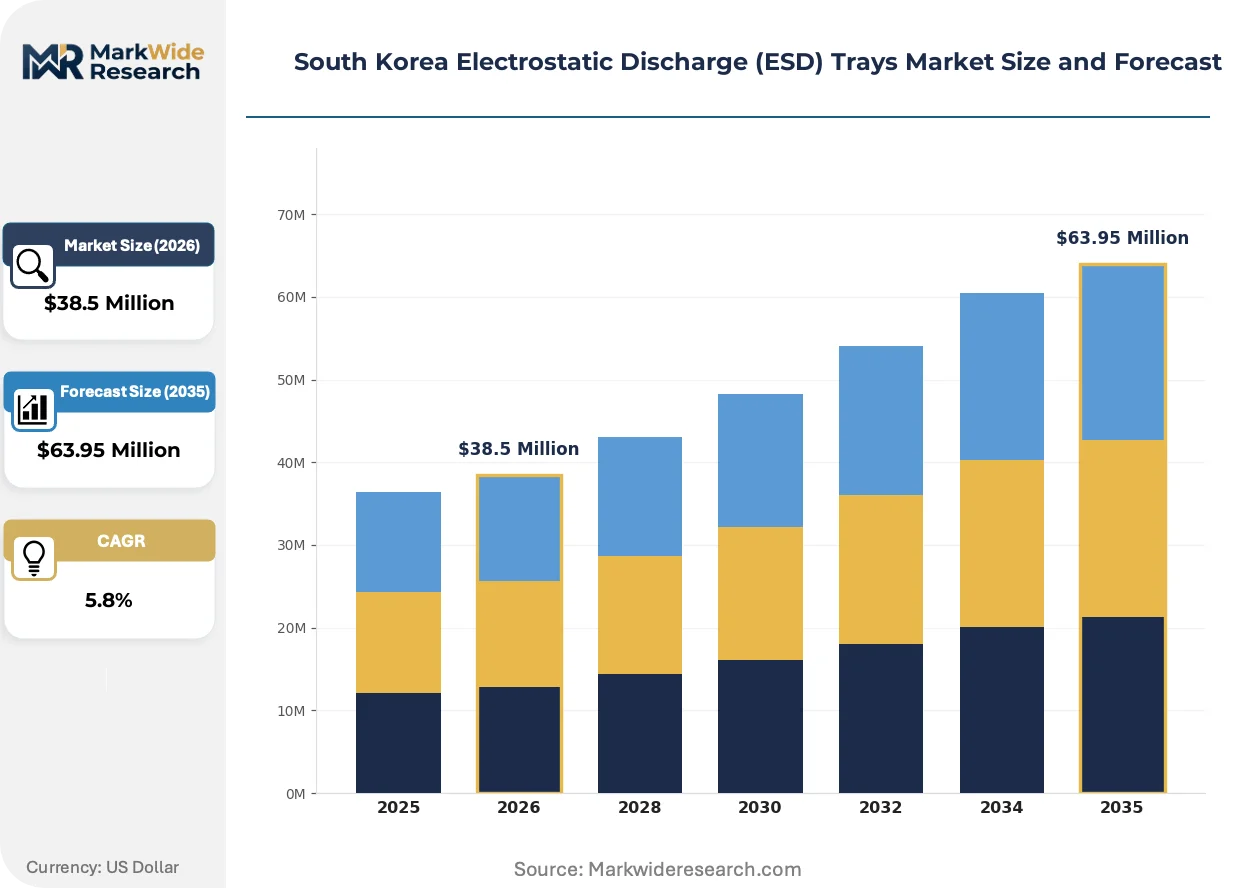
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $63.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Trays, Custom Trays, Stackable Trays, Modular Trays Material: Polypropylene, Polystyrene, Conductive PVC, Anti-static Foam Application: Electronics Manufacturing, Semiconductor Packaging, Automotive Parts, Laboratory Use End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors |
| Companies Covered | ASE Group, Utz Group, Peak International, Daewon, Mishima Kosan, SHINON, TOMOE Engineering, HWA SHU, Sunrise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Electrostatic Discharge (ESD) Trays Market Trends and Innovations
Material science breakthroughs and regulatory tightening are converging to redefine competitive advantage in Korean ESD tray supply, with conductivity precision and cleanroom compliance separating viable suppliers from marginal players.
Multi-walled carbon nanotube (MWCNT) doping is supplanting conventional carbon black loading in premium tray formulations. Samsung's advanced packaging divisions are specifying MWCNT-blended polypropylene for HBM die trays, demanding surface resistivity uniformity within half a decade. This shift is compressing acceptable tolerance bands and disqualifying legacy compounders lacking nanoscale dispersion capabilities.
KESD certification amendments are tightening surface resistivity testing protocols for semiconductor-grade trays. The Korean Agency for Technology and Standards now requires accelerated aging validation under thermal cycling conditions. Domestic molders with in-house conductivity metrology are capturing foundry qualification contracts faster than import-dependent competitors.
Foundry-direct sourcing contracts are displacing distributor-mediated procurement for high-volume tray programs. SK Hynix and Samsung are consolidating suppliers through multi-year molding agreements with cavity exclusivity clauses. This concentration is visible in Gyeonggi Province, where three foundries now contract directly with compounders for captive tray supply.
South Korea Electrostatic Discharge (ESD) Trays Market Segmentation
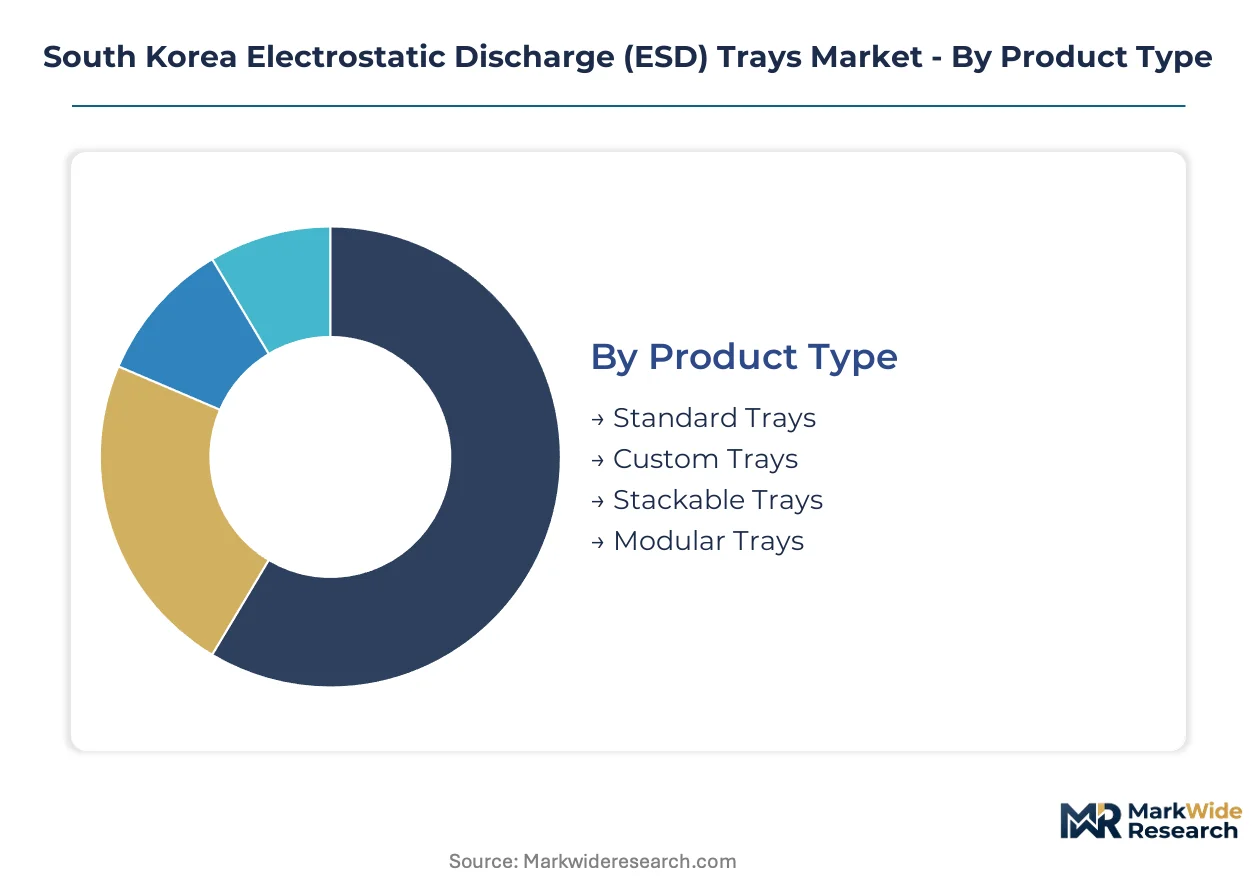
Tray specification choices in South Korea's semiconductor supply chain are tightening around KESD certification requirements and foundry-specific cavity geometries. Material selection and product configuration decisions now flow directly from packaging roadmap demands at Samsung Electronics and SK Hynix facilities.
Product Type:
MFDS cleanroom material mandates and KESD conductivity protocols create divergent compliance burdens across tray configurations, with custom designs facing stricter validation timelines than standardized formats.
- Standard Trays:Injection-molded containers with fixed cavity arrays targeting generic component footprints. Demand concentrates among aftermarket providers serving Gyeonggi Province's smaller electronics subcontractors where die geometries remain standardized.
- Custom Trays:Die-specific thermoformed configurations with cavity tolerances below 50 microns for advanced packaging. Samsung's HBM stacking operations and SK Hynix 3D NAND facilities in Icheon and Cheongju drive specification intensity for fan-out wafer-level packaging compatibility.
- Stackable Trays:Interlocking vertical designs maximizing cleanroom storage density. Tier-1 suppliers adopt these for component staging between assembly stations.
- Modular Trays:Reconfigurable cavity inserts accommodating variable die sizes. Laboratory and cleanroom segments favor adaptability over dedicated tooling investments.
Established volume favors Standard Trays; emerging adoption favors Custom Trays.
Material:
Carbon loading technologies and base resin selection determine surface resistivity stability under thermal cycling, with premium formulations commanding foundry-direct supply contracts.
- Polypropylene:Carbon-filled homopolymer grades dominate semiconductor-grade applications due to chemical resistance and recyclability. Samsung's advanced packaging divisions specify MWCNT-blended variants for HBM die protection, demanding half-decade surface resistivity uniformity.
- Polystyrene:General-purpose conductive blends serve cost-sensitive automotive parts where dimensional tolerances tolerate wider variance. Daewon's compounding capabilities in Ansan reduce lead times for domestic automotive Tier-1s.
- Conductive PVC:Plasticized formulations retain flexibility for irregular component shapes. Automotive wiring harness manufacturers in Ulsan and Changwon source these for connector protection.
- Anti-static Foam:Polyurethane-based cushioning for shock-sensitive laboratory instruments. Cleanroom operators in Daejeon's research clusters specify foam inserts for precision metrology equipment transport.
Polypropylene captures the steepest expansion trajectory as packaging precision requirements intensify.
Application:
End-use concentration in South Korea's semiconductor corridor shapes geographic demand patterns, with packaging facility proximity determining supplier qualification priority.
- Electronics Manufacturing:Surface-mount device handling for consumer electronics assembly. EMS providers in Suwon and Pyeongtaek consume standardized trays for smartphone component logistics.
- Semiconductor Packaging:Wafer-level die protection during stacking and bonding operations. This segment absorbs the majority of custom tray volume as SK Hynix scales HBM3E production and Samsung advances 3D integration roadmaps.
- Automotive Parts:Sensor and control module protection for Hyundai-Kia supply chains. Busan and Gwangju automotive clusters specify Conductive PVC for cost-engineered solutions.
- Laboratory Use:Precision instrument handling in research and metrology environments. SHINON's thermoforming expertise serves KAIST and government research institute procurement.
Semiconductor Packaging commands dominant share; Laboratory Use is climbing the fastest on research infrastructure expansion.
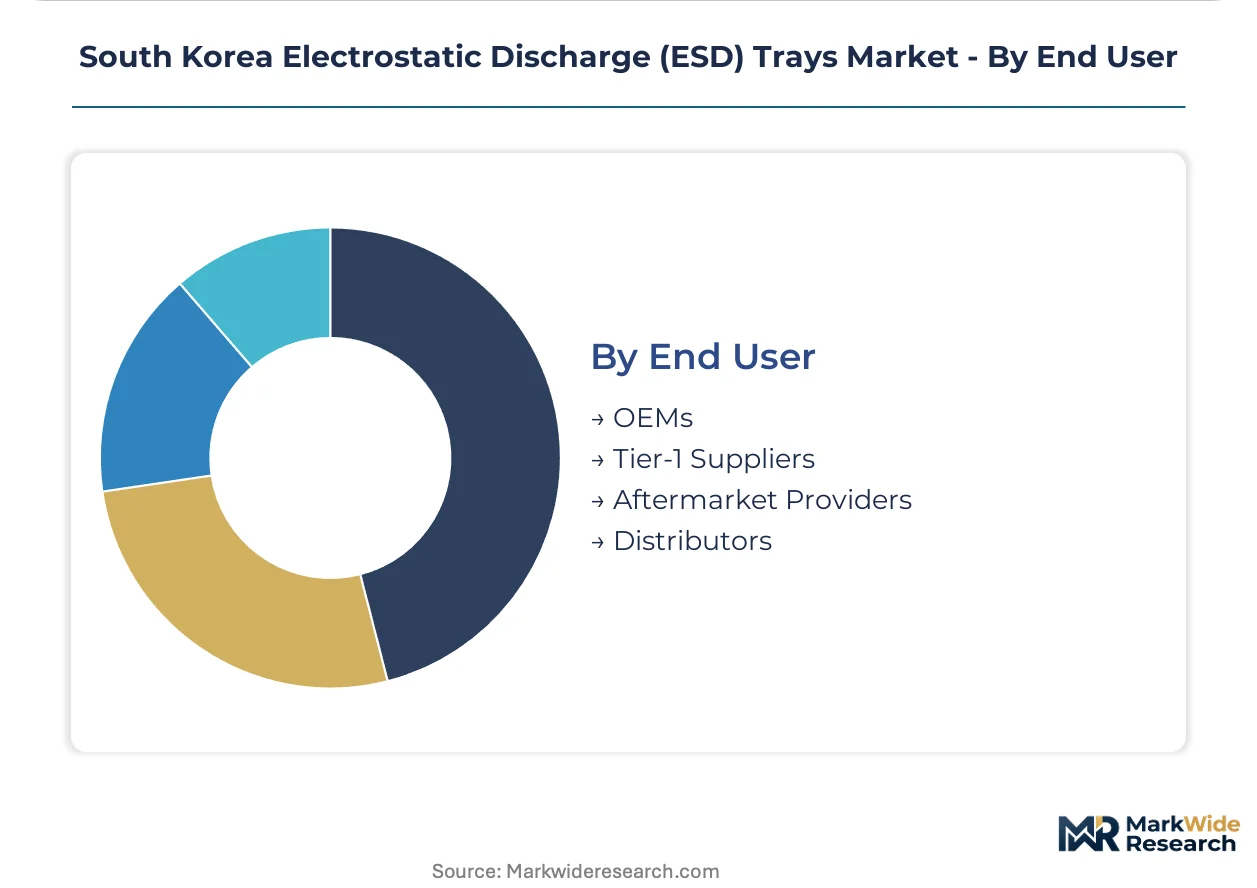
End User:
Procurement centralization patterns separate captive supply arrangements from distributor-mediated fulfillment, with volume scale determining contract structure.
- OEMs:Samsung Electronics and SK Hynix operate foundry-direct sourcing with multi-year molding agreements. Cavity exclusivity clauses lock suppliers into dedicated tooling investments exceeding $200,000 per configuration.
- Tier-1 Suppliers:Hyundai Mobis and LG Innotek maintain approved vendor lists with KESD certification requirements. These intermediaries consolidate tray demand across multiple component programs.
- Aftermarket Providers:Independent distributors serving fragmented electronics repair and refurbishment channels. Price sensitivity drives standard tray preference over custom configurations.
- Distributors:Technical trading houses bridging domestic molders with export-oriented foundries. Chungcheong Province emerging fab investments are creating geographic whitespace for distributor-led supply contracts.
OEMs anchor procurement volume; Distributors are gaining share fastest on geographic expansion outside Gyeonggi concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean ESD tray manufacturers supply semiconductor packaging facilities across East Asia, with export flows concentrated toward Taiwan and China foundry clusters. Domestic consumption anchors volume as Samsung and SK Hynix expand advanced packaging capacity. Sub-regional demand patterns track the geographic dispersion of memory and logic chip fabrication.
Seoul Capital Area
Gyeonggi Province hosts the densest concentration of ESD tray demand, with Samsung's Pyeongtaek and Yongin campuses driving custom cavity specifications for HBM stacking operations. MFDS cleanroom material mandates filter non-compliant imports, securing domestic molder contracts. Icheon's packaging facilities consume premium polypropylene trays with MWCNT doping for die protection during 3D integration.
Busan-Ulsan
Hyundai Motor's Ulsan automotive complex generates steady demand for conductive PVC trays protecting sensor modules and wiring harness connectors. Daewon's Ansan compounding facility reduces lead times for Tier-1 suppliers in this southeastern industrial corridor. The region's port infrastructure supports tray export logistics to Japanese automotive customers.
Daegu-Gyeongbuk
Electronics manufacturing services in Gumi and Pohang consume standardized trays for smartphone component handling. SK Hynix's Cheongju expansion is pulling procurement decisions northward from traditional Seoul-centric patterns. Local vocational programs struggle to supply precision thermoforming technicians for sub-100-micron tolerance production.
Daejeon-Sejong
KAIST and government research institutes anchor laboratory-grade tray demand for precision metrology equipment transport. SHINON's thermoforming expertise serves this cleanroom segment with modular configurations. Sejong's administrative city status attracts distributor operations targeting Chungcheong Province's emerging foundry investments.
Gwangju-Honam
Automotive parts manufacturers in Gwangju and Mokpo source cost-engineered conductive PVC solutions for control module protection. The region's distance from Gyeonggi's semiconductor cluster limits foundry-direct tray procurement. Distributor-mediated fulfillment dominates as volume scale remains below OEM direct contracting thresholds.
South Korea Electrostatic Discharge (ESD) Trays Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification timelines. The vendor base stratifies between foundry-integrated compounders and independent thermoformers serving fragmented aftermarket channels. Three archetypes dominate: captive supply divisions of packaging houses, domestic conductive polymer compounders, and precision thermoforming specialists. Competitive moves concentrate on backward integration into polymer compounding and multi-year molding agreements with cavity exclusivity clauses.
Among packaging-integrated fabricators, ASE Group exemplifies the captive supply archetype through in-house tray molding securing test and assembly operations. Daewon anchors the domestic compounder tier with conductive polymer capabilities reducing Korean chipmaker lead times. SHINON occupies the precision specialist position serving laboratory and cleanroom segments with thermoforming expertise. These three represent distinct strategic postures: vertical capture, material control, and precision differentiation.
| Leading Market Players |
|---|
| ASE Group |
| Utz Group |
| Peak International |
| Daewon |
| Mishima Kosan |
| SHINON |
| TOMOE Engineering |
| HWA SHU |
| Sunrise |
| Others |
Pricing and Supply Chain Analysis
Fourteen-day lead times for MWCNT-blended polypropylene compound delivery from Daewon's Ansan facility concentrate pricing power among domestic molders with captive compounding capabilities, while foundry-direct contracts lock in multi-year volume commitments that insulate premium tray tiers from spot resin volatility.
Pricing Analysis
MWCNT-doped custom tray configurations for HBM3E packaging command substantial premiums over carbon-black-loaded standard trays, with three-tier pricing structure across premium, standard, and economy levels separating foundry-qualified suppliers from automotive-grade molders. Price differentiation hinges on KESD certification tier and cavity tolerance grade, with sub-50-micron precision trays capturing margin expansion while conductive PVC automotive solutions face cost compression from Chinese GB-certified imports. Tier-1 OEM procurement committees exhibit lowest price sensitivity due to die protection failure costs, whereas aftermarket distributors serving Gyeonggi electronics subcontractors prioritize unit economics over performance specifications.
Supply Chain Analysis
Strategic stockpiling of carbon nanotube masterbatch concentrates dominates inventory strategy among qualified compounders, buffering against petrochemical feedstock disruption. Raw material sourcing draws from South Korean naphtha crackers for polypropylene homopolymer, Japanese MWCNT suppliers for conductive additives, and Taiwanese carbon black producers for cost-tier formulations. Single-source vulnerability concentrates in advanced conductive polymer dispersion technology, where qualified Korean compounders number fewer than five qualified suppliers. Distribution runs through foundry-direct contracts for semiconductor-grade volumes, with distributor-mediated fulfillment serving automotive and laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where KESD certification timelines and MFDS cleanroom material validation create switching costs that extend supplier replacement cycles beyond eighteen months.
For Market Incumbents: Shield qualification status by accelerating in-house conductivity metrology investments ahead of amended KESD thermal cycling protocols, while securing aluminum mold tooling exclusivity through multi-year cavity dedication agreements with Samsung and SK Hynix packaging divisions. Chinese thermoformer price undercutting in automotive PVC segments demands channel control reinforcement via Tier-1 supplier approved vendor list consolidation.
For New Entrants and Emerging Players: Rapid qualification services for mid-size foundries represent the most penetrable service-layer gap, as incumbent molders prioritize Samsung and SK Hynix volume commitments over smaller packaging house onboarding. Target Chungcheong Province emerging fab investments with localized molding capacity and fast-track KESD certification support, leveraging geographic whitespace outside Gyeonggi supplier concentration.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because foundry-direct sourcing concentration favors compounders with backward integration into conductive polymer formulation over pure-play thermoformers lacking material science capabilities. Acquisition candidates with MWCNT dispersion expertise and existing Samsung or SK Hynix supply relationships offer strongest positioning. Watch HBM4 packaging roadmap disclosures as inflection indicator for next-generation cavity geometry demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Polymer Compounding | Captive MWCNT formulation capabilities reduce lead times for Korean foundry customers. |
| KESD Certification Fast-Track Investment | Accelerated qualification timelines capture procurement decisions from emerging Chungcheong fabs. |
| Multi-Year Molding Agreement with Cavity Exclusivity | Foundry-direct contracts lock in volume commitments exceeding $200,000 per tooling configuration. |
| Precision Thermoforming Technician Training Program | Domestic vocational pipeline expansion addresses sub-100-micron tolerance operator scarcity. |
| Carbon Nanotube Masterbatch Strategic Stockpile | Inventory buffering against petrochemical input volatility secures compounder margin stability. |
Research Methodology
Desk research of semiconductor packaging equipment databases, Korean Agency for Technology and Standards certification records, and foundry capital expenditure disclosures preceded structured interviews with tray procurement managers at Samsung and SK Hynix, conductive polymer compounders in Ansan and Icheon, and precision thermoforming equipment operators. Secondary validation drew from customs trade data, MFDS cleanroom material compliance filings, and KESD testing protocol documentation. Bottom-up demand modeling from individual packaging facility tray consumption patterns triangulated against top-down market sizing from resin supplier shipment data.
Variance decomposition across product type, material grade, application segment, and end-user procurement structure anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume trajectories weighted by foundry capacity expansion schedules and packaging technology migration patterns. Forecast inputs incorporated HBM stacking layer count roadmaps, 3D NAND die thinning trends, and chiplet integration architectures to model cavity geometry evolution.
Underlying assumptions cover sustained foundry investment in Gyeonggi and Chungcheong provinces, with deviation risk concentrated in petrochemical feedstock cost volatility and Chinese thermoformer certification acceleration. Forecasts reflect these conditions without explicit scenario weighting. Revision becomes warranted when MWCNT dispersion technology licensing crosses thresholds enabling rapid new entrant qualification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market