
 Clear Barrier Films Market | 2026-2036
Clear Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Barrier Films Market Outlook
High-oxygen-barrier specification tiers is bifurcating the competitive landscape as converters separate commodity-grade from performance-grade supply. Amcor Plc leverages its integrated film-to-package pipeline to sustain margin capture across pharmaceutical serialization workflows. DuPont de Nemours Inc. anchors its position through proprietary coextrusion know-how for ethylene vinyl alcohol laminates. Toppan Inc. differentiates via precision deposition barriers that occupy the premium electronics segment in East Asian supply chains.
Clear barrier films are multilayer polymer substrates engineered to block moisture, oxygen, and ultraviolet transmission while maintaining optical clarity, typically manufactured through blown or cast coextrusion with barrier layers of ethylene vinyl alcohol or metallized coatings. These films serve primarily to extend product integrity timelines in sensitive packaged goods. Ethylene vinyl alcohol grades command the deepest technical moats due to their oxygen transmission rates below 1 cc/m²/day, while the food packaging end user category generates the highest absolute volume pull. The 25-50 micron thickness band captures disproportionate margin pools because it balances material efficiency against mechanical durability in form-fill-seal operations.
The EPA regulates volatile organic compound emissions from adhesive lamination processes used in barrier film assembly, while FDA compliance for food-contact substances governs migration limits for multilayer structures. REACH and RoHS frameworks in Europe restrict certain plasticizers and additives, pushing converters toward halogen-free formulations that recertify product lines. Stakeholders must monitor how evolving extended producer responsibility schemes in multiple jurisdictions reshape the economics of multilayer recycling before committing to capacity expansions.
Market Dynamics
Fluorine-free barrier chemistry is decomposing incumbent ethylene vinyl alcohol supply chains as converters retool for EU F-Gas Regulation compliance and REACH-mandated halogen-free formulations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbons in barrier layer manufacturing accelerates capital deployment toward silicon oxide and aluminum oxide deposition technologies across German and Italian converting clusters.
- Pharmaceutical serialization:Track-and-trace mandates for unit-level packaging in the US and EU drive specification upgrades for ultra-high-barrier films with oxygen transmission rates below 0.5 cc/m²/day.
- Active packaging integration:Oxygen scavenger films are penetrating premium fresh protein segments as retailers demand case-ready formats with 21-day shelf-life extension.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Three Japanese and European suppliers control 70% of high-barrier EVOH feedstock, exposing converters to allocation risk during petrochemical turnarounds.
- Metallization energy intensity:Vacuum aluminum deposition requires continuous 10⁻⁴ mbar vacuum maintenance, tying margin performance to regional electricity tariff volatility.
- Multi-layer incompatibility:Current mechanical recycling infrastructure cannot separate EVOH from polyolefin tie layers, forcing reliance on chemical recycling at 3-4x cost premiums.
Strategic Opportunities
- India cold-chain buildout:FSSAI enforcement of temperature-controlled distribution for dairy and vaccines creates first-mover advantage for converters establishing local metallizing capacity.
- Bio-based barrier polymers:Polyhydroxyalkanoate and polylactic acid barrier grades are qualifying for EU Green Deal procurement preferences in fresh produce retail.
- Digital printing convergence:Inkjet-compatible barrier films enable lot-size-one pharmaceutical packaging without plate changeover, compressing converter response times from weeks to hours.
Industry Challenges
- Coextrusion die engineering talent:The scarcity of operators capable of 9+ layer die tuning limits capacity expansion at independent film producers.
- Migration testing timelines:FDA food-contact notification cycles for novel tie-layer adhesives extend 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Barrier Films Market |
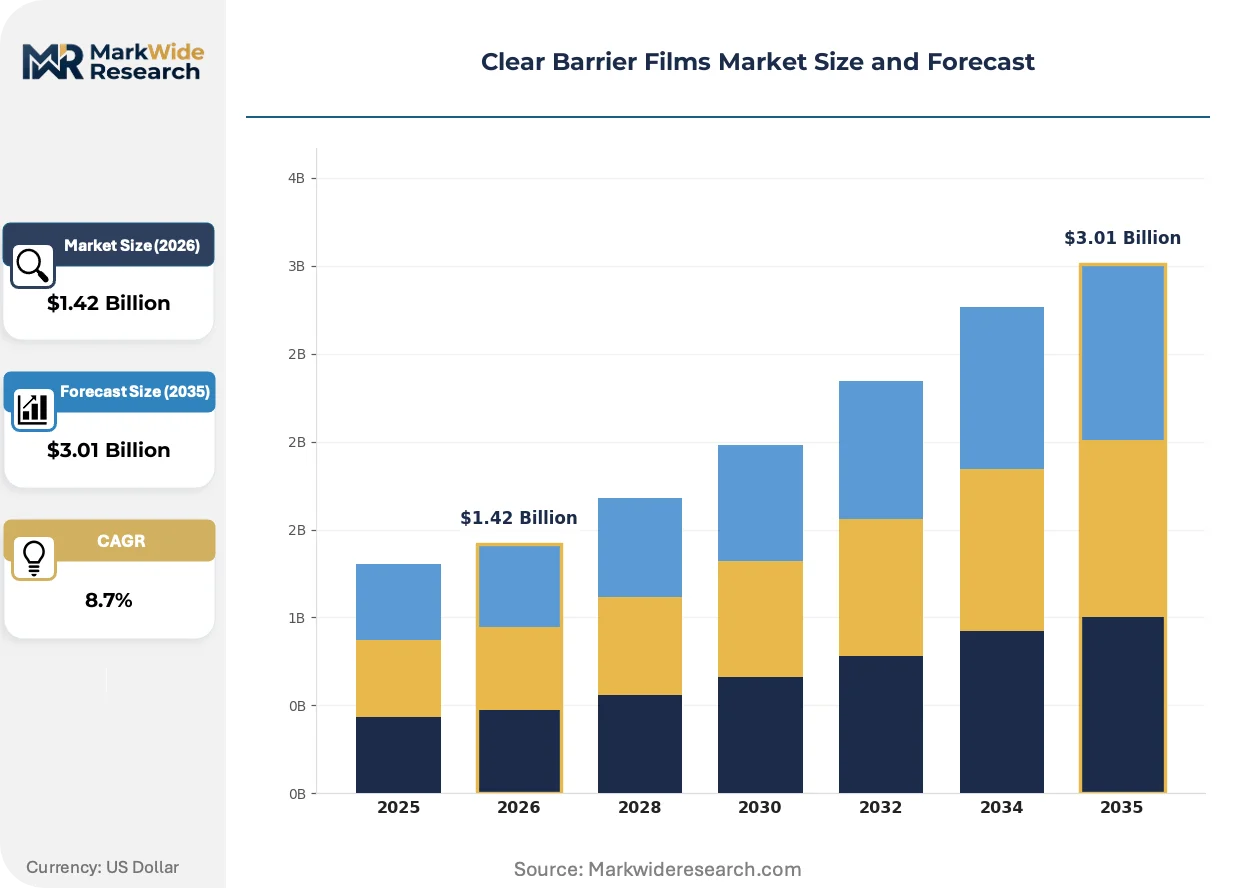
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Ethylene Vinyl Alcohol End User: Food Packaging, Pharmaceutical, Electronics, Consumer Goods Thickness: Below 25 Microns, 25-50 Microns, 50-75 Microns, Above 75 Microns Application: Moisture Barrier, Oxygen Barrier, UV Protection, Shrink Wrap |
| Companies Covered | Amcor Plc, Berry Global Inc., Cosmo Films Ltd., Mondi Plc, Sealed Air Corporation, Toppan Inc., 3M Co., DuPont de Nemours Inc., Glenroy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Barrier Films Market Strategic Shifts
Atomic layer deposition is penetrating flexible packaging as equipment suppliers scale roll-to-roll vacuum chambers from semiconductor wafer dimensions to industrial web widths.
Silicon oxide barrier coatings are decomposing the premium metallized film segment by delivering equivalent oxygen barrier at 40% lower material weight. Pharmaceutical blister pack converters in Switzerland and Germany are qualifying these transparent alternatives for moisture-sensitive solid dose formats. The technology is compressing specification premiums formerly captured by aluminum oxide laminates in East Asian electronics packaging supply chains.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant barrier layers in microwaveable food packaging. ECHA's 2023 restriction proposal covers side-chain fluorinated polymers used in popcorn bags and fast-food wraps. Converters are responding with clay-nanocomposite and bio-wax hybrid barriers that sacrifice some heat resistance for regulatory compliance.
Brand-led sustainability scorecards are reshaping supplier selection criteria beyond unit cost. Nestlé and Unilever procurement teams now weight recyclability design index scores at 25% of total vendor evaluation in Western European flexible packaging tenders. This behavioral shift concentrates volume with converters offering mono-material barrier structures compatible with existing polyethylene recycling streams.
Clear Barrier Films Market Segmentation
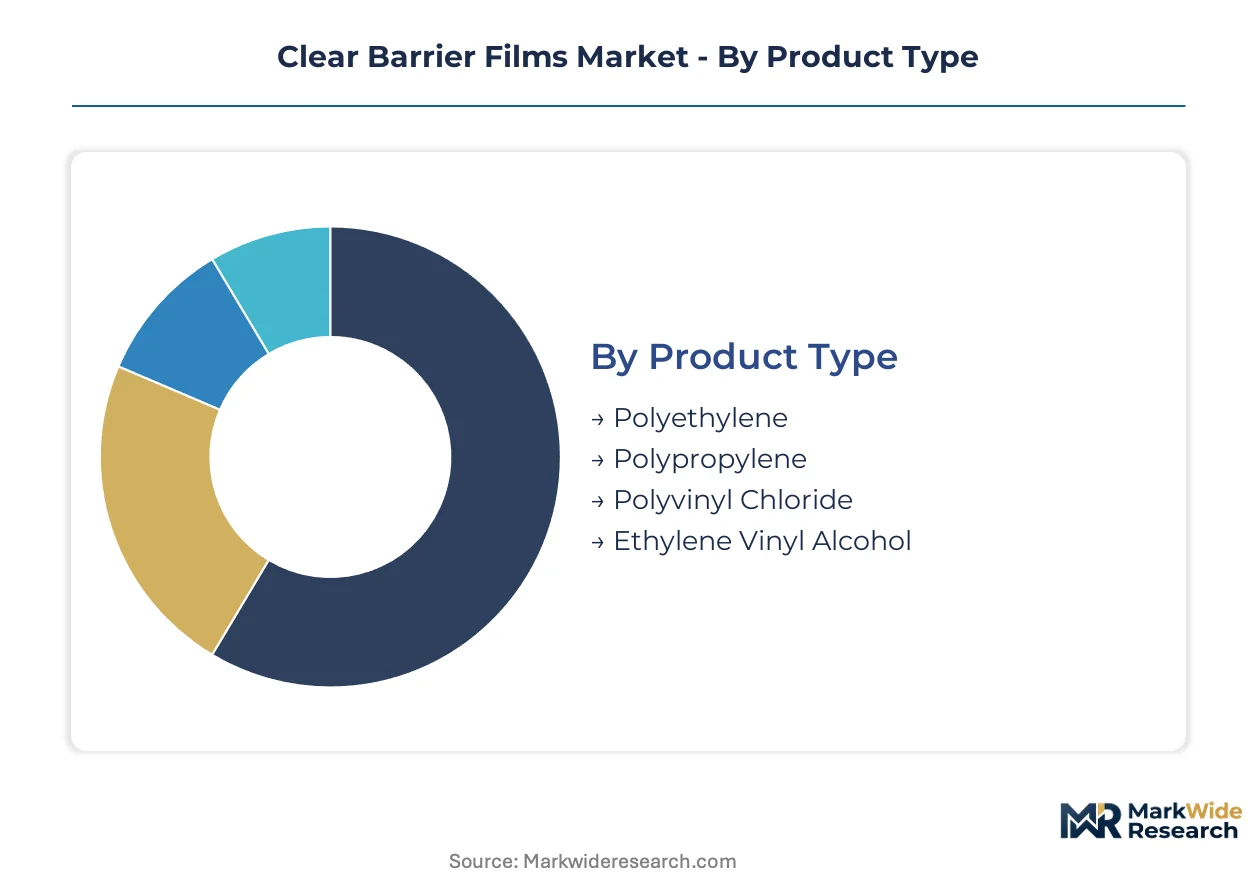
Clear barrier films serve heterogeneous performance requirements across oxygen-sensitive pharmaceuticals, moisture-critical electronics, and shelf-life-extended food formats. Segment boundaries are blurring as silicon oxide coatings displace legacy metallized structures and bio-based polymers qualify for EU Green Deal procurement. Converters must align capacity with specification tiers that separate commodity polyolefin wraps from pharmaceutical-grade ultra-barrier laminates.
Product Type:
Substitution pressure from fluorine-free barrier chemistries is fragmenting incumbent polymer hierarchies as REACH-mandated halogen-free formulations force resin selection changes.
- Polyethylene:Linear low-density grades dominate form-fill-seal operations for frozen food and case-ready meat formats. Demand concentrates in German retail packaging where mono-material polyethylene structures qualify for existing recycling streams under extended producer responsibility schemes.
- Ethylene Vinyl Alcohol:Coextruded EVOH barrier layers deliver oxygen transmission rates below 1 cc/m²/day through 5-7 layer die architectures. Pharmaceutical blister pack converters in Switzerland and Germany specify these grades for moisture-sensitive solid dose formats requiring 24-month stability profiles.
- Polypropylene:Biaxially oriented films serve retort pouch and microwaveable tray lidding applications. Cast film lines in Italy and Spain process these for Mediterranean ready-meal exports.
- Polyvinyl Chloride:Pharmaceutical-grade calendered films persist in unit-dose blister applications despite environmental pressure. Swissmedic-registered converters maintain dedicated PVC lines for legacy drug packaging contracts.
Polyethylene anchors the volume base while Ethylene Vinyl Alcohol gains share at the steepest rate.
End User:
Margin stratification across end-use categories reflects regulatory burden intensity and specification precision requirements.
- Food Packaging:Modified atmosphere packaging for fresh protein and dairy drives the highest absolute tonnage. Retailers in France and the Netherlands mandate 21-day shelf-life extension through oxygen scavenger film integration.
- Pharmaceutical:Track-and-trace serialization mandates in the US and EU drive specification upgrades for ultra-high-barrier films with oxygen transmission rates below 0.5 cc/m²/day. FDA food-contact notification cycles for novel tie-layer adhesives extend 18-24 months.
- Electronics:Flexible circuit and display packaging requires moisture barriers below 0.1 g/m²/day. Precision deposition barriers from Japanese suppliers occupy this premium segment.
- Consumer Goods:Cosmetics and personal care applications prioritize optical clarity and UV protection over oxygen barrier. French and Italian beauty brands drive specification for metallized cosmetic sachets.
Food Packaging generates the largest revenue pool while Pharmaceutical commands the highest unit premiums.
Thickness:
Material efficiency targets are compressing specification bands toward thinner gauges without sacrificing mechanical durability.
- 25-50 Microns:This band captures disproportionate margin pools by balancing material efficiency against form-fill-seal operational reliability. German converting clusters specialize in 9-layer coextrusion dies tuned to this thickness range.
- Below 25 Microns:Ultra-thin gauges serve overwrap and twist-wrap confectionery applications. Japanese equipment suppliers dominate the specialized blown film lines required.
- 50-75 Microns:Heavy-duty laminates for industrial chemical packaging and agricultural film applications. Italian converters process these for Mediterranean horticultural exports.
- Above 75 Microns:Rigid-to-flexible transition structures for medical device packaging and heavy-duty shrink bundling. Swiss pharmaceutical packaging specialists maintain niche capacity.
25-50 Microns dominates current capacity allocation while Below 25 Microns is expanding most quickly.
Application:
Functional specification convergence is blurring traditional application boundaries as multi-barrier films address combined oxygen-moisture-UV requirements.
- Oxygen Barrier:Ethylene vinyl alcohol and metallized coatings prevent oxidative degradation in nut, snack, and pharmaceutical applications. EU F-Gas Regulation compliance is accelerating silicon oxide deposition adoption.
- Moisture Barrier:Aluminum oxide and silicon oxide vacuum-deposited layers protect electronics and hygroscopic pharmaceuticals. German converting clusters lead qualification of transparent alternatives.
- UV Protection:UV-absorbing additive masterbatches and metallized films extend photostability for cosmetics and agricultural chemicals. French beauty packaging drives specification innovation.
- Shrink Wrap:Crosslinked polyolefin films with integrated oxygen barrier serve case-ready meat and poultry. Italian meat processors specify these for export-grade packaging.
Oxygen Barrier holds the largest installed base while Moisture Barrier climbs the fastest on electronics packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clear barrier film manufacturing clusters in Germany, Japan, and the United States concentrate high-barrier coextrusion capacity. German converting hubs around Düsseldorf and Munich supply pharmaceutical-grade laminates across European markets. Japanese precision deposition specialists in Tokyo and Osaka serve electronics packaging demand throughout East Asia.
United States
FDA serialization mandates for pharmaceutical track-and-trace drive ultra-high-barrier film specifications. EPA volatile organic compound regulations govern adhesive lamination processes in converting facilities. New Jersey and Massachusetts pharmaceutical packaging clusters qualify silicon oxide alternatives to metallized structures for moisture-sensitive solid dose formats.
Germany
EU F-Gas Regulation compliance accelerates fluorine-free barrier chemistry adoption across flexible packaging converters. REACH authorization requirements for per- and polyfluoroalkyl substances force reformulation of grease-resistant barrier layers. The Rhine-Ruhr and Bavarian converting clusters specialize in 9-layer coextrusion dies for 25-50 micron pharmaceutical and food packaging laminates.
Japan
PMDA pharmaceutical packaging standards demand oxygen transmission rates below 0.5 cc/m²/day for unit-dose blister applications. METI industrial policy supports atomic layer deposition equipment scaling from semiconductor to packaging web widths. Tokyo and Osaka precision deposition suppliers occupy the premium electronics barrier segment for flexible circuit protection.
Switzerland
Swissmedic-registered converters maintain dedicated capacity for legacy pharmaceutical packaging contracts requiring calendered barrier films. The country's national pharmaceutical regulator enforces stringent migration limits for multilayer food-contact structures. Basel and Zurich packaging specialists supply high-barrier laminates to European pharmaceutical serialization workflows.
India
FSSAI enforcement of temperature-controlled distribution for dairy and vaccines creates demand for metallized barrier capacity. The country's national food safety regulator mandates cold-chain integrity standards that extend shelf-life requirements. Maharashtra and Gujarat emerging converting clusters attract first-mover investment in local vacuum deposition equipment for domestic pharmaceutical packaging.
Clear Barrier Films Market Competitive Environment
Concentration sits with diversified packaging conglomerates and specialized film converters. Three Japanese and European suppliers control the majority of high-barrier EVOH feedstock, exposing independent converters to allocation risk. Strategic archetypes include integrated film-to-package pipelines, precision deposition specialists, and regional coextrusion converters. Competitive moves center on fluorine-free barrier chemistry qualification and pharmaceutical serialization capacity expansion.
Within the integrated packaging tier, Amcor Plc and Berry Global Inc. exemplify scale-driven positions spanning film production through finished package supply. DuPont de Nemours Inc. occupies a technology-licensing archetype rooted in proprietary polymer know-how. Toppan Inc. represents the precision deposition specialist segment serving premium electronics and pharmaceutical applications. These anchors illustrate how competitive positioning fragments across commodity volume, technology licensing, and premium specification tiers.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Cosmo Films Ltd. |
| Mondi Plc |
| Sealed Air Corporation |
| Toppan Inc. |
| 3M Co. |
| DuPont de Nemours Inc. |
| Glenroy Inc. |
| Others |
Value Chain & Pricing Dynamics
Blown film line utilization rates above 85% at German and Japanese coextrusion clusters sustain margin capture for 9-layer barrier laminates while forcing price discipline on commodity-grade polyethylene wraps. This scale asymmetry concentrates pricing power with integrated converters serving pharmaceutical serialization workflows.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European converting clusters. Three-tier pricing structure across pharmaceutical-grade, food-packaging, and industrial-wrap levels separates oxygen transmission rate certifications. Cost compression in commodity polyethylene tiers is intensifying because mono-material recyclability mandates force resin reformulation. Food packaging buyers exhibit highest price sensitivity; pharmaceutical serialization customers accept premium positioning for sub-0.5 cc/m²/day barrier specifications.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes constrains EVOH resin inbound flows to independent converters. Supply concentrates in Japan, Germany, and the United States for high-barrier coextrusion capacity. Feedstock draws from petroleum-based ethylene and vinyl acetate monomer streams, with silicon oxide deposition equipment sourced from Tokyo and Osaka precision engineering specialists. Single-source vulnerability sits with three Japanese and European EVOH resin suppliers controlling 70% of high-barrier feedstock. Distribution runs through converting clusters in Düsseldorf, Munich, and New Jersey before downstream pharmaceutical and food packaging qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical packaging conglomerates and retail-led sustainability procurement coalitions, fragmenting volume allocation across fewer qualified suppliers.
For Market Incumbents: Compound fluorine-free barrier chemistry qualification through silicon oxide deposition capacity additions in Germany and Switzerland. Defend margin position by securing captive EVOH resin offtake agreements before petrochemical turnarounds. Backward integration into metallization equipment maintenance capabilities reduces downtime exposure. For New Entrants and Emerging Players: Lead with India cold-chain buildout as the most penetrable geography, targeting Maharashtra and Gujarat dairy and vaccine packaging demand. Qualify bio-based barrier polymers for EU Green Deal procurement preferences. Establish direct relationships with FSSAI-registered distributors bypassing incumbent converter networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision deposition specialists with atomic layer deposition equipment scaling capabilities. Long-term viability hinges on pharmaceutical serialization compliance infrastructure and fluorine-free formulation pipelines. Acquisition target archetype: regional coextrusion converters with 9-layer die engineering talent and Swissmedic or FDA-registered capacity. Watch silicon oxide qualification timelines at German pharmaceutical blister pack converters as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Barrier Chemistry Qualification | EU F-Gas Regulation compliance secures access to German and Italian converting cluster volumes. |
| Silicon Oxide Deposition Capacity Expansion | Transparent barrier alternatives displace metallized films in Swiss pharmaceutical blister applications. |
| EVOH Resin Offtake Securement | Captive supply agreements mitigate allocation risk during Japanese and European petrochemical turnarounds. |
| India Cold-Chain Metallizing Investment | FSSAI enforcement creates first-mover advantage in Maharashtra and Gujarat vaccine packaging. |
| Pharmaceutical Serialization Compliance Buildout | FDA and EU track-and-trace mandates drive ultra-high-barrier film specification upgrades. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with coextrusion plant managers, pharmaceutical packaging procurement leads, and barrier film R&D directors; and secondary validation through FDA food-contact notification databases, ECHA REACH authorization registers, EU F-Gas Regulation implementation reports, and customs trade flow records. Bottom-up capacity modeling triangulated against top-down pharmaceutical and food packaging demand projections.
Across the analysis window, forecasts integrate polymer grade tier, end-use application, thickness specification, and regional regulatory cluster segmentation. CAGRs derive from elasticity-adjusted demand curves and capacity utilization trajectories at named converting clusters. Forecast inputs include EVOH resin price volatility indices and silicon oxide deposition equipment installation timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement or accelerated REACH per- and polyfluoroalkyl substance restrictions would require recalibration. Forecasts reflect assumptions on pharmaceutical serialization mandate adherence and cold-chain infrastructure buildout pacing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
72 Inch Paint Protection Film Market