
 India Electrostatic Discharge (ESD) Films Market | 2026-2036
India Electrostatic Discharge (ESD) Films Market Size, Share, and Industry Trends Forecast 2026-2036
India Electrostatic Discharge (ESD) Films Market Insights
Asset-light leasing models for cleanroom film converting equipment is fragmenting competitive dynamics in the India ESD films landscape. Uflex Limited leverages its pan-India extrusion footprint to sustain cost advantages in polyethylene-based ESD grades. Polyplex Corporation anchors its position through backward integration into resin compounding, while Cosmo Films Limited differentiates via specialty PET formulations for semiconductor clients.
India Electrostatic Discharge (ESD) Films are multilayer polymer laminates engineered with conductive or dissipative additives, typically surface resistivity between 10^4 and 10^11 ohms per square, manufactured through coextrusion or coating processes to shield sensitive electronic components from electrostatic field damage during handling, transport, and assembly. The primary application spans packaging of integrated circuits, printed circuit boards, and display panels where triboelectric charge buildup risks catastrophic device failure. Polyethylene formulations dominate volume due to cost-efficiency in standard electronics packaging, while PET variants command margin pools in aerospace and semiconductor end uses where optical clarity and thermal stability carry premium value. Thickness segmentation shows 4 mil films capturing the broadest manufacturing adoption, with 6 mil grades growing fastest in automotive sensor protection.
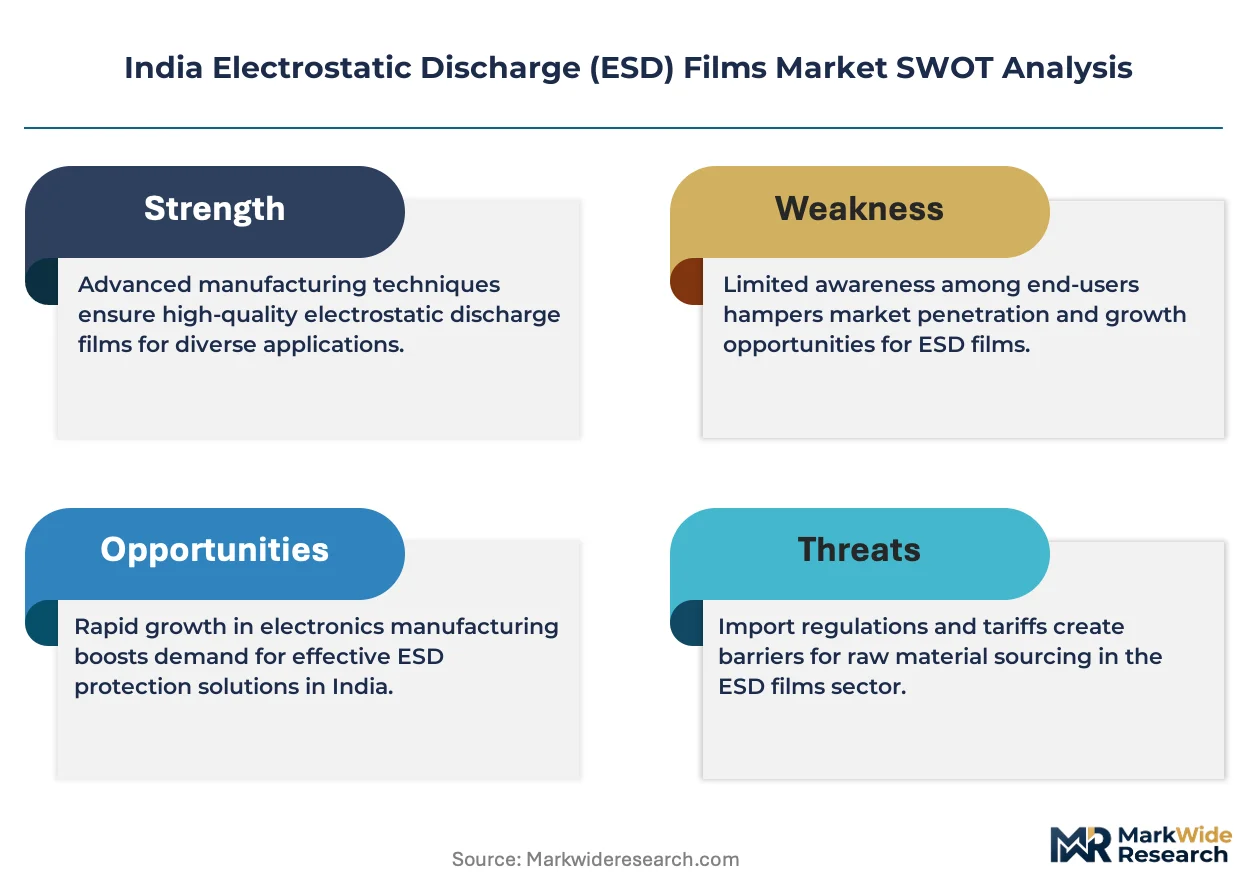
BIS standards for electrostatic control materials, aligned with IEC 61340 series specifications, shape product certification requirements and market access conditions for domestic and imported ESD films. CDSCO and MEITY regulations on medical electronics and telecom hardware manufacturing indirectly amplify ESD compliance obligations across supply chains. Stakeholders must monitor evolving PLI scheme disbursement timelines for electronics manufacturing to calibrate capacity expansion decisions against verified demand signals.
Market Dynamics
Semiconductor fabs in Gujarat and Karnataka are scaling cleanroom packaging procurement faster than domestic film converting capacity can expand, creating a structural supply-demand asymmetry that favors importers with BIS pre-certification.
Growth Catalysts
- PLI scheme disbursements:MEITY's production-linked incentive timelines for electronics manufacturing are accelerating fab construction schedules across Maharashtra and Tamil Nadu.
- BIS certification alignment:Tightening compliance thresholds for electrostatic control materials are locking out uncertified imports and securing market access for qualified domestic producers.
- Triboelectric charge risks:Automotive sensor protection applications in Pune's manufacturing corridor are pulling thicker 6 mil grades into volume production.
Market Restraints
- Resin import dependence:Conductive carbon black and polymer additives concentrate in Southeast Asian supply chains, exposing converters to rupee-denominated cost volatility.
- Cleanroom infrastructure scarcity:Film slitting and converting operations requiring Class 1000 environments cluster in Hyderabad and Bengaluru, limiting geographic diversification.
- Optical clarity tradeoffs:Polyethylene formulations dominate volume but fail aerospace and semiconductor inspection protocols where PET grades command narrow supply.
Strategic Opportunities
- Asset-light leasing models:Equipment-as-a-service arrangements for coextrusion lines are lowering entry barriers for regional converters in Uttar Pradesh and Rajasthan.
- Medical electronics packaging:CDSCO regulations on diagnostic device manufacturing are extending ESD compliance obligations into healthcare supply chains.
- Backward integration pathways:Captive resin compounding investments can secure margin pools currently captured by compounders in Singapore and South Korea.
Industry Challenges
- Cleanroom technician scarcity:Qualified operators for static-controlled manufacturing environments command 40% wage premiums in Karnataka's electronics belt.
- BIS testing timelines:IEC 61340 series certification cycles stretch 14-18 months, delaying product launches for new market entrants.
- Legacy inventory systems:ERP integration with lot-level resistivity tracking remains incomplete across mid-tier packaging distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electrostatic Discharge (ESD) Films Market |
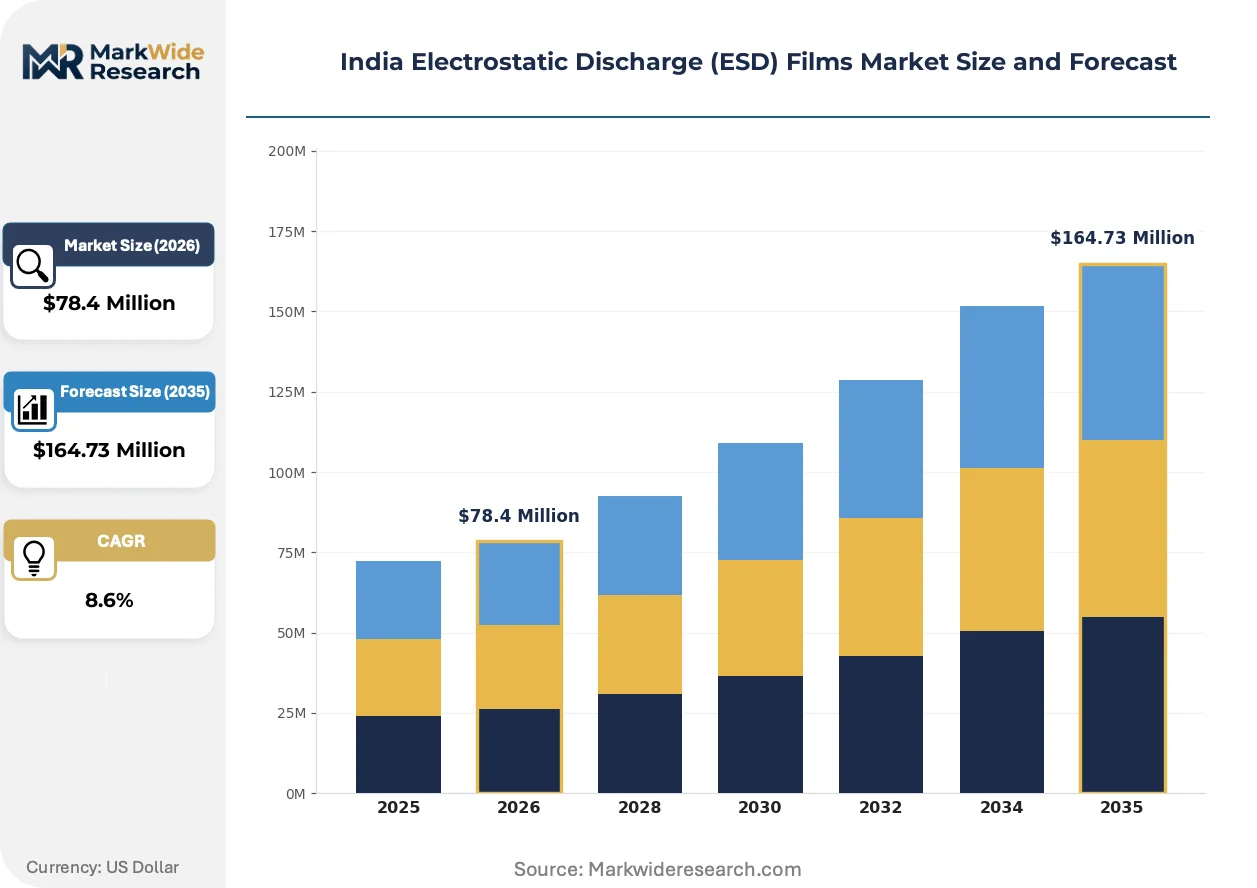
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $164.73 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Packaging, Manufacturing, Electronics, Automotive Thickness: 2 mil, 4 mil, 6 mil, 8 mil End User: Consumer Electronics, Semiconductor, Aerospace, Others |
| Companies Covered | PPG Industries, Uflex Limited, BASF, Polyplex Corporation, Cosmo Films Limited, Smurfit Kappa Group, Techno Stat Industry, Jindal Poly Films, Desco Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electrostatic Discharge (ESD) Films Market Trends and Innovations
Coextrusion technology advances and regulatory harmonization pressures are compressing product development cycles while fragmenting procurement authority across semiconductor supply chains.
Multilayer coextrusion with in-line surface resistivity monitoring is collapsing the distinction between commodity polyethylene grades and specialty formulations. Tier-1 semiconductor packaging houses in Mumbai's electronics corridor are adopting these lines at 18-month replacement cycles. The technology is collapsing margin pools for standard 4 mil films by enabling real-time grade switching without changeover downtime.
BIS standards for electrostatic control materials are tightening alignment with IEC 61340-5-1 specifications for packaging and handling. Domestic testing laboratories in Pune and Chennai are expanding certification capacity to reduce import dependency for validation. Semiconductor fabs in Gujarat are mandating dual-certification (BIS plus IEC) for critical wafer shipment packaging, compressing supplier qualification timelines.
Consolidated procurement desks at electronics manufacturing services firms are displacing decentralized buying by individual fab managers. Maharashtra's contract manufacturers are centralizing film specifications across multiple cleanroom sites to leverage volume pricing. The shift is most visible in Pune's automotive electronics cluster, where tier-1 suppliers now specify ESD grades at the OEM level rather than at individual plant purchasing departments.
India Electrostatic Discharge (ESD) Films Market Segmentation
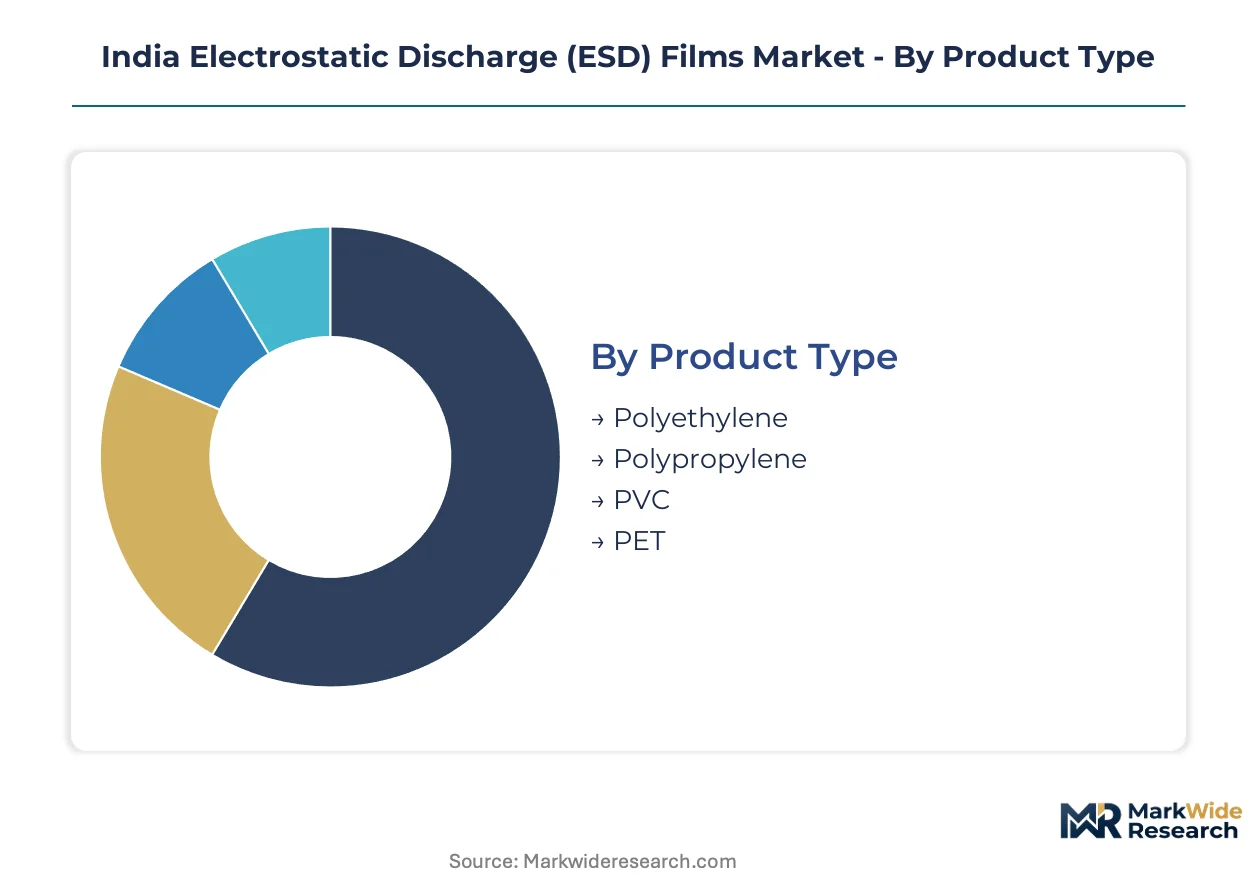
ESD film specifications diverge sharply across India's electronics manufacturing corridor. Material chemistry, thickness tolerances, and end-use certification requirements create distinct procurement silos that converters must navigate simultaneously.
Product Type:
Mature commodity grades dominate procurement volumes while specialty formulations carve defensible margin positions in semiconductor and aerospace channels.
- Polyethylene:Multilayer coextruded formulations with carbon black or metallic filler loadings achieve surface resistivity between 10^4 and 10^11 ohms per square. Maharashtra's contract electronics manufacturers in Pune and Mumbai specify this grade for standard IC and PCB packaging where optical clarity requirements remain minimal.
- PET:Biaxially oriented polyester films with vapor-deposited or coextruded conductive layers deliver thermal stability above 150°C and transmission rates exceeding 85%. Gujarat's semiconductor fabs mandate PET for wafer-level shipment packaging where automated optical inspection protocols reject hazy polyethylene alternatives.
- Polypropylene:Oriented PP grades with dissipative coatings serve moisture-sensitive applications in Tamil Nadu's humid coastal manufacturing zones.
- PVC:Plasticized formulations with inherent conductivity find niche use in temporary protective covers for automotive sensor modules during Karnataka assembly operations.
Polyethylene handles the majority of throughput; PET is the fastest mover on share.
Application:
Procurement authority concentrates at the OEM level rather than individual plant purchasing desks, compressing supplier qualification timelines across Maharashtra's electronics corridor.
- Packaging:Static-dissipative bags, tubing, and stretch films for integrated circuit transport represent the largest volume application. Tamil Nadu's contract manufacturers specify BIS-certified grades for export shipments to ASEAN electronics assembly hubs.
- Electronics:Cleanroom-compatible films for wafer dicing frames and die-attach processes command premium pricing. Karnataka's fab expansion schedules are pulling 6 mil and 8 mil grades into volume production faster than domestic converting capacity can expand.
- Manufacturing:Workstation mats and process trays for assembly line ESD protection serve mid-tier automotive electronics suppliers in Pune's manufacturing belt.
- Automotive:Sensor module protection during powertrain assembly integrates with ADAS component manufacturing schedules across Gujarat and Tamil Nadu.
Packaging absorbs the greatest film tonnage; electronics applications are expanding most quickly as fab construction accelerates.
Thickness:
Thickness selection maps directly to mechanical protection requirements and automated handling compatibility across India's heterogeneous electronics manufacturing base.
- 4 mil:The workhorse specification balances puncture resistance with heat-seal throughput in high-volume bag converting operations. Maharashtra's packaging houses specify this grade for standard IC tubes and carrier tapes.
- 6 mil:Thicker gauges with enhanced puncture resistance serve automotive sensor modules and medical electronics where shipping damage carries catastrophic failure costs. Pune's tier-1 automotive suppliers are mandating this specification at the OEM level.
- 2 mil:Ultra-thin grades for cost-sensitive consumer electronics packaging where single-trip protection suffices.
- 8 mil:Heavy-duty specifications for aerospace component shipment and reusable tote systems in semiconductor tool logistics.
4 mil films command the broadest manufacturing adoption; 6 mil grades are gaining share fastest in automotive sensor protection.
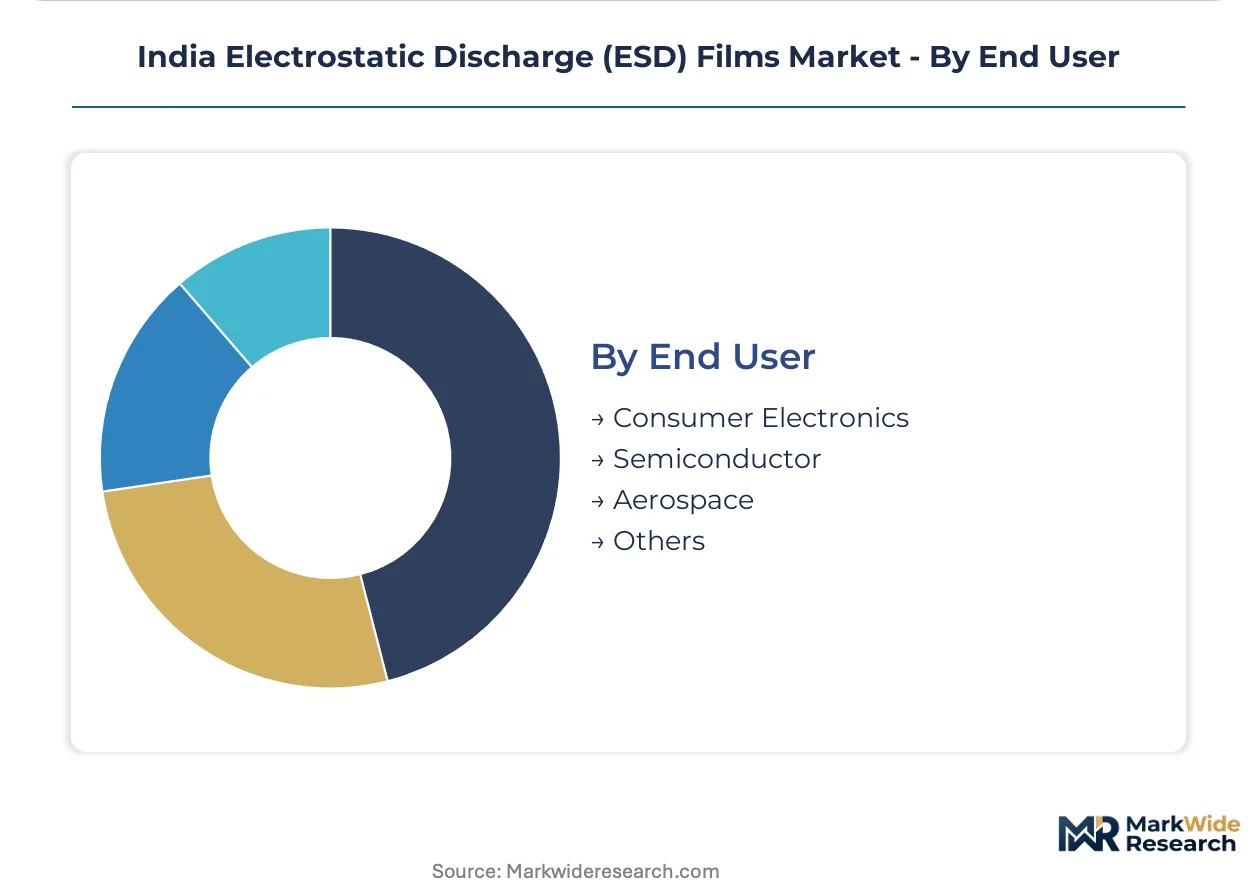
End User:
Certification stringency fragments procurement requirements across India's electronics value chain, with semiconductor and aerospace channels imposing qualification barriers that commodity converters cannot surmount.
- Semiconductor:Wafer-level packaging requires dual BIS and IEC 61340-5-1 certification with lot-level resistivity traceability. Gujarat's new fabs are mandating domestic sourcing for critical shipment packaging, compressing supplier qualification timelines.
- Consumer Electronics:High-volume, price-sensitive procurement for smartphone and laptop component packaging concentrates in Tamil Nadu's contract manufacturing clusters.
- Aerospace:MIL-PRF-81705 and AS9137 compliance requirements limit qualified suppliers to converters with dedicated cleanroom slitting capacity in Hyderabad and Bengaluru.
- Others:Medical electronics and telecom hardware applications extend ESD compliance obligations through CDSCO and MEITY regulatory channels.
Consumer electronics channels move the greatest film volume; semiconductor end users are climbing the fastest on procurement value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEITY's PLI scheme disbursements are accelerating fab construction schedules across Maharashtra and Tamil Nadu, concentrating ESD film procurement in western and southern industrial corridors. BIS certification mandates are tightening compliance thresholds, locking out uncertified imports and securing market access for qualified domestic producers.
Maharashtra
Pune's automotive electronics cluster and Mumbai's contract manufacturing corridor drive demand for 4 mil and 6 mil polyethylene grades. BIS standards for electrostatic control materials shape product certification requirements for packaging houses serving export markets. Maharashtra's electronics manufacturing belt concentrates procurement authority at OEM level, compressing supplier qualification timelines.
Gujarat
New semiconductor fabs in Ahmedabad and Gandhinagar mandate dual BIS and IEC 61340-5-1 certification for critical wafer shipment packaging. CDSCO regulations on medical electronics manufacturing extend ESD compliance obligations into diagnostic device supply chains. Cleanroom infrastructure scarcity limits film slitting and converting operations to select industrial zones.
Karnataka
Bengaluru's fab expansion schedules pull thicker 6 mil and 8 mil grades into volume production faster than domestic converting capacity can expand. MEITY's production-linked incentive timelines accelerate cleanroom packaging procurement from qualified vendors. Qualified operators for static-controlled manufacturing environments command wage premiums in the state's electronics belt.
Tamil Nadu
Contract manufacturers in Chennai's coastal clusters specify BIS-certified grades for export shipments to ASEAN electronics assembly hubs. Humid coastal conditions favor oriented polypropylene grades with dissipative coatings for moisture-sensitive applications. PLI scheme disbursements for electronics manufacturing are accelerating capacity expansion decisions.
Telangana
Hyderabad's concentrated cleanroom slitting and converting operations serve as a hub for aerospace and semiconductor packaging requirements. Class 1000 environments for film processing cluster in the city, limiting geographic diversification of supply. CDSCO and MEITY regulations on telecom hardware manufacturing amplify ESD compliance obligations across regional supply chains.
India Electrostatic Discharge (ESD) Films Market Competitive Landscape
On the supply side, the industry is consolidating around converters with BIS pre-certification and captive cleanroom infrastructure. Asset-light leasing models for coextrusion equipment are fragmenting competitive dynamics by lowering entry barriers for regional players. Three archetypes dominate: integrated resin compounders with backward control, specialty PET formulators serving semiconductor channels, and scale-driven polyethylene converters. Dominant competitive moves include strategic partnerships with fab operators and portfolio diversification into medical electronics packaging.
Among India-based flexible packaging specialists, Uflex Limited, Polyplex Corporation, and Cosmo Films Limited occupy distinct positioning vectors. Uflex exemplifies the scale-driven archetype through its pan-India extrusion footprint. Polyplex represents converters anchoring position through upstream resin compounding capabilities. Cosmo Films sits within the specialty tier, differentiating via material science capabilities for premium semiconductor applications. These three entities collectively illustrate the competitive tension between volume efficiency and technical specification depth that defines supplier selection in Gujarat's fab procurement desks.
| Leading Market Players |
|---|
| PPG Industries |
| Uflex Limited |
| BASF |
| Polyplex Corporation |
| Cosmo Films Limited |
| Smurfit Kappa Group |
| Techno Stat Industry |
| Jindal Poly Films |
| Desco Industries |
| Others |
Pricing and Supply Chain Analysis
Rupee-denominated volatility in conductive carbon black imports from Southeast Asian compounders compresses margin pools across polyethylene grades while simultaneously forcing domestic converters toward BIS-certified PET formulations that command wider pricing spreads. This currency exposure shapes procurement behavior across Maharashtra's electronics corridor, where OEMs now specify dual-certified grades to hedge against supply disruption premiums.
Pricing Analysis
Certification level creates the primary spread between commodity polyethylene and specialty PET grades, with BIS-plus-IEC dual certification adding substantial premiums over single-standard alternatives. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade PET from automotive-specification polyethylene and undifferentiated consumer electronics films. Cost compression in standard 4 mil polyethylene runs through rupee depreciation against resin import invoices, while margins are tightening for uncertified converters locked out of Gujarat fab procurement desks. Consumer electronics contract manufacturers in Tamil Nadu exhibit highest price sensitivity, whereas semiconductor packaging houses in Ahmedabad demonstrate lowest sensitivity due to catastrophic failure costs from ESD damage.
Supply Chain Analysis
Tariff exposure between India and Singaporean resin compounders dominates supply chain risk calculations for domestic film converters. Raw material sourcing draws from Singapore and South Korea for conductive additives, with domestic polyethylene resin production anchored in Gujarat and Maharashtra. Single-source vulnerability concentrates in carbon black masterbatch supply, where three Southeast Asian compounders control qualified formulations for BIS-certified grades. Distribution runs through Hyderabad and Bengaluru cleanroom slitting hubs before final delivery to fab operators, with limited geographic diversification creating logistics chokepoints during monsoon disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India ESD Films Market functions as a regulatory entrenchment story where BIS certification timelines create switching costs that protect qualified incumbents from import competition. Network effects consolidate procurement authority at OEM level, compressing supplier rosters and deepening moats for pre-certified domestic producers.
For Market Incumbents: Harden certification moats through captive testing laboratory investments in Pune and Chennai, reducing BIS validation cycles from 18 months toward 12-month competitive benchmarks. Expand cleanroom slitting capacity in Uttar Pradesh and Rajasthan to capture asset-light regional converters before they achieve scale, while monitoring emerging entrant activity in medical electronics packaging where CDSCO regulations are extending compliance obligations. For New Entrants and Emerging Players: Asset-light equipment leasing arrangements for coextrusion lines in Rajasthan and Uttar Pradesh represent the most penetrable entry point, enabling BIS certification pursuit without capital-intensive cleanroom infrastructure ownership. Medical electronics packaging for diagnostic device manufacturers offers secondary white-space, with CDSCO regulatory tailwinds amplifying ESD compliance requirements beyond traditional semiconductor channels. Go-to-market positioning should emphasize lot-level resistivity traceability systems that mid-tier distributors currently lack. For Investors and Strategic Acquirers: Specialty PET formulators with existing dual BIS-IEC certification and established Gujarat fab relationships present the most attractive acquisition archetype, given semiconductor procurement value growth and limited qualified supplier pools. Long-term viability hinges on backward integration into resin compounding to capture margin pools currently exported to Singapore and South Korea. Monitor PLI scheme disbursement timelines for electronics manufacturing as the critical inflection signal for capacity expansion decisions against verified demand.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Dual BIS-IEC qualification unlocks Gujarat semiconductor fab procurement desks and commands pricing premiums. |
| Backward Integration into Resin Compounding | Captive additive formulation reduces rupee exposure to Singaporean compounders and secures margin pools. |
| Cleanroom Infrastructure Expansion | Class 1000 slitting capacity in underserved states captures regional converter growth before asset-light entrants scale. |
| Medical Electronics Packaging Diversification | CDSCO regulatory extensions into diagnostic devices amplify addressable market beyond semiconductor channels. |
| Lot-Level Resistivity Tracking Systems | ERP integration with traceability protocols addresses legacy inventory gaps across mid-tier packaging distributors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cleanroom packaging procurement managers at Gujarat semiconductor fabs, film converting plant managers in Maharashtra and Karnataka, and BIS certification laboratory directors in Pune and Chennai. Secondary validation drew from BIS notification records, CDSCO medical device manufacturing guidelines, MEITY PLI scheme disbursement documentation, and customs import data for conductive carbon black formulations. Bottom-up demand estimates from individual fab expansion schedules were triangulated against top-down market sizing from extrusion capacity utilization rates across domestic converters.
Calibration approaches anchored volume projections to verified cleanroom packaging procurement timelines at semiconductor construction sites across Gujarat and Tamil Nadu, with value estimates reflecting grade-specific pricing spreads between polyethylene and PET formulations. Segmentation modeling incorporated material chemistry tiers, thickness specifications, end-use certification requirements, and regional manufacturing cluster density. CAGRs were derived from slope analysis of annual procurement value trajectories, with cross-validation against resin import volume trends and BIS certification issuance rates for electrostatic control materials.
Practitioners should monitor rupee volatility against Southeast Asian currencies, PLI scheme disbursement acceleration or delays, and BIS testing laboratory capacity expansion for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market