
 Electrostatic Discharge (ESD) Packaging Market | 2026-2036
Electrostatic Discharge (ESD) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Electrostatic Discharge (ESD) Packaging Market Analysis
The EU Green Deal is rebalancing material specifications across European electronics supply chains, compelling packaging converters to eliminate halogenated additives from ESD formulations. DS Smith leverages its corrugated fiberboard R&D network to develop paper-based static-dissipative alternatives for automotive module shipments. Smurfit Kappa Group anchors volume production through its integrated European containerboard mills, sustaining cost advantages in tray and box segments. Nefab Group specializes in returnable ESD container programs for aerospace OEMs, differentiating through lifecycle logistics rather than disposable unit sales.
Electrostatic Discharge (ESD) Packaging comprises engineered materials and structures designed to prevent electrostatic field buildup or sudden charge transfer that damages sensitive electronic components, typically incorporating surface resistivities between 10^3 and 10^11 ohms per square through conductive, dissipative, or shielding layer constructions. Bags manufactured from multi-layer polyethylene with embedded carbon or metalized films dominate unit volume due to semiconductor wafer and memory chip shipping requirements, while conductive foam trays command premium positioning for precision component nesting in automated assembly lines. Polypropylene formulations are displacing PVC in healthcare device packaging as medical OEMs phase out plasticizers under biocompatibility protocols, and direct sales channels retain margin concentration by locking in multi-year supply agreements with tier-one electronics contract manufacturers.
FDA device packaging guidelines, EPA hazardous substance reporting under TSCA, and ISO 11197 standards for medical electrical equipment collectively shape material selection and validation protocols for ESD packaging entering regulated end uses. REACH substance restrictions and RoHS hazardous material limits constrain additive chemistries available to European compounders, while China's GB standards for electronic product environmental protection create parallel certification burdens for imports. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these jurisdictions draft packaging waste rules that could reclassify conductive additives as hazardous contaminants, forcing reformulation investments ahead of regulatory finalization.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are expanding cleanroom packaging procurement, pulling ESD material specifications toward higher-performance multi-layer laminates with embedded carbon mesh shielding layers.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance mandates are pushing converters toward halogen-free conductive formulations, expanding addressable market for bio-based dissipative polymers in European electronics corridors.
- Healthcare device packaging:Medical OEMs are phasing out PVC plasticizers under biocompatibility protocols, creating specification windows for polypropylene ESD formulations in diagnostic equipment shipments.
- Yangtze River Delta electronics manufacturing:China's concentrated electronics corridor is generating sustained procurement volumes for wafer-level ESD bags and conductive foam nesting systems.
Market Restraints
- Carbon black supply concentration:Conductive additive production clusters in select Asian chemical processing zones, exposing compounders to input cost volatility and freight surcharge exposure.
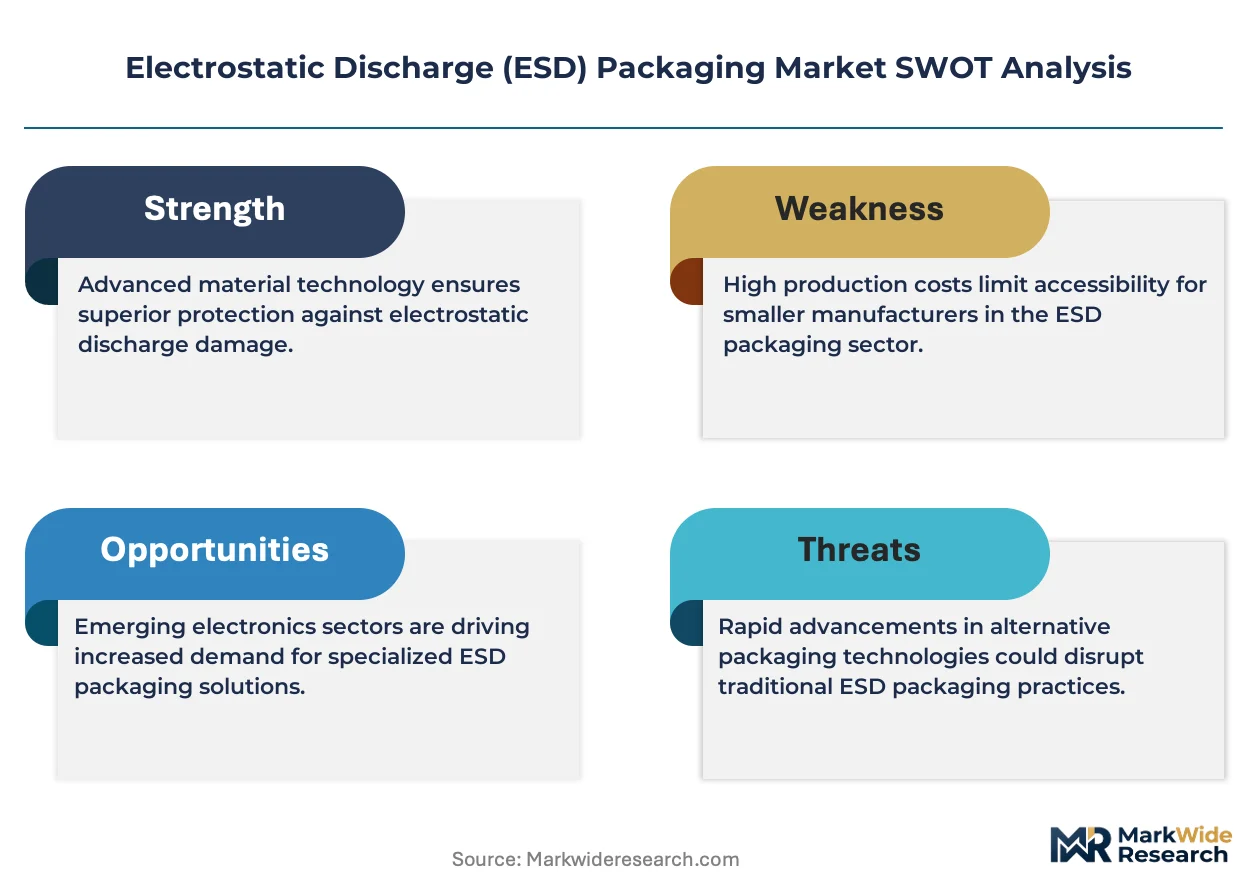
- REACH substance restrictions:ECHA's evolving candidate list constrains additive chemistries available to European compounders, forcing reformulation cycles that compress margin recovery timelines.
- Metalized film substitution:Vacuum-deposited aluminum barriers in flexible packaging are capturing share in lower-sensitivity electronics segments where full Faraday cage protection is overspecified.
Strategic Opportunities
- Returnable container programs:Aerospace OEMs in Germany and France are adopting lifecycle logistics models for precision avionics modules, shifting revenue from disposable units to pooled asset management fees.
- Automotive module shipments:EV battery management systems and ADAS sensor clusters require ESD-protected transit packaging with vibration damping, opening specification windows for fiberboard-based static-dissipative alternatives.
- Extended producer responsibility laws:California and New York state-level packaging waste rules are forcing reformulation investments ahead of finalization, creating first-mover advantages for halogen-free compounders.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 compliance validation for ESD packaging production environments extends facility qualification periods, delaying capacity ramp schedules.
- Multi-standard harmonization:Concurrent GB standards, RoHS limits, and FDA device packaging guidelines create overlapping testing burdens that fragment quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrostatic Discharge (ESD) Packaging Market |
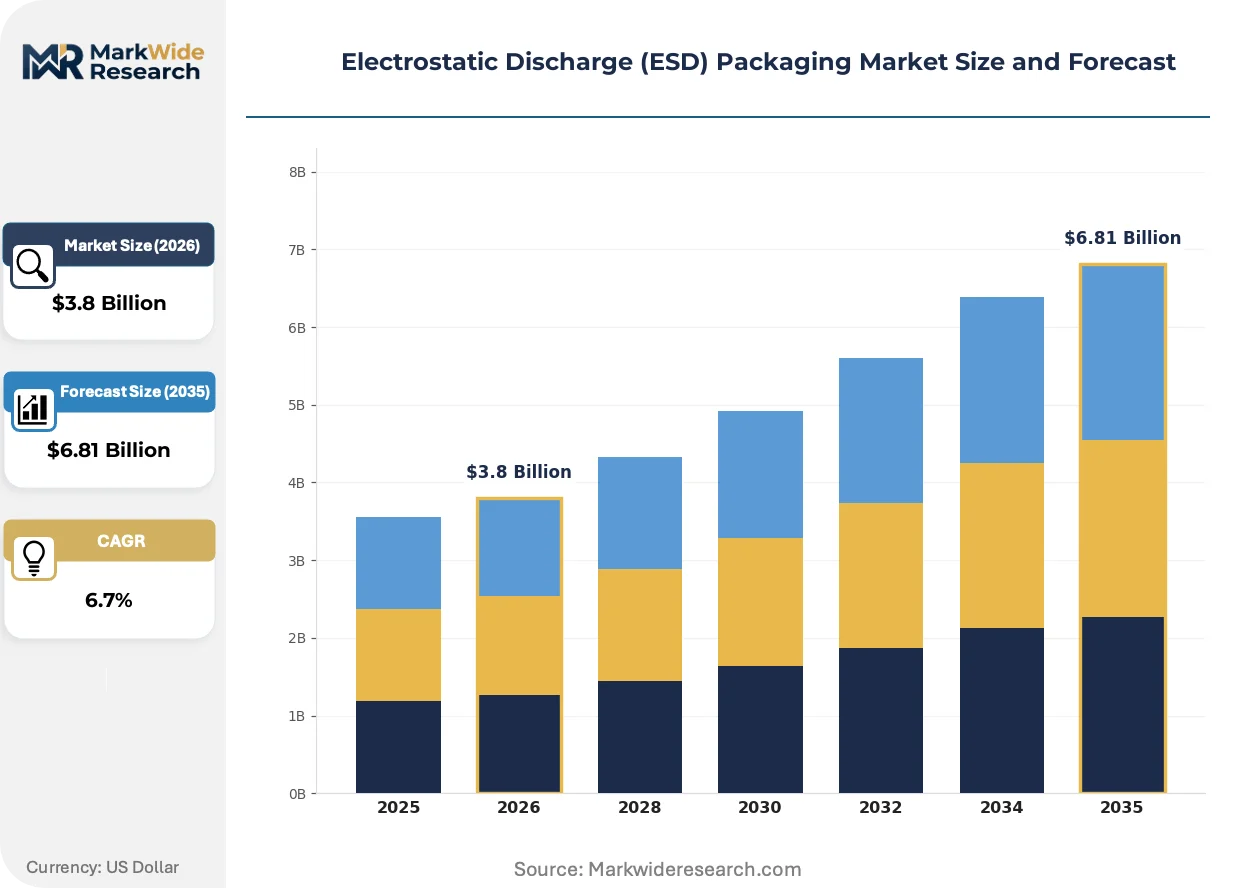
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Trays, Boxes Material: Polyethylene, Polypropylene, PVC, Conductive Foam End User: Electronics, Automotive, Aerospace, Healthcare Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | DS Smith, GWP Group, Desco Industries, Elcom Ltd., Teknis Limited, Smurfit Kappa Group, Nefab Group, Delphon Industries, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrostatic Discharge (ESD) Packaging Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to reshape how static protection is engineered into packaging architectures across electronics supply chains.
Multi-layer polyethylene formulations with tunable surface resistivity are modularizing how semiconductor manufacturers specify protection tiers. Wafer fabs in Hsinchu and Pyeongtaek are adopting standardized layer-stack configurations that separate shielding, dissipative, and abrasion-resistant functions into interchangeable film combinations. This architecture is modularizing procurement patterns, allowing buyers to mix performance grades without redesigning entire packaging systems.
REACH substance restrictions and RoHS hazardous material limits are eliminating legacy brominated flame retardants from European ESD compound formulations. German and Dutch packaging converters are accelerating qualification of phosphorus-nitrogen intumescent systems that maintain volume resistivity targets. Medical device exports to the EU are most affected, with contract manufacturers demanding pre-certified material streams to avoid customs detention at Rotterdam and Hamburg.
Direct sales channels with multi-year supply agreements are displacing spot-market purchasing for tier-one electronics contract manufacturers. Foxconn and Pegatron procurement teams are consolidating vendor panels to lock in volume pricing and dedicated production slots. This concentration is most visible in Taiwan and South Korea, where semiconductor packaging houses are trading price transparency for supply security in volatile resin markets.
Electrostatic Discharge (ESD) Packaging Market Segmentation
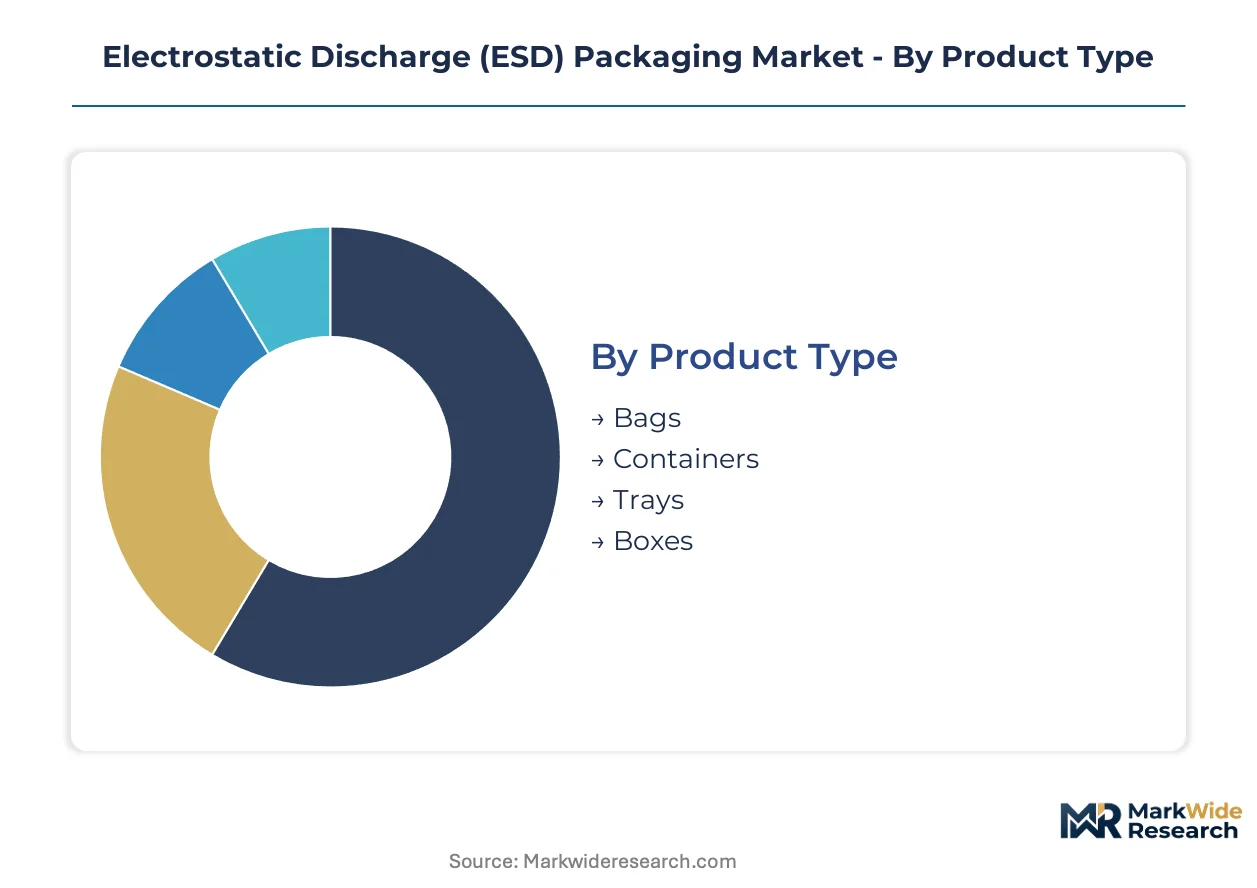
ESD packaging procurement splits across performance tiers and compliance regimes. Semiconductor fabs, automotive module assemblers, and aerospace OEMs each impose distinct material specifications that reshape converter product portfolios.
Product Type:
Buyers differentiate by automation compatibility and unit economics in high-volume electronics corridors.
- Bags:Multi-layer polyethylene laminates with embedded carbon mesh or metalized films dominate wafer and memory chip shipments. Taiwan's Hsinchu and South Korea's Pyeongtaek fabs are standardizing layer-stack configurations that separate shielding, dissipative, and abrasion-resistant functions into modular film combinations.
- Trays:Conductive foam nesting systems command premium positioning for precision component handling in automated assembly lines. German automotive tier-one suppliers specify these for EV battery management system modules where vibration damping intersects with static protection requirements.
- Containers:Returnable programs for aerospace OEMs in France and Germany shift revenue from disposable units to pooled asset management fees under lifecycle logistics contracts.
- Boxes:Corrugated fiberboard with static-dissipative coatings serve automotive module shipments where cost containment outweighs maximum shielding performance.
Volume sits with bags; growth tilts toward trays.
Material:
Regulatory chemistry constraints and end-use biocompatibility protocols are fragmenting compounder supply bases.
- Polyethylene:Dominates multi-layer film production for semiconductor shipping applications, with tunable surface resistivity enabling modular procurement patterns across protection tiers.
- Conductive Foam:Polyurethane and polyethylene foam variants with controlled carbon loading provide precision component nesting for automated pick-and-place operations in Taiwan contract manufacturing facilities.
- Polypropylene:Healthcare device OEMs are phasing out PVC plasticizers under biocompatibility protocols, opening specification windows for polypropylene formulations in diagnostic equipment shipments bound for EU markets.
- PVC:Legacy formulations face REACH substance restrictions and medical device export barriers, with residual demand concentrating in cost-sensitive industrial electronics segments.
Polyethylene captures volume concentration; polypropylene climbs the fastest on healthcare conversion.
End User:
Each vertical imposes distinct certification burdens and performance floors that filter converter participation.
- Electronics:Semiconductor fabs in Taiwan and South Korea drive cleanroom packaging procurement toward higher-performance multi-layer laminates with embedded carbon mesh shielding layers.
- Automotive:EV battery management systems and ADAS sensor clusters require ESD-protected transit packaging with integrated vibration damping, opening specification windows for fiberboard-based static-dissipative alternatives.
- Aerospace:German and French OEMs are adopting lifecycle logistics models for precision avionics modules, shifting procurement from disposable units to returnable container programs with pooled asset management fees.
- Healthcare:FDA device packaging guidelines and ISO 11197 standards for medical electrical equipment shape material selection and validation protocols, with REACH and RoHS constraints eliminating legacy additive chemistries from European-bound shipments.
Electronics commands volume dominance; automotive shows steepest expansion trajectory on electrification.
Distribution Channel:
Contract manufacturer consolidation is compressing vendor panels and elongating agreement structures.
- Direct Sales:Foxconn and Pegatron procurement teams are locking in multi-year supply agreements with dedicated production slots, trading price transparency for supply security in volatile resin markets.
- Distributors:Serve mid-tier electronics manufacturers and maintenance-repair-operations procurement with inventory buffering across Asian chemical processing zones.
- Online:Spot-market purchasing persists for prototype volumes and small-batch customizations where specification flexibility outweighs unit cost optimization.
- Retail:Minimal penetration; limited to hobbyist electronics and small-scale assembly operations without cleanroom requirements.
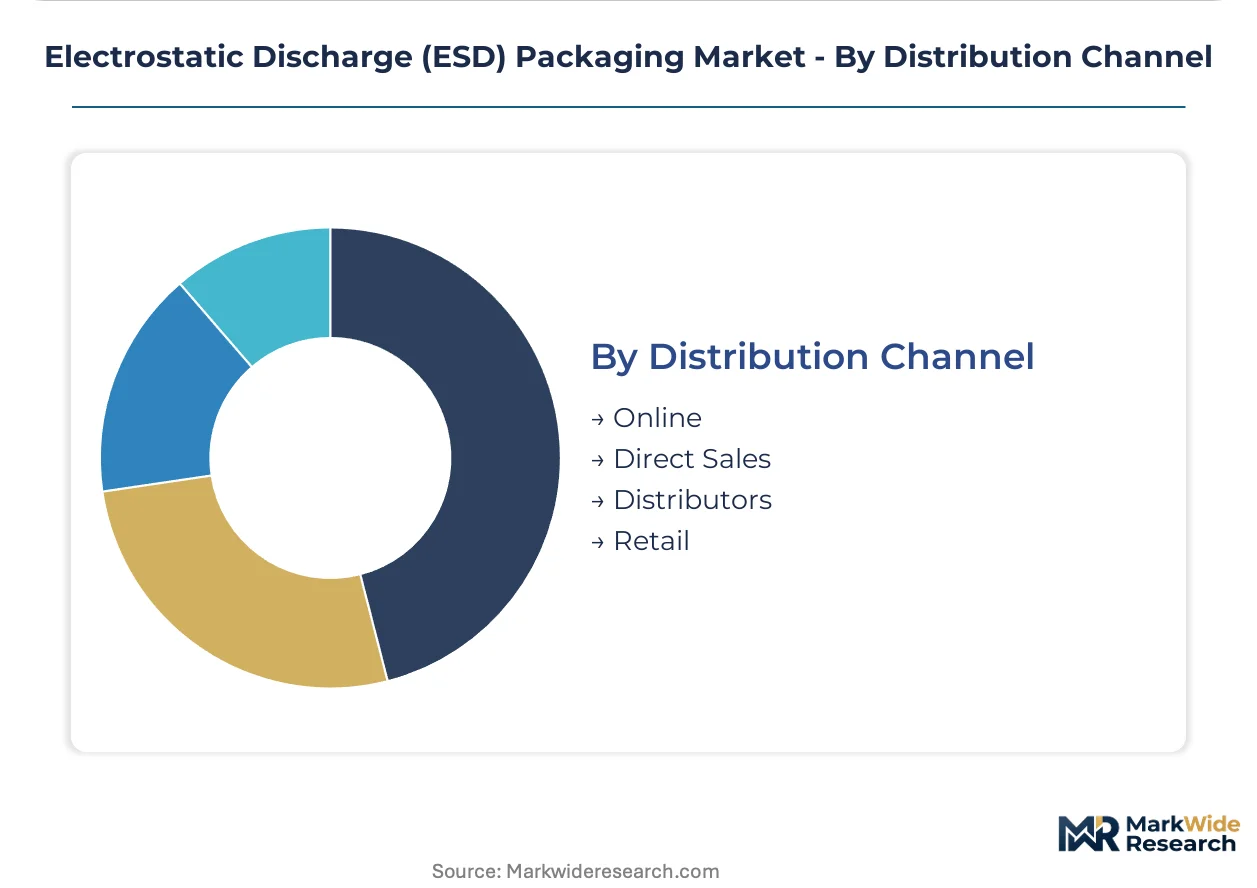
Direct sales anchor volume concentration; online channels gain share fastest on prototype demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors semiconductor packaging procurement volumes, with fabs in Taiwan and South Korea pulling ESD material specifications toward higher-performance multi-layer laminates.
United States
EV battery management systems and ADAS sensor clusters drive specification windows for fiberboard-based static-dissipative alternatives. FDA device packaging guidelines and EPA hazardous substance reporting under TSCA shape material selection for medical electrical equipment. California's draft extended producer responsibility laws are forcing reformulation investments ahead of regulatory finalization.
Germany
Automotive tier-one suppliers specify conductive foam nesting systems for precision component handling in EV module assembly. REACH substance restrictions and RoHS hazardous material limits constrain additive chemistries available to compounders. Aerospace OEMs in Bavaria and Baden-Württemberg are adopting lifecycle logistics models for avionics modules.
China
Yangtze River Delta electronics manufacturing corridors generate sustained procurement volumes for wafer-level ESD bags and conductive foam nesting systems. GB standards for electronic product environmental protection create parallel certification burdens for imports. Cleanroom packaging production in Shanghai and Suzhou is expanding capacity for semiconductor contract manufacturers.
South Korea
Memory chip and semiconductor fabs in Pyeongtaek drive cleanroom packaging procurement toward embedded carbon mesh shielding layers. Direct sales channels with multi-year supply agreements are displacing spot-market purchasing for tier-one contract manufacturers. Samsung and SK Hynix supplier ecosystems are consolidating vendor panels to lock in dedicated production slots.
France
Aerospace OEMs in Toulouse and Paris regions are shifting procurement from disposable units to returnable container programs with pooled asset management fees. EU F-Gas Regulation and REACH compliance mandates push converters toward halogen-free conductive formulations. Medical device exports to European markets demand pre-certified material streams to avoid customs detention at Rotterdam and Hamburg.
Electrostatic Discharge (ESD) Packaging Market Vendor Landscape
The competitive structure tilts toward integrated packaging converters with captive containerboard supply and specialized logistics operators. Tier-one electronics contract manufacturers are consolidating vendor panels, compressing participation to suppliers with multi-year capacity commitments. Two strategic archetypes dominate: integrated paper-based packaging conglomerates with corrugated fiberboard R&D networks, and specialized ESD logistics providers with returnable container program expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves, as compounders secure resin supply agreements and cleanroom certification timelines.
Among European-based integrated packaging groups, DS Smith and Smurfit Kappa Group exemplify the scale-driven archetype with containerboard mill networks sustaining cost advantages in tray and box segments. Nefab Group occupies a position within the specialized logistics tier, anchoring returnable ESD container programs for aerospace OEMs through lifecycle contracts rather than disposable unit sales. These three companies represent the structural segmentation between volume-commodity production and service-embedded asset management models.
| Leading Market Players |
|---|
| DS Smith |
| GWP Group |
| Desco Industries |
| Elcom Ltd. |
| Teknis Limited |
| Smurfit Kappa Group |
| Nefab Group |
| Delphon Industries |
| Sealed Air Corporation |
| Others |
Supply Flow & Price Mechanics
Cleanroom technician labor pools in Hsinchu and Pyeongtaek create cost differentials that propagate through ESD packaging tiers, with premium multi-layer laminates commanding spreads over economy-grade conductive bags based on contamination-control labor intensity rather than resin content alone.
Pricing Analysis
Yield-protection guarantees from wafer fabs anchor value-based pricing for semiconductor-grade ESD materials, with surface resistivity certification tiers separating premium Faraday-cage laminates from standard dissipative films. Foxconn and Pegatron procurement teams exploit volume scale for contract-based long-term offtake, compressing margins for spot-market suppliers. Pricing pressure stems from carbon black feedstock volatility in Asian chemical processing zones. Contract manufacturers show least price sensitivity; prototype buyers in online channels absorb highest per-unit premiums.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore warehouse finished ESD materials for hub-and-spoke fulfillment to semiconductor corridors. Compounders draw from carbon black production clusters in China and South Korea, with resin formulation concentrated in Taiwan and Germany. Single-source vulnerability runs through conductive additive supply. Distribution runs through direct sales channels with dedicated production slots, displacing distributor inventory buffering for tier-one electronics contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor panel consolidation by Foxconn and Pegatron is compressing participation to suppliers with multi-year capacity commitments, forcing weaker compounders without cleanroom certification or captive resin supply toward exit.
For Market Incumbents: To counter margin compression from resin volatility, secure backward integration into carbon black sourcing or polyethylene resin supply agreements. Anchor defensive positioning through ISO 14644 cleanroom certification investments that extend facility qualification timelines beyond entrant replication capacity. For New Entrants and Emerging Players: The mid-tier pricing gap between premium Faraday-cage laminates and economy conductive bags offers white-space entry through halogen-free polypropylene formulations for healthcare device OEMs. Target diagnostic equipment shipments bound for EU markets with pre-certified REACH-compliant material streams. Differentiate through lifecycle logistics contracts for aerospace returnable container programs rather than disposable unit sales. For Investors and Strategic Acquirers: Re-rating potential sits with specialized ESD logistics providers given aerospace OEM adoption of pooled asset management models. Long-term viability favors operators with returnable container program expertise over commodity film converters. Monitor California and New York extended producer responsibility rule finalization as inflection signal for halogen-free formulation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | ISO 14644 compliance extends facility qualification timelines beyond replication capacity for semiconductor packaging supply. |
| Halogen-Free Formulation Transition | REACH and EU F-Gas Regulation compliance opens specification windows in European electronics and healthcare corridors. |
| Returnable Container Program Expansion | Lifecycle logistics contracts with Airbus and Safran shift revenue from disposable units to pooled asset management fees. |
| Direct Sales Channel Consolidation | Multi-year supply agreements with Foxconn and Pegatron lock in dedicated production slots and volume pricing. |
| Carbon Black Supply Integration | Backward integration into conductive additive production mitigates input cost volatility from Asian chemical processing zones. |
Methodological Framework
Independent corroboration across primary interviews with ESD packaging plant managers, semiconductor procurement leads at Taiwan contract manufacturers, medical device regulatory affairs directors, and aerospace logistics coordinators underwrites the qualitative findings. Secondary validation draws from customs trade data for conductive polymer imports, SEC 10-K filings of integrated packaging groups, REACH substance restriction updates from ECHA, and GB standards documentation for electronic product environmental protection. Bottom-up demand modeling from wafer fab expansion announcements triangulates with top-down market sizing from resin consumption patterns.
Comparable-period anchoring to historical semiconductor capital expenditure cycles and electronics manufacturing production indices shaped the forecast window construction. Segmentation dimensions modeled include product type, material formulation, end-use vertical, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis against wafer shipment volumes and cleanroom packaging procurement trends. Industry-specific inputs incorporated carbon black price indices and REACH regulatory timeline assumptions.
Inputs from primary field interviews and regulatory filing databases were available through the study window; gaps in real-time carbon black inventory data and draft state-level extended producer responsibility rule language introduce uncertainty bands. Forecasts reflect documented assumptions regarding semiconductor fab expansion schedules and regulatory finalization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Flooring Market
Electrostatic Discharge (ESD) Packaging
ESD Tray Market
Electrostatic Discharge (ESD) Packaging
UAE Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Packaging Market
Electrostatic Discharge (ESD) Packaging
ESD Foldable Container Market
Electrostatic Discharge (ESD) Packaging
Asia-Pacific Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Workstations Market
Electrostatic Discharge (ESD) Packaging
ESD Safe Matting Market
Electrostatic Discharge (ESD) Packaging
India Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
ESD Totes Market
Electrostatic Discharge (ESD) Packaging
Shielding Bags Market
Electrostatic Discharge (ESD) Packaging
South Korea Electrostatic Discharge (ESD) Trays Market
Electrostatic Discharge (ESD) Packaging
ESD Clamshell Market
Electrostatic Discharge (ESD) Packaging
Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Saudi Arabia Electrostatic Discharge (ESD) Films Market
Electrostatic Discharge (ESD) Packaging
Metallic Static Shielding Bags Market